
 Diesel Exhaust Fluid Market | 2026-2036
Diesel Exhaust Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Exhaust Fluid Market Intelligence
A transition from single-source contracts toward multi-source procurement by large fleet operators is recalibrating the supply landscape for diesel exhaust fluid. This shift creates opportunities for large-scale producers to gain market share. Yara International leverages its extensive global distribution network to serve diverse clients. CF Industries sustains its market position through significant urea production capacity, while BASF SE competes on high-purity automotive-grade solutions.
Diesel exhaust fluid is an aqueous urea solution, specifically composed of 32.5% high-purity urea and 67.5% deionized water. It functions as a reducing agent in selective catalytic reduction (SCR) systems to convert nitrogen oxides (NOx) into nitrogen and water. Demand from heavy-duty vehicles represents the largest application, driven by emissions compliance. Sales through fuel stations and direct supply to large fleets constitute the primary distribution channels.
Global emissions standards, enforced by bodies like the US EPA and subject to regulations like the EU's REACH, are the principal market driver. The ISO 22241 standard dictates quality specifications, ensuring SCR system compatibility. Producers must navigate a complex web of national environmental rules and international quality benchmarks to maintain market access. Future competitive advantage hinges on securing low-cost urea feedstock and optimizing distribution logistics.
Market Dynamics
The diesel exhaust fluid market is fundamentally shaped by a global regulatory framework mandating nitrogen oxide emissions reduction. This non-negotiable compliance, enforced by bodies like the US EPA and through standards like Euro VI, creates a captive and expanding customer base.
Growth Catalysts
- Stringent Emissions Mandates:Regulations such as the EPA 2010 standards in the United States and Euro VI norms in Europe legally require the use of selective catalytic reduction systems, directly fueling demand from the heavy-duty vehicle sector.
- Industrial Expansion in China:Rapid growth in China’s logistics, transportation, and construction industries, coupled with the enforcement of its own national emissions standards, accelerates consumption on a massive scale.
- Global Quality Standardization:The ISO 22241 standard provides a universal quality benchmark, ensuring fluid-to-engine compatibility and fostering confidence among fleet operators, which de-risks adoption and supports market expansion.
Market Restraints
- Urea Price Volatility:As the primary raw material, urea prices are tied to volatile natural gas markets, creating unpredictable input costs for DEF producers and pressuring margins throughout the supply chain.
- Alternative Powertrain Transition:The long-term shift towards battery-electric and hydrogen fuel-cell trucks, particularly in developed economies, presents a structural substitution threat that will eventually cap market growth.
- Logistical Inefficiencies:The high water content of DEF makes it heavy and costly to transport relative to its value, creating regional supply-demand imbalances and limiting the economic viability of long-distance distribution.
Strategic Opportunities
- Non-Road Mobile Machinery:Expanding emissions regulations to cover non-road mobile machinery, including agricultural tractors, mining equipment, and construction vehicles, opens a significant new application segment for DEF suppliers.
- Emerging Market Adoption:As countries in Latin America and Southeast Asia begin to implement stricter diesel emissions rules modeled on European or US standards, they represent underpenetrated markets with substantial growth potential.
- On-Site Production and Blending:Offering modular, on-site blending systems for large fleet operators provides a value-added service that reduces transportation costs, ensures supply, and strengthens customer relationships.
Industry Challenges
- Consistent Quality Assurance:Maintaining the precise 32.5% urea concentration and purity required by ISO 22241 across production, bulk transport, and storage is a constant operational challenge that requires rigorous testing and control.
- Fragmented Distribution Management:The move by large fleets to multi-source procurement creates demand variability and logistical complexity for suppliers, challenging inventory management and route optimization without long-term volume guarantees.
- Navigating Regulatory Patchworks:Adhering to a complex web of international quality standards like ISO 22241 alongside national chemical regulations such as the EU's REACH requires significant compliance resources and expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Exhaust Fluid Market |
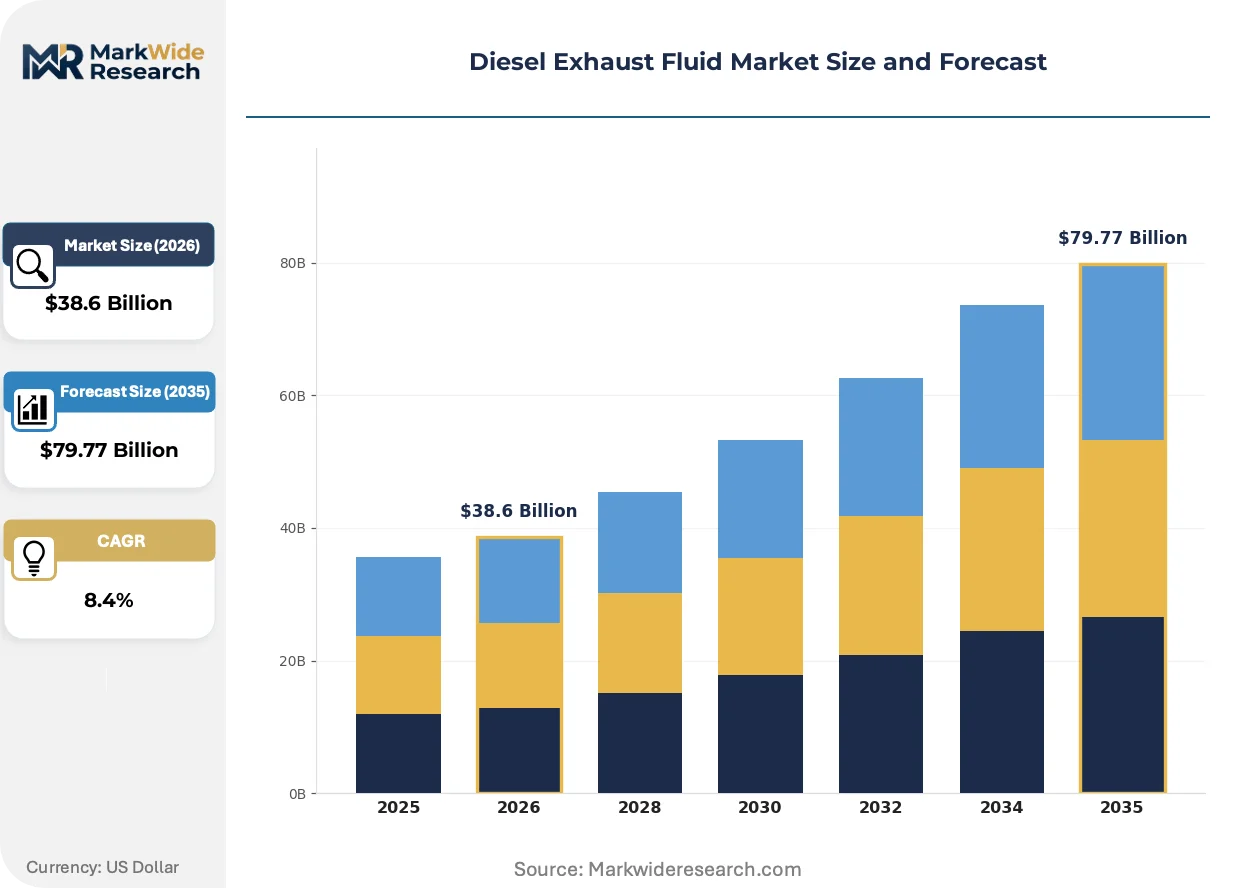
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AdBlue, DEF Concentrate, Industrial Urea Solution, Agricultural Urea Solution, Marine Urea Solution Application: Heavy-Duty Vehicles, Construction Equipment, Agricultural Machinery, Marine Engines, Power Generators End User: Fleet Operators, OEMs, Aftermarket Suppliers, Equipment Rental Companies, Public Transport Authorities Distribution Channel: Direct Sales, Retail Pharmacies, Online Retailers, Wholesale Distributors, Fuel Stations |
| Companies Covered | CF Industries, Yara International, BASF SE, TotalEnergies, Shell PLC, China Petrochemical Corporation, Brenntag AG, Airgas, Nissan Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Exhaust Fluid Market Strategic Shifts & Innovations
The market is evolving from a simple compliance commodity into a sophisticated industrial fluid category. This maturation is driven by the integration of digital monitoring technologies and the development of more complex, service-oriented supply models for large-scale consumers.
Advanced sensor suites are becoming integral to modern selective catalytic reduction systems. These sensors provide real-time monitoring of DEF quality, level, and consumption rates directly within the vehicle's onboard diagnostics. Fleet operators are widely adopting these systems to prevent costly engine damage and ensure continuous emissions compliance. This integrated technology **is absorbing** the operational risks of fluid contamination and system failure, making total cost of ownership a key purchasing metric.
China's National VI emissions standard is a powerful regulatory force that has dramatically accelerated market development. The policy, which aligns with or exceeds Euro VI levels, mandates the use of high-performance SCR systems in all new heavy-duty diesel vehicles. This has created a massive, compulsory market for DEF, forcing a rapid build-out of production and distribution infrastructure to serve the nation's vast commercial vehicle fleet.
A notable behavioral shift is occurring among large-scale fleet operators, who are moving toward integrated fluid management programs. This trend disrupts the traditional retail channel, favoring direct-supply relationships that include bulk storage tanks, automated dispensing equipment, and quality assurance services. The shift is most visible in the mature logistics markets of North America and Europe, where operational efficiency and cost control are paramount.
Diesel Exhaust Fluid Market Segmentation
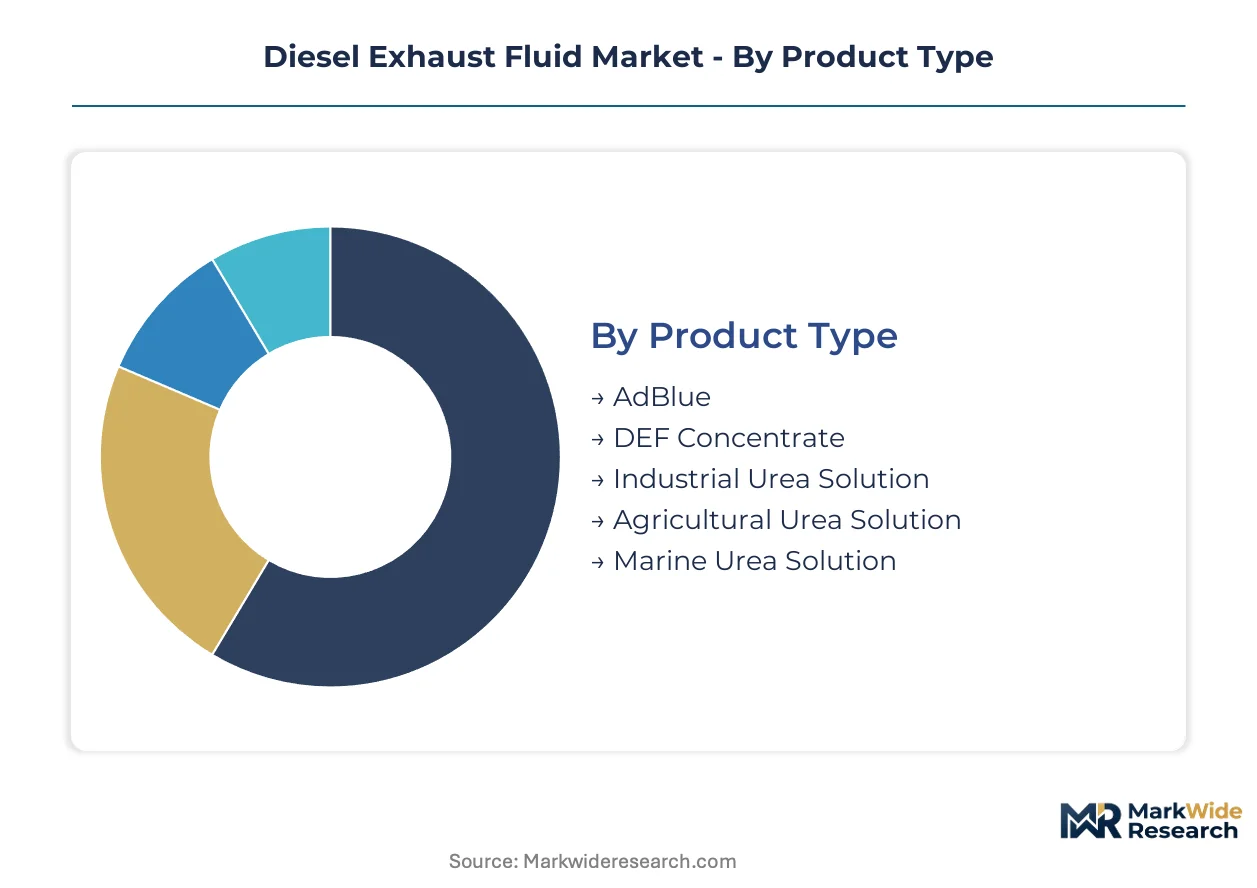
Diesel Exhaust Fluid market segmentation offers critical insights into the diverse product formulations, application requirements, and distribution complexities. It illuminates how specific end-user needs drive demand for tailored solutions and delivery mechanisms. This granular understanding allows market participants to strategically align their offerings with high-growth segments.
Product Type:
Producing diverse DEF product types necessitates varying capital investments, especially for high-purity grades and specialized formulations.
- AdBlue:This specific brand of Diesel Exhaust Fluid adheres strictly to ISO 22241 standards, comprising 32.5% urea and 67.5% deionized water. Demand concentrates in Europe, driven by Euro VI emissions norms for heavy-duty vehicles.
- DEF Concentrate:This higher-concentration urea solution reduces shipping volume and costs, requiring dilution before use. Demand is gaining traction among large fleet operators in North America seeking to optimize logistics and storage efficiency.
- Industrial Urea Solution:This solution serves non-automotive industrial applications requiring NOx reduction, often with less stringent purity specifications.
- Agricultural Urea Solution:Tailored for agricultural machinery with SCR systems, this product helps meet off-road emissions standards.
- Marine Urea Solution:Designed for marine engines, this variant addresses specific NOx reduction requirements in the shipping sector.
AdBlue absorbs the bulk of installed capacity; DEF Concentrate is expanding most quickly.
Application:
The application segments for DEF are primarily differentiated by the specific emissions regulations impacting each machinery type.
- Heavy-Duty Vehicles:This segment represents the largest consumer of DEF, driven by stringent emissions mandates like EPA 2010 and Euro VI across North America and Europe. Fleets prioritize consistent supply to ensure compliance and avoid operational penalties.
- Construction Equipment:Emissions regulations are expanding to cover non-road mobile machinery, increasing DEF consumption for excavators, loaders, and other heavy equipment. China's national standards significantly influence this segment's growth.
- Agricultural Machinery:Tractors and harvesters increasingly integrate SCR systems to meet off-road emissions standards, driving DEF usage in the farming sector.
- Marine Engines:Large commercial vessels and recreational boats utilize DEF to comply with IMO Tier III NOx limits in Emission Control Areas.
- Power Generators:Stationary and mobile power generation units use DEF for NOx reduction, particularly in urban areas with strict air quality regulations.
Heavy-Duty Vehicles dominate consumption volume; Power Generators represent an emerging demand source.
End User:
End-user segmentation highlights distinct procurement strategies and service requirements across different customer types.
- Fleet Operators:These large-scale consumers, managing extensive vehicle pools, increasingly seek multi-source procurement and integrated fluid management programs. Their demand is concentrated in logistics hubs across developed economies.
- OEMs:Original Equipment Manufacturers integrate DEF into new vehicles as factory fill, ensuring initial compliance and validating SCR system performance. They demand high-quality, certified solutions for brand reputation.
- Aftermarket Suppliers:These entities provide DEF refills and related components through retail channels and service networks for vehicles already in operation.
- Equipment Rental Companies:These companies manage diverse machinery fleets, requiring reliable DEF supply to maintain operational readiness and regulatory compliance.
- Public Transport Authorities:Municipal bus and rail operators use DEF for their vehicle fleets, driven by urban air quality mandates and public sector procurement rules.
Fleet Operators exert significant influence over distribution logistics; OEMs establish initial product specifications.
Distribution Channel:
Distribution channels are shaped by the need for efficient delivery and accessibility, impacting supply concentration and cost structures.
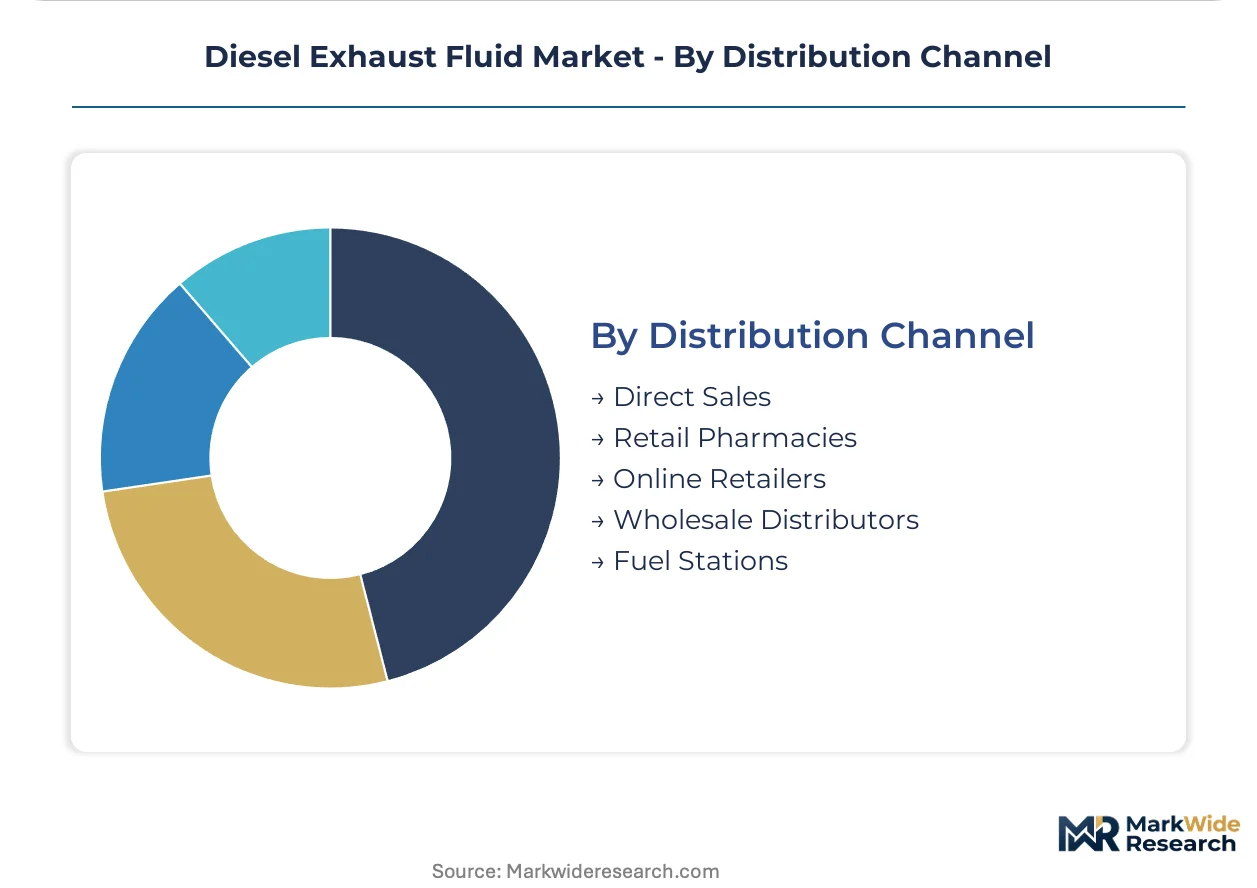
- Fuel Stations:These outlets provide convenient DEF access for individual truckers and smaller fleets, offering both bulk and packaged solutions. Their widespread network supports on-the-go refills.
- Direct Sales:Large fleet operators and industrial clients benefit from direct supply, often involving bulk deliveries and on-site storage solutions. This channel reduces logistical inefficiencies for high-volume users.
- Retail Pharmacies:These stores offer packaged DEF containers to a broad consumer base, catering to smaller volume requirements.
- Online Retailers:E-commerce platforms facilitate the purchase of DEF, providing convenience and competitive pricing for various customer segments.
- Wholesale Distributors:These intermediaries aggregate DEF from producers and supply it to smaller retailers, service centers, and regional fleets.
Fuel Stations and Direct Sales remain primary distribution avenues; Online Retailers represent an emerging channel for packaged DEF.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Diesel Exhaust Fluid market's regional dynamics are heavily influenced by the availability of natural gas feedstock for urea production. China's industrial expansion and stringent national emissions standards significantly drive demand. The United States and Europe also represent major consumption hubs due to their mature heavy-duty vehicle sectors.
China
China's rapid expansion in logistics and construction industries fuels substantial DEF consumption. The National VI emissions standard mandates high-performance SCR systems, creating a massive compulsory market. Cities like Shanghai and Guangzhou, with their dense commercial vehicle fleets, drive demand for localized distribution networks.
United States
Demand in the United States originates from the large heavy-duty trucking industry. EPA 2010 standards legally require SCR systems, ensuring consistent DEF usage across commercial fleets. Major transportation corridors in Texas and California concentrate demand for accessible fuel station and direct-supply solutions.
Germany
Germany's robust automotive sector and strict environmental regulations underpin its DEF market. Euro VI norms for heavy-duty vehicles ensure widespread adoption of SCR technology. The industrial regions of North Rhine-Westphalia and Bavaria require consistent DEF supply for their logistics and manufacturing operations.
India
India's burgeoning infrastructure development and increasing vehicle parc are boosting DEF requirements. The Bharat Stage VI (BS VI) emission standards, aligned with Euro VI, accelerate SCR system integration in new diesel vehicles. Major metropolitan areas like Delhi and Mumbai are witnessing a build-out of DEF distribution infrastructure.
Brazil
Brazil's agricultural and mining sectors are expanding, driving demand for DEF in off-road machinery. PROCONVE P-7 (equivalent to Euro V) and upcoming P-8 standards mandate NOx reduction technologies. The São Paulo and Minas Gerais regions, with their extensive logistics and agribusiness, represent significant consumption centers.
Diesel Exhaust Fluid Market Key Industry Players
Global majors compete with regional champions across production capacity and distribution reach. The market structure exhibits a tiered consolidation, with large chemical companies anchoring the supply of urea feedstock. Strategic archetypes include integrated chemical producers, specialized DEF blenders, and logistics-focused distributors. Dominant competitive moves involve significant capacity expansion and strategic partnerships for last-mile delivery.
Among the integrated chemical producers, CF Industries and Yara International exemplify companies leveraging extensive global production networks. BASF SE occupies a position focused on high-purity automotive-grade solutions, emphasizing quality specifications. These players anchor the market by ensuring a stable supply of the primary raw material and high-quality finished products.
| Leading Market Players |
|---|
| CF Industries |
| Yara International |
| BASF SE |
| TotalEnergies |
| Shell PLC |
| China Petrochemical Corporation |
| Brenntag AG |
| Airgas |
| Nissan Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Large fleet operators' shift towards multi-source procurement recalibrates the diesel exhaust fluid supply landscape. This demand-side pressure compels producers to offer competitive pricing and flexible delivery solutions, directly impacting margin structures.
Pricing Analysis
Bundled service offerings, including quality assurance and automated dispensing equipment, differentiate diesel exhaust fluid pricing beyond the product itself. The dominant pricing structure involves contract-based long-term offtake agreements for large fleet operators and transactional sales at fuel stations. Price differentiation stems from ISO 22241 certification levels and volume scale. Urea price volatility creates persistent upward pressure on producer input costs. Individual truckers and small operators exhibit higher price sensitivity compared to large fleets prioritizing consistent supply and compliance.
Supply Chain Analysis
Workforce availability for urea production and specialized blending operations impacts supply stability in key manufacturing geographies like China, the United States, and Germany. The global supply chain draws primarily from these nations, which house significant urea production capacity. Raw material dependencies center on urea and deionized water. Logistical inefficiencies, driven by DEF's high water content, present a structural risk, leading to regional supply-demand imbalances. Distribution runs through direct supply to large fleet operators and an extensive network of fuel stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diesel exhaust fluid market is poised for consolidation, as stringent quality standards like ISO 22241 and the need for significant capital investment increasingly pressure smaller, less compliant producers. Only robust operations can meet the evolving regulatory and logistical demands.
For Market Incumbents:Deploy advanced sensor integration within SCR systems to offer real-time DEF quality monitoring, mitigating operational risks for fleet operators. Expand global distribution networks, leveraging existing infrastructure to counter the threat of alternative powertrain transitions. Secure long-term, low-cost urea feedstock contracts to stabilize input costs against market volatility. Optimize distribution logistics for high-volume users through on-site blending solutions.
For New Entrants and Emerging Players:Enter via specialized segments like non-road mobile machinery, focusing on agricultural tractors or mining equipment where emissions regulations are expanding. Target underpenetrated emerging markets in Latin America and Southeast Asia, mirroring established European or US standards. Offer modular, on-site production and blending systems directly to large fleet operators, providing a value-added service that reduces transportation costs and ensures supply. Emphasize compliance solutions for newly regulated sectors.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking to consolidate fragmented regional distribution networks. The market exhibits long-term viability over the next 5-10 years, underpinned by non-negotiable emissions compliance mandates. Target specialized DEF blenders with strong last-mile delivery capabilities or producers of high-purity automotive-grade solutions. The accelerated adoption of Euro VI-equivalent emissions standards in emerging economies serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Urea Production | Ensures stable feedstock supply and reduces reliance on volatile natural gas markets. |
| Investment in On-Site Blending Technology | Reduces transportation costs for large fleet operators and strengthens customer relationships. |
| Certification for Non-Road Mobile Machinery | Unlocks new application segments like agricultural and construction equipment. |
| Geographic Expansion into Emerging Markets | Captures demand from countries implementing stricter diesel emissions regulations. |
| Development of Advanced DEF Quality Sensors | Provides real-time monitoring, mitigating contamination risks for fleet operators. |
Research Approach
Customs/trade data, ACC/Cefic reports, and ISO 22241 documentation formed the secondary backbone for this analysis. Primary interviews were conducted with procurement leads at large fleet operators, R&D directors at DEF producers, distribution channel partners, and regulatory compliance officers. This approach combined qualitative insights with quantitative data, employing both bottom-up and top-down triangulation to validate market size and growth projections.
The analytical framework aggregated vehicle parc data and DEF consumption rates from a bottom-up perspective, validated by top-down regulatory impact assessments across the modeling period. Segmentation dimensions included product type, application, end user, and distribution channel. Compound annual growth rates derived from historical trends incorporated projected regulatory enforcement. Heavy-duty vehicle sales forecasts and urea feedstock price outlook served as key inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant global trade policy shifts or accelerated alternative powertrain adoption. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Foam Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market