
 Europe Industrial Gases Market | 2026-2036
Europe Industrial Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Gases Market Intelligence
Buyer concentration across European steel and chemical processing is restructuring demand patterns for bulk industrial gases. Linde PLC leverages its pipeline network density to sustain long-term supply contracts with integrated mills. Air Liquide anchors its position through on-site generation systems at major petrochemical complexes. Messer Group competes by specializing in regional merchant gas distribution across Central and Eastern Europe.
Europe industrial gases encompass purified or mixed atmospheric and synthetic gases—oxygen, nitrogen, argon, hydrogen, and carbon dioxide—typically supplied at pressures exceeding 150 bar or in cryogenic liquid form below minus 180 degrees Celsius, serving as essential process inputs for oxidation, inerting, cooling, and chemical synthesis. The oxygen segment dominates volume flows into steelmaking and medical respiratory therapy, while hydrogen is capturing accelerated investment as refiners and ammonia producers retrofit for lower-carbon feedstocks. Electronics manufacturing applications for ultra-high-purity nitrogen and argon command premium pricing due to stringent particulate and moisture specifications.
REACH, the EU Green Deal, and the F-Gas Regulation are tightening emissions accountability and phasing down fluorinated gas use, compelling producers to certify carbon footprints and invest in carbon capture-enabled hydrogen. ECHA chemical safety assessments are extending compliance burdens to gas blends and novel hydrogen carriers. Stakeholders must monitor carbon border adjustment mechanisms and renewable hydrogen certification schemes to secure contract renewals with energy-intensive buyers.
Market Dynamics
The EU Green Deal is compressing capital deployment timelines for hydrogen infrastructure, forcing producers to choose between retrofitting steam methane reformers with carbon capture or building electrolysis capacity from scratch.
Growth Catalysts
- Carbon Border Adjustment Mechanism:Energy-intensive buyers in steel and cement face embedded carbon costs, accelerating demand for certified low-carbon hydrogen and oxygen from electrolytic sources.
- REACH chemical safety expansion:ECHA assessments now cover novel hydrogen carriers and gas blends, creating compliance-driven replacement cycles for legacy supply contracts.
- Medical oxygen infrastructure:Healthcare facilities across Italy and Spain are building buffer storage and redundant distribution after supply disruptions during respiratory surges.
Market Restraints
- Natural gas price volatility:Steam methane reforming remains the dominant hydrogen production pathway, exposing margins to TTF hub fluctuations and Russian supply uncertainty.
- Cryogenic transport equipment scarcity:Specialized tanker fleets for liquid oxygen and nitrogen concentrate among three logistics providers, creating regional bottlenecks during peak demand.
- F-Gas phasedown timeline:The EU F-Gas Regulation mandates refrigerant replacement in industrial cooling systems, forcing gas processors to certify alternative fluorinated compounds or abandon certain product lines.
Strategic Opportunities
- Poland and Czech Republic merchant gaps:Central European manufacturing clusters lack dense pipeline networks, opening territory for packaged gas and small-scale on-site generation deployment.
- Electronics-grade nitrogen demand:Semiconductor fabs in Ireland and the Netherlands require ultra-high-purity specifications, commanding price premiums five to eight times standard industrial grades.
- Renewable Hydrogen Certification:The CertifHy scheme creates tradable guarantees of origin, enabling producers to capture green premiums from ammonia and refining customers under Scope 3 pressure.
Industry Challenges
- Cryogenic engineering talent scarcity:Europe trains fewer than two hundred specialists annually in low-temperature process design, constraining expansion timelines for liquefaction facilities.
- Legacy ASU integration complexity:Air separation units built before 2010 lack digital process controls, complicating retrofit for variable renewable electricity input and demand-response participation.
- Cross-border hydrogen pipeline permitting:National safety regulators apply diverging pressure vessel standards, fragmenting project timelines for trans-European hydrogen backbone connections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Gases Market |
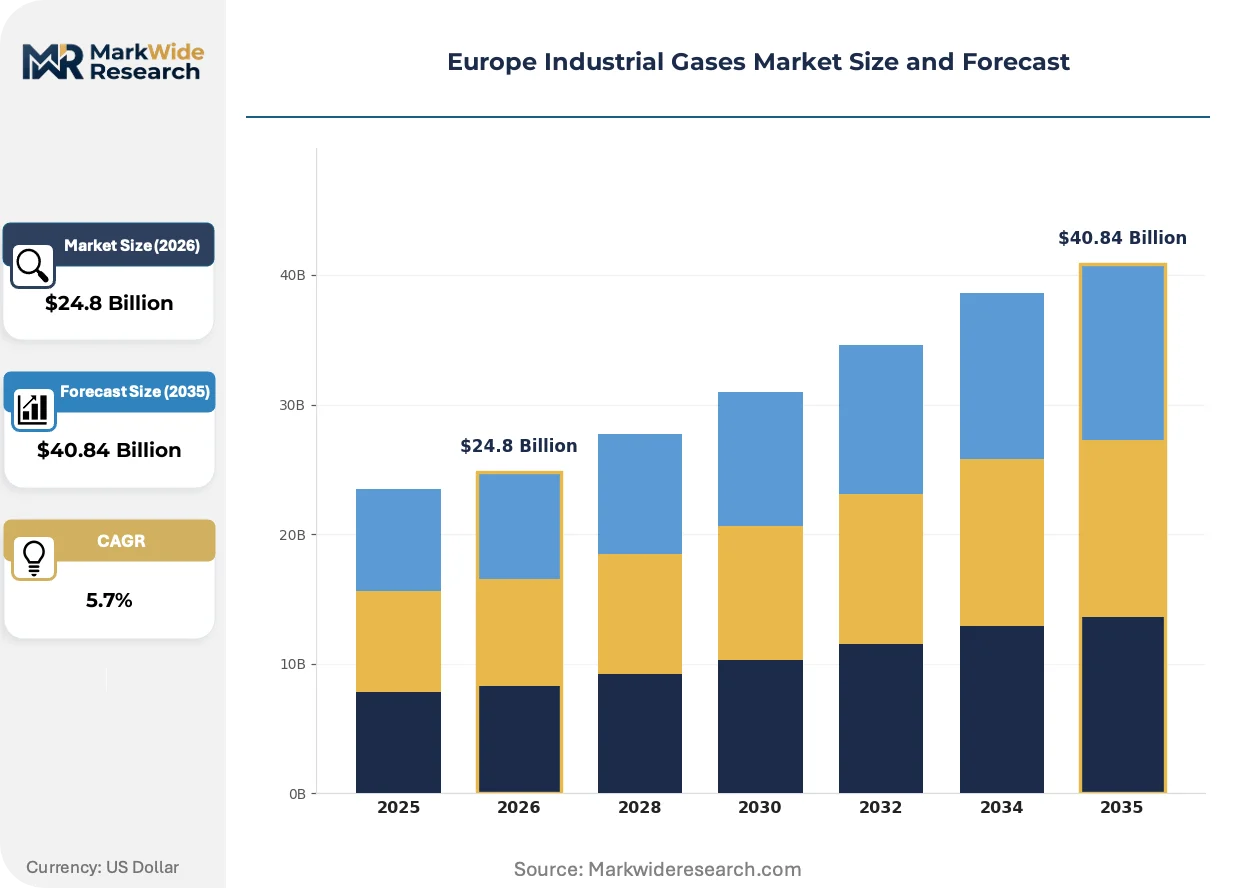
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
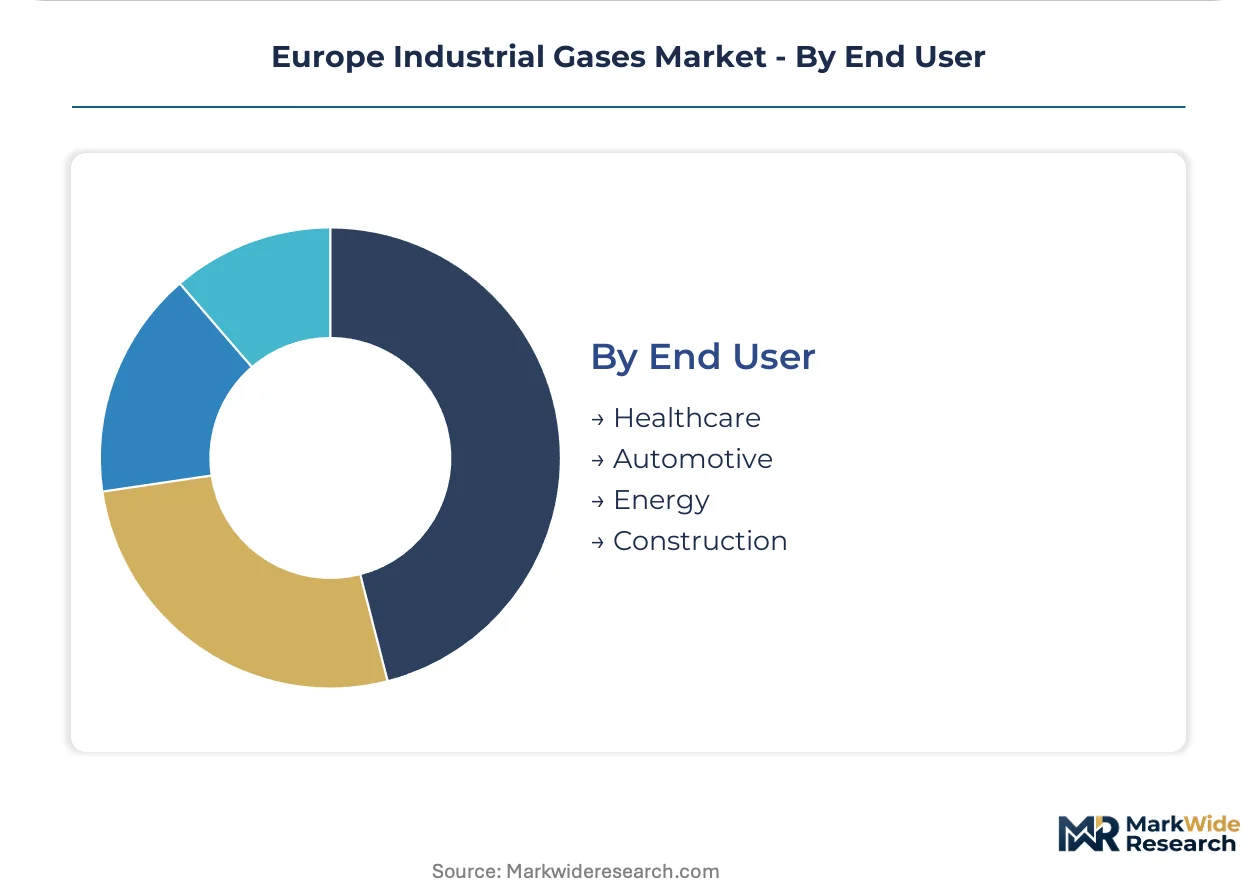
| Segmentation | Product Type: Oxygen, Nitrogen, Argon, Hydrogen Application: Metal Fabrication, Chemical Processing, Food Preservation, Electronics Manufacturing Distribution Channel: Manufacturers, Distributors, Retail, Online End User: Healthcare, Automotive, Energy, Construction |
| Companies Covered | Messer Group, BASF SE, Linde PLC, Matheson Tri-Gas, SIAD Group, Air Liquide, SOL Group, Elliniki Gases, Air Products and Chemicals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Gases Market Strategic Shifts & Innovations
Digital process control and modular plant design are compressing project delivery timelines while enabling demand-responsive production scheduling that was technically impossible with legacy equipment.
Advanced process control systems using predictive algorithms are automating air separation unit load balancing. Steel mills in Germany and the Netherlands deploy these systems to match oxygen supply with electric arc furnace batch cycles. The technology is automating demand forecasting and reducing buffer storage requirements by fifteen to twenty percent at integrated sites.
REACH authorization requirements for nickel catalysts used in hydrogen production are tightening supply chain documentation burdens. ECHA's 2024 update extends substance volume tracking to imported catalyst precursors. Hydrogen producers in Belgium and France are responding by qualifying domestic catalyst suppliers and accelerating testing of iron-based alternatives.
Long-term take-or-pay contracts are fragmenting into shorter-term agreements with indexed pricing and volume flexibility clauses. Chemical processors in the Rotterdam-Antwerp corridor now procure hydrogen through quarterly tenders rather than decade-long commitments. This pattern is most visible among ammonia producers hedging against renewable hydrogen cost curves and carbon price volatility.
Europe Industrial Gases Market Segmentation
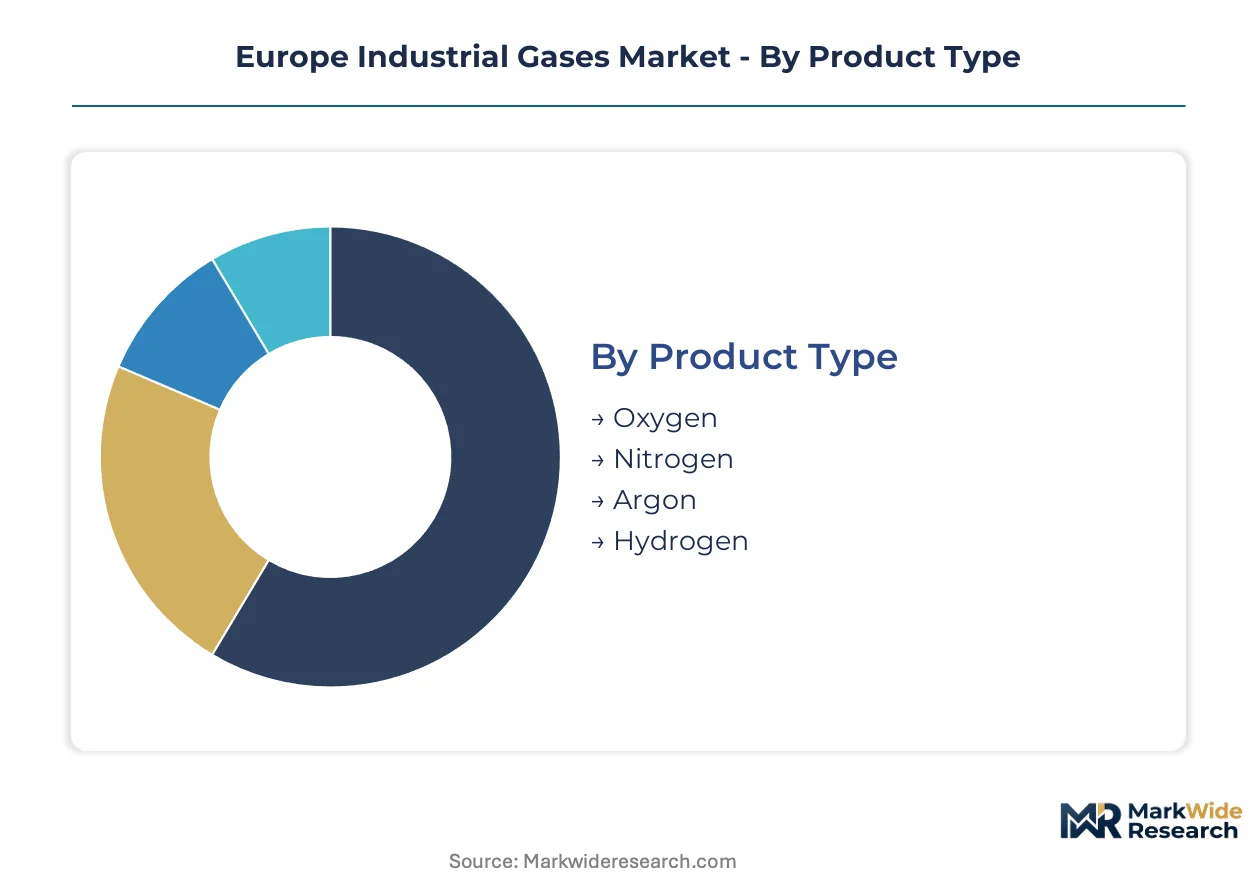
Industrial gas procurement decisions in Europe hinge on purity specifications, volume scale, and delivery reliability rather than brand preference. Segmentation reveals how hydrogen infrastructure investments and electronics-grade demand are reshaping supplier priorities across the continent.
Product Type:
Purity thresholds and production method certification drive buyer selection more than commodity pricing in this category.
- Oxygen:Supplied at pressures exceeding 150 bar or in cryogenic liquid form below minus 180 degrees Celsius, this segment serves steelmaking oxidation processes and medical respiratory therapy across Germany and Italy. Demand concentrates in electric arc furnace operations as integrated mills retrofit for scrap-based production.
- Hydrogen:Capturing accelerated investment as refiners and ammonia producers retrofit for lower-carbon feedstocks, with electrolytic and carbon capture-enabled steam methane reforming routes competing for certification under the EU Green Deal. Rotterdam-Antwerp corridor buyers now source through quarterly tenders rather than long-term commitments.
- Nitrogen:Inerting and blanketing applications dominate volume flows into chemical processing and food packaging operations.
- Argon:Shielding gas demand from welding applications and specialty steel production anchors merchant distribution in Central Europe.
Volume sits with oxygen; growth tilts toward hydrogen.
Application:
Process integration depth determines whether buyers opt for pipeline supply, on-site generation, or packaged gas delivery.
- Metal Fabrication:Oxygen-fuel cutting and argon-shielded welding consume bulk volumes across Polish and Czech manufacturing clusters lacking dense pipeline infrastructure. Steel mills deploy predictive algorithms to match supply with electric arc furnace batch cycles.
- Electronics Manufacturing:Semiconductor fabs in Ireland and the Netherlands require ultra-high-purity nitrogen and argon with particulate and moisture specifications commanding price premiums five to eight times standard industrial grades.
- Chemical Processing:Hydrogen feedstock demand from ammonia and methanol producers anchors long-term contract structures despite fragmentation toward shorter-term indexed agreements.
- Food Preservation:Modified atmosphere packaging and cryogenic freezing drive merchant nitrogen and carbon dioxide demand across regional distribution networks.
Metal fabrication holds the installed base; electronics manufacturing claims the steepest expansion trajectory.
Distribution Channel:
Capital intensity and logistics specialization create sharp tiering between integrated producers and regional intermediaries.
- Manufacturers:Direct supply relationships anchor bulk oxygen and hydrogen flows to integrated steel and petrochemical complexes through pipeline networks and on-site generation systems.
- Distributors:Regional merchant gas specialists concentrate packaged cylinder and cryogenic liquid delivery across Central and Eastern Europe where pipeline density remains thin.
- Retail:Local welding supply shops and medical equipment vendors handle small-volume oxygen and argon for fragmented end-users.
- Online:Digital procurement platforms emerge for standardized cylinder exchanges and emergency replenishment, though cryogenic liquids resist full e-commerce migration.
Manufacturers capture value concentration; distributors fill geographic coverage gaps.
End User:
Regulatory compliance burdens and safety-critical applications segment buyers by certification requirements and contract duration preferences.
- Healthcare:Medical oxygen infrastructure investment surged across Italy and Spain after respiratory surge disruptions, with buffer storage and redundant distribution now mandatory in hospital procurement specifications.
- Energy:Power-to-gas projects and hydrogen blending in natural gas networks drive electrolysis capacity deployment in Germany and the Netherlands under CertifHy certification schemes.
- Automotive:Fuel cell vehicle pilot programs and hydrogen refueling station networks concentrate demand in Germany and France.
- Construction:Welding and cutting applications sustain packaged gas demand through regional distributor relationships.
Healthcare anchors contractual stability; energy absorbs capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steelmaking clusters and hydrogen infrastructure investments concentrate demand across Germany, France, the Netherlands, and emerging Central European manufacturing zones. EU Green Deal funding streams and national hydrogen strategies are reshaping production capacity deployment timelines.
Germany
Electric arc furnace retrofits at ThyssenKrupp and Salzgitter operations drive oxygen demand spikes in the Ruhr and Lower Saxony steel belts. The National Hydrogen Strategy channels €9 billion toward electrolysis hubs in the North Sea wind corridor. Hamburg and Bremen port authorities are coordinating liquid hydrogen import terminal construction with Dutch counterparts.
France
Nuclear-powered electrolysis projects in Normandy and Grand Est target ammonia and refining feedstock replacement for TotalEnergies complexes. ECHA chemical safety assessments now cover imported hydrogen catalyst precursors under REACH authorization expansions. The Dunkirk industrial zone hosts pilot carbon capture-enabled hydrogen production tied to ArcelorMittal blast furnace decarbonization.
Netherlands
Rotterdam-Antwerp corridor chemical processors procure hydrogen through quarterly indexed tenders rather than decade-long contracts. CertifHy certification schemes enable green premium capture from Scope 3-pressured buyers. Eindhoven semiconductor fabs command ultra-high-purity nitrogen premiums five to eight times standard industrial grades.
Italy
Medical oxygen buffer storage mandates now apply to hospital procurement specifications after respiratory surge disruptions in Lombardy and Veneto. SIAD Group maintains packaged gas distribution density across the Po Valley manufacturing belt. The government hydrogen roadmap targets 5 GW electrolysis capacity by 2030 concentrated in Southern port zones.
Poland
Central European manufacturing clusters lack dense pipeline infrastructure, opening merchant gas and small-scale on-site generation deployment opportunities. Messer Group specializes in regional cylinder distribution across Silesian steel and automotive welding applications. National hydrogen strategy documents prioritize coal region transition funding for electrolysis projects in Upper Silesia.
Europe Industrial Gases Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electrolysis specialization and regional merchant coverage. The market structures around three dominant positions: integrated pipeline network operators, on-site generation system providers, and packaged gas distributors filling geographic gaps. Strategic moves concentrate on hydrogen infrastructure partnerships and carbon capture retrofits rather than traditional capacity expansion.
Among Germany-based industrial conglomerates, BASF SE anchors chemical sector hydrogen demand through ammonia and methanol feedstock relationships. French-origin operators exemplify the on-site generation archetype through long-term supply contracts at petrochemical complexes. Linde PLC and Air Liquide occupy positions across multiple tiers, with the former leveraging pipeline density and the latter anchoring electronics-grade purity supply to semiconductor fabrication clusters in Ireland and the Netherlands.
| Leading Market Players |
|---|
| Messer Group |
| BASF SE |
| Linde PLC |
| Matheson Tri-Gas |
| SIAD Group |
| Air Liquide |
| SOL Group |
| Elliniki Gases |
| Air Products and Chemicals |
| Others |
Cost & Logistics Intelligence
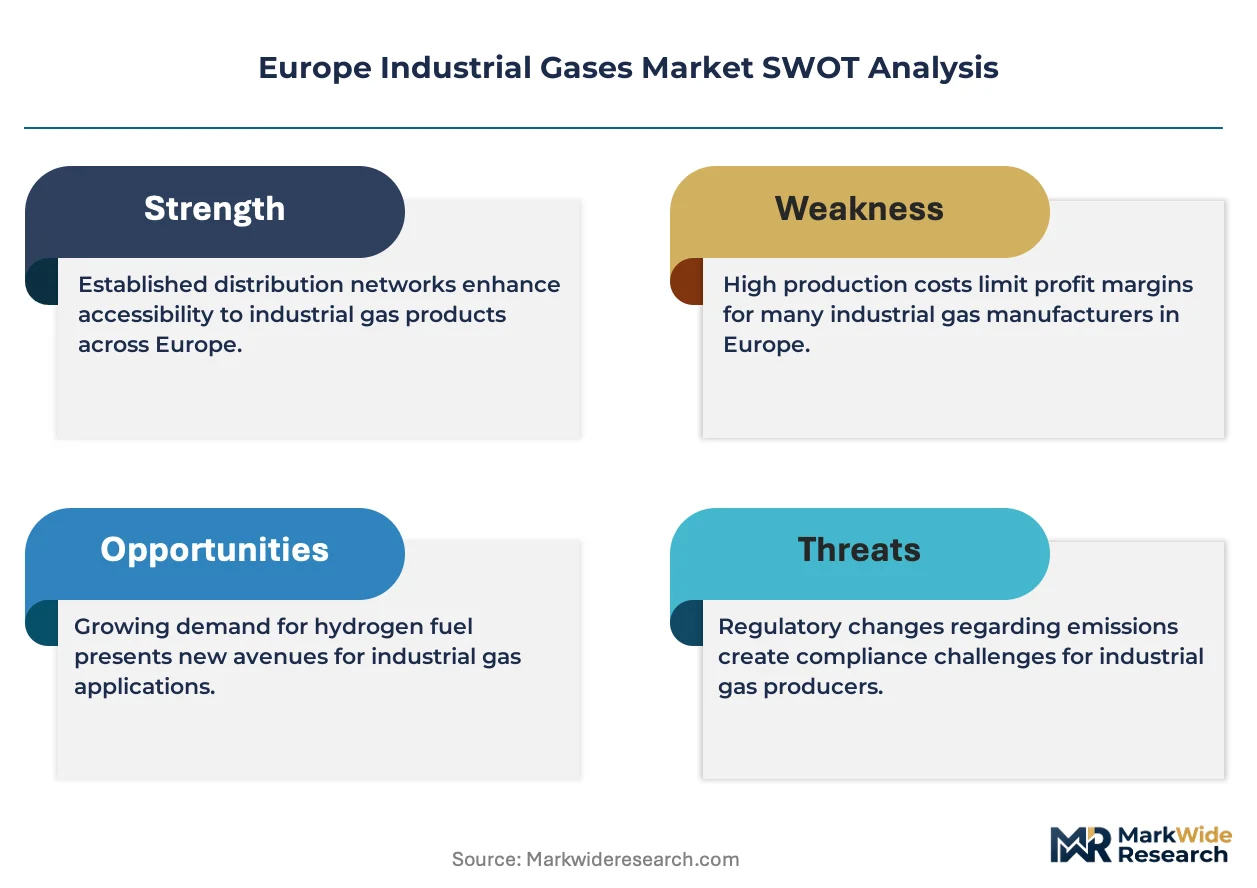
Natural gas feedstock costs cascade through hydrogen production economics, compressing margins at steam methane reformers while electrolytic routes capture green premiums under CertifHy certification. TTF hub volatility feeds directly into contract renegotiation cycles across the Rotterdam-Antwerp corridor, where quarterly indexed tenders now displace decade-long offtake agreements.
Pricing Analysis
Bulk oxygen and nitrogen trade on thin margins anchored to energy input costs, while electronics-grade nitrogen and argon command substantial premiums tied to particulate specifications. Price differentiation rests on purity certification and delivery reliability rather than brand equity. Cost compression in standard industrial grades is intensifying as electric arc furnace operators consolidate procurement volumes. Chemical processors show highest price sensitivity due to feedstock substitution options, whereas semiconductor fabs absorb premium pricing with minimal volume elasticity.
Supply Chain Analysis
Cryogenic logistics costs concentrate supply power among specialized tanker fleets serving liquid oxygen and nitrogen flows. Production clusters in Germany, the Netherlands, and Belgium anchor regional supply, drawing from air separation units and reformer complexes. Feedstock exposure to natural gas and electricity price volatility constitutes the dominant structural risk. Distribution runs through pipeline networks at integrated sites, with merchant cylinder and liquid delivery filling geographic gaps across Central and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolysis capacity deployment timelines lag demand acceleration from steel decarbonization and ammonia feedstock switching, propping hydrogen pricing power through supply scarcity.
For Market Incumbents: Cement pipeline network density through exclusive supply contracts with electric arc furnace retrofits in the Ruhr and Lower Saxony belts. Anchor on-site generation systems at Rotterdam-Antwerp petrochemical complexes to preempt merchant gas entrants. Certification investment under the EU Green Deal hydrogen backbone initiative defends position against electrolysis specialists capturing green premiums. For New Entrants and Emerging Players: Enter via packaged gas distribution across Polish and Czech manufacturing clusters where pipeline infrastructure remains underdeveloped. Target Silesian steel and automotive welding applications with regional cylinder logistics. Small-scale on-site nitrogen generation for food packaging operations offers the most penetrable entry vector with lower capital barriers. For Investors and Strategic Acquirers: Finalization of cross-border hydrogen pipeline permitting under unified pressure vessel standards is the leading indicator that trans-European backbone capacity will unlock stranded electrolysis assets. Long-term viability favors operators with integrated carbon capture capabilities or exclusive renewable power purchase structures. Acquisition targets should display captive demand from ammonia or refining offtakers under Scope 3 compliance pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolysis Hub Development | North Sea wind corridor projects in Germany and the Netherlands anchor green hydrogen supply for steel decarbonization. |
| Carbon Capture Retrofit | Steam methane reformer upgrades at Belgian and French complexes preserve asset value under EU Green Deal compliance timelines. |
| Long-term Supply Agreement | Indexed hydrogen contracts with quarterly flexibility clauses match Rotterdam-Antwerp ammonia producer hedging strategies. |
| Joint Venture | Port authority partnerships for liquid hydrogen import terminals coordinate Hamburg-Bremen-Dutch infrastructure deployment. |
| Certification Investment | CertifHy guarantee-of-origin schemes enable premium capture from Scope 3-pressured refining and chemical buyers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Industrial Gases Market assessment. Primary interviews with air separation unit operators, hydrogen procurement leads at refineries, cryogenic logistics specialists, and ECHA regulatory affairs directors combined with Cefic industry statistics, SEC filings from listed producers, and EU hydrogen strategy implementation reports. Bottom-up capacity deployment tracking and top-down demand segmentation triangulated volume estimates across the analysis window.
Granularity-level modeling distinguished electrolytic from carbon capture-enabled hydrogen production routes, purity grades from standard industrial to electronics specifications, and delivery modes spanning pipeline, on-site generation, and merchant distribution. CAGRs derived from production capacity commissioning schedules, steel mill retrofit timelines, and semiconductor fab expansion announcements. Forecast inputs incorporated TTF natural gas price scenarios and renewable electricity cost curves without year-specific anchoring.
Revisions become necessary when cross-border hydrogen pipeline permitting harmonization stalls, electrolysis capacity deployment accelerates beyond steel demand absorption, or F-Gas Regulation phasedown timelines compress refrigerant replacement cycles. Forecasts reflect documented assumptions about EU Green Deal funding continuity and carbon border adjustment mechanism implementation scope. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market