
 Helium Market | 2026-2036
Helium Market Size, Share, and Industry Trends Forecast 2026-2036
Helium Market Intelligence
Modular cylinder leasing and fractional ownership models are rebalancing procurement economics for mid-volume buyers. ExxonMobil Corporation leverages its integrated natural gas processing footprint to capture helium as a secondary stream. Air Liquide anchors European supply through cryogenic logistics networks. Linde plc competes on global distribution density across semiconductor corridors.
Helium is a noble gas with atomic number 2, boiling point of minus 268.9 degrees Celsius, and zero reactivity under standard conditions, making it irreplaceable for ultra-low-temperature applications and inert atmosphere control. Industrial helium dominates volume flows through steel and aerospace welding operations. Medical helium sustains premium pricing through respiratory therapy and MRI magnet cooling protocols. High-purity helium captures the fastest expansion as extreme ultraviolet lithography nodes demand six-nines purity standards.
The U.S. Bureau of Land Management, the EU F-Gas Regulation, and South Korea's MFDS shape helium allocation through reserve divestiture protocols, fluorinated gas phase-down mandates, and medical gas import certification respectively. Stakeholders must monitor regulatory stockpile releases against semiconductor capacity buildouts to anticipate supply tightness.
Market Dynamics
Semiconductor fabrication at sub-3nm nodes is compressing helium supply chains as EUV lithography systems demand six-nines purity in volumes that outpace conventional extraction economics. This single end-use vertical now dictates allocation priority across all regional markets.
Growth Catalysts
- EUV Lithography Expansion:Extreme ultraviolet systems at 3nm and below require helium for plasma generation and wafer temperature control, pulling volume from industrial grades into semiconductor corridors.
- US Federal Helium Reserve Divestiture:The Bureau of Land Management's privatization protocols are forcing domestic buyers to secure long-term offtake agreements with private producers.
- Medical Gas Certification Mandates:South Korea's MFDS and the EU MDR are tightening import standards for MRI magnet cooling, locking in premium-grade demand regardless of price volatility.
Market Restraints
- Geologic Concentration Risk:Commercial helium reserves cluster in natural gas formations across the US Great Plains, Qatar's North Field, and Algeria's Hassi R'Mel, creating single-point failure exposure.
- Extraction Cost Structure:Helium capture requires cryogenic separation from methane at minus 269 degrees Celsius, making marginal fields uneconomic when natural gas prices collapse.
- Regulatory Friction:The EU F-Gas Regulation treats helium as a fluorinated gas equivalent for reporting purposes, adding compliance overhead without addressing actual climate impact.
Strategic Opportunities
- Fractional Ownership Models:Modular cylinder leasing programs are penetrating mid-volume buyers in Taiwan's Hsinchu Science Park and South Korea's Yongin cluster, reducing working capital requirements.
- Space Launch Propulsion:Reusable rocket programs are integrating helium for tank pressurization and purge systems, creating demand elasticity outside semiconductor cycles.
- Quantum Computing Cryogenics:Dilution refrigerator manufacturers are specifying helium-3 isotope blends for millikelvin cooling, opening specialty isotope markets.
Industry Challenges
- Cryogenic Logistics Talent Scarcity:Qualified technicians for superfluid helium handling are concentrated at Air Liquide and Linde training centers, constraining regional distribution expansion.
- Certification Timeline Compression:Six-nines purity validation for EUV applications requires 90-day analytical protocols that delay spot market responsiveness during supply shocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helium Market |
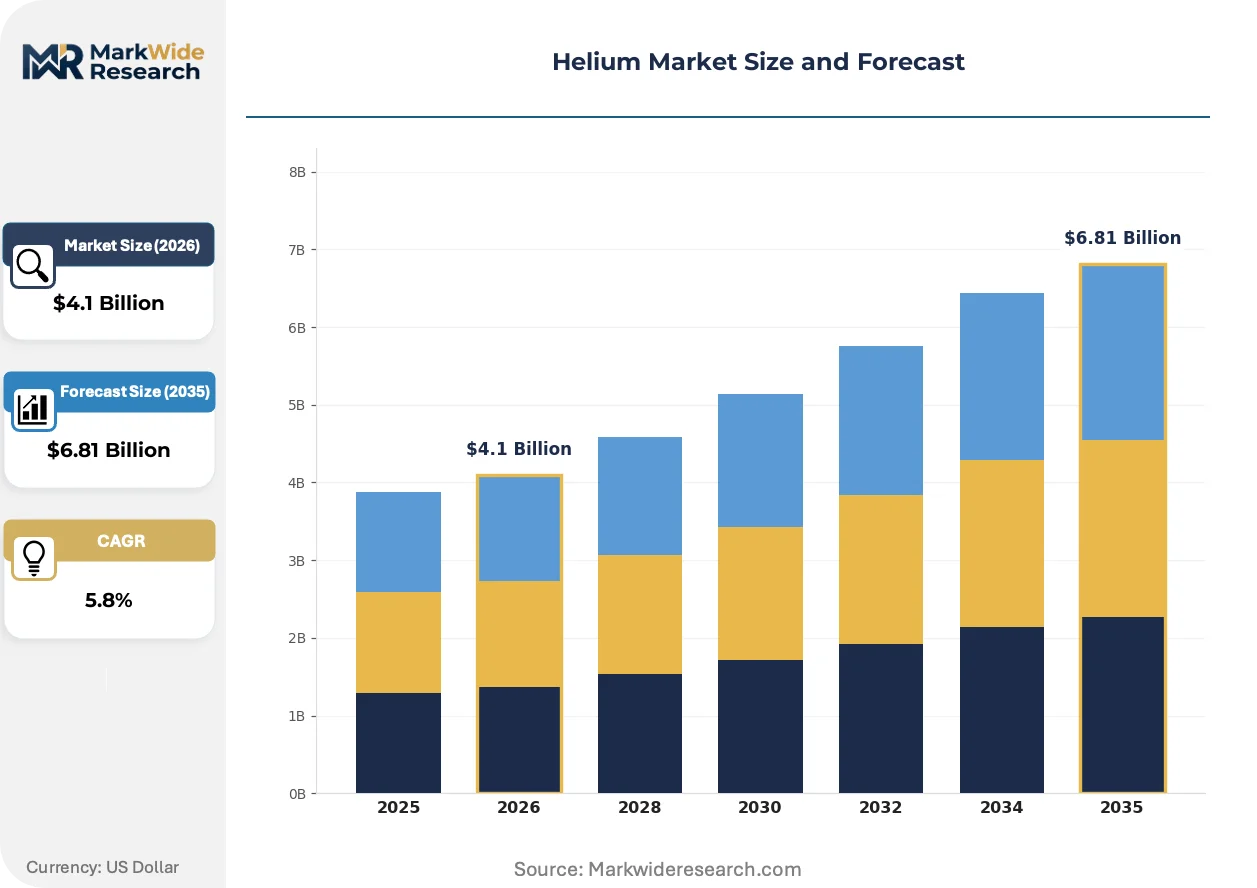
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Helium, Medical Helium, High-Purity Helium, Specialty Gas Helium Application: Cryogenics, Leak Detection, Welding, Controlled Atmospheres, Balloon Inflation End User: Healthcare Facilities, Semiconductor Manufacturers, Research Laboratories, Metal Fabricators Distribution Channel: Direct Sales, Distributors, Online Platforms, Gas Suppliers |
| Companies Covered | ExxonMobil Corporation, Messer Group, Air Liquide, North American Helium, Iwatani Corporation, Air Products and Chemicals, Inc., Gazprom, Gulf Cryo, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helium Market Strategic Shifts & Innovations
Helium supply chains are bifurcating between commodity industrial flows and captive semiconductor-grade streams, with technology lock-in effects hardening faster than regulatory frameworks can adapt.
Membrane separation technology is integrating with traditional cryogenic distillation to boost helium recovery rates from previously subeconomic natural gas streams. Mid-size processors in the US Permian Basin are piloting hybrid systems that cut energy intensity by one-third. This convergence is compressing the minimum viable scale for helium production, fragmenting supply concentration.
The EU F-Gas Regulation is tightening reporting thresholds for helium imports despite its zero global warming potential, creating administrative drag on European buyers. Industrial gas distributors are consolidating import licenses to amortize compliance costs across larger volume bases. Medical and semiconductor end-users in Germany and France are absorbing premium pricing to secure certified supply chains ahead of 2027 phase-down milestones.
Long-term offtake contracting is displacing spot market purchases among Taiwanese and South Korean fabrication clusters. Buyers are accepting five-year fixed-price structures with built-in escalation clauses rather than weathering auction volatility. This behavioral shift is most visible in Hsinchu and Yongin, where foundries are directly financing extraction infrastructure in exchange for priority allocation rights.
Helium Market Segmentation
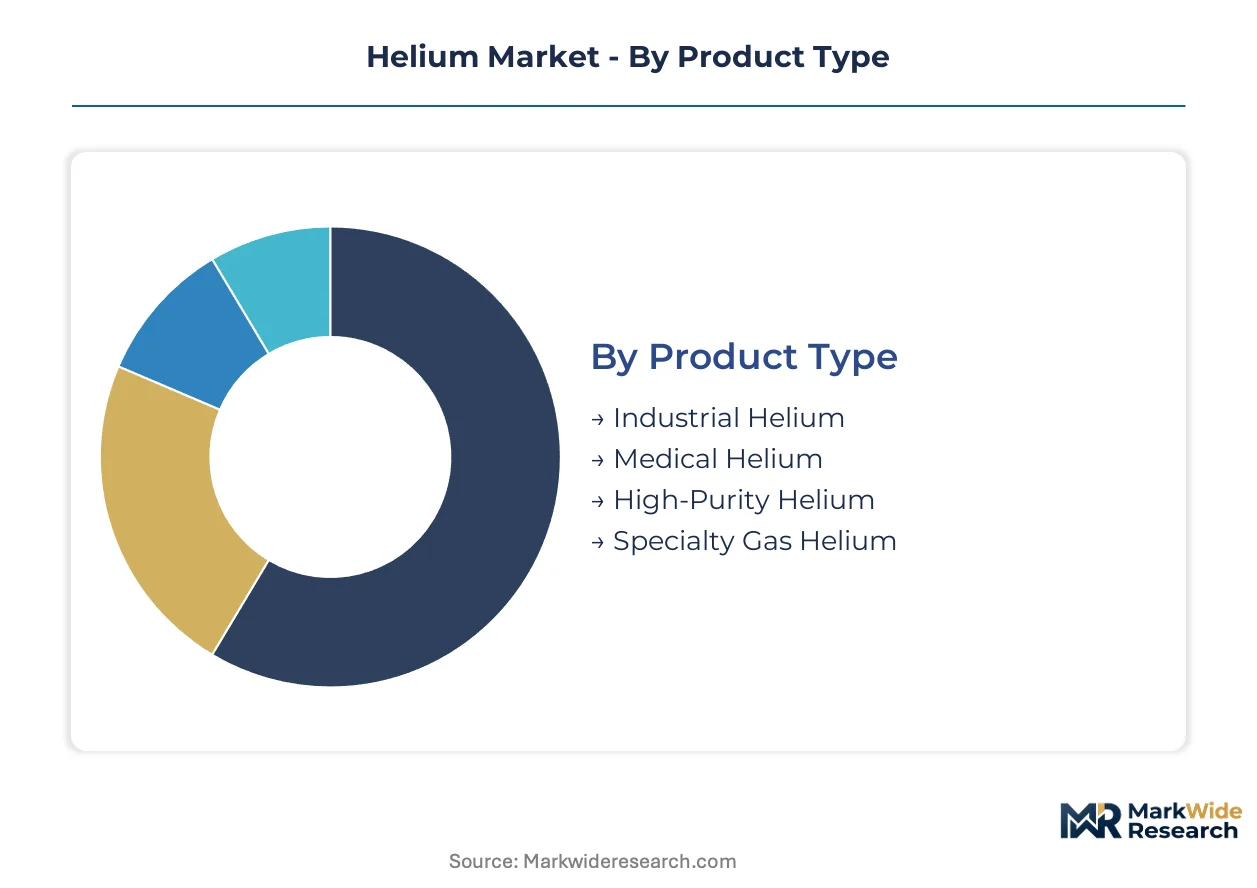
Helium supply chains fragment across purity grades and end-use specifications, with semiconductor fabs and MRI networks commanding allocation priority. Understanding these divides exposes where pricing power concentrates and where substitution risk looms.
Product Type:
Supply concentration tilts toward cryogenic separation facilities in Qatar's North Field and the US Great Plains, with purity thresholds determining which streams reach which buyers.
- Industrial Helium:Standard-grade helium at 99.997% purity serves steel welding and aerospace fabrication. Metal fabricators in Germany's Ruhr Valley and Japan's Chiba Prefecture absorb steady volumes for shielding gas applications, though spot pricing remains vulnerable to semiconductor-grade pull-through.
- Medical Helium:Ultra-high purity helium for MRI magnet cooling and respiratory therapy meets FDA and EU MDR certification protocols. South Korea's MFDS import requirements lock hospital networks into validated supply chains regardless of cost spikes.
- High-Purity Helium:Six-nines (99.9999%) specification for EUV lithography plasma generation. Taiwan's Hsinchu Science Park and Samsung's Yongin cluster now pre-purchase five-year allocations directly from Qatari processors.
- Specialty Gas Helium:Helium-3 isotope blends and custom mixtures for dilution refrigerators in quantum computing labs. Oak Ridge National Laboratory and Delft University facilities anchor niche demand.
Industrial helium absorbs the bulk of installed capacity; high-purity helium is expanding most quickly.
Application:
Cost tier stratification separates commodity uses from premium-grade applications where technical substitution is impossible.
- Cryogenics:Superfluid helium at 2.17 Kelvin enables superconducting magnets in MRI scanners and particle accelerators. CERN's Large Hadron Collider and Siemens Healthineers' magnet production in Erlangen, Germany anchor European demand.
- Leak Detection:Helium mass spectrometry for semiconductor chamber integrity testing and vacuum system validation. Applied Materials and ASML specify tracer gas protocols that lock in consumption.
- Welding:Inert atmosphere shielding for titanium and aluminum joining in aerospace supply chains. Boeing's Everett facility and Airbus Hamburg operations maintain contracted volumes.
- Controlled Atmospheres:Purge and inerting for fiber optic manufacturing and silicon crystal growth. Corning's Wilmington, North Carolina plant runs dedicated helium supply.
- Balloon Inflation:Party and scientific balloon applications now face allocation rationing during supply shocks. This segment bears first-cut volume reductions when semiconductor demand surges.
Welding and controlled atmospheres command stable contract pricing; cryogenics captures the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with semiconductor fabs negotiating direct offtake while smaller buyers rely on distributor intermediaries.
- Healthcare Facilities:Hospital networks and imaging centers require uninterrupted MRI cooling supply. The UK's NHS and France's AP-HP operate strategic helium reserves against disruption.
- Semiconductor Manufacturers:TSMC, Samsung, and Intel now finance extraction infrastructure for priority allocation. Sub-3nm EUV nodes pull volume from all other grades during capacity ramps.
- Research Laboratories:National labs and university physics departments face allocation competition from commercial buyers. CERN and Brookhaven National Laboratory secure government-protected quotas.
- Metal Fabricators:Steel and aluminum processors purchase industrial grade through regional gas distributors. This buyer class lacks leverage during supply tightness.
Semiconductor manufacturers now absorb the dominant share of high-purity flows; healthcare facilities retain the most inelastic demand profile.
Distribution Channel:
Channel structure reflects volume scale and purity requirements, with direct sales capturing premium tiers and distributors serving fragmented industrial demand.
- Direct Sales:Long-term offtake agreements between Qatari producers and Taiwanese foundries. These contracts now include built-in price escalation and volume flex provisions.
- Distributors:Regional industrial gas networks like Airgas and Messer serve welding and balloon customers. Inventory pooling buffers small buyers against spot volatility.
- Online Platforms:Emerging digital procurement for cylinder exchanges and small-volume laboratory supply. Limited penetration outside North America.
- Gas Suppliers:Integrated majors Linde and Air Liquide operate captive logistics networks. Their cryogenic tanker fleets control last-mile delivery for medical and semiconductor customers.
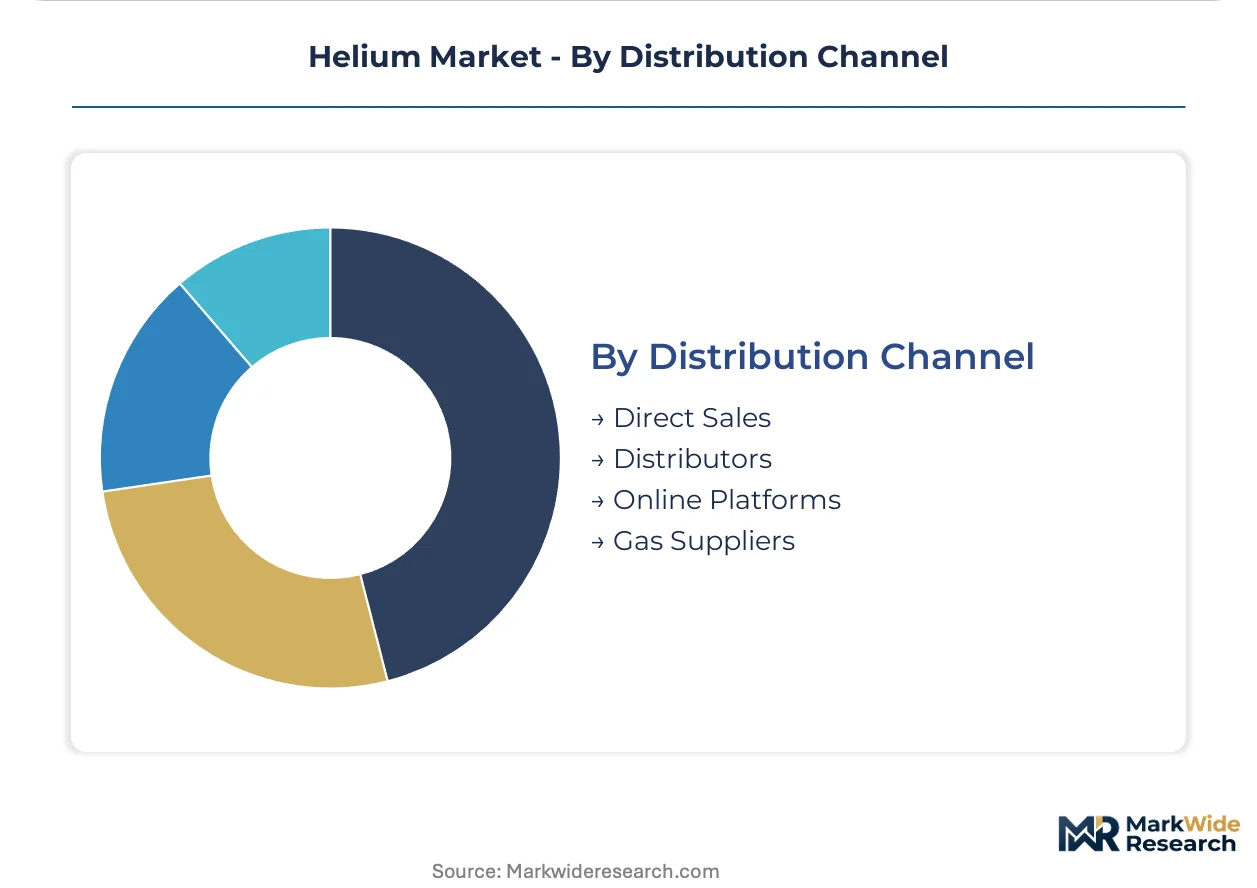
Direct sales channels are gaining share fastest; distributor networks retain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar and the United States concentrate extraction capacity while East Asian fabrication clusters consume the dominant share of high-purity output. This geographic mismatch forces long-haul cryogenic logistics and shapes procurement strategies across consuming regions.
United States
The Bureau of Land Management's reserve divestiture is forcing domestic semiconductor fabs and MRI networks into direct offtake negotiations with private producers. FDA and EPA protocols govern medical and industrial gas certification respectively. The Permian Basin in Texas anchors emerging extraction projects that supply Hsinchu and Yongin through long-term contracts.
Qatar
North Field expansion projects position the emirate as the dominant source for six-nines purity helium bound for EUV lithography clusters. The central energy regulator oversees natural gas processing quotas that determine helium capture volumes. Ras Laffan Industrial City hosts cryogenic separation facilities that pre-sell five-year allocations to TSMC and Samsung.
Taiwan
TSMC's sub-3nm ramp is pulling global high-purity supply toward Hsinchu Science Park regardless of spot price spikes. The Ministry of Economic Affairs coordinates strategic reserve protocols for critical industrial gases. Kaohsiung port infrastructure is expanding cryogenic tanker reception capacity to handle Qatari direct shipments.
South Korea
Samsung and SK Hynix are financing extraction infrastructure abroad in exchange for priority allocation rights under MFDS import certification mandates. The Yongin cluster now operates dedicated helium storage against supply disruption. National technology sovereignty programs classify high-purity helium as a strategic material requiring inventory buffers.
Germany
Siemens Healthineers' MRI magnet production in Erlangen and CERN procurement through Geneva anchor European medical and research demand. The EU F-Gas Regulation imposes reporting burdens that industrial gas distributors absorb through license consolidation. The Ruhr Valley's steel fabricators face allocation competition from semiconductor buyers during global tightness.
Helium Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across extraction, purification, and distribution layers. The market structure tilts toward consolidation at the top tier where integrated majors control cryogenic logistics networks, while mid-volume processors fragment across regional natural gas basins. Three archetypes dominate: integrated energy majors capturing helium as secondary streams, industrial gas specialists with captive distribution infrastructure, and emerging pure-play extractors targeting specific geological formations. Competitive moves center on long-term offtake contracting with semiconductor fabs and backward integration into extraction assets.
Among integrated energy majors, ExxonMobil Corporation exemplifies the secondary-stream capture archetype through natural gas processing scale. Air Liquide and Linde plc occupy positions within the industrial gas specialist tier, anchoring European and global distribution density respectively. These three entities represent contrasting strategic postures: upstream resource leverage versus downstream logistics control.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Messer Group |
| Air Liquide |
| North American Helium |
| Iwatani Corporation |
| Air Products and Chemicals, Inc. |
| Gazprom |
| Gulf Cryo |
| Linde plc |
| Others |
Cost & Logistics Intelligence
Five-year fixed-price offtake commitments from TSMC and Samsung are forcing Qatari processors to lock in extraction capacity years ahead of production, compressing spot market liquidity and amplifying price volatility for uncontracted buyers. This procurement shift rewards integrated majors with captive supply while marginalizing distributor-dependent industrial accounts.
Pricing Analysis
Margin tightening in industrial-grade helium reflects semiconductor-grade pull-through during EUV capacity ramps, with spot premiums widening against contract baselines. Three-tier pricing structure across six-nines semiconductor, medical-grade MRI, and standard industrial certification levels anchors differentiation. Cost-down pressure on balloon and welding segments accelerates because fabs now absorb volume regardless of price. Metal fabricators exhibit highest price sensitivity; MRI networks show least elasticity due to MFDS and FDA certification lock-in.
Supply Chain Analysis
Cylinder return and refurbishment flows from Taiwan's Hsinchu cluster back to Ras Laffan are compressing working capital cycles for modular leasing programs. Supply concentrates in Qatar's North Field, the US Permian Basin, and Algeria's Hassi R'Mel, with cryogenic separation capacity tethered to natural gas processing economics. Raw material dependencies span methane feedstock, liquid nitrogen for pre-cooling, and specialized aluminum alloy tanks. Single-source vulnerability from BLM reserve divestiture dominates risk profiles. Distribution runs through integrated majors' captive tanker fleets for premium tiers, regional distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race: control over cryogenic logistics networks or Qatari extraction slots determines who captures margin in semiconductor corridors.
For Market Incumbents: Lock in five-year offtake extensions with Yongin and Hsinchu fabs before pure-play extractors commission competing capacity. Deepen backward integration into Permian Basin processing infrastructure to offset BLM reserve loss. Prioritize certification investment for six-nines validation protocols against emerging membrane separation rivals. For New Entrants and Emerging Players: Mid-volume research laboratories in Germany and France face allocation competition from commercial buyers yet lack direct procurement leverage. White-space targets span quantum computing dilution refrigerator supply and fractional ownership programs for university physics departments. A go-to-market angle through digital cylinder exchange platforms bypasses integrated majors' distributor lock-in. For Investors and Strategic Acquirers: The window for entry favors pure-play helium extractors with permitted North American acreage over diversified gas processors. Long-term viability rests on proximity to semiconductor demand corridors rather than industrial welding density. Monitor BLM reserve release schedules and TSMC capex disclosures as inflection indicators for supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | TSMC's five-year Qatari offtake locks in six-nines priority allocation against spot volatility. |
| Backward Integration | ExxonMobil's Permian processing expansion captures helium as secondary natural gas stream. |
| Capacity Expansion | Ras Laffan cryogenic separation buildout targets EUV lithography purity specifications. |
| Joint Venture | Samsung's Yongin infrastructure financing secures MFDS-certified supply chain control. |
| Technology Licensing | Membrane-cryogenic hybrid systems from US mid-size processors fragment minimum viable scale. |
Research Approach
Independent corroboration across cryogenic logistics operators, semiconductor fab procurement directors, and natural gas processing engineers underwrites the qualitative findings. Primary fieldwork engaged helium plant managers, MRI facility biomedical engineers, and industrial gas distributor account executives. Secondary validation drew from BLM reserve divestiture protocols, EU F-Gas Regulation filings, and customs trade data for cryogenic tanker movements. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Rate-of-change decomposition separated volume growth from purity-grade mix shifts and regional demand rebalancing across the projection horizon. The analytical framework modeled helium supply across purity tier, end-use application, distribution channel, and regional regulatory cluster. CAGRs derived from time-series extrapolation of extraction capacity additions against semiconductor node transition schedules. Forecast inputs incorporated EUV lithography adoption curves and BLM reserve release trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Qatar's North Field expansion timing and sub-2nm node helium intensity. Forecasts reflect documented assumptions on substitution elasticity and regulatory phase-down stringency. Practitioners should monitor TSMC and Samsung capex announcements, BLM auction schedules, and membrane separation pilot results for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Xenon Gas Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Krypton Gas Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
Gas Purifiers Market