
 Global Syngas and Derivatives Market | 2026-2036
Global Syngas and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Syngas and Derivatives Market Foresight
Long-term offtake contracts for hydrogen and ammonia are reconfiguring how syngas producers secure revenue visibility across power-to-x value chains. Sasol Limited anchors its position through proprietary Fischer-Tropsch technology and integrated coal-to-liquids complexes in South Africa. Air Liquide S.A. dominates industrial gas distribution networks, leveraging pipeline clusters around Rotterdam and the US Gulf Coast to sustain hydrogen delivery economics. Linde plc competes through large-scale steam methane reformers and carbon capture retrofits at existing syngas facilities.
Syngas and derivatives encompass synthesis gas—a blend of hydrogen and carbon monoxide produced via gasification, partial oxidation, or reforming of hydrocarbon feedstocks—and the downstream chemicals, fuels, and industrial gases manufactured from it, typically operating at pressures of 20–70 bar and temperatures of 800–1,600°C depending on the technology route. The primary commercial purpose centers on converting carbonaceous materials into storable energy carriers and chemical building blocks for fertilizers, fuels, and refined metals. Ammonia derived from syngas maintains the largest volume footprint due to entrenched fertilizer demand, while hydrogen from autothermal and steam reforming captures the fastest growth trajectory as steelmakers and shipping operators seek decarbonization pathways. Gasification technology retains margin concentration in regions with low-cost coal or biomass feedstock access.
The US EPA enforces New Source Performance Standards that constrain emissions from syngas manufacturing facilities, pushing operators toward carbon capture integration or feedstock switching to natural gas and biomass. The EU Green Deal and associated F-Gas Regulation tighten carbon intensity benchmarks for imported hydrogen and ammonia, reshaping trade flows and certification requirements. China's MEE implements dual carbon goals that mandate efficiency upgrades at coal gasification plants while channeling investment into electrolysis-based hydrogen. Stakeholders must monitor how divergent carbon accounting standards across these jurisdictions fragment market access and capital allocation priorities.
Market Dynamics
Capital deployment across syngas and derivatives is pivoting toward carbon capture integration as the EU Green Deal and China's dual carbon goals harden emission intensity thresholds for hydrogen and ammonia offtake contracts.
Growth Catalysts
- Steel Decarbonization Mandates:European steelmakers under EU ETS Phase IV are contracting green hydrogen-derived direct reduced iron, pulling syngas reforming capacity toward low-carbon ammonia feedstock.
- F-Gas Regulation:The EU F-Gas Regulation is tightening leakage standards for fluorinated gases used in syngas cooling loops, accelerating membrane separation technology adoption at Rotterdam and Antwerp pipeline clusters.
- Biomass Gasification Economics:Agricultural residue collection networks in India and Brazil are achieving feedstock scale sufficient to sustain 100+ MW biomass-to-syngas units without fossil price linkage.
Market Restraints
- Coal Price Volatility:Indonesian and Australian thermal coal benchmarks swing 40-60% annually, eroding margin predictability at coal-gasification complexes in China and South Africa.
- Reformer Catalyst Supply Concentration:Nickel and cobalt catalyst manufacturing concentrates in Russian and Chinese refiners, exposing European and North American operators to export restriction risk.
- Electrolysis Cost Floor:Alkaline and PEM electrolyzer stack costs remain above $400/kW at scale, blocking green hydrogen from displacing steam methane reforming in cost-sensitive ammonia markets.
Strategic Opportunities
- Saudi Arabia NEOM Integration:The kingdom's giga-scale renewable hydrogen clusters offer offtake anchoring for syngas-to-ammonia exporters seeking 15-20 year purchase agreements with sovereign credit backing.
- CCUS Tax Credit Stacking:The US IRA 45Q credit combined with state-level clean fuel programs creates effective carbon capture economics at Texas and Louisiana Gulf Coast reforming facilities.
- Autothermal Reforming Convergence:Integration of cryogenic air separation with autothermal reforming is collapsing oxygen production costs for partial oxidation units serving methanol and Fischer-Tropsch synthesis.
Industry Challenges
- Process Control Engineering Scarcity:Gasification and reforming facilities face 18-24 month recruitment timelines for distributed control system specialists capable of managing 800-1,600°C reaction zones.
- Certification Timeline Compression:EU CertifHy and TÜV SÜD low-carbon hydrogen certification requires 6-12 month validation cycles that lag behind offtake contract execution windows.
- Legacy ASU Retrofit Complexity:Air separation units built for 90% oxygen purity require complete cold box replacement to achieve 99.5% purity demanded by blue hydrogen production, doubling capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Syngas and Derivatives Market |
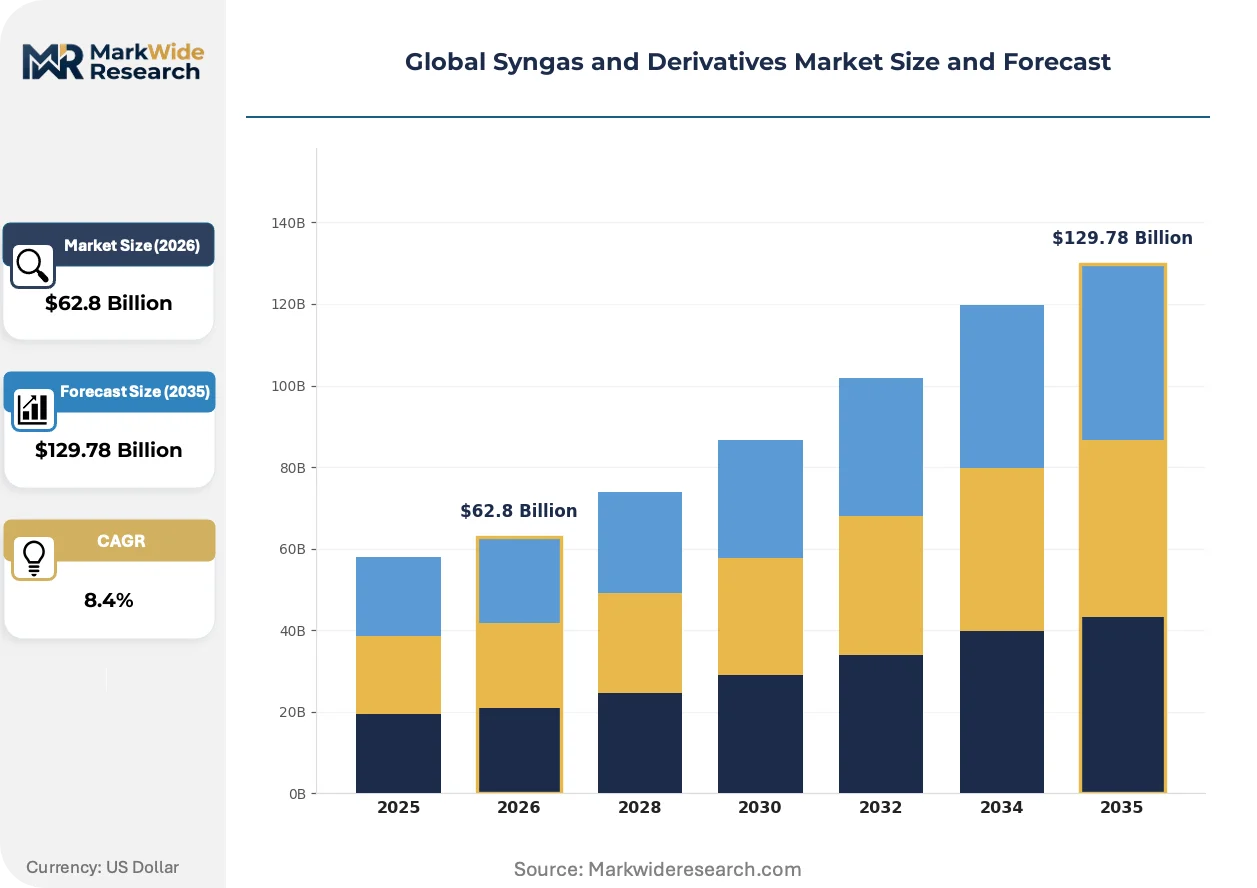
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $129.78 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthesis Gas, Methanol, Hydrogen, Ammonia, Formaldehyde Application: Power Generation, Chemical Synthesis, Fuel Production, Metal Refining, Biofuel Conversion Technology: Gasification, Partial Oxidation, Steam Reforming, Autothermal Reforming, Plasma Reforming End User: Chemical Manufacturing, Energy Sector, Metal Processing, Bioenergy Plants, Industrial Gases Providers |
| Companies Covered | Sasol Limited, Air Liquide S.A., Air Products and Chemicals Inc., Linde plc, BASF SE, Shell PLC, KBR Inc., Haldor Topsoe A/S, TechnipFMC PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Syngas and Derivatives Market Shifts & Advancements
Technology migration across syngas production is compressing the cost delta between fossil and renewable hydrogen pathways while regulatory fragmentation forces multimodal compliance architectures.
Plasma gasification is migrating from municipal waste destruction toward hazardous industrial residue processing. Chemical manufacturers in Germany and Japan are piloting 50 MW units for chlorinated solvent recovery. The technology is migrating from batch-fed waste applications to continuous industrial feedstock conversion, enabling syngas yields above 85% from previously non-recyclable process residues.
REACH authorization requirements for nickel catalyst precursors are forcing reforming operators toward iron-based alternatives. The ECHA sunset date for unregistered nickel compounds is compressing catalyst procurement timelines. European ammonia producers are responding by qualifying Chinese and Indian iron-molybdenum catalyst suppliers ahead of 2026 authorization deadlines.
Long-term hydrogen offtake contracting is displacing spot market exposure for syngas derivatives. Steel and shipping operators in South Korea and the Netherlands are securing 10-15 year ammonia supply agreements with fixed-price escalation clauses. This contract structure is most visible at Rotterdam and Singapore trading hubs, where term sheets now standardize carbon intensity certification as a delivery condition.
Global Syngas and Derivatives Market Segmentation
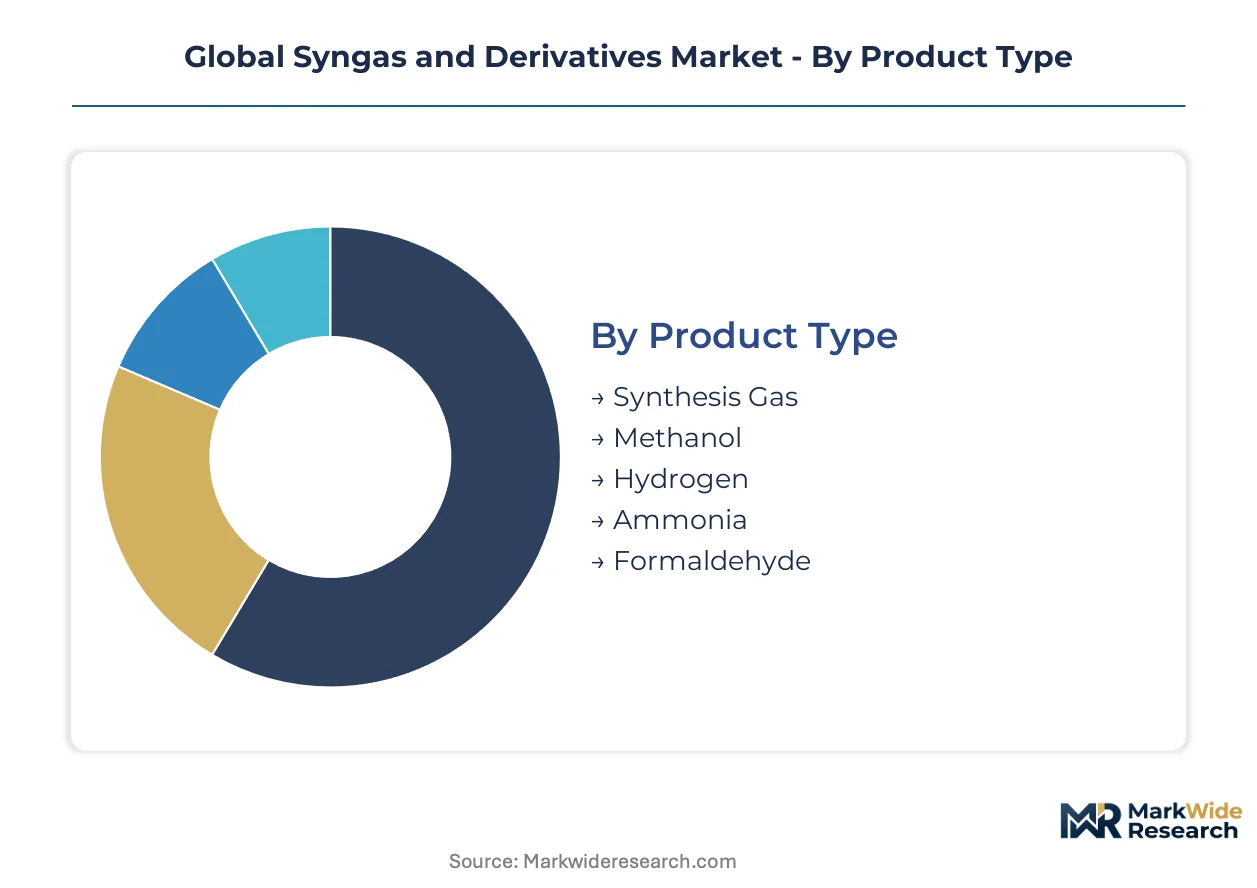
Segmentation across syngas and derivatives reveals how feedstock economics, carbon intensity mandates, and end-use specifications fragment procurement patterns. Each dimension captures distinct margin structures and technology lock-ins that shape capital deployment priorities.
Product Type:
Cost tier differentiation across syngas products separates commodity ammonia from premium hydrogen grades with diverging carbon certification requirements.
- Synthesis Gas:A hydrogen-carbon monoxide blend produced at 20–70 bar and 800–1,600°C serving as the universal upstream feedstock. Steelmakers in Germany and South Korea are contracting certified low-carbon syngas under EU ETS and K-ETS compliance deadlines.
- Hydrogen:Purified H2 from steam methane reforming, autothermal reforming, or electrolysis integration. Rotterdam and Singapore trading hubs now standardize carbon intensity thresholds in term sheets as shipping operators seek ammonia cracking feedstock.
- Methanol:CH3OH synthesis via copper-zinc oxide catalysis from syngas feeds. Maritime fuel blending specifications in the EU and China are pulling methanol demand toward renewable carbon pathways.
- Ammonia:NH3 produced via Haber-Bosch synthesis with nitrogen from air separation. Fertilizer demand in India and Brazil sustains volume, while bunkering contracts in the Netherlands and Japan drive low-carbon premium grades.
- Formaldehyde:CH2O derivative for resins and specialty chemicals. Construction sector demand in China and the United States concentrates consumption, though urea-formaldehyde substitution pressures are mounting.
Ammonia holds installed capacity. Hydrogen is rotating up the share rankings.
Application:
Application segmentation tracks how syngas derivatives bridge power, materials, and mobility sectors with diverging carbon accounting rules.
- Chemical Synthesis:Methanol-to-olefins, ammonia-to-fertilizer, and Fischer-Tropsch liquid production. Chinese coal-to-chemicals complexes and Middle Eastern gas-based units compete on feedstock cost, with EU carbon border adjustments reshaping trade economics.
- Fuel Production:Synthetic diesel, jet fuel, and marine gasoil from Fischer-Tropsch or methanol-to-gasoline pathways. The EU Renewable Energy Directive and IMO 2024 carbon intensity indicators are pulling investment toward bio-syngas integration.
- Power Generation:Syngas combustion in integrated gasification combined cycle plants. Limited newbuild activity concentrates in regions with stranded coal assets or biomass residue availability.
- Metal Refining:Direct reduced iron production using syngas-derived hydrogen. European steelmakers under EU ETS Phase IV are contracting green hydrogen offtake, displacing natural gas-based DRI.
- Biofuel Conversion:Agricultural and forestry residue gasification to renewable syngas. Collection network economics in India and Brazil are achieving scale without fossil price linkage.
Chemical Synthesis anchors volume demand. Fuel Production is climbing the fastest.
Technology:
Technology segmentation captures the divergence between mature thermal routes and emerging plasma and electrolysis-hybrid systems.
- Steam Reforming:Endothermic methane conversion at 700–1,000°C with nickel catalysts. The US Gulf Coast and Rotterdam pipeline clusters sustain hydrogen delivery economics through scale, with 45Q tax credits accelerating carbon capture retrofits.
- Gasification:Partial oxidation of coal, biomass, or petroleum coke at 1,200–1,600°C. China's dual carbon goals mandate efficiency upgrades at coal gasification plants while channeling investment into biomass and waste feedstocks.
- Autothermal Reforming:Combined steam and partial oxidation with internal heat balance. Integration with cryogenic air separation is collapsing oxygen production costs for methanol and Fischer-Tropsch synthesis.
- Partial Oxidation:Non-catalytic hydrocarbon conversion with oxygen. Heavy residue processing in refineries sustates niche demand, though competing with residue hydrocracking.
- Plasma Reforming:Electric arc dissociation of waste or hazardous residues. German and Japanese chemical manufacturers are piloting 50 MW units for chlorinated solvent recovery with syngas yields above 85%.
Steam Reforming holds installed capacity. Autothermal Reforming is gaining share fastest.
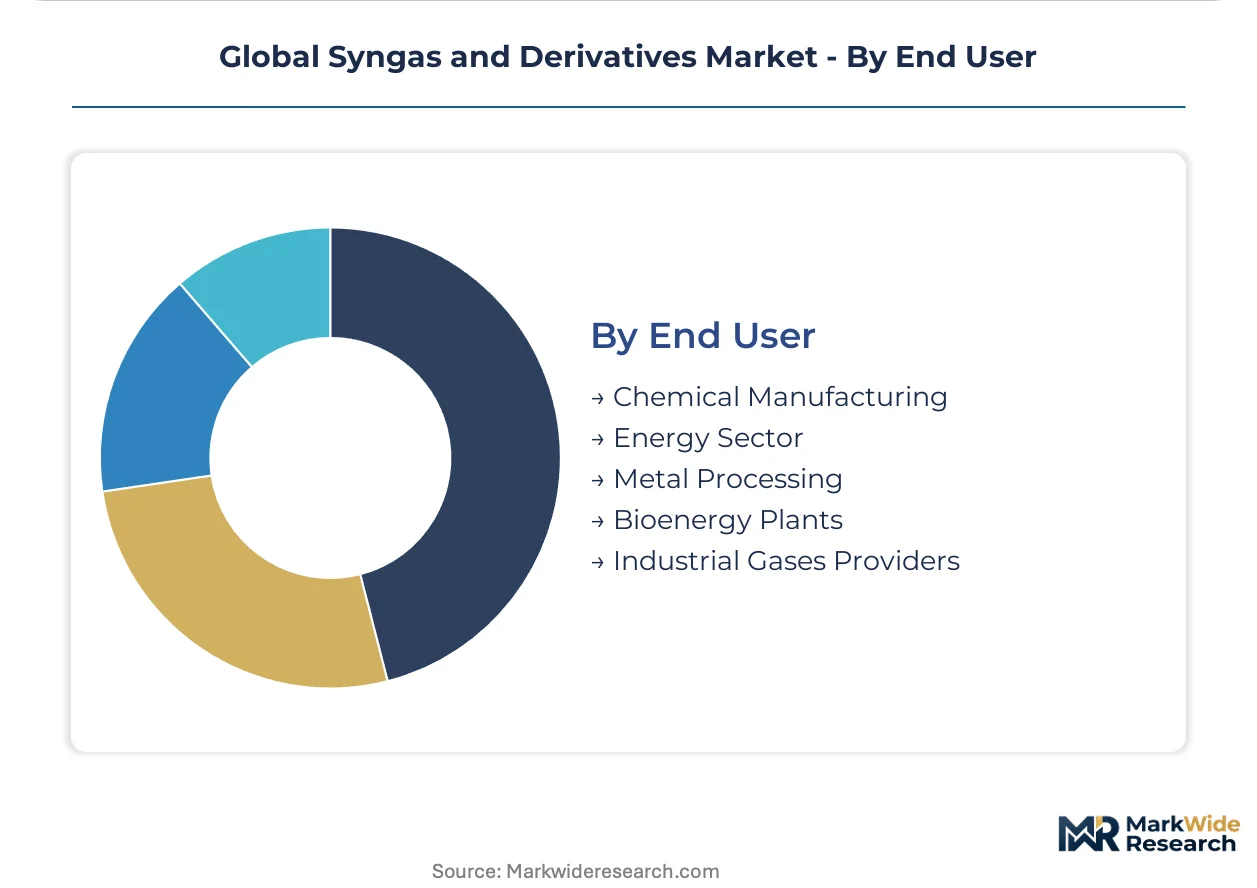
End User:
Customer type segmentation separates commodity offtakers from premium hydrogen buyers with diverging contract tenors and certification requirements.
- Chemical Manufacturing:Ammonia, methanol, and hydrogen offtake for fertilizer, plastics, and solvents. REACH authorization deadlines for nickel catalysts are compressing procurement timelines and forcing iron-based alternative qualification.
- Energy Sector:Power generators and gas utilities seeking hydrogen blending or synthetic methane. EU F-Gas Regulation tightening on fluorinated cooling gases is accelerating membrane separation adoption.
- Metal Processing:Steelmakers and aluminum smelters requiring hydrogen for DRI or reduction processes. South Korean and Dutch operators are securing 10–15 year ammonia supply agreements with fixed-price escalation clauses.
- Bioenergy Plants:Operators converting agricultural residues to renewable syngas. Feedstock collection scale in India and Brazil is sustaining 100+ MW units without fossil price linkage.
- Industrial Gases Providers:Air Liquide, Linde, and regional distributors managing pipeline clusters. Certification timeline compression at EU CertifHy and TÜV SÜD is lagging behind offtake contract execution windows.
Chemical Manufacturing anchors volume offtake. Metal Processing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam hydrogen pipeline cluster anchors Northwest Europe's syngas distribution architecture, while China's coal-to-chemicals corridor along the Yellow River basin concentrates global gasification capacity. The US Gulf Coast steam methane reforming network connects Texas and Louisiana production to ammonia and methanol export terminals.
China
Steelmakers in Hebei and Jiangsu provinces are contracting hydrogen-derived direct reduced iron under MEE dual carbon compliance deadlines. The country's dual carbon goals mandate efficiency upgrades at coal gasification plants while channeling investment into electrolysis-based hydrogen production. The Ningxia-Inner Mongolia corridor hosts integrated coal-to-olefins complexes scaling biomass co-gasification pilots.
United States
Gulf Coast ammonia exporters are securing 45Q tax credit stacking for carbon capture retrofits at Texas and Louisiana reforming facilities. EPA New Source Performance Standards constrain emissions from syngas manufacturing, pushing operators toward feedstock switching. The Houston Ship Channel corridor concentrates hydrogen pipeline delivery economics through Air Liquide and Linde industrial gas networks.
Germany
Ruhr Valley steelmakers under EU ETS Phase IV are contracting green hydrogen-derived direct reduced iron, pulling syngas reforming capacity toward low-carbon ammonia feedstock. ECHA REACH authorization requirements for nickel catalyst precursors are compressing procurement timelines for ammonia producers. The Leuna chemical complex qualifies iron-molybdenum catalyst suppliers ahead of 2026 authorization deadlines.
Saudi Arabia
NEOM's giga-scale renewable hydrogen clusters offer offtake anchoring for syngas-to-ammonia exporters seeking 15-20 year purchase agreements with sovereign credit backing. The kingdom's industrial development program channels capital toward integrated gas-to-chemicals complexes at Jubail and Yanbu. Red Sea shipping corridors position Saudi ammonia for European bunkering contracts under EU carbon intensity benchmarks.
India
Agricultural residue collection networks in Maharashtra and Punjab are achieving feedstock scale sufficient to sustain 100+ MW biomass-to-syngas units without fossil price linkage. Fertilizer demand from the Indo-Gangetic Plain sustains ammonia production volume, though coal price volatility erodes margin predictability at gasification complexes. The Hazira-Bharuch corridor in Gujarat concentrates petrochemical syngas demand from Reliance Industries' refining operations.
Global Syngas and Derivatives Market Competitive Landscape
On the supply side, the industry is consolidating around integrated technology licensors and industrial gas distributors with captive pipeline infrastructure. Three archetypes dominate: Fischer-Tropsch technology specialists with captive coal-to-liquids complexes, global industrial gas majors leveraging hydrogen delivery networks, and engineering contractors licensing gasification and reforming process packages. Capacity expansion and carbon capture retrofit partnerships constitute the primary competitive vectors as offtake contracts harden carbon intensity requirements.
Among South African and European integrated operators, Sasol Limited and Shell PLC occupy positions exemplifying Fischer-Tropsch synthesis and gas-to-liquids integration. Within the industrial gas distribution tier, Air Liquide S.A. anchors hydrogen pipeline economics at Rotterdam and US Gulf Coast clusters. Linde plc sits within the large-scale reforming and carbon capture retrofit segment, competing through steam methane reformer deployment.
| Leading Market Players |
|---|
| Sasol Limited |
| Air Liquide S.A. |
| Air Products and Chemicals Inc. |
| Linde plc |
| BASF SE |
| Shell PLC |
| KBR Inc. |
| Haldor Topsoe A/S |
| TechnipFMC PLC |
| Others |
Supply & Pricing Matrix
Coal price volatility at Indonesian and Australian thermal benchmarks determines both margin compression at coal-gasification complexes and the geographic redistribution of reforming capacity toward natural gas and biomass feedstocks. This commodity exposure fragments pricing power across feedstock tiers while forcing supply chain reconfiguration around pipeline-connected hydrogen clusters.
Pricing Analysis
Volume-discount tiering structures separate long-term offtake contracts for certified low-carbon hydrogen from spot-market ammonia transactions. Premium pricing attaches to EU CertifHy-validated and TÜV SÜD-certified grades serving steel decarbonization mandates, while standard-tier ammonia trades on fertilizer-demand fundamentals. Cost compression in the standard tier intensifies because Indonesian coal benchmarks swing unpredictably, eroding margin predictability. Fertilizer cooperatives in India and Brazil exhibit the highest price sensitivity, whereas European steelmakers under EU ETS Phase IV absorb premium hydrogen pricing without volume elasticity.
Supply Chain Analysis
Contract-manufacturing concentration for nickel and cobalt catalyst precursors sits with Russian and Chinese refiners, exposing European and North American reforming operators to export restriction risk. Syngas production draws from coal gasification complexes in China, steam methane reforming clusters along the US Gulf Coast, and biomass gasification pilots in India and Brazil. Feedstock dependencies center on thermal coal, natural gas, and agricultural residue collection networks. Single-source vulnerability in catalyst supply channels threatens operational continuity. Distribution runs through pipeline clusters at Rotterdam, the Houston Ship Channel, and Singapore trading hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The syngas and derivatives market represents an early-cycle expansion story anchored by steel decarbonization mandates pulling hydrogen demand into long-term contracting structures.
For Market Incumbents: Entrench pipeline-connected hydrogen delivery economics at Rotterdam and US Gulf Coast clusters to defend against electrolysis-based green hydrogen entrants. Secure backward integration into carbon capture retrofit partnerships before 45Q tax credit stacking windows narrow. Cement long-term ammonia offtake with South Korean and Dutch steelmakers to lock in volume visibility against bio-syngas competitors. For New Entrants and Emerging Players: Establish a beachhead in biomass gasification serving Indian and Brazilian agricultural residue networks where feedstock scale now sustains 100+ MW units without fossil price linkage. Target the chlorinated solvent recovery segment in Germany and Japan where plasma gasification yields above 85% from hazardous industrial residues. Lead with iron-molybdenum catalyst qualification to exploit REACH authorization compression ahead of ECHA sunset deadlines. For Investors and Strategic Acquirers: EU F-Gas Regulation tightening on fluorinated cooling gases reshapes the acquisition landscape toward membrane separation technology specialists at Rotterdam and Antwerp pipeline clusters. Five-to-ten-year viability favors integrated operators with captive Fischer-Tropsch synthesis or industrial gas distribution infrastructure. Monitor carbon intensity certification timeline compression at EU CertifHy as the inflection signal—validation cycles lagging behind offtake execution windows indicate due diligence bottlenecks that will consolidate procurement power among pre-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | 45Q tax credit stacking at Texas and Louisiana Gulf Coast facilities secures margin protection against coal volatility. |
| Biomass Gasification Scale-Up | Agricultural residue collection networks in Maharashtra and Punjab achieve feedstock independence from fossil benchmarks. |
| Long-Term Hydrogen Offtake Contracting | Rotterdam and Singapore trading hubs now standardize carbon intensity certification as a delivery condition. |
| Iron-Based Catalyst Qualification | Leuna chemical complex and European ammonia producers pivot ahead of ECHA nickel compound authorization deadlines. |
| Plasma Gasification Pilot Expansion | German and Japanese chemical manufacturers process chlorinated solvent recovery at 50 MW units with 85% syngas yields. |
Research Methodology
Desk research of customs and trade flow databases, SEC 10-K filings, and EIA energy statistics preceded structured interviews with plant managers at gasification and reforming facilities, procurement leads at downstream ammonia and methanol offtakers, EPC contractors specializing in carbon capture integration, and technical R&D directors at catalyst manufacturers. Primary intelligence combined with secondary validation from IEA hydrogen project databases and EU emissions trading registry data. Bottom-up capacity installation tracking triangulated against top-down demand modeling across chemical synthesis, fuel production, and metal refining applications.
Assumption sets held carbon capture retrofit cost curves and electrolyzer stack cost floors fixed at current technology readiness levels while varying feedstock price scenarios and regulatory enforcement timelines across jurisdictions. The analytical framework modeled product type, application, technology route, and end-user industry segments across the projection horizon. CAGRs derived from installation pipeline tracking and offtake contract execution velocity incorporated steel decarbonization mandate deadlines, EU carbon border adjustment implementation, and sovereign hydrogen cluster development programs as demand-pull inputs.
Macroeconomic conditions sit as an overlay; deviation in thermal coal benchmark volatility, sovereign credit availability for giga-scale renewable hydrogen projects, or catalyst precursor export restriction severity would shift the trajectory. Forecasts reflect documented assumptions regarding technology cost convergence and regulatory enforcement harmonization. Quarterly review of EU ETS allowance pricing, Indonesian coal futures, and EU CertifHy certification throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Helium Gas Market
Industrial Gases
Europe Syngas Market
Industrial Gases
North America Syngas Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Welding Gas Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Welding Shielding Gas Market