
 LAMEA Industrial Nitrogen Market | 2026-2036
LAMEA Industrial Nitrogen Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Industrial Nitrogen Market Insights
Aftermarket service revenue is fragmenting as on-site generation contracts displace traditional bulk supply arrangements across LAMEA industrial zones. Linde plc leverages its pipeline infrastructure in Jubail to sustain long-term offtake agreements with Saudi Aramco affiliates. Air Liquide S.A. anchors regional growth through cryogenic logistics investments in the UAE and South Africa. Gulf Cryo competes on localized cylinder distribution networks serving mid-sized Egyptian and Jordanian manufacturers.
Industrial nitrogen encompasses gaseous and liquid forms of N₂ produced via cryogenic air separation or pressure swing adsorption, typically delivered at purities exceeding 99.9% for inerting, blanketing, and process control applications. The gas serves primarily to prevent oxidation during metalworking, preserve food integrity through modified atmosphere packaging, and maintain sterile conditions in pharmaceutical synthesis. Liquid nitrogen commands premium margins in electronics and pharmaceutical end uses where ultra-low temperature requirements dominate specification sheets. Cryogenic delivery modes lead value pools in Gulf petrochemical corridors, while on-site generation captures share among large-volume African mining operators. Compressed nitrogen sustains steady demand across fragmented metalworking shops in Morocco and Tunisia.
Saudi Arabia's SFDA and the UAE's MOHAP enforce pharmaceutical-grade nitrogen purity standards that elevate barrier-to-entry for regional suppliers. South Africa's Department of Employment and Labour applies OSHA-aligned industrial gas handling regulations that shape workforce certification requirements. Brazil's ANVISA mandates specific inert gas parameters for active pharmaceutical ingredient manufacturing. Stakeholders must monitor how Gulf sovereign industrial strategies redirect nitrogen infrastructure investments toward hydrogen-ammonia integration projects.
Market Dynamics
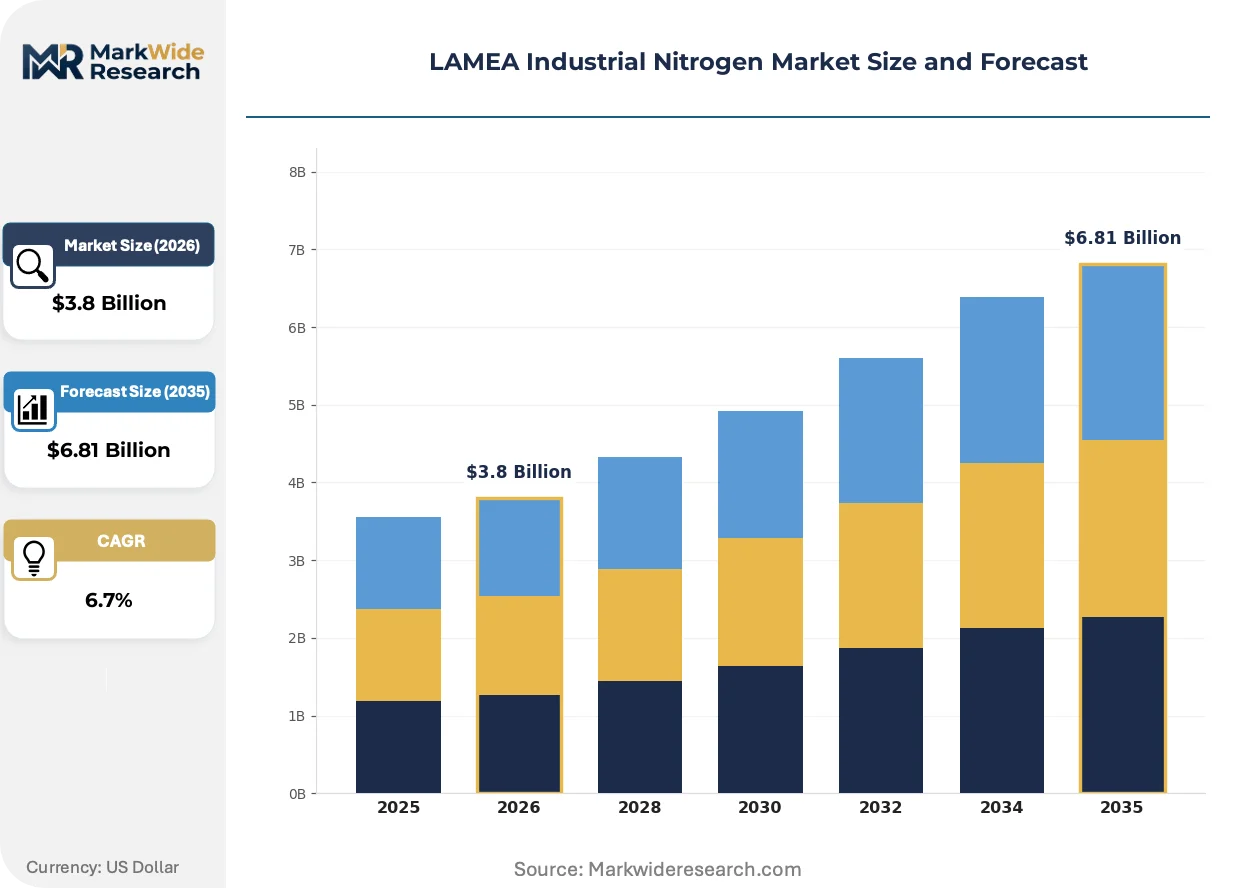
The LAMEA industrial nitrogen market is reconfiguring around on-site generation systems that displace bulk liquid delivery contracts across mining corridors and petrochemical clusters. This shift compresses traditional distributor margins while rewarding pipeline-integrated producers with long-term offtake security.
Growth Catalysts
- ANVISA pharmaceutical mandates:Brazil's regulator enforces inert gas specifications for active pharmaceutical ingredient synthesis, forcing domestic manufacturers to upgrade nitrogen purity infrastructure.
- Jubail Industrial City concentration:Saudi Arabia's integrated petrochemical complex generates sustained demand for cryogenic nitrogen in polyethylene and ammonia production trains.
- Pressure swing adsorption advances:Modular PSA units now achieve 99.9% purity at scales viable for mid-sized Egyptian food processors, expanding addressable manufacturing bases.
Market Restraints
- Grid electricity cost volatility:Cryogenic air separation consumes 0.4-0.6 kWh per cubic meter of nitrogen, exposing South African producers to Eskom tariff fluctuations and load-shedding disruptions.
- Jubail supply concentration:Three integrated producers control pipeline delivery infrastructure in Saudi Arabia's eastern province, limiting price competition for derivative chemical manufacturers.
- Liquid nitrogen substitution ceiling:Ultra-low temperature applications in UAE electronics fabrication cannot migrate to gaseous supply, locking in high logistics costs for cryogenic distribution.
Strategic Opportunities
- Moroccan phosphate expansion:OCP Group's fertilizer capacity additions at Jorf Lasfar create demand for nitrogen blanketing in phosphoric acid production and ammonium derivative synthesis.
- SFDA pharmaceutical-grade certification:Saudi Arabia's regulator is tightening purity documentation requirements, creating premium service tiers for certified nitrogen suppliers to Riyadh and Jeddah drug manufacturers.
- PSA-hybrid microgeneration:Combined membrane-PSA systems are virtualizing small-scale supply for Tunisian metalworking clusters previously dependent on cylinder exchange programs.
Industry Challenges
- Cryogenic logistics certification:UAE and Saudi transport operators face MOHAP and SFDA driver qualification requirements for pharmaceutical-grade liquid nitrogen haulage, constraining fleet expansion timelines.
- Legacy bulk contract restructuring:Brazilian fertilizer manufacturers locked into decade-long liquid supply agreements struggle to justify PSA capital expenditure despite favorable ten-year operating economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Industrial Nitrogen Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Liquid, Cryogenic, Compressed Application: Manufacturing, Food Preservation, Chemical Processing, Electronics Delivery Mode: Pipelines, Cylinders, Bulk Supply, On-Site Generation End User: Aerospace, Food & Beverage, Pharmaceuticals, Metalworking |
| Companies Covered | Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Gulf Cryo, Dubai Industrial Gases, SOL Group, Messer Group, Southern Industrial Gas, Ellenbarrie Industrial Gases Ltd, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Industrial Nitrogen Market Trends and Innovations
Digital monitoring systems and modular generation architectures are fragmenting traditional supply relationships across LAMEA industrial zones. Producers now compete on real-time purity verification and predictive maintenance integration rather than bulk volume commitments alone.
Membrane separation technology is virtualizing nitrogen supply for small-to-mid industrial users in Jordan and Tunisia who previously relied on cylinder distribution networks. Food packaging operations and electronics assemblers are adopting skid-mounted units at accelerating rates. This compression of minimum viable scale is eroding distributor margins in secondary North African cities.
South Africa's Department of Employment and Labour is enforcing OSHA-aligned industrial gas handling protocols that mandate recertification for cryogenic system operators. The regulation is compressing workforce availability for liquid nitrogen distribution while elevating training costs for Transnet-linked logistics contractors. Mining operators in the Platinum Belt are responding by accelerating automation of nitrogen injection systems for inertization.
Contract structures are unbundling equipment ownership from gas supply across Brazilian agricultural chemical manufacturing. OEMs now retain PSA asset title while selling nitrogen-by-the-cubic-meter to fertilizer blenders, transferring operational risk and maintenance burden. This model is concentrating in São Paulo state and Rio Grande do Sul processing corridors where ANVISA documentation requirements favor integrated service providers over commodity merchants.
LAMEA Industrial Nitrogen Market Segmentation
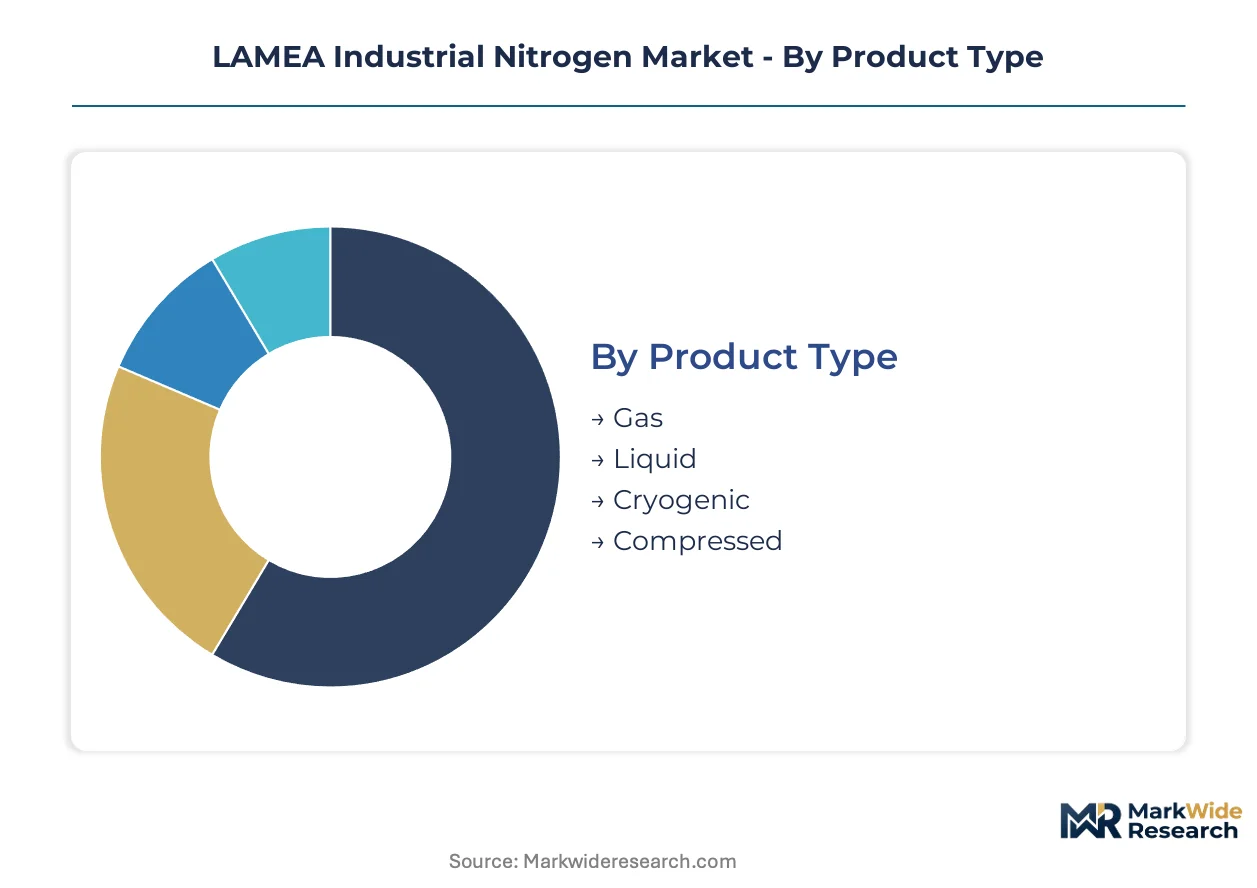
Industrial nitrogen supply chains fragment across physical states, delivery mechanisms, and purity specifications that dictate margin capture. Each segmentation axis reveals distinct competitive dynamics between pipeline-integrated producers and modular generation specialists.
Product Type:
Cycle times vary dramatically across physical states, with liquid nitrogen turning inventory weekly in pharmaceutical corridors while compressed gas cylinders rotate monthly in dispersed metalworking shops.
- Liquid:Cryogenic N₂ at -196°C serves ultra-low temperature applications in UAE electronics fabrication and Saudi pharmaceutical synthesis. Jubail petrochemical clusters anchor demand for bulk liquid offtake under long-term pipeline contracts.
- Gas:Gaseous nitrogen at 99.9-99.999% purity dominates metalworking inerting and food packaging blanketing. Brazilian fertilizer manufacturers drive expanding adoption for phosphoric acid production and ammonium derivative handling.
- Cryogenic:Ultra-cold liquid storage and vaporization systems support semiconductor manufacturing and biological sample preservation. South African mining operators leverage cryogenic nitrogen for underground inertization of volatile ore deposits.
- Compressed:High-pressure cylinder supply sustains fragmented demand from Tunisian and Moroccan metalworking shops lacking pipeline access. Cylinder exchange programs retain relevance where on-site generation economics fail to clear capital hurdles.
Gas anchors the volume base while liquid gains share at the steepest rate.
Application:
Cost tiers separate commodity blanketing from premium-grade pharmaceutical inerting, with purity documentation requirements driving price multiples.
- Chemical Processing:Ammonia synthesis and polyethylene production in Saudi Arabia's Jubail Industrial City consume nitrogen at massive scale for process control and safety inerting. Pipeline delivery integrates directly with derivative chemical manufacturing trains.
- Manufacturing:Metal fabrication, heat treatment, and laser cutting operations across South Africa's Platinum Belt require continuous gaseous nitrogen supply. Mining operators are accelerating PSA adoption to escape cylinder logistics costs.
- Food Preservation:Modified atmosphere packaging for Brazilian agricultural exports and UAE dairy processing demands food-grade nitrogen with documented purity chains. ANVISA and MOHAP specifications elevate barrier-to-entry for regional suppliers.
- Electronics:Semiconductor fabrication and flat-panel display manufacturing in UAE and Saudi Arabia require ultra-high purity nitrogen with sub-ppb contaminant thresholds. Cryogenic delivery locks in premium logistics costs given substitution impossibility.
Chemical processing anchors the volume base while electronics gains share at the steepest rate.
Delivery Mode:
Customer concentration determines channel economics, with integrated petrochemical complexes justifying pipeline capital while fragmented metalworking sustains cylinder networks.
- Pipelines:Dedicated pipeline infrastructure serves Saudi Aramco affiliates and SABIC derivatives producers in Jubail Industrial City with continuous high-volume supply. Three integrated producers control eastern province delivery, constraining price competition.
- On-Site Generation:Modular PSA and membrane systems displace bulk liquid contracts across Egyptian food processing and South African mining corridors. OEMs increasingly retain asset ownership while selling nitrogen-by-the-cubic-meter.
- Bulk Supply:Cryogenic tanker delivery sustains mid-scale manufacturers in Jordan and Tunisia lacking pipeline proximity. Liquid storage and vaporization systems bridge the gap between cylinder inefficiency and on-site generation capital requirements.
- Cylinders:High-pressure gas cylinders serve fragmented demand from small Tunisian metalworking shops and Moroccan fabrication units. Gulf Cryo competes on localized distribution density in secondary North African cities.
Pipelines anchor the volume base while on-site generation gains share at the steepest rate.
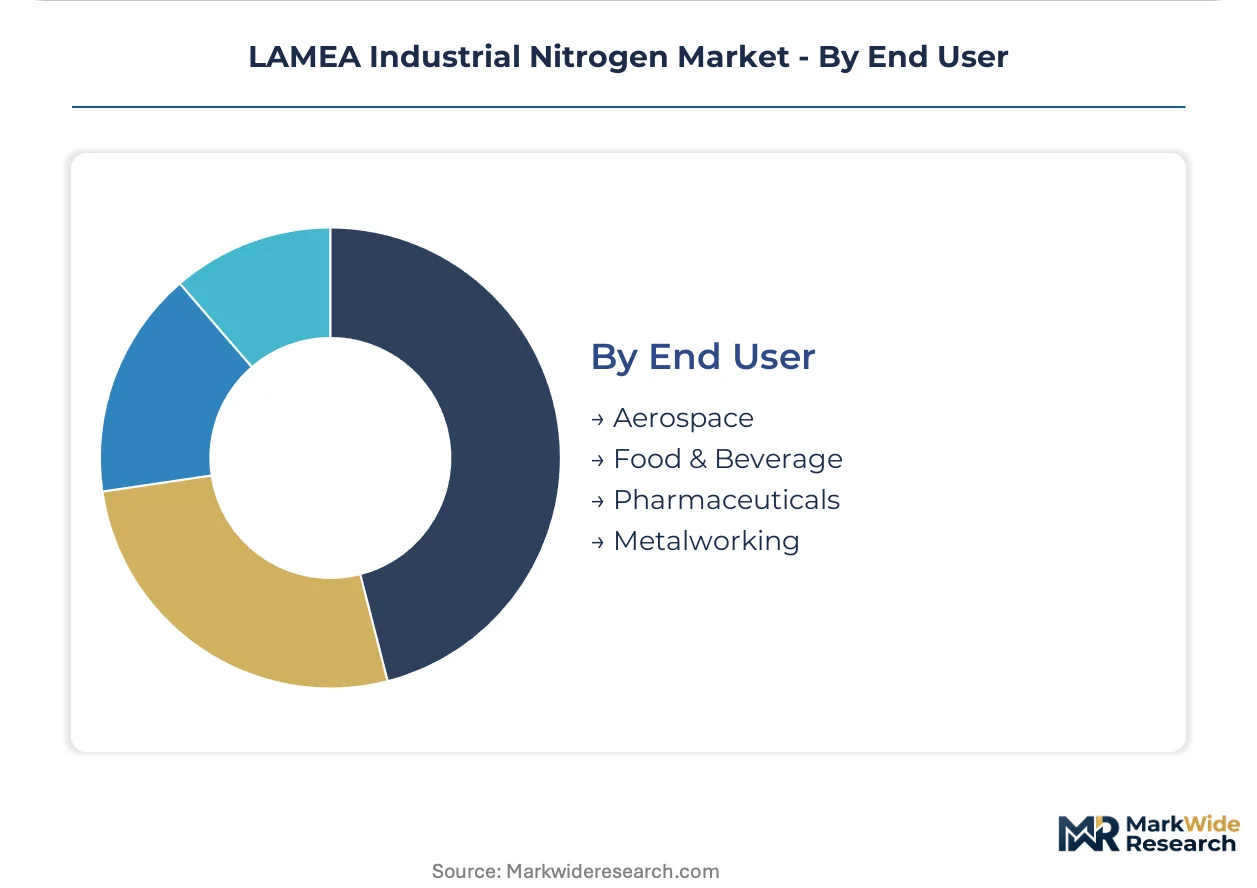
End User:
Maturity gradients separate established pharmaceutical specifications from emerging aerospace applications, with certification requirements shaping supplier selection.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and sterile packaging in Brazil, Saudi Arabia, and South Africa demand nitrogen with documented purity chains. ANVISA, SFDA, and OSHA-aligned regulations enforce specific inert gas parameters and workforce certification.
- Metalworking:Laser cutting, heat treatment, and inert atmosphere furnaces across South Africa's industrial corridors consume gaseous nitrogen at scale. Mining operators in the Platinum Belt deploy nitrogen injection for underground fire suppression.
- Food & Beverage:Modified atmosphere packaging, beverage dispensing, and controlled atmosphere storage support Brazilian agricultural export infrastructure. PSA-hybrid microgeneration is virtualizing supply for mid-sized processors.
- Aerospace:Fuel tank inerting, tire inflation, and composite manufacturing for defense and commercial aviation applications. Gulf sovereign industrial strategies are redirecting nitrogen infrastructure toward hydrogen-ammonia integration.
Metalworking anchors the volume base while pharmaceuticals gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and Brazil anchor the LAMEA consumption mix through divergent pathways—pipeline-integrated petrochemical corridors in the Gulf versus distributed agricultural chemical manufacturing across South American agricultural belts.
Saudi Arabia
Jubail Industrial City concentrates demand for cryogenic nitrogen in polyethylene and ammonia production trains. The SFDA enforces pharmaceutical-grade purity documentation requirements that elevate barrier-to-entry for Riyadh and Jeddah drug manufacturers. SABIC affiliates and Saudi Aramco derivatives producers sustain long-term offtake agreements through dedicated pipeline infrastructure in the Eastern Province.
Brazil
Fertilizer manufacturers in São Paulo state and Rio Grande do Sul drive expanding adoption as agricultural output intensifies. ANVISA mandates specific inert gas parameters for active pharmaceutical ingredient synthesis, forcing domestic manufacturers to upgrade nitrogen purity infrastructure. Phosphoric acid production and ammonium derivative handling at OCP Group's Jorf Lasfar-connected operations anchor regional demand.
South Africa
Mining operators in the Platinum Belt deploy nitrogen injection systems for underground inertization of volatile ore deposits. The Department of Employment and Labour applies OSHA-aligned industrial gas handling regulations that shape workforce certification requirements for Transnet-linked logistics contractors. Cryogenic logistics face compression from recertification mandates for liquid nitrogen haulage operators.
UAE
Electronics fabrication and flat-panel display manufacturing in Dubai and Abu Dhabi require ultra-high purity nitrogen with sub-ppb contaminant thresholds. MOHAP enforces pharmaceutical-grade nitrogen purity standards that constrain fleet expansion timelines for cryogenic transport operators. Semiconductor clusters sustain premium logistics costs given substitution impossibility for ultra-low temperature applications.
Egypt
Mid-sized food processors in Cairo and Alexandria adopt modular PSA units achieving 99.9% purity at newly viable scales. The country's national industrial gas regulator shapes safety protocols for cylinder distribution networks serving secondary manufacturing cities. Gulf Cryo competes on localized distribution density where on-site generation economics fail to clear capital hurdles.
LAMEA Industrial Nitrogen Market Competitive Landscape
Capability concentration sits with pipeline-integrated producers possessing cryogenic infrastructure; scale advantage sits with modular generation specialists deploying asset-light service models. The market structures around three tiers: Gulf-based pipeline operators with sovereign-linked offtake security, European multinationals leveraging cryogenic logistics investments, and regional cylinder distributors competing on localized network density. Dominant competitive moves include PSA-hybrid microgeneration partnerships and long-term equipment ownership retention with nitrogen-by-the-cubic-meter contracting.
Within the integrated infrastructure tier, Linde plc and Air Liquide S.A. exemplify archetypes of pipeline-anchored producers leveraging Jubail corridor concentration and UAE cryogenic logistics respectively. Gulf Cryo occupies a position representing regional cylinder distribution specialists competing on secondary city network penetration across Egyptian and Jordanian manufacturing bases.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide S.A. |
| Air Products and Chemicals, Inc. |
| Gulf Cryo |
| Dubai Industrial Gases |
| SOL Group |
| Messer Group |
| Southern Industrial Gas |
| Ellenbarrie Industrial Gases Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in South African cryogenic air separation plants drives aggressive contract renegotiation behavior from Eskom-exposed producers while simultaneously elevating spot market premiums for emergency nitrogen supply to Platinum Belt mining operators. This utilization squeeze compresses margin buffers for liquid nitrogen distributors and accelerates PSA adoption among price-sensitive mid-volume buyers.
Pricing Analysis
Long-term offtake agreements dominate the Jubail Industrial City corridor where SABIC affiliates lock in pipeline-integrated supply at volume-scaled rates, while spot and short-term contracts prevail in fragmented North African metalworking markets. Price differentiation rests on pharmaceutical-grade certification tiers under SFDA and ANVISA mandates versus industrial-grade commodity supply. Pricing pressure intensifies from modular PSA units achieving 99.9% purity at capital costs now viable for Egyptian food processors. Large-volume petrochemical buyers exhibit lowest price sensitivity given substitution impossibility, while Tunisian cylinder-dependent fabricators face acute cost compression.
Supply Chain Analysis
Tariff exposure between European cryogenic equipment suppliers and LAMEA project developers dominates supply chain risk planning for new air separation unit deployments. Geographic concentration centers on Saudi Arabia's Eastern Province pipeline infrastructure, South African industrial corridors around Johannesburg and Rustenburg, and Brazil's São Paulo-Rio Grande do Sul fertilizer belt. Raw material dependencies encompass specialized aluminum alloy cold boxes, molecular sieve adsorbents, and high-efficiency compression trains. Distribution runs through three integrated producers in Jubail, regional cylinder networks across North Africa, and emerging OEM-retained PSA asset ownership models in Brazilian agricultural chemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across delivery modes and purity tiers creates multiple entry points as on-site generation disrupts traditional bulk liquid contracts and pharmaceutical certification requirements elevate service complexity.
For Market Incumbents: Harden pipeline-integrated positions in Jubail through exclusive SABIC derivative supply arrangements while accelerating PSA-hybrid microgeneration partnerships to capture Brazilian fertilizer manufacturers escaping legacy bulk contracts. Cryogenic logistics certification investments under UAE MOHAP and Saudi SFDA protocols defend against regional cylinder distributors seeking upstream migration. For New Entrants and Emerging Players: Mid-sized Egyptian food processors and Jordanian electronics assemblers represent the most penetrable entry point for membrane-PSA combined systems at scales below incumbent bulk supply minimums. Target ANVISA documentation services as a differentiated go-to-market wrapper around commodity nitrogen delivery to Brazilian pharmaceutical API manufacturers. For Investors and Strategic Acquirers: Long-term, this sits as a utility-like infrastructure play because nitrogen demand tracks industrial GDP with contractual visibility through pipeline offtake security and equipment-retained service models. Acquisition focus should center on regional cylinder distributors with dense North African network coverage and established pharmaceutical customer relationships. The signal to watch is Gulf sovereign industrial strategy announcements redirecting nitrogen infrastructure toward hydrogen-ammonia integration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| PSA-Hybrid Microgeneration Deployment | Captures Egyptian and Tunisian mid-volume manufacturers below pipeline economic thresholds. |
| Pharmaceutical-Grade Certification Investment | Unlocks premium service tiers under SFDA and ANVISA documentation mandates. |
| Pipeline Infrastructure Expansion | Secures long-term offtake with SABIC affiliates in Jubail Industrial City corridors. |
| Cryogenic Logistics Fleet Automation | Reduces workforce recertification burdens under South African OSHA-aligned protocols. |
| Equipment-Retained Service Contracting | Transfers operational risk to OEMs while capturing Brazilian fertilizer blender volume. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at Jubail petrochemical complexes, procurement leads at Brazilian fertilizer manufacturers, distribution channel partners across North Africa, and aftermarket service heads at South African mining operators. Secondary validation drew from customs and trade data, SEC filings of listed industrial gas majors, national regulator safety protocol documentation, and project development databases for air separation unit deployments. Bottom-up volume modeling triangulated against top-down GDP-industrial output correlations.
Calibration against historical capacity utilization rates and documented contract restructuring events anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass physical state, delivery mode, purity specification tier, and end-use industry vertical. CAGRs were derived from elasticity-adjusted demand curves incorporating PSA substitution rates and pharmaceutical regulatory expansion timelines.
Practitioners should monitor Gulf sovereign hydrogen-ammonia integration announcements, Eskom tariff restructuring outcomes, and ANVISA certification requirement expansions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
3D Printing Gases Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Gas Processing Market