
 South-East Asia (SEA) Syngas Market | 2026-2036
South-East Asia (SEA) Syngas Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia (SEA) Syngas Market Analytics
Long-term maintenance and catalyst replacement contracts are rebalancing how syngas technology vendors capture value across South-East Asia. Air Liquide leverages its regional industrial gas infrastructure to bundle syngas plant servicing with hydrogen supply agreements. Linde plc anchors large-scale gasification projects through engineering partnerships with Indonesian state energy enterprises. Siemens Energy differentiates via power-island integration, combining syngas turbines with carbon capture readiness in Malaysian proposals.
Syngas is a fuel gas mixture comprising primarily hydrogen and carbon monoxide, produced through partial oxidation or steam reforming of carbonaceous feedstocks such as coal, biomass, or natural gas at temperatures typically exceeding 1,200°C; its industrial purpose centers on serving as an intermediate feedstock for ammonia, methanol, and synthetic fuel synthesis. Gasification technology dominates installed capacity across the region given abundant low-rank coal reserves in Indonesia and Vietnam, though reforming routes gain traction where natural gas pipeline networks exist. Hydrogen output from syngas plants represents the fastest-expanding product segment as regional ammonia and refinery hydrogen demand intensifies, while synthetic natural gas remains comparatively nascent due to infrastructure gaps and cost barriers.
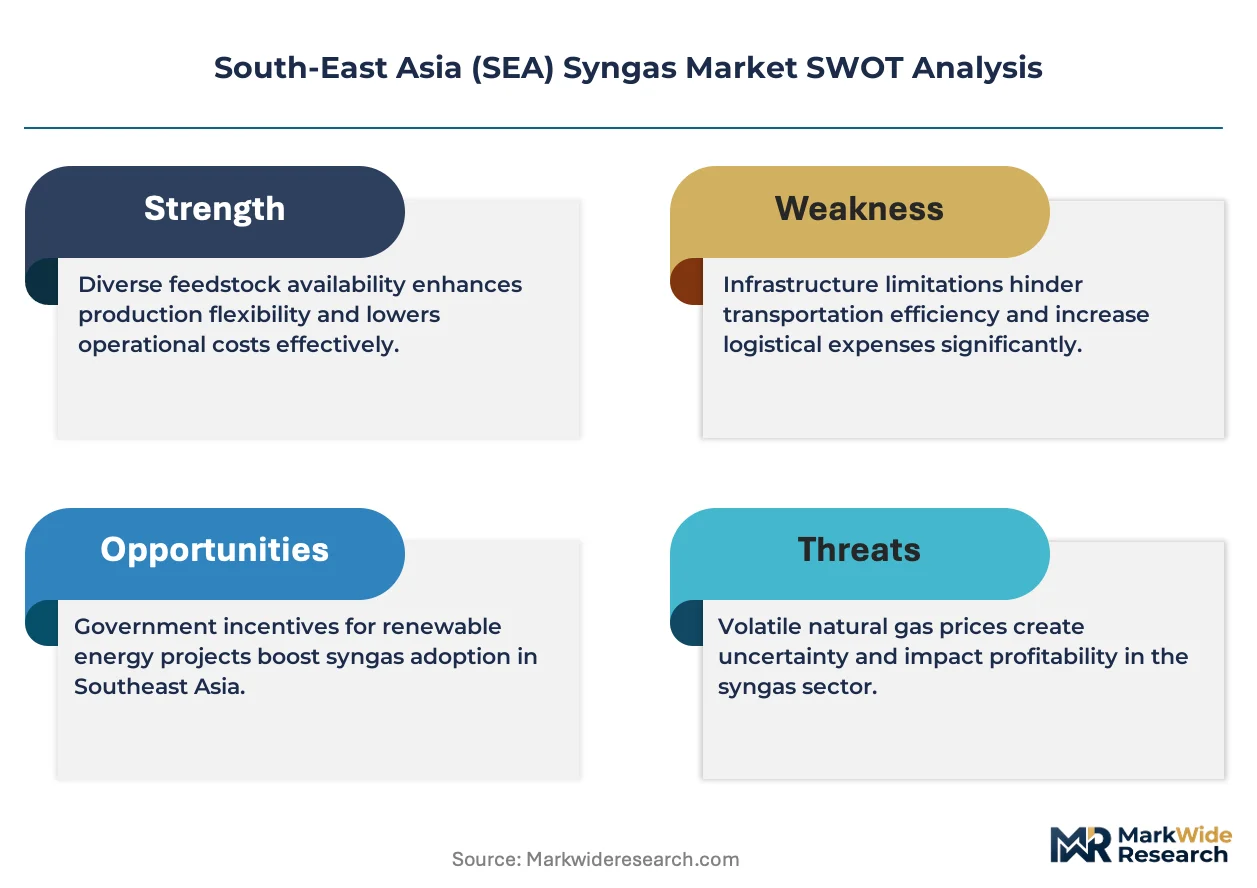
Indonesia's Ministry of Energy and Mineral Resources enforces domestic coal gasification quotas that directly shape syngas project economics and feedstock allocation priorities. Malaysia's Department of Environment applies emissions intensity thresholds under the Environmental Quality Act that influence gasification plant design standards and carbon management investments. Thailand's Board of Investment extends tax incentives for clean energy transitions that encompass biomass-to-syngas pathways, altering investor site selection across the Mekong sub-region. Stakeholders must weigh feedstock cost trajectories against evolving national decarbonization commitments when committing capital to multi-decade gasification assets.
Market Dynamics
Indonesia's domestic coal gasification mandates under MEMR Regulation No. 7 of 2022 are redirecting capital flows toward integrated syngas complexes, compressing project development timelines and reshaping feedstock procurement patterns across the region's chemical value chains.
Growth Catalysts
- Domestic Coal Gasification Mandates:MEMR Regulation No. 7 of 2022 requires coal producers to allocate portions of output to gasification, guaranteeing feedstock supply security for ammonia and methanol producers in East Kalimantan.
- Ammonia Sector Expansion:Fertilizer producers across Indonesia, Malaysia, and Vietnam are scaling syngas offtake as coal-to-chemical complexes reach commercial operation, anchoring regional hydrogen demand growth.
- Carbon Capture Readiness:Engineering standards for new gasification plants now incorporate carbon capture integration, positioning syngas-derived hydrogen for future low-carbon ammonia export markets.
Market Restraints
- Low-Rank Coal Quality Variability:Indonesian sub-bituminous coal exhibits high moisture and ash content, requiring pre-treatment investments that elevate project capex by 15-25% versus higher-grade alternatives.
- Specialized Equipment Supply Concentration:Gasification reactor vessels and syngas coolers rely on fabrication capabilities concentrated in China, South Korea, and Germany, exposing projects to extended lead times.
- Natural Gas Price Arbitrage:Where pipeline infrastructure exists in Malaysia and Thailand, steam methane reforming competes on variable cost, compressing gasification margins during LNG price troughs.
Strategic Opportunities
- Biomass-to-Syngas Pathways:Thailand's Board of Investment tax incentives for clean energy transitions encompass agricultural residue gasification, creating first-mover advantages in Mekong sub-region site selection.
- Refinery Hydrogen Integration:Pertamina's downstream facilities present captive demand for syngas-derived hydrogen, enabling integrated production-consumption models that bypass merchant market price exposure.
- Modular Small-Scale Gasification:Containerized biomass gasification units below 50 MW thermal are penetrating remote industrial clusters in Vietnam's Central Highlands, accessing stranded feedstock reserves.
Industry Challenges
- Gasification Operator Skill Scarcity:Slagging, fouling, and syngas composition control require specialized expertise concentrated among retired engineers from Sasol and Lurgi legacy projects, constraining talent pipelines.
- Multi-Decade Asset-Policy Misalignment:Gasification plants operate on 25-30 year horizons, yet Indonesia's domestic coal gasification quotas and carbon pricing trajectories remain subject to electoral cycle revisions.
- Legacy Amine System Integration:Existing carbon capture installations at regional ammonia plants utilize MEA-based absorption requiring high energy input, complicating retrofits for emerging low-carbon hydrogen certification schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia (SEA) Syngas Market |
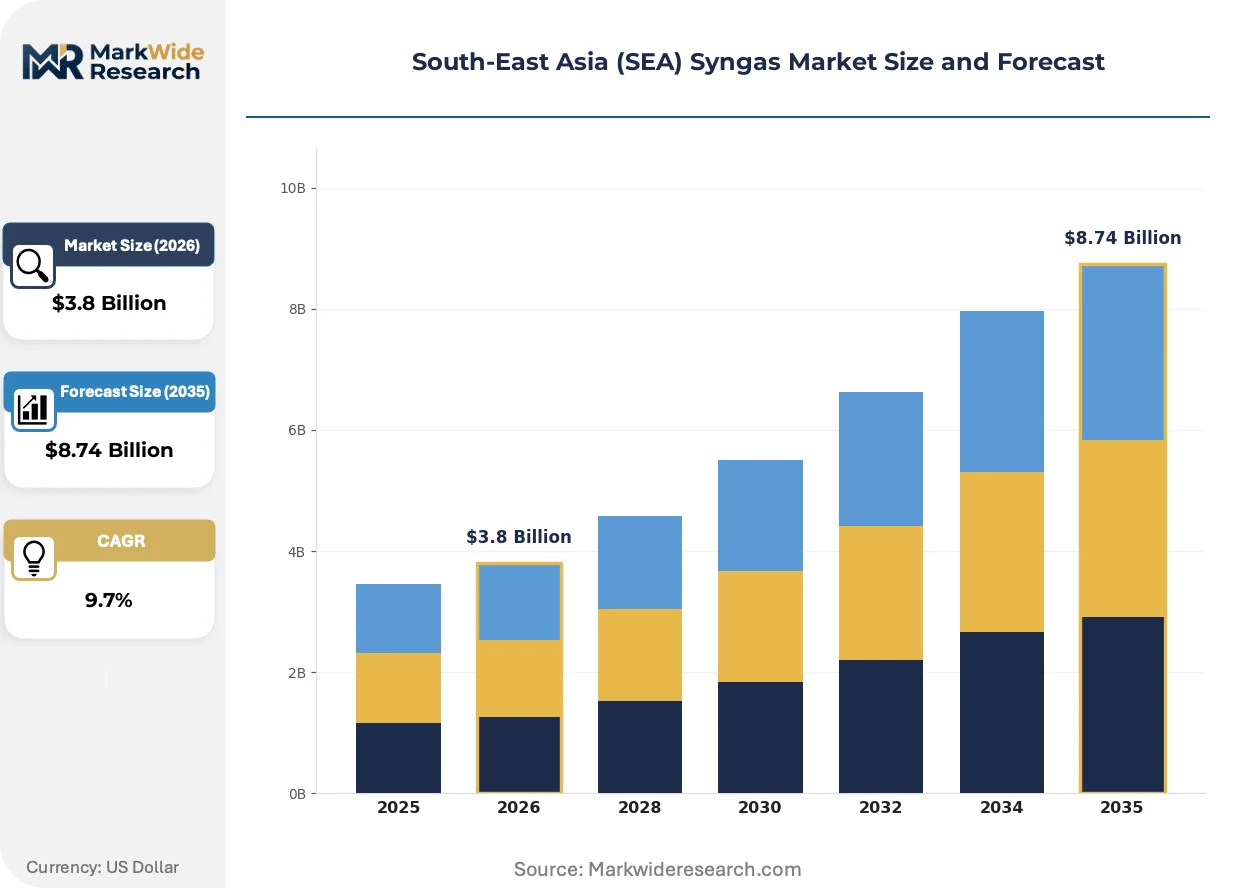
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen, Carbon Monoxide, Methanol, Synthetic Natural Gas Technology: Gasification, Reforming, Pyrolysis, Anaerobic Digestion Application: Chemical Manufacturing, Fertilizer Production, Power Generation, Fuel Cells End User: Energy Sector, Chemical Industry, Agriculture, Transportation |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Inc., Siemens Energy, Mitsubishi Heavy Industries, PT Pertamina (Persero), Shell Global Solutions International B.V., Haldor Topsoe A/S, General Electric, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia (SEA) Syngas Market Evolving Landscape
Modular reactor architectures and digital twin deployment are compressing commissioning timelines while enabling remote operational optimization across dispersed syngas facilities. These shifts intersect with evolving certification requirements and buyer procurement preferences.
Biomass entrained-flow gasification is decentralizing syngas production geography across South-East Asia. This technology converts agricultural residues into hydrogen-rich syngas at 1,400°C operating temperatures. Food processors and palm oil mill operators in Malaysia and Indonesia are piloting 10-30 MW units to displace diesel-fired captive power. Distributed generation models are emerging that bypass centralized coal supply chains and grid connection dependencies.
Malaysia's Department of Environment emissions intensity thresholds under the Environmental Quality Act are mandating carbon management investments in new gasification proposals. The regulation imposes CO2 per-ton-ammonia caps that effectively require partial carbon capture or biomass co-feeding. Greenfield projects in Sarawak and Sabah are responding with pre-investment in solvent absorption systems, while brownfield facilities face retrofit compliance timelines.
Refinery hydrogen buyers are consolidating procurement through long-term offtake agreements that bundle syngas plant output with carbon intensity guarantees. This contractual evolution displaces spot market transactions and spot-indexed pricing that dominated historical ammonia and methanol feedstock sourcing. Indonesian state energy enterprises are most visibly adopting this structure, using 15-20 year hydrogen supply contracts to underpin project finance for integrated gasification complexes.
South-East Asia (SEA) Syngas Market Segmentation
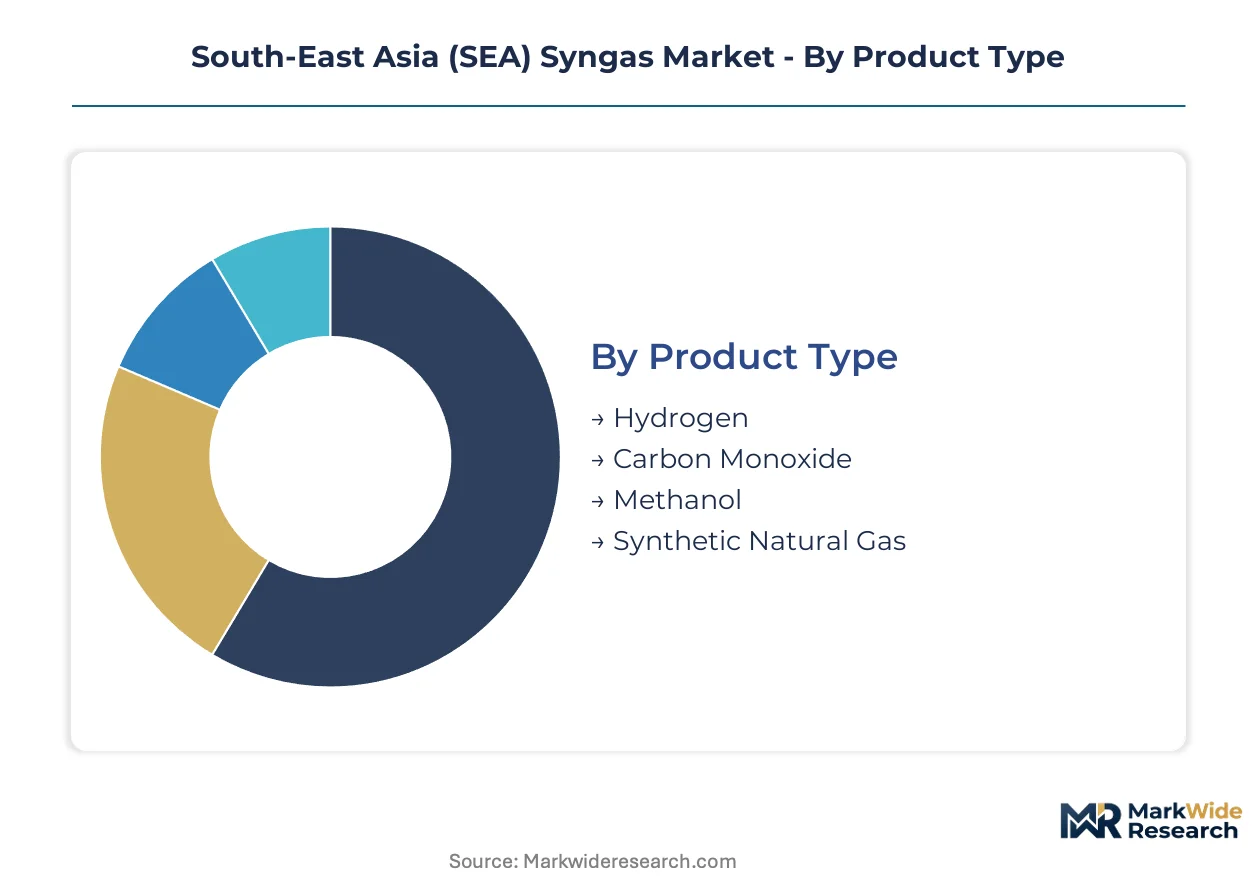
Syngas market segmentation in South-East Asia reveals divergent buyer priorities across product chemistry, conversion technology, and downstream integration depth. Understanding these splits enables vendors to align engineering configurations with specific offtake economics in Indonesia, Malaysia, and Vietnam.
Product Type:
Buyers in this category differentiate by hydrogen purity requirements and carbon intensity specifications for downstream chemical synthesis.
- Hydrogen:High-purity output from coal gasification serves ammonia and refinery desulfurization processes across East Kalimantan and Riau. Demand concentrates with Pertamina's downstream facilities and state fertilizer producers seeking captive hydrogen supply under domestic coal gasification mandates.
- Carbon Monoxide:Syngas-derived CO feeds methanol and acetic acid production, with specifications varying by catalyst sensitivity in Malaysian chemical parks. Steelmakers in Vietnam explore CO-rich syngas for direct reduction iron trials.
- Methanol:Merchant methanol offtake from integrated gasification complexes supplies formaldehyde and MTBE producers. Indonesian coal-to-methanol projects target domestic chemical value chain extension.
- Synthetic Natural Gas:Methanation of syngas into pipeline-grade methane remains nascent due to cost premiums versus conventional natural gas in Thailand and Malaysia.
Volume sits with Hydrogen; growth tilts toward Synthetic Natural Gas as low-carbon certification schemes mature.
Technology:
Technology selection tracks feedstock availability and scale economics, with coal-rich geographies favoring high-temperature conversion routes.
- Gasification:Entrained-flow and fluidized-bed reactors dominate Indonesian projects processing sub-bituminous coal at 1,400°C. East Kalimantan facilities deploy Shell and Siemens gasification technology for ammonia-urea integration.
- Reforming:Steam methane reforming competes in Malaysia's Peninsular gas corridor where pipeline infrastructure exists. Petronas-linked chemical sites favor reforming for lower capital intensity and faster commissioning.
- Pyrolysis:Biomass pyrolysis-to-syngas pilots operate in Thailand's agricultural processing clusters, converting rice husks and palm empty fruit bunches.
- Anaerobic Digestion:Biogas upgrading to syngas quality specifications serves small-scale rural power in Vietnam's Mekong Delta.
Gasification commands installed capacity; pyrolysis is expanding most quickly on Thailand's clean energy incentives.
Application:
Application splits reflect divergent margin structures and carbon accounting requirements across industrial offtakers.
- Chemical Manufacturing:Methanol, ammonia, and synthetic fuel production absorb the majority of regional syngas output. Indonesian coal-to-chemical complexes anchor demand with integrated product slate optimization.
- Fertilizer Production:Urea and ammonium phosphate facilities in Vietnam and Indonesia require consistent hydrogen-to-nitrogen ratios for Haber-Bosch efficiency. State procurement policies guarantee offtake volumes.
- Power Generation:Integrated gasification combined cycle plants in Malaysia demonstrate baseload flexibility, though deployment lags chemical applications.
- Fuel Cells:High-purity hydrogen for stationary and mobility fuel cells represents emerging demand in Singapore and Bangkok industrial zones.
Chemical Manufacturing holds revenue concentration; fuel cells show steepest expansion trajectory on hydrogen mobility pilots.
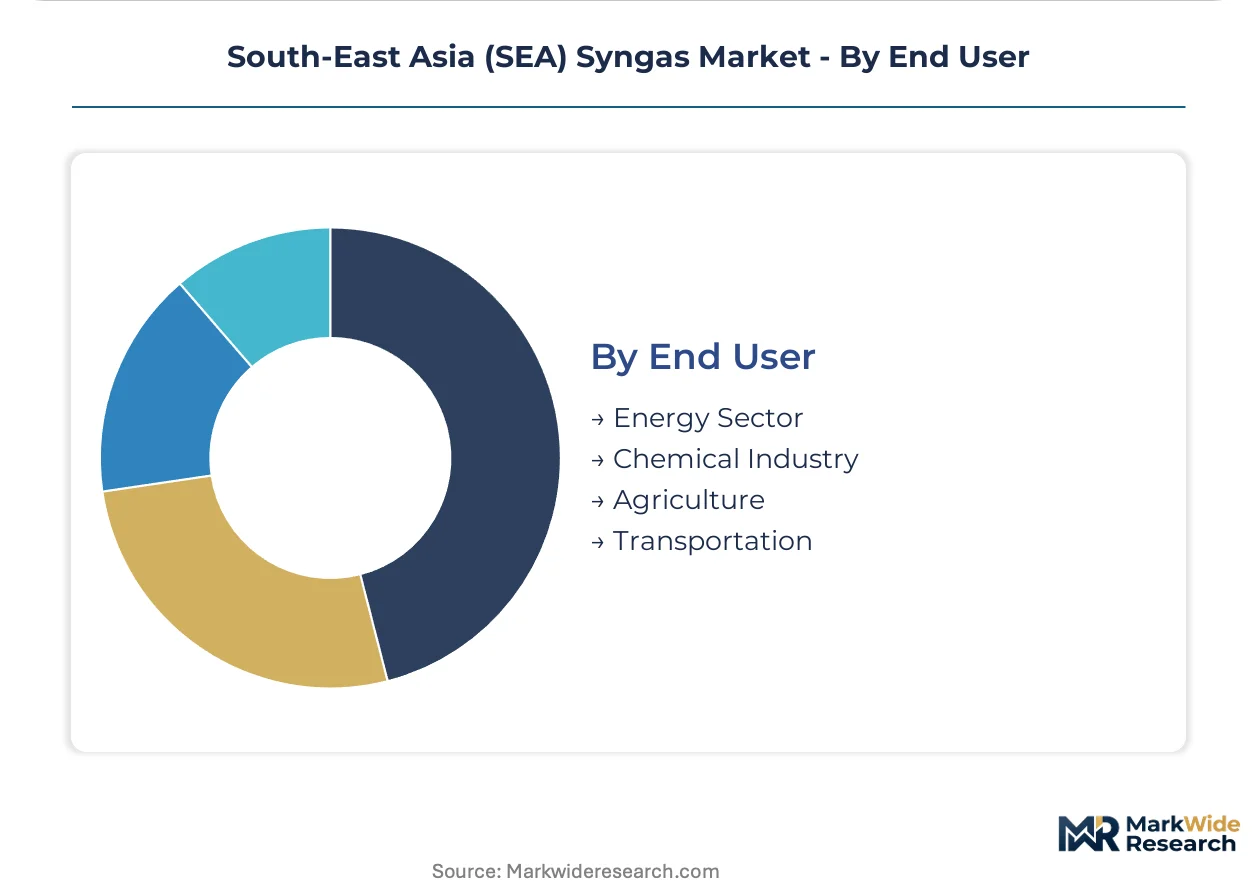
End User:
End user segmentation maps to national industrial policy priorities and state enterprise procurement patterns.
- Energy Sector:State oil and gas companies—Pertamina, Petronas, PetroVietnam—drive integrated gasification investments for refinery hydrogen and power generation diversification.
- Chemical Industry:Methanol and ammonia producers in Malaysia's Kertih and Indonesia's Bontang clusters specify syngas composition for catalyst protection and yield optimization.
- Agriculture:Fertilizer cooperatives and plantation conglomerates in Sumatra and Peninsular Malaysia secure long-term syngas-derived urea supply through state allocation mechanisms.
- Transportation:Shipping and aviation offtakers explore synthetic fuel pathways, with Singapore positioning as regional bunkering hub for ammonia and methanol marine fuels.
Energy Sector dominates capital deployment; Transportation is gaining share fastest on maritime decarbonization regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia produces syngas feedstock at scale while Malaysia and Thailand concentrate conversion capacity and downstream chemical demand. This production-consumption divide shapes capital flows and technology transfer patterns across the region.
Indonesia
East Kalimantan hosts the densest concentration of coal gasification investments, with Pertamina and partners developing integrated facilities for ammonia and methanol output. MEMR Regulation No. 7 of 2022 mandates domestic coal allocation to gasification, securing feedstock supply for state chemical enterprises. Bontang industrial clusters anchor urea and synthetic fuel pilot projects.
Malaysia
Petronas-linked chemical sites in Kertih drive hydrogen demand for refinery desulfurization and ammonia synthesis. The Department of Environment applies CO2 per-ton-ammonia caps under the Environmental Quality Act, forcing carbon capture pre-investment. Sarawak and Sabah greenfield projects incorporate solvent absorption systems to meet emissions thresholds.
Vietnam
Steelmakers in the Northern Key Economic Zone trial CO-rich syngas for direct reduction iron processes, diversifying from blast furnace routes. State fertilizer producers expand ammonia capacity using coal gasification technology licensed from European engineering groups. The Central Highlands deploy modular biomass gasification units below 50 MW thermal for remote industrial clusters.
Thailand
Agricultural processing clusters in the Central Plains and Eastern Economic Corridor pilot rice husk and palm empty fruit bunch gasification. The Board of Investment extends tax incentives for clean energy transitions encompassing biomass-to-syngas pathways, altering investor site selection. Food processors displace diesel-fired captive power with distributed syngas generation models.
Singapore
Jurong Island refineries and chemical parks position as hydrogen offtake hubs for regional syngas-derived supply. Maritime decarbonization regulations drive ammonia and methanol bunkering pilot programs, creating demand pull for low-carbon synthetic fuels. Trading houses consolidate long-term offtake agreements with carbon intensity guarantees from Indonesian production assets.
South-East Asia (SEA) Syngas Market Competitive Landscape
Top-tier vendors anchor integrated gasification complexes, while mid-tier engineering specialists capture maintenance and catalyst replacement contracts. The market structures around three player categories: industrial gas conglomerates bundling syngas plant servicing with hydrogen supply, state energy enterprises directing domestic coal gasification mandates, and technology licensors providing reactor designs and process guarantees. Competitive moves concentrate on engineering partnerships with Indonesian state enterprises and carbon capture readiness integration in Malaysian proposals.
Among European industrial gas leaders, Air Liquide and Linde plc exemplify the bundled-service archetype, leveraging regional infrastructure to combine plant operation with hydrogen delivery. Siemens Energy occupies a position on the power-island integration vector, pairing gasification turbines with capture-ready designs. Within the state enterprise tier, PT Pertamina anchors Indonesian downstream integration, capturing captive demand from refinery hydrogen requirements. Mitsubishi Heavy Industries and Shell Global Solutions represent the technology-licensor archetype, supplying entrained-flow reactor designs for high-ash coal processing.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals, Inc. |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| PT Pertamina (Persero) |
| Shell Global Solutions International B.V. |
| Haldor Topsoe A/S |
| General Electric |
| Others |
Value Network & Pricing Analysis
Gasification operator skill scarcity in East Kalimantan and Riau compresses labor-cost differentials into pricing-tier spreads, with specialized slagging and fouling expertise commanding premiums that separate integrated service contracts from equipment-only supply.
Pricing Analysis
Margin tightening in standard-tier gasification equipment traces to pre-treatment capex inflation for high-moisture Indonesian sub-bituminous coal. Three-tier pricing structure across premium, standard, and economy levels differentiates by carbon capture readiness certification and after-sales service bundling. Cost-down pressure on economy-tier units accelerates because modular biomass gasification pilots in Vietnam and Thailand bypass centralized coal procurement. State fertilizer producers in Indonesia show lowest price sensitivity given captive offtake guarantees under MEMR Regulation No. 7 of 2022, while remote industrial clusters in Vietnam's Central Highlands prioritize capital efficiency over performance specifications.
Supply Chain Analysis
Direct-to-state-enterprise channels anchor large-scale project procurement, with Pertamina and Petronas-linked entities consolidating hydrogen offtake through 15-20 year supply agreements. Fabrication of gasification reactor vessels and syngas coolers concentrates in China, South Korea, and Germany, creating extended lead time exposure for Indonesian and Malaysian project timelines. Raw material dependencies span high-chrome steel alloys for reactor linings, specialized ceramic refractories, and proprietary catalyst formulations from Haldor Topsoe and Shell Global Solutions. Single-source vulnerability in entrained-flow reactor technology licensing feeds from concentrated engineering expertise at Mitsubishi Heavy Industries and Siemens Energy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with gasification operator skill scarcity propping pricing power for bundled maintenance and catalyst replacement contracts across Indonesian state chemical enterprises.
For Market Incumbents: Cement feedstock supply security through backward integration into coal pre-treatment facilities in East Kalimantan, countering quality variability penalties that inflate project capex by 15-25%. Deepen engineering partnerships with Pertamina to capture captive refinery hydrogen demand, insulating revenue streams from merchant market price exposure during LNG price troughs in Malaysia's Peninsular gas corridor. For New Entrants and Emerging Players: Thailand's Board of Investment tax incentives for clean energy transitions open a window for agricultural residue gasification specialists to establish first-mover positions in Mekong sub-region site selection. Target modular sub-50 MW biomass units for Vietnam's Central Highlands and Thailand's Eastern Economic Corridor, leveraging distributed generation models that bypass grid connection dependencies and centralized coal supply chains. For Investors and Strategic Acquirers: Re-rating potential sits with technology licensors possessing entrained-flow reactor designs for high-ash coal processing, given Indonesia's domestic gasification mandates and carbon capture readiness requirements in Malaysia. Monitor carbon intensity certification scheme maturation as inflection indicator for synthetic natural gas segment viability and low-carbon ammonia export market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal Pre-treatment | Captures margin erosion from high-moisture Indonesian sub-bituminous coal quality variability. |
| Carbon Capture Readiness Certification | Positions syngas-derived hydrogen for Malaysia's Department of Environment CO2 per-ton-ammonia caps compliance. |
| Long-term Hydrogen Supply Agreements | Underpins project finance for Indonesian integrated gasification complexes through Pertamina captive offtake. |
| Modular Biomass Gasification Deployment | Accesses Thailand's clean energy tax incentives and Vietnam's stranded agricultural residue feedstocks. |
| Engineering Partnership with State Enterprises | Secures preferred vendor status for MEMR Regulation No. 7 of 2022-mandated domestic coal gasification quotas. |
Research Methodology
Document review covered engineering procurement databases, customs trade records for gasification equipment imports, and MEMR regulatory filings, complemented by interviews with plant managers at Indonesian coal-to-chemical complexes, procurement leads at Malaysian refinery hydrogen buyers, and EPC contractors specializing in entrained-flow reactor installation. Secondary validation drew from IEA energy transition reports, ASEAN energy statistics, and technology licensor patent disclosures. Bottom-up capacity buildout estimates triangulated against top-down chemical demand projections.
Installed capacity and revenue outputs trace to a segmented analytical framework spanning product chemistry, conversion technology, and downstream integration depth across the projection horizon. CAGRs derive from feedstock cost trajectory modeling, regulatory enforcement probability assessments, and offtake contract tenor analysis. Key inputs include Indonesian domestic coal gasification quota compliance rates, Malaysian emissions intensity threshold evolution, and modular biomass gasification unit deployment pace in Thailand.
Caveats apply where Indonesian electoral cycle revisions to MEMR Regulation No. 7 of 2022, Malaysian carbon pricing trajectory shifts, or breakthroughs in steam methane reforming cost competitiveness could materially shift the outlook. Practitioners should monitor carbon capture retrofit compliance timelines at legacy ammonia plants and biomass feedstock cost inflation in Thailand's Central Plains for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Gas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Oxygen Market
Industrial Gases
Noble Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Global Liquid Nitrogen Market