
 Transcritical CO2 Market | 2026-2036
Transcritical CO2 Market Size, Share, and Industry Trends Forecast 2026-2036
Transcritical CO2 Market Intelligence
The OEM-direct channel for transcritical CO2 systems is narrowing as European supermarket chains consolidate procurement through framework agreements with specialized integrators. Danfoss leverages its compressor and valve portfolio to anchor long-term supply relationships with retrofit-focused contractors. Advansor competes through packaged rack systems designed for quick deployment in existing store footprints. Mayekawa sustains its position in industrial-scale installations through custom-engineered heat pump configurations for food processing plants.
Transcritical CO2 refers to refrigeration and heat pump cycles where carbon dioxide operates above its critical point of 31.1°C and 73.8 bar, enabling high-temperature heat rejection without condensation while maintaining favorable thermodynamic efficiency across ambient conditions. The technology serves commercial and industrial cooling applications where phase-out of hydrofluorocarbon refrigerants creates urgent equipment replacement needs. Heat exchangers command the largest technology segment due to their role in gas cooler performance optimization under variable ambient temperatures. Compressors represent the fastest-expanding technology category as manufacturers develop larger-displacement units for multi-megawatt industrial cooling loads. Food retail anchors end-user demand, though beverage industry adoption is accelerating where process cooling requirements align with CO2's temperature glide characteristics.
The EU F-Gas Regulation and Ecodesign directives mandate refrigerant phase-downs that directly compel supermarket operators toward transcritical CO2 adoption before service bans tighten. REACH compliance requirements for materials compatibility shape component supplier qualification processes across the European supply base. EPA SNAP rules in the United States restrict certain HFC alternatives, creating parallel regulatory momentum for CO2 systems in North American commercial refrigeration. Stakeholders must monitor how national building codes evolve to address CO2 charge limits and ventilation requirements in enclosed retail spaces.
Market Dynamics
The EU F-Gas Regulation's accelerated phase-down schedule is compressing replacement cycles for commercial refrigeration equipment, forcing supermarket operators to commit to transcritical CO2 systems before HFC service bans take full effect. This regulatory pressure is reshaping capital allocation across European food retail chains.
Growth Catalysts
- F-Gas Regulation mandates:The EU's refrigerant phase-down creates binding compliance deadlines that eliminate HFC alternatives for new installations and retrofits.
- Heat pump integration:Industrial food processors are deploying transcritical CO2 for combined cooling and heating, capturing waste heat for sanitation and space conditioning.
- Norwegian cluster density:Regulatory precedents and installer expertise in Oslo and Bergen are creating demonstration effects for neighboring Nordic markets.
Market Restraints
- Steel and aluminum volatility:Heat exchanger fabrication depends on commodity metals whose price swings compress OEM margins on fixed-price contracts.
- Specialized compressor supply:Large-displacement CO2 compressor production concentrates among German and Japanese suppliers, creating single-source vulnerabilities.
- Charge limit constraints:National building codes in enclosed retail spaces cap CO2 system sizes, fragmenting equipment specifications across jurisdictions.
Strategic Opportunities
- Italian retrofit backlog:Southern European supermarket chains remain underpenetrated relative to Nordic peers, creating whitespace for integrator expansion.
- Beverage process cooling:Breweries and soft-drink bottlers are adopting transcritical CO2 for pasteurization and bottle washing where temperature glide aligns with process needs.
- Digital twin integration:Predictive maintenance platforms are converging with refrigeration controls, enabling performance-based service contracts.
Industry Challenges
- CO2 technician certification:The installed base of HFC-trained service engineers requires reskilling on high-pressure systems and safety protocols.
- Legacy control integration:Existing building management systems in older stores lack native compatibility with transcritical cycle controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcritical CO2 Market |
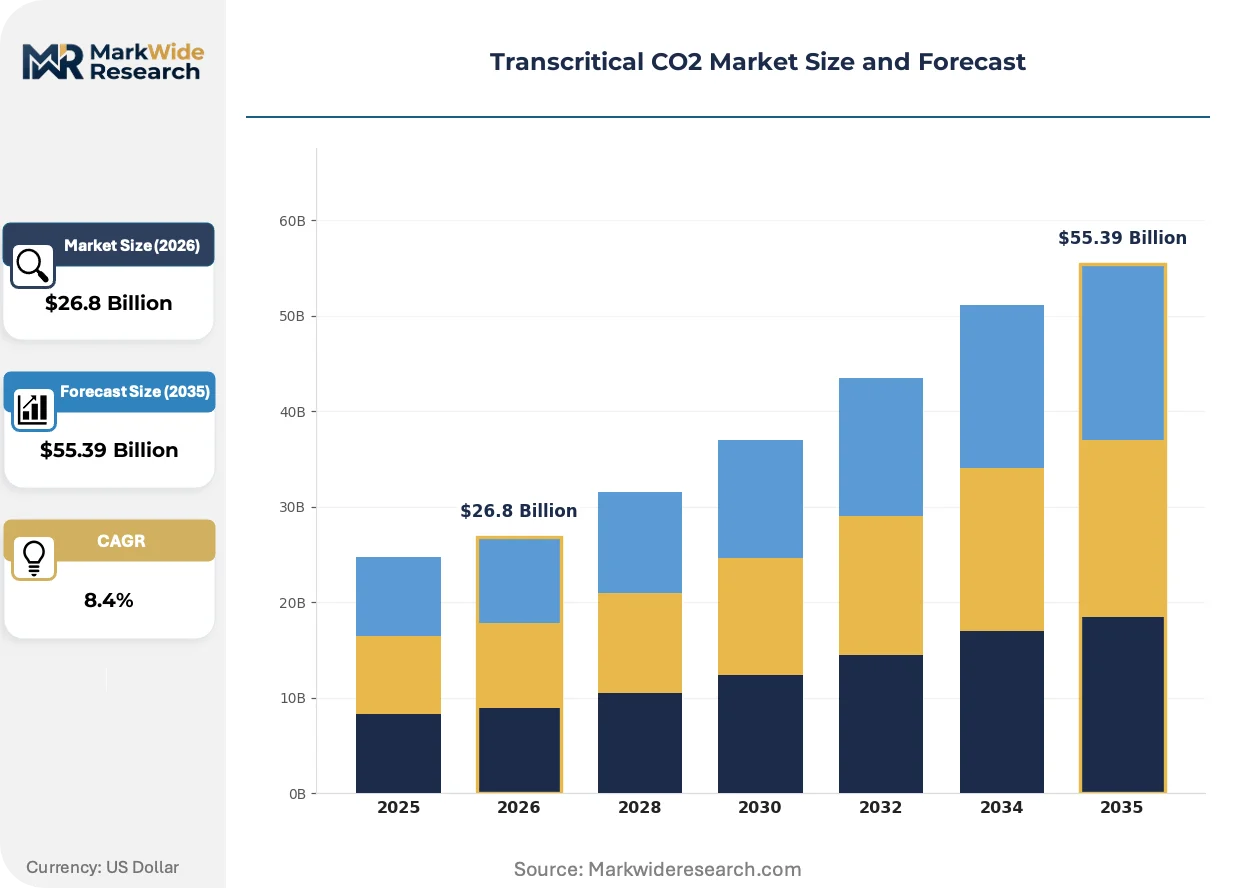
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $55.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Refrigeration, HVAC, Industrial Cooling, Food Processing Technology: Heat Exchangers, Compressors, Expansion Devices, Valves End User: Food Retail, Supermarkets, Commercial Sector, Beverage Industry Installation: New System, Retrofit, Upgrade, Maintenance |
| Companies Covered | Mayekawa, Advansor, Danfoss, Baltimore Aircoil Company, Hillphoenix, Emerson Climate Technologies, Carrier Commercial Refrigeration, Green & Cool, Bitzer Kuhlmaschinenbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcritical CO2 Market Strategic Shifts & Innovations
Equipment intelligence and thermal energy recovery are converging to expand transcritical CO2 beyond pure cooling into integrated energy systems. These developments are redefining value propositions for industrial adopters.
Adiabatic gas cooler technology is virtualizing the traditional air-cooled heat rejection paradigm. German supermarket operators are retrofitting existing transcritical racks with evaporative pre-cooling modules to maintain efficiency during summer peak loads. This upgrade path is compressing the performance gap between standard and premium system configurations.
The EU Ecodesign directive's 2024 tightening of energy efficiency requirements is mandating seasonal performance metrics that favor variable-speed compressor architectures. Equipment manufacturers are redesigning rack controllers to optimize part-load operation across ambient temperature bands. Food retail chains in Denmark and Sweden are specifying these advanced packages to preempt compliance deadlines.
Framework procurement agreements are consolidating buyer power among European supermarket cooperatives. Specialized integrators are displacing traditional distributor channels by offering lifecycle cost guarantees and remote monitoring services. This concentration is most visible in Germany, where REWE and EDEKA central purchasing units now dominate equipment selection for hundreds of stores.
Transcritical CO2 Market Segmentation
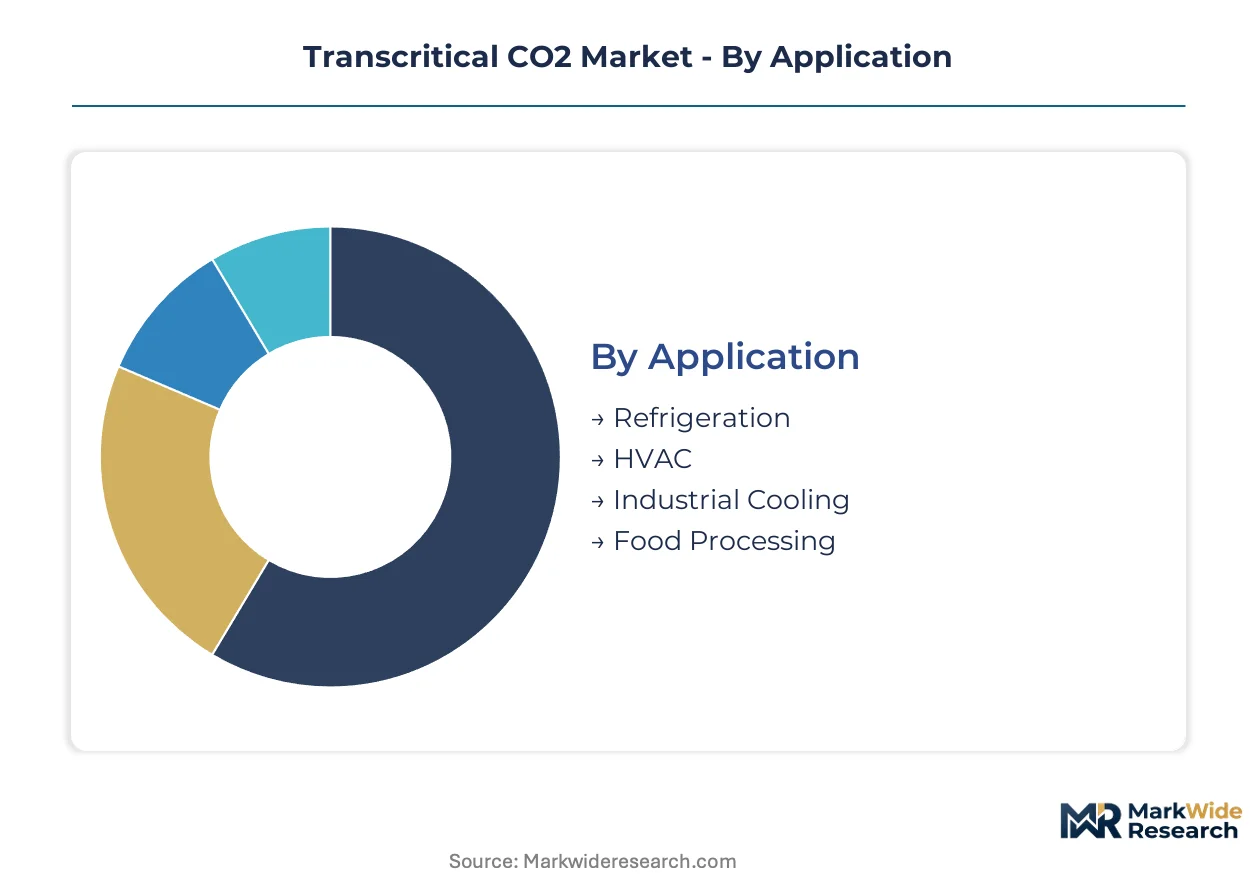
Transcritical CO2 systems serve divergent thermal loads across temperature bands and pressure regimes. Segmentation reveals how component specifications and installation approaches must adapt to each use case's thermodynamic profile and regulatory exposure.
Application:
Demand intensity varies with process temperature requirements and heat rejection profiles across commercial and industrial settings.
- Refrigeration:Medium and low-temperature display cases and cold rooms dominate unit deployment. Supermarket chains in Germany and Denmark specify these systems to preempt F-Gas Regulation service bans on hydrofluorocarbon equipment.
- HVAC:Building climate control applications exploit CO2's heat pump capability for simultaneous heating and cooling. Norwegian commercial buildings are integrating transcritical racks with district heating networks to maximize thermal energy recovery.
- Industrial Cooling:Process cooling for manufacturing and data centers leverages CO2's high volumetric capacity. Chemical plants in the Netherlands deploy these systems for reaction temperature control where flammability constraints exclude hydrocarbon alternatives.
- Food Processing:Blast freezing and chilled water production for meat and dairy operations. Swedish food processors are retrofitting ammonia systems with CO2 to eliminate toxic leak risks in occupied facilities.
Established volume favors Refrigeration; emerging adoption favors Food Processing.
Technology:
Component cost structures and supply concentration shape procurement strategies for system integrators.
- Heat Exchangers:Gas coolers and evaporators fabricated from aluminum microchannel tubing dominate material spend. Italian OEMs are qualifying domestic suppliers to reduce exposure to commodity aluminum price volatility.
- Compressors:Large-displacement semi-hermetic units enable multi-megawatt industrial installations. German and Japanese manufacturers control capacity expansion for these high-pressure designs, creating supply bottlenecks for rush orders.
- Expansion Devices:Electronic expansion valves modulate refrigerant flow across variable ambient conditions. French controls specialists are integrating these valves with predictive algorithms to optimize seasonal performance metrics.
- Valves:High-pressure ball valves and safety relief devices manage CO2's 73.8 bar critical pressure. Danish system builders stock standardized valve skids to accelerate rack assembly timelines.
Margin concentration sits with Compressors; procurement leverage concentrates in Heat Exchangers.
End User:
Customer scale and technical sophistication determine service model and financing structure.
- Food Retail:Small-format convenience stores and large hypermarkets present divergent charge limit constraints. Spanish retail cooperatives are piloting distributed systems to circumvent building code restrictions in enclosed urban locations.
- Supermarkets:Central procurement units at REWE and EDEKA in Germany negotiate framework agreements covering hundreds of locations. These buyers demand lifecycle cost guarantees and remote monitoring integration.
- Commercial Sector:Hotels, restaurants, and institutional kitchens require compact packaged systems. French hospitality groups prioritize plug-and-play racks that minimize on-site commissioning time.
- Beverage Industry:Breweries and soft-drink bottlers exploit CO2's temperature glide for pasteurization and bottle washing. Italian craft breweries are adopting transcritical heat pumps to capture waste heat for mashing operations.
Contract standardization favors Supermarkets; technical customization dominates Beverage Industry.
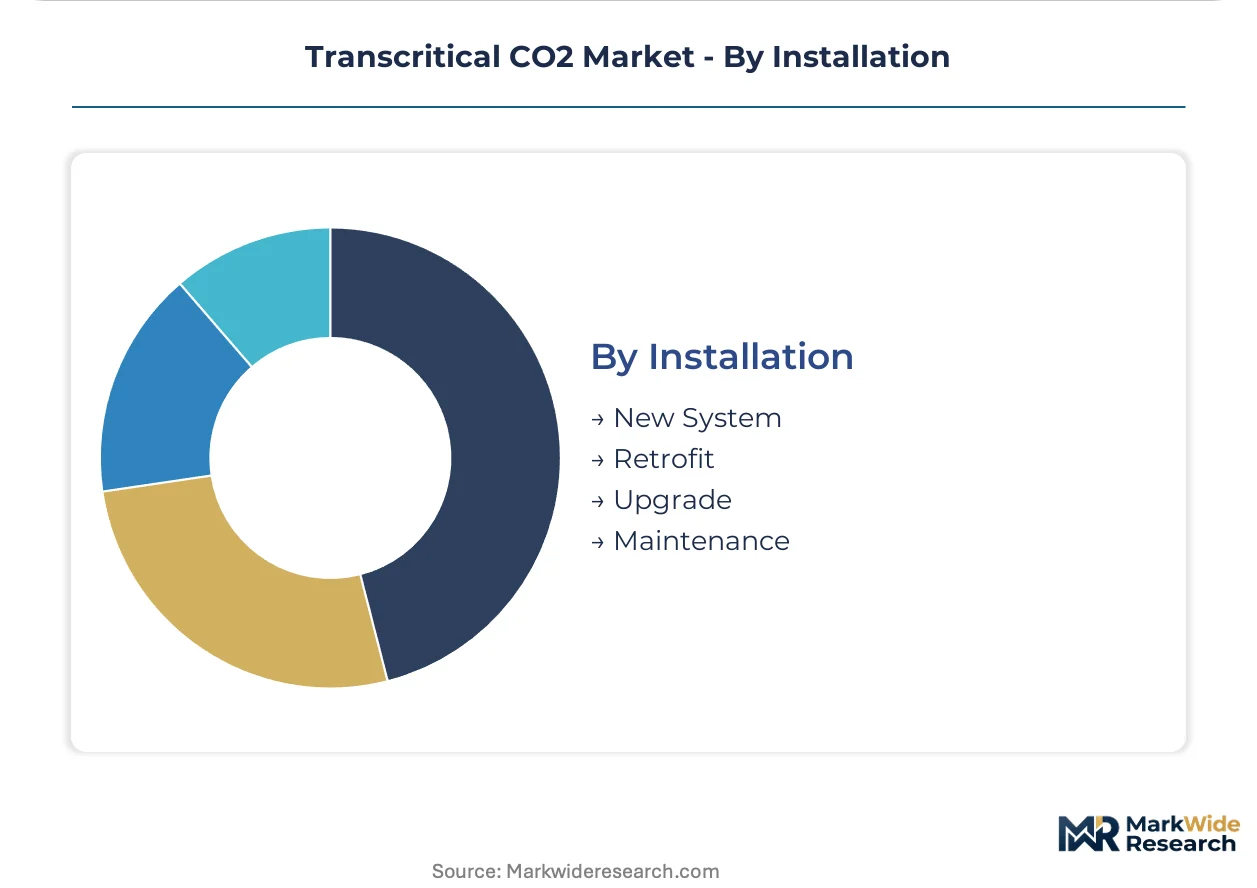
Installation:
Project type dictates engineering resource allocation and margin profile for specialized integrators.
- New System:Greenfield installations allow optimized charge minimization and integrated heat recovery from design phase. Norwegian supermarket construction permits now mandate transcritical CO2 for all new retail buildings.
- Retrofit:Existing store conversions require rack replacement within constrained mechanical rooms. German contractors are developing modular skid designs that fit through standard door openings to accelerate project timelines.
- Upgrade:Adiabatic gas cooler additions and compressor speed control retrofits improve seasonal efficiency. Danish operators are adding evaporative pre-cooling modules to existing racks to meet tightened Ecodesign requirements.
- Maintenance:Predictive service contracts using digital twin diagnostics are displacing break-fix arrangements. Swedish integrators offer performance-based contracts where fees scale with achieved energy savings.
Revenue stability favors Maintenance; growth velocity concentrates in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German supermarket operators command pricing leverage through framework procurement agreements that Nordic counterparts cannot replicate. Danish and Norwegian buyers absorb premium engineering costs for heat recovery integration. Southern European markets lag on installer density, compressing margins for first-mover integrators.
Germany
REWE and EDEKA central purchasing units negotiate lifecycle cost guarantees across hundreds of store locations. The F-Gas Regulation's accelerated phase-down compels HFC equipment replacement before service bans tighten. Berlin and Hamburg clusters concentrate retrofit contractor capacity for existing urban store footprints.
Denmark
Supermarket cooperatives specify variable-speed compressor architectures to preempt Ecodesign directive tightening. The Danish Energy Agency subsidizes heat pump integration for combined cooling and heating applications. Copenhagen and Aarhus host the densest concentration of transcritical CO2 installer expertise outside Norway.
Norway
Building codes now mandate transcritical CO2 for all new retail construction permits issued in Oslo and Bergen. The Norwegian Environment Agency enforces stricter charge limit protocols than EU minimums for enclosed spaces. Stavanger food processors are retrofitting ammonia systems with CO2 to eliminate toxic leak risks in occupied facilities.
Sweden
Food processors deploy transcritical heat pumps to capture waste heat for sanitation and mashing operations. The Swedish Energy Agency funds industrial cooling retrofits through climate transition grants. Malmö and Gothenburg integrators offer performance-based service contracts tied to achieved energy savings.
Italy
Southern European supermarket chains remain underpenetrated relative to Nordic peers, creating whitespace for expansion. Italian craft breweries adopt transcritical systems for pasteurization where temperature glide aligns with process needs. Milan and Turin OEMs are qualifying domestic aluminum suppliers to reduce commodity price volatility exposure.
Transcritical CO2 Market Key Industry Players
Component specialists and system integrators split the market along the value chain boundary. Compressor and valve manufacturers anchor long-term supply relationships through captive component portfolios. Rack assemblers compete on deployment speed and lifecycle service bundling. Dominant competitive moves include backward integration into heat exchanger fabrication and framework procurement consolidation among retail cooperatives.
Within the industrial-scale tier, Mayekawa occupies a position exemplifying custom-engineered heat pump configurations for food processing plants. Among European system integrators, Advansor and Green & Cool represent the packaged rack archetype designed for rapid retrofit deployment in constrained mechanical rooms. Danfoss anchors the component-specialist position through compressor and valve portfolio breadth that sustains supply relationships with retrofit-focused contractors.
| Leading Market Players |
|---|
| Mayekawa |
| Advansor |
| Danfoss |
| Baltimore Aircoil Company |
| Hillphoenix |
| Emerson Climate Technologies |
| Carrier Commercial Refrigeration |
| Green & Cool |
| Bitzer Kuhlmaschinenbau |
| Others |
Cost & Logistics Intelligence
Stuttgart's compressor manufacturing cluster anchors European supply capacity for large-displacement CO2 units, concentrating pricing leverage among German and Japanese OEMs while downstream rack assemblers absorb margin compression on fixed-price framework contracts.
Pricing Analysis
Configured-to-order pricing for custom-engineered industrial heat pumps commands substantial premiums over standard packaged rack systems for supermarket retrofits. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the standard tier is intensifying because aluminum microchannel tubing volatility squeezes heat exchanger fabrication margins. Small-format convenience stores exhibit highest price sensitivity due to charge limit constraints fragmenting equipment specifications, while industrial food processors show lowest sensitivity given waste heat recovery value capture.
Supply Chain Analysis
Export control regimes on high-pressure compressor manufacturing equipment limit capacity expansion outside Germany and Japan, constraining supply elasticity for rush orders. Component fabrication draws from specialized steel forging in Germany, precision machining in Japan, and aluminum extrusion in Italy. Single-source vulnerability concentrates in large-displacement semi-hermetic compressor supply where Bitzer and Mayekawa control capacity expansion. Distribution runs through specialized integrators displacing traditional distributor channels across Northern European supermarket cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized procurement units at REWE and EDEKA as framework agreements consolidate equipment selection across hundreds of store locations, fragmenting vendor pricing leverage.
For Market Incumbents: Harden supply relationships with retrofit-focused contractors through captive compressor and valve portfolios that anchor long-term framework agreements. Deepen backward integration into heat exchanger fabrication to offset aluminum price volatility exposure. Prioritize certification investment for CO2 technician training programs to lock in service contract renewals as emerging integrators threaten aftermarket revenue. For New Entrants and Emerging Players: Establish a beachhead in Italian supermarket retrofit backlog where installer density lags Nordic peers and first-mover margins remain intact. Target beverage process cooling applications where temperature glide characteristics align with craft brewery expansion. Pursue remote monitoring integration as a go-to-market angle to displace break-fix service arrangements with performance-based contracts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because F-Gas Regulation phase-down mandates create irreversible equipment replacement cycles independent of economic cycles. Acquisition targets should emphasize specialized integrators with lifecycle cost guarantee capabilities and digital twin platform integration. Watch installer certification bottlenecks as the inflection signal for service contract pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Fabrication | Italian OEMs qualifying domestic aluminum suppliers reduce commodity price volatility exposure from global metal markets. |
| Framework Procurement Consolidation | REWE and EDEKA central purchasing units now dominate equipment selection across hundreds of German store locations. |
| Digital Twin Platform Integration | Swedish integrators offer performance-based contracts where fees scale with achieved energy savings from predictive diagnostics. |
| Variable-Speed Compressor Architecture Investment | Danish supermarket cooperatives specify advanced packages to preempt tightened EU Ecodesign directive compliance deadlines. |
| Adiabatic Gas Cooler Retrofit Deployment | German operators retrofit existing racks with evaporative pre-cooling modules to maintain efficiency during summer peak loads. |
Research Approach
Operator-level perspectives from supermarket procurement directors, refrigeration system integrators, compressor OEM product managers, and food processing plant engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation from EU F-Gas Regulation implementation reports, Ecodesign directive compliance filings, national building code amendments, and aluminum commodity trade data. Bottom-up installation tracking across Germany, Denmark, Norway, and Sweden triangulated against top-down market sizing from component manufacturer capacity disclosures.
Scenario-bracketing around regulatory phase-down schedules and commodity price volatility bands shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include application temperature regime, system capacity tier, installation project type, and end-user procurement sophistication. CAGRs derived from installed base turnover rates and replacement cycle compression under accelerated compliance deadlines. Industry-specific forecast inputs incorporated heat pump integration adoption curves and adiabatic cooling retrofit penetration patterns.
Sensitivities concentrate around F-Gas Regulation enforcement intensity, aluminum price volatility spikes, and compressor supply capacity expansion timing. Forecasts reflect documented assumptions on regulatory schedule adherence and installer certification pipeline throughput. Material shifts in EU member state building code harmonization or German-Japanese compressor supply allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
North America Syngas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Krypton-85 Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Industrial Gas Phase Filtration System Market