
 Krypton Gas Market | 2026-2036
Krypton Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Krypton Gas Market Outlook
The Krypton Gas Market is restructuring around a sharp divergence between high-purity semiconductor-grade supply and commodity industrial grades. Air Liquide leverages its cryogenic separation infrastructure to dominate the premium tier. Linde plc sustains cost advantages through backward integration into air separation units. Messer Group differentiates via regional hub strategies across Central European industrial clusters.
Krypton is a monatomic noble gas with atmospheric concentration of roughly 1.14 parts per million, extracted via fractional distillation of liquid air and purified through adsorption and catalytic processes to achieve purity levels exceeding 99.999% for electronics applications. Its primary industrial purpose centers on high-performance insulation in triple-pane windows and as a buffer medium in excimer lasers for semiconductor lithography. High-Purity Krypton commands the dominant margin pool due to stringent specifications from chip foundries, while Laser Systems application growth outpaces the mature Lighting segment where LED displacement continues. Specialty Krypton variants occupy niche positions in aerospace propulsion testing, though volume remains constrained by limited qualified suppliers.
EPA regulations on fluorinated greenhouse gases and the EU F-Gas Regulation impose reporting obligations and phase-down schedules that indirectly tighten krypton recovery economics, while China's GB standards for electronic-grade gases set import substitution targets that reshape competitive access. The analysis shows stakeholders must monitor rare gas recycling investments and semiconductor capital expenditure cycles as decisive variables for supply allocation.
Market Dynamics
Semiconductor lithography demand is pulling high-purity krypton supply toward electronics-grade specifications, while EU F-Gas Regulation phase-down schedules tighten atmospheric gas recovery economics and reshape allocation priorities across industrial clusters.
Growth Catalysts
- Semiconductor capital expenditure cycles:Chip foundries in Taiwan and South Korea are expanding excimer laser installations for advanced node production, pulling premium krypton volumes away from commodity applications.
- EU F-Gas Regulation:The phase-down mandates for fluorinated greenhouse gases indirectly elevate krypton recovery economics by constraining alternative buffer gas options in insulation and lighting systems.
- China's GB standards for electronic-grade gases:Import substitution targets under national semiconductor self-sufficiency programs are accelerating domestic rare gas purification capacity buildout.
Market Restraints
- Atmospheric concentration limits:Krypton's 1.14 ppm atmospheric abundance imposes fundamental throughput ceilings on cryogenic air separation units, constraining volume scaling regardless of capital deployment.
- Ukraine-Russia supply corridor concentration:Pre-conflict rare gas refining infrastructure concentration in Eastern European industrial zones created lasting supply security premiums that persist in contract pricing.
- LED substitution in lighting:Solid-state lighting technology has compressed incandescent and halogen lamp demand, eliminating a historical krypton offtake anchor in consumer and commercial segments.
Strategic Opportunities
- Aerospace propulsion testing:Hypersonic vehicle development programs in the United States are creating qualified-supplier-constrained demand for specialty krypton variants in wind tunnel and engine test applications.
- Triple-pane window retrofits:Building energy efficiency mandates in Germany and France are accelerating high-performance glazing replacement cycles in existing commercial and residential building stock.
- Rare gas recycling infrastructure:Closed-loop recovery systems for semiconductor process exhaust are enabling captive supply models that bypass traditional merchant gas distribution channels.
Industry Challenges
- Cryogenic engineering talent scarcity:Fractional distillation plant operations and maintenance require specialized expertise that has atrophied as industrial gas majors consolidated regional production networks.
- Semiconductor-grade certification timelines:Chip foundry qualification protocols for new krypton suppliers extend 18-36 months, freezing out merchant market entrants regardless of purity achievement.
- Legacy air separation unit retrofit complexity:Existing ASU infrastructure optimized for oxygen and nitrogen production requires capital-intensive reconfiguration to enhance rare gas capture yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Krypton Gas Market |
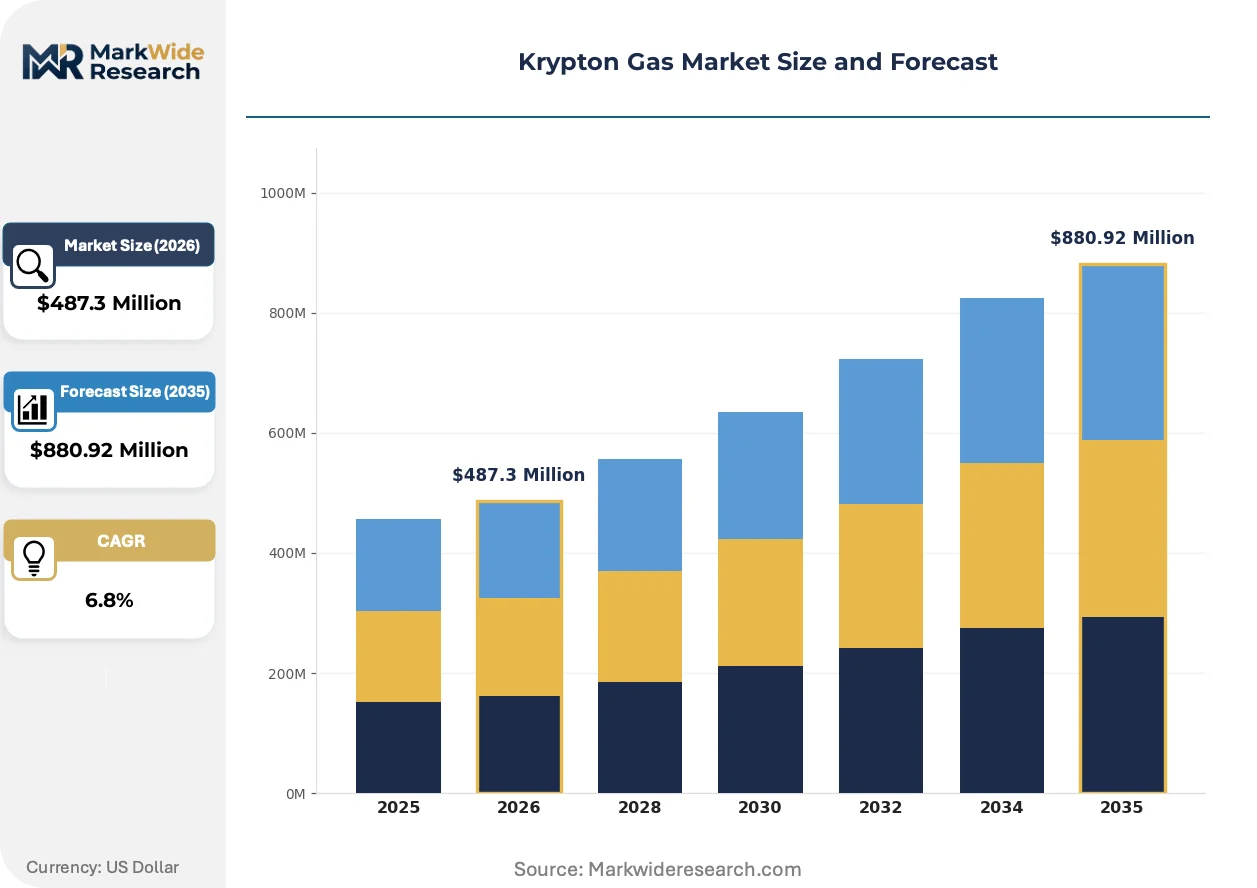
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Krypton, Krypton Mixtures, Industrial Krypton, Specialty Krypton Application: Lighting, Insulation, Astronomy, Laser Systems End User: Manufacturing, Scientific Research, Telecommunications, Aerospace Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Messer Group, Matheson Tri-Gas, Taiyo Nippon Sanso Corporation, Praxair Technology, Iceblick Ltd, SOL Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Krypton Gas Market Strategic Shifts
Process intensification in rare gas separation and purification is compressing the cost gap between merchant supply and on-site recovery, while regulatory phase-down schedules and semiconductor specification tightening are bifurcating the market into premium and commodity tiers.
Membrane-assisted cryogenic separation is absorbing incremental capital allocation from major industrial gas producers seeking to debottleneck krypton and xenon recovery from large-scale air separation trains. ASU operators in Belgium and Japan are piloting hybrid membrane-cryogenic configurations that promise 15-20% yield improvements over conventional distillation alone. The technology is absorbing engineering resources that might otherwise flow to green hydrogen or carbon capture projects, reflecting strategic prioritization of rare gas margin pools.
EPA regulations on fluorinated greenhouse gases and the EU F-Gas Regulation are tightening reporting obligations and recovery mandates for atmospheric-derived specialty gases. These frameworks are elevating krypton as a compliant alternative in applications where sulfur hexafluoride or perfluorocarbons face phase-down pressure. Insulation glass manufacturers in the Netherlands and lighting system integrators in Italy are reformulating product specifications to substitute krypton where thermal performance or discharge characteristics permit.
Long-term offtake contracting is displacing spot market procurement for high-purity krypton as semiconductor foundries seek supply security for multi-year capital equipment deployment cycles. Taiwan and South Korea-based chip manufacturers are negotiating direct supply agreements with air separation operators, bypassing traditional merchant gas distributors. This pattern concentrates volume allocation decisions among a handful of integrated device manufacturers and constrains availability for secondary industrial applications.
Krypton Gas Market Segmentation
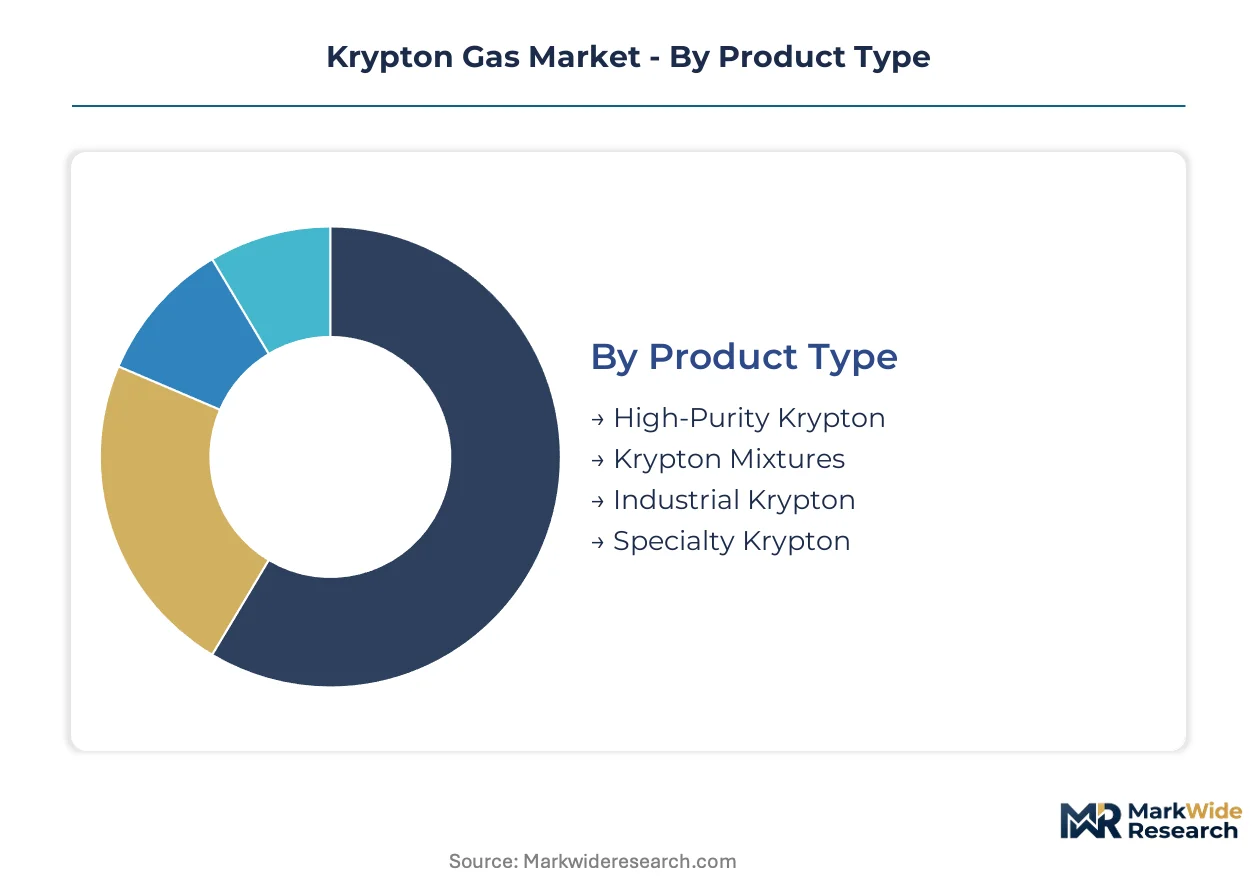
Krypton gas segmentation reflects divergent certification burdens across purity grades and end-use specifications. Chip foundries impose qualification protocols that freeze out unqualified suppliers, while industrial applications tolerate broader specification bands.
Product Type:
High-Purity Krypton carries the heaviest certification load, requiring SEMI standards compliance and individual foundry qualification that extends 18-36 months. Industrial Krypton faces lighter regulatory scrutiny under general industrial gas standards.
- High-Purity Krypton:Exceeds 99.999% purity through adsorption and catalytic finishing processes. Demand concentrates in Taiwan and South Korea for excimer laser buffer gas in semiconductor lithography, with foundry capital expenditure cycles pulling supply away from commodity markets.
- Krypton Mixtures:Blends with argon or xenon for specialized discharge characteristics. German and French insulation glass manufacturers are reformulating specifications to substitute krypton mixtures where EU F-Gas Regulation phase-down pressures alternative fluorinated gases.
- Industrial Krypton:Standard purity grades for general manufacturing and research applications.
- Specialty Krypton:Custom isotopic compositions for aerospace propulsion testing and scientific instrumentation.
Leading the category by volume: Industrial Krypton. Growing fastest: High-Purity Krypton.
Application:
Application segments diverge sharply by margin structure, with semiconductor-facing uses commanding premium pricing over mature industrial categories.
- Laser Systems:Excimer laser buffer gas for deep ultraviolet lithography at advanced semiconductor nodes. Taiwan-based foundries are expanding installations, pulling krypton volumes toward electronics-grade specifications with multi-year offtake contracting displacing spot procurement.
- Insulation:Fill gas for triple-pane windows delivering thermal performance superior to argon. Building energy efficiency mandates in Germany and France are accelerating replacement cycles in existing commercial and residential stock.
- Lighting:Incandescent and halogen lamp fill gas facing LED substitution pressure.
- Astronomy:Calibration sources and detector applications in observatory instrumentation.
Highest margin capture: Laser Systems. Steepest volume decline: Lighting.
End User:
End user concentration determines contract structure, with integrated device manufacturers negotiating direct supply agreements that bypass traditional distribution.
- Manufacturing:Window fabrication, lighting assembly, and general industrial processing.
- Scientific Research:Laboratory instrumentation and experimental physics applications.
- Telecommunications:Fiber optic manufacturing and specialized laser systems.
- Aerospace:Hypersonic vehicle development programs in the United States are creating qualified-supplier-constrained demand for specialty krypton variants in wind tunnel and engine test applications.
Deepest supply security premiums: Aerospace. Most price-sensitive procurement: Manufacturing.
Distribution Channel:
Channel selection tracks customer scale and specification stringency, with high-purity volumes migrating toward direct relationships.
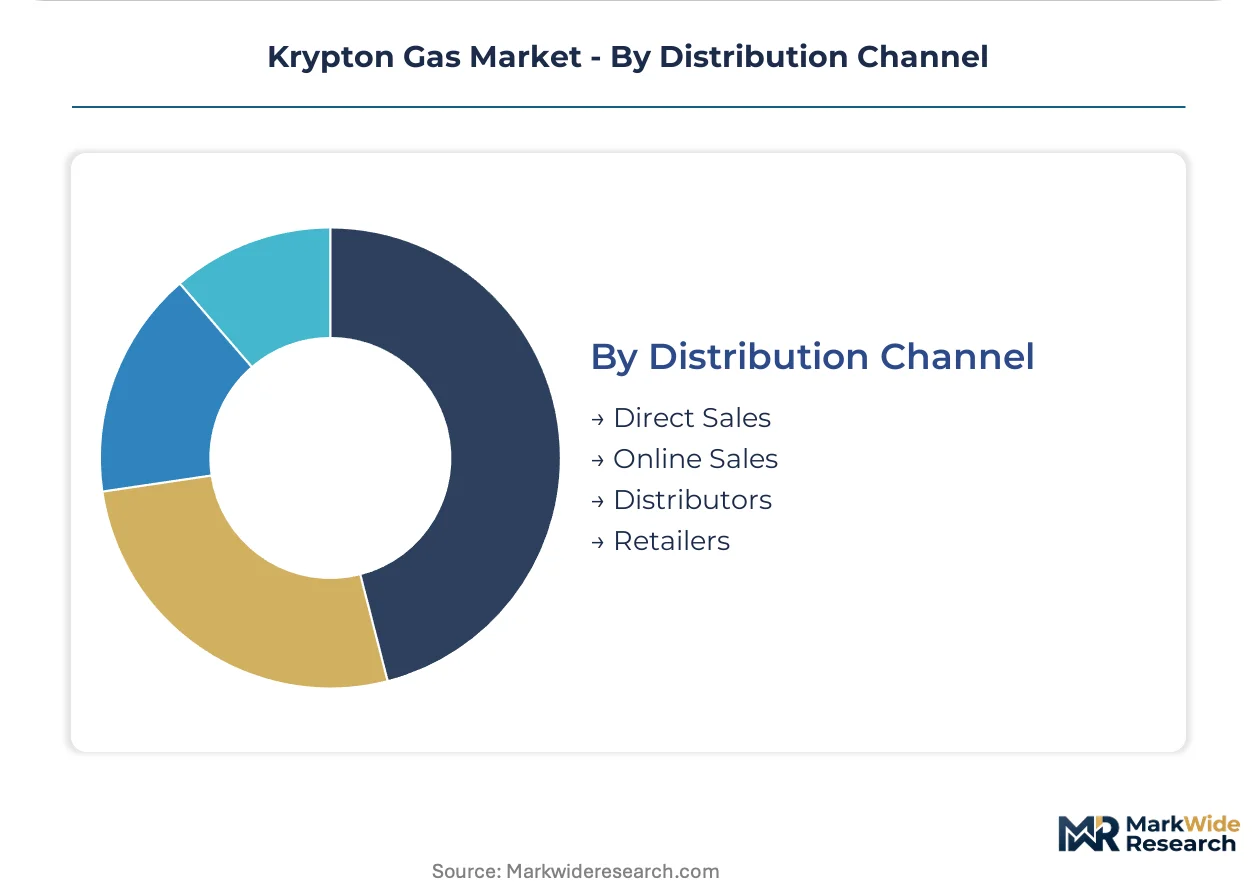
- Direct Sales:Long-term offtake agreements between air separation operators and semiconductor foundries. Taiwan and South Korea-based chip manufacturers are negotiating direct supply agreements, concentrating volume allocation decisions among integrated device manufacturers.
- Distributors:Merchant gas networks serving fragmented industrial and research demand.
- Online Sales:Catalog procurement for standard purity grades and small-volume laboratory requirements.
- Retailers:Limited presence concentrated in welding supply and specialty gas storefronts.
Fastest channel expansion: Direct Sales. Most channel compression: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei anchors high-purity krypton procurement as Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation expand excimer laser installations for advanced node production.
United States
Hypersonic vehicle development programs at Arnold Engineering Development Complex and NASA Langley Research Center drive specialty krypton demand for wind tunnel testing. EPA regulations on fluorinated greenhouse gases elevate krypton as a compliant buffer gas alternative. Houston-Gulf Coast industrial clusters concentrate air separation capacity serving petrochemical and aerospace applications.
Germany
Building energy efficiency mandates accelerate triple-pane window retrofits across commercial and residential building stock. EU F-Gas Regulation phase-down schedules constrain alternative fluorinated insulation gases. Ruhr industrial corridor hosts concentrated air separation infrastructure optimized for rare gas recovery from steel and chemical plant feedstocks.
China
Domestic rare gas purification capacity scales rapidly under GB standards for electronic-grade gases and national semiconductor self-sufficiency programs. Ministry of Ecology and Environment dual carbon goals reshape industrial gas investment priorities. Yangtze River Delta clusters in Shanghai and Jiangsu province concentrate new cryogenic separation plant construction.
South Korea
Samsung Foundry and SK Hynix expand deep ultraviolet lithography capacity, pulling premium krypton volumes through multi-year direct supply agreements. Korean Industrial Standards for specialty gases tighten import substitution targets. Pyeongtaek-Dongtan semiconductor complex emerges as decisive demand concentration point for high-purity specifications.
Japan
Excimer laser system manufacturers in Nagoya-Chubu industrial zone sustain precision gas demand for domestic and export equipment sales. METI technology roadmaps prioritize rare gas supply chain resilience. Osaka-Kobe chemical industry corridor maintains legacy air separation infrastructure with incremental krypton yield enhancement investments.
Krypton Gas Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification burden and purity specification tiers. The market structure consolidates around cryogenic air separation operators with backward integration into atmospheric gas recovery. Three archetypes dominate: integrated industrial gas majors with global ASU networks, regional specialists with hub-and-spoke distribution models, and captive semiconductor supply joint ventures. Capacity expansion and long-term offtake contracting constitute the dominant competitive moves as foundries seek supply security.
Within the integrated major tier, Air Liquide, Linde plc, and Air Products and Chemicals occupy positions defined by cryogenic infrastructure scale and rare gas purification depth. These entities exemplify the premium-tier archetype through control over air separation unit economics and qualification timelines for semiconductor-grade certification. Regional specialists including Messer Group and Matheson Tri-Gas represent hub-focused alternatives with concentrated Central European and North American presence respectively. Japanese and Korean market presence includes Taiyo Nippon Sanso Corporation as a representative of Asia-Pacific industrial gas consolidation.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals |
| Messer Group |
| Matheson Tri-Gas |
| Taiyo Nippon Sanso Corporation |
| Praxair Technology |
| Iceblick Ltd |
| SOL Group |
| Others |
Value Chain & Pricing Dynamics
High-purity semiconductor-grade krypton diverges sharply from commodity industrial grades, with chip foundry certification timelines and EU F-Gas Regulation compliance costs embedding premium pricing into electronics-tier supply chains while atmospheric concentration limits constrain volume scaling across all tiers.
Pricing Analysis
Yield-based pricing anchors semiconductor-grade krypton contracts, with foundries paying premiums tied to excimer laser uptime guarantees and lithography throughput performance. Three-tier pricing structure across premium, standard, and economy levels separates SEMI-qualified electronics grades from industrial window-fill specifications and generic research supply. Cost compression in the commodity tier is intensifying because Chinese domestic capacity buildout under GB standards is expanding merchant gas availability. Manufacturing procurement teams exhibit highest price sensitivity, while aerospace propulsion programs show lowest sensitivity due to qualified-supplier scarcity.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale semiconductor demand, bypassing traditional merchant distributors for multi-year offtake agreements. Supply concentrates in Belgium, Japan, and the United States for cryogenic separation infrastructure, with Ukraine-Russia corridor disruption elevating security premiums in European contract pricing. Raw material draws from atmospheric air separation, specialized adsorption media, and catalytic purification catalysts. Single-source vulnerability persists in Eastern European rare gas refining capacity. Distribution runs through hub-and-spoke industrial gas networks for fragmented research and manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Excimer laser technology is displacing mercury-vapor lithography systems, restructuring demand specifications and supplier qualification requirements across the forecast period.
For Market Incumbents: Extend semiconductor-grade certification pipelines to lock in foundry relationships before Chinese domestic suppliers achieve GB standards compliance. Deepen backward integration into air separation unit retrofits to enhance krypton yield capture from existing oxygen-nitrogen infrastructure. LED substitution in lighting and Ukraine-Russia supply corridor concentration represent dual threats requiring geographic diversification of cryogenic capacity.
For New Entrants and Emerging Players: E-commerce platforms for laboratory-grade rare gases offer the most penetrable entry vector, bypassing 18-36 month foundry qualification barriers that freeze out merchant market entrants. Target aerospace propulsion testing segments where qualified-supplier constraints limit incumbent coverage. Specialty isotopic compositions for wind tunnel applications present white-space opportunity with lighter certification burdens than electronics-grade supply.
For Investors and Strategic Acquirers: Re-rating potential sits with regional hub specialists given EU F-Gas Regulation phase-down schedules elevating compliant gas alternatives. Long-term viability hinges on rare gas recycling infrastructure deployment across semiconductor manufacturing clusters. Monitor closed-loop recovery system investments as the decisive signal for captive supply model displacement of traditional distribution channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Assisted Cryogenic Separation Deployment | Belgian and Japanese ASU operators pilot hybrid configurations promising 15-20% krypton yield improvements. |
| Long-Term Foundry Offtake Contracting | Taiwan and South Korea chip manufacturers negotiate direct supply agreements bypassing merchant distributors. |
| Rare Gas Recycling Infrastructure Buildout | Closed-loop semiconductor exhaust recovery enables captive supply models circumventing traditional channels. |
| Triple-Pane Window Retrofit Acceleration | German and French building efficiency mandates drive high-performance glazing replacement cycles. |
| Aerospace Propulsion Testing Qualification | Arnold Engineering Development Complex programs create supplier-constrained demand for specialty krypton variants. |
Study Parameters
Document review covered SEC filings from industrial gas majors, EU F-Gas Regulation implementation reports, and SEMI standards documentation, complemented by interviews with cryogenic plant operations managers, semiconductor procurement leads at Taiwan and South Korea foundries, specialty gas distribution channel partners, and EPA regulatory affairs specialists. Secondary validation drew from customs trade data, air separation unit capacity databases, and national semiconductor self-sufficiency program disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Segment-level outputs across the analysis window reflect purity grade tiering, application specifications, end-user concentration, and regional production hub clustering. CAGRs were derived from regression analysis against semiconductor capital expenditure cycles and building energy efficiency mandate implementation timelines. Cryogenic engineering talent scarcity and legacy ASU retrofit complexity served as industry-specific forecast constraints.
The model holds under stable EU regulatory phase-down schedules and continued foundry capacity expansion; deviation in Chinese domestic purification technology advancement or Ukraine-Russia corridor stabilization would shift supply allocation and pricing power assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Helium Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Helium Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
North America Syngas Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market