
 Pharmaceutical Thermal Analysis Market | 2026-2036
Pharmaceutical Thermal Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Thermal Analysis Market Analytics
Multi-source procurement for thermal analysis instrumentation is pivoting toward consolidated vendor partnerships with embedded service contracts. TA Instruments leverages its North American service infrastructure to anchor long-term relationships with large pharmaceutical manufacturers. NETZSCH differentiates through specialized high-temperature calorimetry systems designed for polymer-excipient compatibility studies. PerkinElmer competes by extending its software ecosystem into compliant data-management workflows that satisfy 21 CFR Part 11 requirements.
Pharmaceutical thermal analysis encompasses calorimetric and thermogravimetric techniques that measure heat flow, mass change, and mechanical properties of drug substances and excipients under controlled temperature programs, typically operating from sub-ambient conditions to 1,600°C depending on the analytical method. These systems serve the primary commercial purpose of characterizing polymorphism, glass transitions, and thermal stability to ensure batch consistency and regulatory compliance in drug development. Differential scanning calorimetry occupies the largest product-type position due to its ubiquity in preformulation screening and stability-protocol design. Thermogravimetric analysis represents the fastest-expanding segment as lyophilized biologic formulations require precise moisture-content validation. Dynamic mechanical analysis remains a comparatively mature niche, serving specialized polymer-coating and modified-release applications where viscoelastic property mapping justifies capital investment.
The FDA enforces ICH Q1A stability-testing guidelines that mandate thermal characterization for new molecular entities, while the EMA's QWP stability recommendations impose comparable analytical burdens on European filings. ISO 11357 and USP <891> provide harmonized methodological frameworks that shape instrument validation protocols and cross-border market access for equipment vendors. Stakeholders must monitor evolving pharmacopeial standards for cell and gene therapy products, where novel excipient classes and lipid-nanoparticle formulations challenge conventional thermal analysis boundaries and instrument specification requirements.
Market Dynamics
The FDA's tightened stability-testing guidelines for novel biologics and biosimilars compel manufacturers to invest in higher-resolution thermal instrumentation, compressing replacement cycles for legacy calorimetry platforms across contract research organizations and large pharmaceutical manufacturers.
Growth Catalysts
- ICH Q1A Stability Mandates:The FDA enforces thermal characterization requirements for new molecular entities, forcing drug developers to acquire compliant differential scanning calorimetry systems for preformulation screening and batch consistency validation.
- Lyophilized Biologic Expansion:Thermogravimetric analysis demand accelerates as moisture-content validation becomes critical for freeze-dried protein formulations and lipid-nanoparticle drug delivery systems.
- Boston-San Francisco Biopharma Cluster Density:Concentrated R&D investment in these metropolitan corridors drives instrument replacement and service contract expansion for thermal analysis vendors.
Market Restraints
- High-Purity Gas Supply Volatility:Thermal analysis systems require consistent nitrogen, helium, and argon flows; input cost swings constrain operational budgeting for high-throughput analytical labs.
- Instrument Vendor Concentration:North American and European equipment manufacturers dominate precision calorimetry supply, creating procurement risk for Asian-Pacific pharmaceutical developers seeking localized support infrastructure.
- Temperature Range Limitations:Conventional differential scanning calorimetry caps near 700°C, forcing polymer-excipient compatibility studies onto specialized high-temperature platforms with extended lead times.
Strategic Opportunities
- Cell and Gene Therapy Excipient Characterization:Novel lipid-nanoparticle and viral-vector formulations challenge conventional thermal analysis boundaries, creating specification gaps for instrument vendors to address.
- India CDMO Instrumentation Upgrade Cycle:Contract development and manufacturing organizations in Indian pharmaceutical hubs underinvest in thermal analysis capacity relative to formulation complexity, presenting equipment penetration potential.
- 21 CFR Part 11 Software Ecosystem Integration:Compliant data-management workflow demand creates attach-rate expansion for vendors bundling thermal hardware with validated electronic record systems.
Industry Challenges
- Qualified Thermal Analyst Scarcity:Pharmaceutical companies struggle to hire personnel proficient in both calorimetric method development and regulatory submission documentation.
- Legacy System Data Migration:Pharmaceutical manufacturers face integration friction when connecting decades-old thermal analysis platforms to modern laboratory information management systems.
- Pharmacopeial Standard Lag:ISO 11357 and USP <891> frameworks require revision to address cell therapy products, delaying instrument validation protocols for emerging modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Thermal Analysis Market |
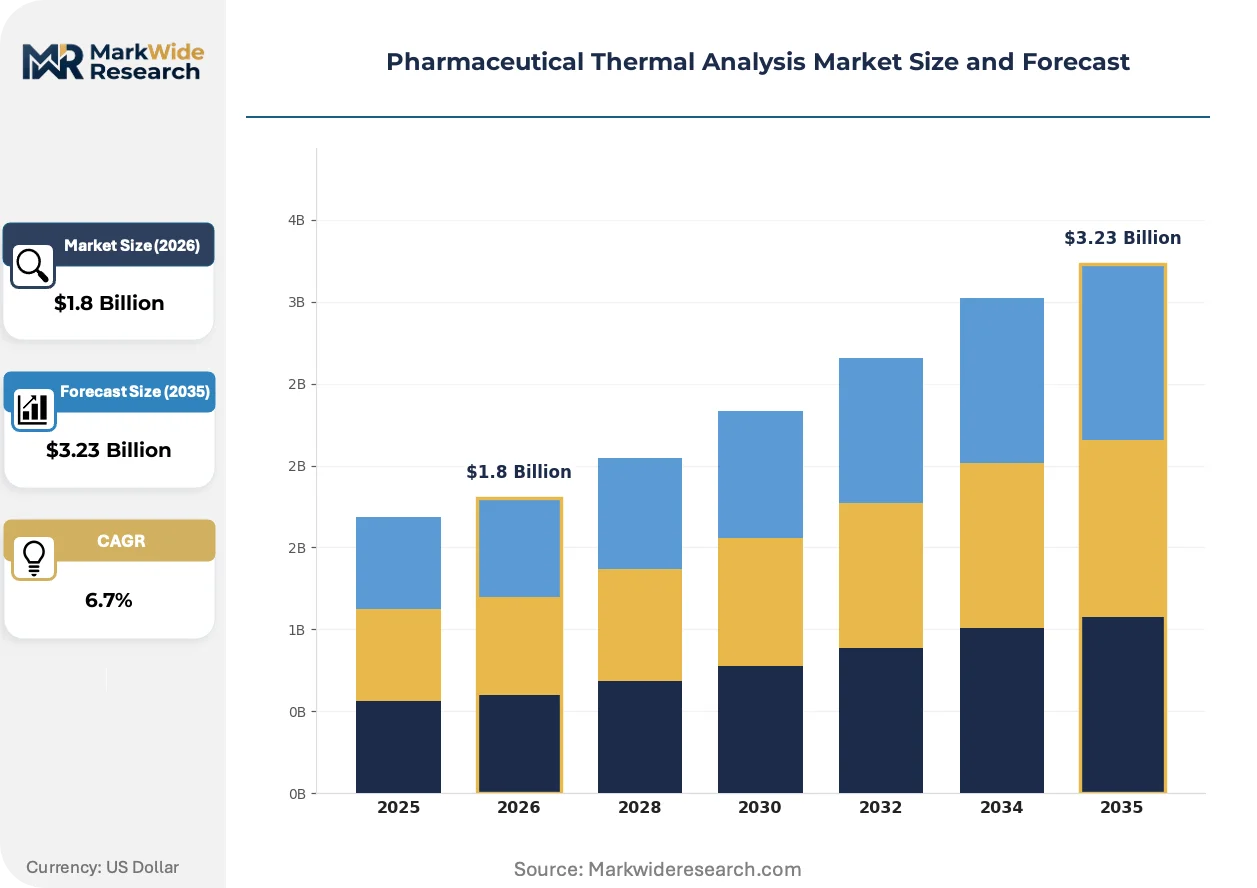
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
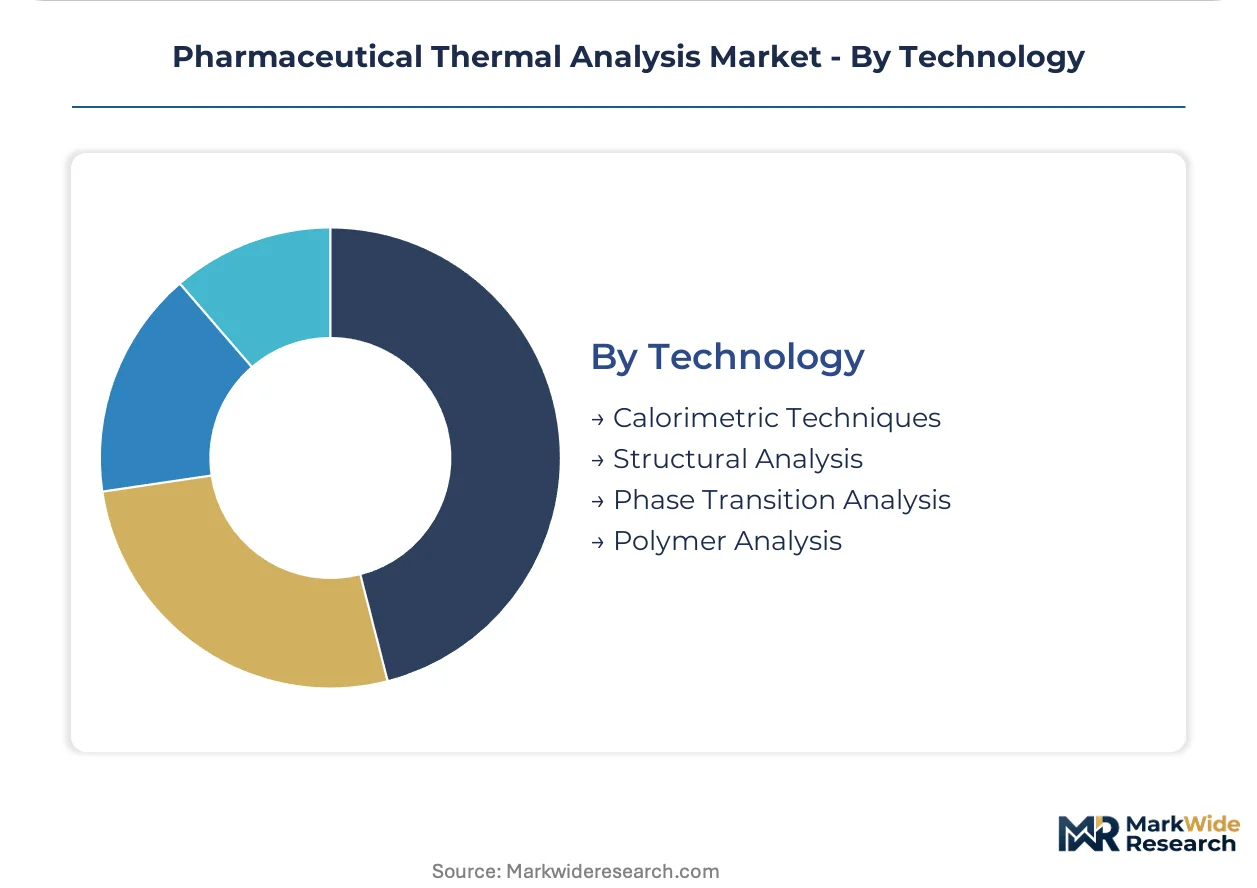
| Segmentation | Product Type: Differential Scanning Calorimetry, Thermogravimetric Analysis, Dynamic Mechanical Analysis, Thermal Conductivity End User: Pharmaceutical Companies, Research Laboratories, Academic Institutions, Contract Research Organizations Application: Stability Testing, Quality Control, Formulation Development, Material Characterization Technology: Calorimetric Techniques, Structural Analysis, Phase Transition Analysis, Polymer Analysis |
| Companies Covered | PerkinElmer, TA Instruments, Mettler-Toledo, Hitachi High-Technologies, NETZSCH, LECO Corporation, Rigaku, Setaram Instrumentation, Linseis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Thermal Analysis Market Evolving Landscape
Modular thermal analysis architectures are displacing monolithic platforms, enabling pharmaceutical labs to reconfigure calorimetric, thermogravimetric, and mechanical analysis capabilities without full instrument replacement.
Hyphenated thermal analysis is integrating mass spectrometry detection with thermogravimetric systems to identify evolved gases during drug substance decomposition. Large pharmaceutical manufacturers in the United States and Germany adopt these coupled platforms for impurity profiling and forced degradation studies. This convergence compresses analytical timelines by combining thermal stability assessment with molecular identification in a single workflow.
The EMA's QWP stability recommendations impose analytical burdens comparable to FDA guidelines, compelling European filers to harmonize thermal characterization protocols across transatlantic submissions. This regulatory alignment forces instrument vendors to standardize software compliance modules for simultaneous 21 CFR Part 11 and Annex 11 qualification. Biologics developers in Switzerland and the Netherlands now prioritize dual-validated platforms to streamline multi-territory regulatory filings.
Service contract unbundling is fragmenting traditional thermal analysis procurement, with pharmaceutical buyers separating hardware acquisition from validation, training, and maintenance agreements. Contract research organizations in the San Francisco Bay Area increasingly source instrumentation through capital-light leasing arrangements while purchasing compliance documentation separately. This disintermediation pressures vendors to price service components transparently and compete on response-time guarantees rather than bundled discounts.
Pharmaceutical Thermal Analysis Market Segmentation
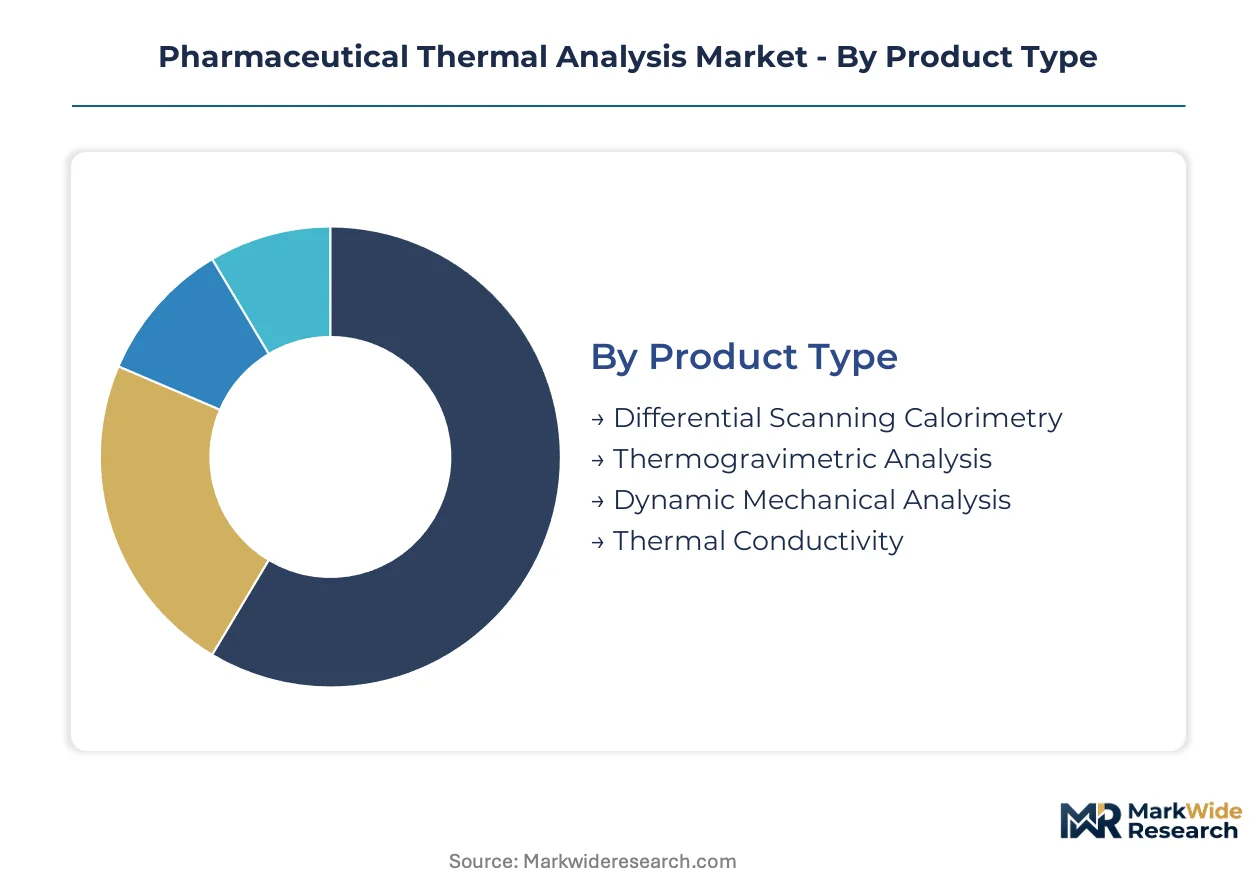
Segmentation in pharmaceutical thermal analysis reveals how instrument specifications align with distinct regulatory and operational requirements across drug development workflows. Product type and end-user configurations determine capital allocation patterns, while application and technology dimensions shape vendor R&D priorities and service contract structures.
Product Type:
Supply concentration among North American and European OEMs favors platforms with embedded compliance documentation and rapid service response capabilities.
- Differential Scanning Calorimetry:Measures heat flow differences between sample and reference under controlled temperature programs, typically spanning -180°C to 700°C. Pharmaceutical companies in the United States deploy these systems for preformulation polymorphism screening and batch consistency validation under FDA ICH Q1A mandates. The technique dominates installed base due to its ubiquity in stability-protocol design and regulatory submission requirements.
- Thermogravimetric Analysis:Quantifies mass change as a function of temperature or time, operating from ambient to 1,600°C depending on furnace configuration. Demand concentrates around Boston and San Francisco biopharma clusters where lyophilized biologic formulations require precise moisture-content validation for protein stability. The segment is expanding most quickly as lipid-nanoparticle drug delivery systems proliferate.
- Dynamic Mechanical Analysis:Characterizes viscoelastic properties of polymer coatings and excipient matrices under oscillatory stress. Specialized applications in modified-release tablet development justify capital investment despite narrower addressable market.
- Thermal Conductivity:Determines heat transfer coefficients for packaging materials and cold-chain validation studies. Emerging relevance in cell therapy logistics drives incremental adoption among contract research organizations.
Differential Scanning Calorimetry absorbs the bulk of installed capacity; Thermogravimetric Analysis is expanding most quickly.
End User:
Procurement authority and compliance burden vary sharply across customer types, with large pharmaceutical manufacturers demanding bundled validation services that contract research organizations often unbundle.
- Pharmaceutical Companies:Internal analytical departments at large drug developers in Germany and Switzerland prioritize dual-validated platforms for simultaneous FDA and EMA filings. Capital budgets accommodate high-resolution instrumentation with 21 CFR Part 11 software ecosystems.
- Contract Research Organizations:Outsourced analytical validation is accelerating across the San Francisco Bay Area and Boston corridors. CROs increasingly favor capital-light leasing arrangements with separate compliance documentation purchases, fragmenting traditional bundled procurement.
- Research Laboratories:Academic and government facilities emphasize modular architectures enabling technique reconfiguration without full instrument replacement.
- Academic Institutions:Training and method development applications drive demand for entry-level systems with expandable temperature ranges and software upgrade paths.
Pharmaceutical Companies command the largest share of premium instrument shipments; Contract Research Organizations are climbing the fastest as outsourced thermal characterization expands.
Application:
Regulatory filing requirements and manufacturing-stage timing determine which applications justify capital expenditure versus outsourced analytical support.
- Stability Testing:FDA-enforced ICH Q1A guidelines mandate thermal characterization for new molecular entities, compelling acquisition of compliant systems. European filers under EMA QWP recommendations harmonize protocols, creating dual-validation requirements.
- Quality Control:Batch release testing for commercial manufacturing demands high-throughput platforms with automated sampling and validated electronic records. Operational budgeting prioritizes uptime guarantees and rapid service response.
- Formulation Development:Preclinical-stage excipient compatibility and polymorphism screening require flexible method development capabilities with broad temperature ranges.
- Material Characterization:Polymer-excipient interaction studies and glass transition mapping support modified-release design, typically conducted on specialized high-temperature platforms.
Stability Testing anchors the largest installed base; Quality Control is gaining share fastest as commercial manufacturing scales expand.
Technology:
Instrument specification boundaries are blurring as hyphenated configurations combine multiple detection modalities in single workflows.
- Calorimetric Techniques:Encompass differential scanning and isothermal titration methods measuring enthalpic changes during phase transitions and binding events. Core to regulatory-mandated thermal characterization across United States and European filings.
- Structural Analysis:X-ray diffraction and spectroscopic coupling with thermal platforms enables simultaneous phase identification and stability assessment. Large pharmaceutical manufacturers in Germany adopt these integrated systems for impurity profiling.
- Phase Transition Analysis:Glass transition, melting point, and crystallization behavior mapping for amorphous solid dispersion design. Critical for bioavailability enhancement in poorly soluble drug candidates.
- Polymer Analysis:Viscoelastic and thermomechanical characterization of coating films and controlled-release matrices. Specialized niche serving modified-release formulation specialists.
Calorimetric Techniques retain the dominant installed position; Structural Analysis is expanding most quickly as hyphenated platform adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering in thermal instrumentation anchors the geographic distribution of pharmaceutical thermal analysis demand, with specialized calorimetry manufacturing concentrated in Bavaria and Baden-Württemberg feeding instrument supply chains worldwide.
United States
FDA-enforced ICH Q1A stability mandates drive differential scanning calorimetry acquisition across large pharmaceutical manufacturers. The agency's tightened guidelines for novel biologics compel investment in higher-resolution thermal platforms. The Boston-Cambridge biopharma cluster and San Francisco Bay Area corridor dominate replacement cycles for legacy systems.
Germany
EMA QWP stability recommendations impose analytical burdens comparable to FDA guidelines, compelling dual-validated platform procurement. German pharmaceutical manufacturers prioritize hyphenated thermal-mass spectrometry systems for impurity profiling. The Rhine-Main and Rhine-Ruhr industrial regions concentrate instrument deployment for polymer-excipient compatibility studies.
Switzerland
Swissmedic-aligned filing requirements harmonize thermal characterization protocols for transatlantic submissions. Basel-based biologics developers anchor demand for 21 CFR Part 11 compliant data-management workflows. The country's pharmaceutical manufacturing density supports premium instrument service contract expansion.
India
CDSCO stability guidelines and export-oriented manufacturing drive thermal analysis capacity investment across contract development organizations. Mumbai-Pune and Hyderabad pharmaceutical hubs underinvest in thermal analysis relative to formulation complexity. Local CDMOs face procurement risk from concentrated North American and European equipment supply.
Japan
PMDA quality guidelines mandate thermal characterization for new molecular entity submissions. Tokyo-Osaka pharmaceutical corridors deploy thermogravimetric analysis for lyophilized biologic moisture-content validation. Domestic instrument vendors compete with European OEMs through localized support infrastructure.
Pharmaceutical Thermal Analysis Market Competitive Landscape
Strategic partnerships dominate the current landscape as instrument vendors embed service contracts into long-term customer relationships. The market structure concentrates around North American and European OEMs with established compliance documentation capabilities. Three archetypes prevail: full-stack platform vendors bundling hardware with validated software ecosystems, specialized high-temperature calorimetry manufacturers, and modular architecture providers enabling technique reconfiguration. Geographic expansion and technology licensing represent the primary competitive vectors as vendors seek to penetrate underdeveloped analytical markets.
Among North American platform vendors, PerkinElmer and TA Instruments occupy positions emphasizing compliant data-management workflows and service infrastructure anchoring respectively. NETZSCH exemplifies the specialized high-temperature segment within European manufacturing. These three represent distinct strategic postures: software-integrated compliance, service-contract consolidation, and application-specific instrumentation depth.
| Leading Market Players |
|---|
| PerkinElmer |
| TA Instruments |
| Mettler-Toledo |
| Hitachi High-Technologies |
| NETZSCH |
| LECO Corporation |
| Rigaku |
| Setaram Instrumentation |
| Linseis |
| Others |
Value Network & Pricing Analysis
Large pharmaceutical manufacturers concentrated in the Boston-Cambridge and San Francisco Bay Area corridors negotiate consolidated vendor partnerships with embedded multi-year service contracts, anchoring a pricing model where compliance documentation and rapid response guarantees command substantial premiums over base hardware costs. This buyer concentration compresses procurement leverage for contract research organizations, which increasingly unbundle validation and maintenance purchases to regain pricing flexibility.
Pricing Analysis
Warranty and service bundling separates premium-tier offerings from standard configurations, with full-stack vendors embedding 21 CFR Part 11 validation workflows and Annex 11 qualification modules into enterprise pricing. Price differentiation rests on certification grade and geographic service density, with dual-validated platforms for simultaneous FDA and EMA filings commanding substantial premiums. Cost compression in the standard tier intensifies because modular architectures enable technique reconfiguration without full instrument replacement. Contract research organizations exhibit the highest price sensitivity, while German and Swiss biologics developers prioritize compliance assurance over capital expenditure minimization.
Supply Chain Analysis
Direct-to-OEM channels handle demand from large pharmaceutical manufacturers and specialized CROs, with authorized distributors serving smaller research laboratories and academic institutions requiring localized support infrastructure. Geographic supply concentrates in Germany, the United States, and Japan, with precision calorimetry manufacturing anchored in Bavaria and Baden-Württemberg feeding global instrument deployment. Raw material dependencies include high-purity sensor ceramics, precision furnace components, and specialized thermal analysis software licenses. Single-source vulnerability runs through concentrated noble gas supply chains for purge and protective atmospheres, with nitrogen, helium, and argon flow consistency critical to analytical reproducibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical thermal analysis is transitioning from monolithic platforms to modular architectures that enable technique reconfiguration without full instrument replacement, with hyphenated thermal-mass spectrometry systems displacing standalone calorimetry for impurity profiling workflows.
For Market Incumbents: Cement service contract consolidation by embedding compliance documentation and rapid response guarantees into multi-year agreements with large pharmaceutical manufacturers in Germany and Switzerland. Defend against modular architecture disruptors by acquiring specialized high-temperature calorimetry capabilities or licensing hyphenated detection technologies. Prioritize backward integration into precision sensor manufacturing to reduce exposure to ceramic component supply volatility. For New Entrants and Emerging Players: Contract research organizations in the San Francisco Bay Area represent the most penetrable channel partner type, with capital-light leasing arrangements and unbundled compliance documentation purchases creating entry points outside incumbent service ecosystems. Target Indian CDMO instrumentation upgrade cycles in Mumbai-Pune and Hyderabad, where thermal analysis capacity lags formulation complexity. Pursue white-label modular platform partnerships that enable technique reconfiguration without proprietary furnace manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized high-temperature calorimetry manufacturers with established polymer-excipient compatibility study applications in Germany and Switzerland. Long-term viability hinges on cell and gene therapy excipient characterization capabilities, where novel lipid-nanoparticle formulations challenge conventional thermal analysis boundaries. Watch for pharmacopeial standard revisions addressing cell therapy products as an inflection indicator for instrument validation protocol demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hyphenated Platform Integration | Combines thermal stability assessment with mass spectrometry detection for impurity profiling in German pharmaceutical labs. |
| Modular Architecture Development | Enables technique reconfiguration without full instrument replacement, serving academic and CRO capital constraints. |
| 21 CFR Part 11 Software Ecosystem Expansion | Addresses FDA enforcement of ICH Q1A stability mandates for new molecular entity submissions. |
| Service Contract Unbundling | Responds to San Francisco Bay Area CRO preference for transparent pricing and separate compliance documentation purchases. |
| Cell Therapy Excipient Characterization Capability | Closes specification gaps for lipid-nanoparticle and viral-vector formulations challenging conventional thermal analysis boundaries. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with analytical instrumentation product managers, pharmaceutical quality control directors, regulatory affairs specialists, and contract research organization procurement leads. FDA 510(k) submissions, EMA scientific advice letters, USP pharmacopeial revision notices, and ISO 11357 standard documentation provided methodological validation. Bottom-up instrument shipment data triangulated against top-down pharmaceutical R&D expenditure patterns across the analysis window.
Data-stream reconciliation across product type, end user, application, and technology dimensions shaped the analytical framework, with regional regulatory cluster variations modeled separately for FDA, EMA, PMDA, and CDSCO jurisdictions. CAGRs derived from instrument replacement cycle analysis, stability-testing guideline revision timelines, and biologics pipeline expansion trajectories. Forecast inputs incorporated lyophilized formulation proliferation rates and cell therapy manufacturing capacity buildouts.
Caveats apply where pharmacopeial standard lag for cell and gene therapy products, qualified thermal analyst scarcity, or legacy system data migration friction could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and biopharma cluster R&D concentration persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market