
 Global Rare Gases Market | 2026-2036
Global Rare Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rare Gases Market Foresight
Buyer concentration among semiconductor foundries is recalibrating contract structures across the rare gases supply base. Linde plc anchors long-term supply agreements with leading wafer manufacturers through captive helium extraction assets. Air Liquide S.A. differentiates via on-site gas generation systems integrated directly into fab operations. Messer Group GmbH competes through regional cylinder distribution networks serving mid-tier research institutes and specialty welding contractors.
Rare gases comprise the seven elements of Group 18—helium, neon, argon, krypton, xenon, and radon—characterized by complete valence electron shells rendering them chemically inert at standard conditions; industrial production relies on cryogenic air separation and natural gas helium recovery, yielding purities from 99.9% to 99.9999% depending on end-use specifications. Helium dominates volume flows due to irreplaceable roles in MRI magnet cooling and semiconductor process control, while krypton and xenon command premium pricing from concentrated demand in aerospace ion propulsion and high-performance insulation glazing. Electronics applications are outpacing legacy lighting segments as OLED manufacturing and extreme ultraviolet lithography drive neon and xenon offtake.
EPA enforcement of Clean Air Act emissions standards shapes domestic production facility permitting, while EMA and REACH protocols govern import certification for European healthcare and industrial users. FDA device regulations and ISO 13485 quality standards constrain medical imaging gas supply chains to documented batch purity and traceability. Stakeholders must monitor evolving export controls on helium reserves and assess captive versus merchant supply strategies before capacity commitments crystallize.
Market Dynamics
Semiconductor lithography node advancement below 3nm is compressing rare gas purity tolerances while concentrating demand among fewer wafer fabrication facilities with captive supply requirements.
Growth Catalysts
- EUV Lithography Expansion:Extreme ultraviolet scanners at Samsung and TSMC fabs consume neon and xenon in multi-thousand-liter quantities per system annually, locking in long-term offtake contracts.
- EU F-Gas Regulation Phase-Down:Mandated reductions in hydrofluorocarbon use for insulation glazing redirect specification engineers toward krypton-filled window units in commercial construction.
- Helium Stewardship Act Reserve Releases:US federal auctions of strategic helium reserves stabilize feedstock access for MRI magnet cooling and semiconductor process control applications.
Market Restraints
- Feedstock Concentration Risk:Over 40% of global helium derives from US Bureau of Land Management pipeline infrastructure and associated natural gas processing in the Hugoton-Panhandle complex.
- Cryogenic Energy Intensity:Air separation units require 0.4-0.6 kWh per cubic meter of rare gas extracted, exposing production economics to natural gas and electricity tariff volatility.
- Argon Substitution in Welding:Carbon dioxide-argon blends and active gas mixtures displace pure argon shielding in automotive fabrication, eroding legacy volume anchors.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor and display manufacturing attract rare gas distributors to establish Bengaluru and Hyderabad cylinder filling infrastructure.
- Spacecraft Ion Propulsion:Xenon thruster adoption by satellite constellation operators creates dedicated demand streams separate from terrestrial semiconductor cycles.
- On-Site Generation Systems:Membrane and pressure-swing adsorption units integrated at fab perimeters reduce logistics exposure and enable just-in-time krypton and neon delivery.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Specialized expertise in helium liquefaction and ultra-high vacuum systems concentrates among retiring cohorts at national laboratory facilities.
- REACH Documentation Burden:European chemical substance registration requires batch-level impurity characterization that extends certification timelines for imported xenon and krypton.
- Legacy Infrastructure Integration:Brownfield semiconductor fabs face physical constraints retrofitting high-purity gas distribution manifolds compatible with sub-10nm process requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rare Gases Market |
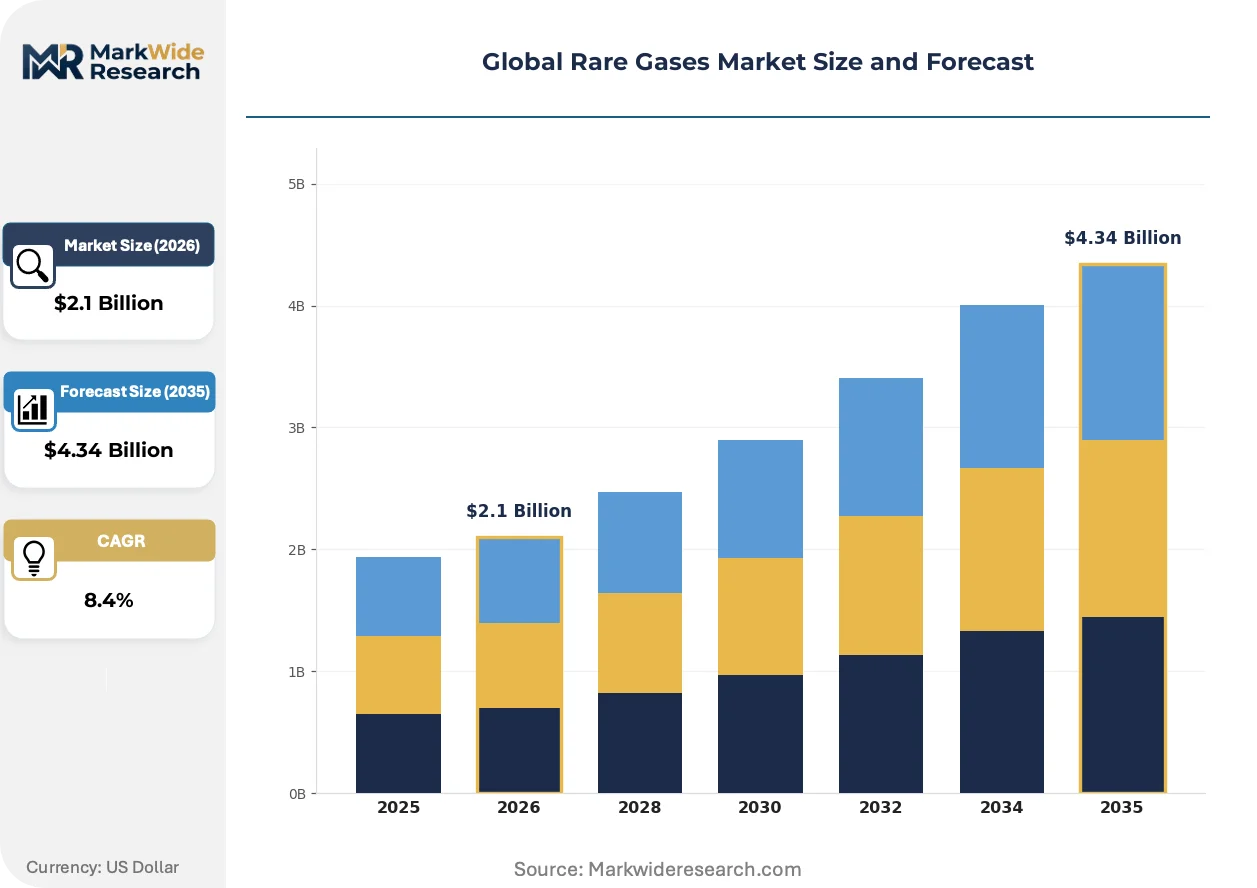
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helium, Neon, Argon, Krypton, Xenon, Radon Application: Lighting, Welding, Cryogenics, Electronics, Medical Imaging, Aerospace End User Industry: Semiconductor Fabrication, Healthcare Facilities, Research Institutes, Manufacturing Plants, Energy Producers, Defense Contractors Supply Method: Bulk Gas, Cylinder Gas, Cryogenic Liquid, Specialty Gas Mixtures |
| Companies Covered | Messer Group GmbH, Matheson Tri-Gas, Inc., Linde plc, Air Water Inc., Coregas Pty Ltd., Air Liquide S.A., Iwatani Corporation, Taiyo Nippon Sanso Corporation, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rare Gases Market Shifts & Advancements
Process gas delivery architectures are converging toward point-of-use purification, eliminating contamination risks from centralized bulk storage while enabling fab-scale rare gas recycling loops.
Closed-loop helium recovery systems are unifying liquefier technology with MRI magnet service protocols. GE Healthcare and Siemens Healthineers service divisions now specify integrated reliquefaction modules at hospital installations. This unifying architecture compresses helium loss rates from 30% annually toward single-digit percentages, restructuring long-term supply contracting toward service-inclusive models.
REACH authorization requirements for persistent organic pollutants intersect with F-Gas Regulation hydrofluorocarbon quotas to accelerate krypton adoption in triple-glazed building envelopes. German window fabricators report specification shifts in Passivhaus-certified residential projects. The regulatory overlay most affects Nordic and Alpine markets where thermal performance mandates exceed baseline EU requirements.
Consolidated procurement consortia among memory chip foundries are displacing individual fab gas purchasing. Samsung, SK Hynix, and Micron coordinate bulk neon and xenon tenders through shared specification committees, compressing supplier margins while demanding dedicated on-site storage infrastructure. This concentration is most visible in South Korea's Pyeongtaek and Yongin industrial corridors where three mega-fabs operate within 50 kilometers.
Global Rare Gases Market Segmentation
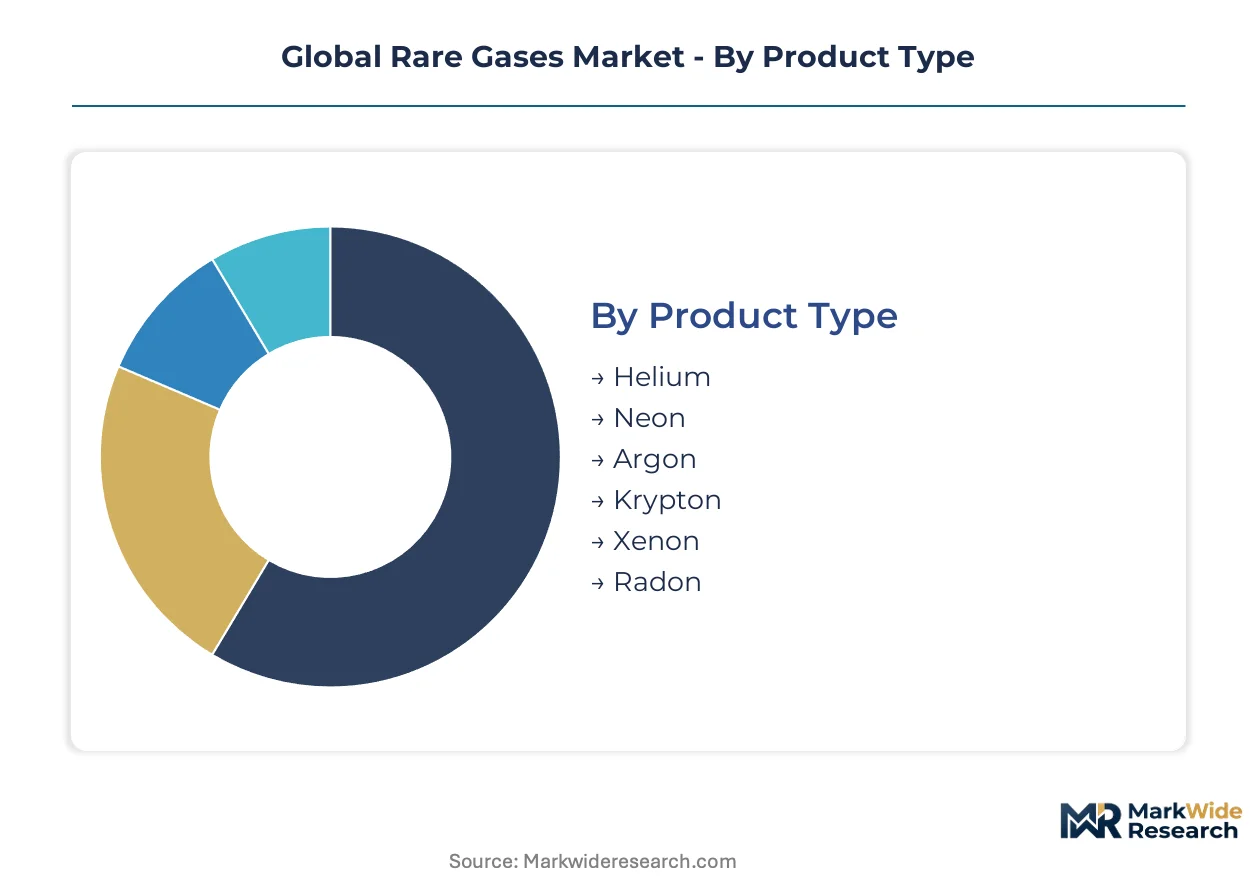
Rare gases command vastly different price points and purity specifications across end-use contexts. Segmentation reveals how helium extraction economics diverge from neon lithography demand, and why supply method selection determines margin capture.
Product Type:
Upgrade cycles in semiconductor lithography and MRI magnet cooling are redrawing volume hierarchies among the six rare gases, with node advancement below 3nm compressing purity tolerances for specific elements.
- Helium:The only element requiring natural gas feedstock extraction rather than air separation; irreplaceable for MRI magnet cooling at 4.2 Kelvin and semiconductor wafer handling. Demand concentrates at Samsung's Pyeongtaek campus and US hospital networks, constrained by BLM pipeline concentration risk.
- Neon:Cryogenic air separation yields 99.9999% purity grades essential for EUV laser excitation in lithography scanners. Ukrainian production disruption has accelerated captive extraction investments by South Korean and Japanese industrial gas majors.
- Argon:Highest-volume rare gas from steel mill air separation byproduct recovery; shielding gas applications in automotive fabrication face displacement by active gas mixtures.
- Krypton:Triple-glazed window insulation commands premium pricing in German Passivhaus construction; REACH and F-Gas Regulation alignment accelerates specification.
- Xenon:Ion propulsion thrusters for satellite constellations create demand separate from terrestrial semiconductor cycles; spacecraft-grade purity extends certification timelines.
- Radon:Trace radioactive decay product with negligible commercial volume; regulated as hazardous material in residential and occupational settings.
Volume placements concentrate in helium; the faster expansion belongs to xenon.
Application:
Cost tier stratification separates commodity welding gases from specialty electronics and medical grades, with purification overhead determining viable supply configurations.
- Electronics:EUV lithography and OLED manufacturing require point-of-use purification eliminating centralized bulk storage contamination risks. Samsung and TSMC fabs lock in multi-thousand-liter annual offtake contracts per scanner system.
- Medical Imaging:MRI magnet cooling demands 99.999% helium with documented batch traceability under FDA device regulations and ISO 13485 standards. GE Healthcare and Siemens Healthineers specify integrated reliquefaction modules compressing annual loss rates toward single-digit percentages.
- Cryogenics:Research superconducting magnets and particle accelerators consume liquid helium and neon in continuous boil-off configurations.
- Welding:Automotive fabrication shifts toward carbon dioxide-argon blends displacing pure argon shielding; eroding legacy volume anchors.
- Lighting:Incandescent and HID lamp demand contracts as LED and OLED technologies displace legacy segments.
- Aerospace:Satellite constellation operators adopt xenon thrusters for station-keeping maneuvers; dedicated demand streams decoupled from terrestrial industrial cycles.
Electronics commands premium pricing tiers; medical imaging sustains the most rigid contract structures.
End User Industry:
Customer type concentration among memory chip foundries is recalibrating procurement power across supply bases, with consolidated tenders displacing individual fab purchasing.
- Semiconductor Fabrication:Samsung, SK Hynix, and Micron coordinate bulk neon and xenon tenders through shared specification committees. South Korea's Pyeongtaek and Yongin corridors host three mega-fabs within 50 kilometers demanding dedicated on-site storage infrastructure.
- Healthcare Facilities:Hospital networks prioritize service-inclusive helium supply models integrating liquefier maintenance with magnet service protocols.
- Research Institutes:Mid-tier cylinder demand for spectroscopy and particle physics; Messer Group regional distribution networks serve this fragmentation.
- Manufacturing Plants:Steel mill argon byproduct recovery and automotive welding applications face substitution pressure from active gas mixtures.
- Energy Producers:Natural gas processing facilities with helium extraction assets anchor captive supply strategies.
- Defense Contractors:Aerospace ion propulsion and surveillance sensor applications; export-controlled procurement channels.
Semiconductor fabrication absorbs the highest absolute volumes; healthcare facilities generate the most predictable recurring revenue streams.
Supply Method:
Geography of demand relative to production assets determines viable delivery modes, with on-site generation investments accelerating in South Korean and Taiwanese industrial corridors.
- Bulk Gas:Pipeline delivery to clustered semiconductor fabs and steel complexes; requires proximity to air separation infrastructure.
- Cryogenic Liquid:Dewar and tanker distribution for MRI installations and research facilities; Linde and Air Liquide anchor long-term supply agreements through captive helium extraction assets.
- Cylinder Gas:Regional filling infrastructure serves fragmented research and specialty welding demand; Messer Group competes through distribution network density.
- Specialty Gas Mixtures:On-site generation systems using membrane and pressure-swing adsorption enable just-in-time krypton and neon delivery at fab perimeters.
Cryogenic liquid dominates value capture; specialty gas mixtures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean memory chip foundries concentrate neon and xenon procurement through consolidated tenders, while helium extraction economics tie production geography to natural gas basins rather than demand centers.
United States
BLM pipeline infrastructure and Hugoton-Panhandle natural gas processing deliver over 40% of global helium feedstock. EPA Clean Air Act enforcement shapes domestic production facility permitting timelines. Houston and Amarillo industrial corridors host extraction assets serving MRI magnet cooling and semiconductor process control applications.
South Korea
Samsung and SK Hynix operate leading memory chip foundries scaling rare gas consumption for EUV lithography below 3nm nodes. MFDS pharmaceutical regulations govern medical imaging gas import certification. Pyeongtaek and Yongin corridors host three mega-fabs within 50 kilometers demanding dedicated on-site storage infrastructure.
Germany
Passivhaus-certified residential construction accelerates krypton-filled triple-glazed window specification. ECHA REACH protocols and EU F-Gas Regulation alignment mandate batch-level impurity characterization for imported xenon. Bavarian and Baden-Württemberg industrial clusters anchor cryogenic air separation capacity serving Central European electronics manufacturing.
Japan
Tokyo Electron and Shin-Etsu Chemical drive neon purity requirements for domestic lithography equipment supply chains. METI industrial policy incentivizes captive helium extraction investments to reduce import dependency. Kyushu and Chubu regions concentrate semiconductor materials fabrication with integrated rare gas recycling infrastructure.
China
Domestic air separation capacity expansion targets electronics-grade neon and krypton for memory chip foundry localization under Made in China 2025. MEE environmental standards constrain cryogenic energy intensity at new production facilities. Yangtze River Delta and Pearl River Delta clusters integrate on-site gas generation systems at fab perimeters.
Global Rare Gases Market Competitive Landscape
North American producers anchor one tier; European and Asian specialists hold differentiated positions through captive extraction assets and on-site generation integration. The supply base concentrates around three to five integrated industrial gas majors with cryogenic infrastructure ownership. Two strategic archetypes dominate: vertically integrated extraction-to-distribution operators and regional cylinder specialists serving fragmented research demand. Competitive moves center on long-term offtake contracting with semiconductor foundries and point-of-use purification system deployment.
Among Germany-based operators, Messer Group GmbH exemplifies regional distribution network density serving mid-tier research institutes and specialty welding contractors. Japanese industrial gas majors including Taiyo Nippon Sanso Corporation and Iwatani Corporation occupy positions within the Asia-Pacific electronics supply tier. These entities represent geographic specialization archetypes rather than scale-driven consolidation plays.
| Leading Market Players |
|---|
| Messer Group GmbH |
| Matheson Tri-Gas, Inc. |
| Linde plc |
| Air Water Inc. |
| Coregas Pty Ltd. |
| Air Liquide S.A. |
| Iwatani Corporation |
| Taiyo Nippon Sanso Corporation |
| Air Products and Chemicals, Inc. |
| Others |
Supply & Pricing Matrix
BLM helium auction pricing cascades through semiconductor and medical imaging supply chains, compressing margins at merchant distributors while amplifying returns for captive extraction operators with direct pipeline access.
Pricing Analysis
Volume placements concentrate in bulk helium for MRI cooling; margin capture concentrates in specialty xenon and krypton for aerospace and insulation glazing. Three-tier pricing structure across semiconductor-grade, medical-grade, and industrial-grade certification levels separates EUV lithography neon from welding argon. Cost compression in standard-grade argon is intensifying because automotive fabrication shifts toward active gas mixtures. Research institutes exhibit highest price sensitivity; memory chip foundries with consolidated procurement show lowest sensitivity due to long-term offtake lock-ins.
Supply Chain Analysis
Dual-sourcing qualification requirements from Samsung and SK Hynix mandate redundant neon and xenon supplier approvals, extending certification timelines for new entrants. Production gravity centers on the United States for helium extraction, South Korea for semiconductor consumption, and Germany for cryogenic air separation equipment. Feedstock dependencies include natural gas helium recovery, cryogenic distillation energy inputs, and Ukrainian neon purification infrastructure. Single-source vulnerability concentrates in BLM pipeline infrastructure serving North American helium demand. Distribution runs through on-site generation systems at fab perimeters and cryogenic liquid tankers for medical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium extraction capacity constraints at BLM auction volumes prop pricing premiums, sustaining returns for incumbent producers with pipeline access while rationing supply to price-sensitive industrial segments.
For Market Incumbents: Anchor long-term supply agreements through dedicated on-site storage infrastructure at Pyeongtaek and Yongin semiconductor corridors. Deepen backward integration into natural gas helium recovery assets to offset BLM pipeline concentration risk. Prioritize certification investment for REACH batch-level documentation to defend European medical imaging market position against emerging Asian competitors. For New Entrants and Emerging Players: Membrane-based on-site generation systems offer entry into South Korean and Taiwanese fab perimeter gas supply without cryogenic infrastructure scale requirements. Target India's Bengaluru and Hyderabad cylinder filling infrastructure under PLI scheme incentives as the most penetrable geography. Pursue joint development agreements with satellite constellation operators for spacecraft-grade xenon thruster supply as a go-to-market angle decoupled from terrestrial semiconductor cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional cylinder distribution specialists with established Messer Group-type network density in fragmented European research markets. Long-term viability hinges on consolidation plays that aggregate mid-tier filling infrastructure into platforms capable of serving on-site generation retrofits. Watch for EU F-Gas Regulation enforcement intensity as the inflection signal determining krypton insulation glazing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Helium Extraction | Captive natural gas processing assets insulate margins from BLM auction volatility. |
| On-Site Generation System Deployment | Membrane units at Samsung and TSMC fabs reduce logistics exposure and enable just-in-time delivery. |
| REACH Batch Documentation Investment | ECHA compliance infrastructure opens European medical imaging procurement channels. |
| Long-Term Supply Agreement Structuring | Multi-thousand-liter annual offtake contracts with memory chip foundries lock in volume visibility. |
| Joint Venture for Satellite Xenon Supply | Spacecraft-grade purification partnerships with constellation operators diversify beyond terrestrial cycles. |
Research Methodology
Independent corroboration across cryogenic plant managers, semiconductor procurement leads at memory chip foundries, and medical imaging service engineers underwrites the qualitative findings. Primary interviews with air separation unit operators, distribution channel partners, and technical R&D directors at industrial gas majors combined with secondary validation from EPA enforcement records, ECHA REACH registration databases, SEC 10-K filings, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation converge on segment-level outputs.
Rate-of-change decomposition separates volume growth from pricing trajectory across the projection horizon. Segmentation dimensions modeled include rare gas element type, application tier, end-user industry concentration, and supply method configuration. CAGRs derive from installed base expansion in EUV lithography scanners, MRI magnet cooling demand, and spacecraft ion propulsion adoption. Industry-specific forecast inputs incorporate BLM helium reserve release schedules and South Korean mega-fab construction pipelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to Ukrainian neon purification infrastructure and unannounced regulatory amendments to EU F-Gas Regulation phase-down timelines. Forecasts reflect documented assumptions regarding semiconductor node advancement rates and natural gas processing economics. A model refresh is warranted upon material change in BLM pipeline utilization rates or South Korean memory chip capital expenditure announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Welding Gas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Syngas Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Noble Gas Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Gas Processing Market
Industrial Gases
Krypton Gas Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market