
 Resorcinol Market | 2026-2036
Resorcinol Market Size, Share, and Industry Trends Forecast 2026-2036
Resorcinol Market Intelligence
The gap between pharmaceutical-grade and industrial-grade resorcinol is shifting toward wider price spreads and divergent purity specifications. Sumitomo Chemicals leverages captive benzene supply chains to anchor high-purity output for European pharmaceutical buyers. Mitsui Chemicals Inc. competes on rubber-bonding specialization across Southeast Asian tire plants. Atul Ltd. dominates Indian domestic demand through backward integration into phenol derivatives.
Resorcinol is a dihydric phenol with the chemical formula C6H4(OH)2, typically produced via sulfonation of benzene followed by alkali fusion, yielding a crystalline solid melting at 110°C that functions primarily as a chemical intermediate and crosslinking agent. The adhesive segment sustains the largest volume pull from tire manufacturers requiring resorcinol-formaldehyde-latex bonding systems for steel-belt adhesion. The pharmaceutical application occupies premium margin pools through dermatological formulations and antiseptic compounds subject to pharmacopeial purity standards. The coating segment navigates slower growth as waterborne alternatives displace solvent-based resorcinol resins in some wood adhesive uses.
REACH registration requirements in Europe constrain non-compliant imports while EPA toxic substance reporting in the United States shapes domestic handling protocols. BIS certification in India governs import quality thresholds for industrial chemical grades. Stakeholders must monitor evolving phenol derivative regulations and tire sustainability mandates that will determine which purity tiers command priority investment.
Market Dynamics
Tire sustainability mandates and REACH chemical safety protocols are bifurcating the resorcinol supply base into compliant pharmaceutical-grade producers and cost-optimized industrial-grade suppliers serving rubber-bonding applications.
Growth Catalysts
- REACH registration compliance:European chemical safety mandates filter out non-compliant imports, creating protected margin pools for registered producers serving pharmaceutical and high-specification adhesive buyers.
- Steel-belt tire bonding:Southeast Asian tire manufacturers sustain volume demand for resorcinol-formaldehyde-latex systems as vehicle production scales across Thailand, Indonesia, and Vietnam.
- Benzene sulfonation process refinement:Continuous alkali fusion improvements reduce phenol derivative waste streams while yielding higher-purity crystalline output for dermatological applications.
Market Restraints
- Benzene feedstock volatility:Crude oil price swings transmit directly to resorcinol production economics, compressing margins for non-integrated processors lacking captive aromatics supply.
- Chinese supply concentration:Bulk industrial-grade output clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for global rubber adhesive formulators.
- Waterborne adhesive substitution:Emulsion polymer technologies displace solvent-based resorcinol resins in select wood bonding applications, constraining coating segment expansion.
Strategic Opportunities
- Indian domestic tire manufacturing:PLI scheme incentives for automotive component production expand addressable demand for adhesive-grade resorcinol among Mumbai and Chennai-based formulators.
- Pharmacopeial dermatology compounds:Antiseptic and topical therapeutic applications command premium pricing tiers as purity specifications tighten beyond industrial-grade thresholds.
- Dual carbon compliance in China:MEE emissions standards favor producers investing in closed-loop sulfonation waste recovery, advantaging early movers in Shandong chemical parks.
Industry Challenges
- Pharmaceutical certification timelines:USP and EP monograph compliance for dermatological grades requires 18-24 month validation cycles, locking working capital in qualification batches.
- Legacy phenol derivative integration:Rubber adhesive formulators face technical friction retrofitting waterborne resorcinol systems into existing solvent-based production lines without adhesion performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resorcinol Market |
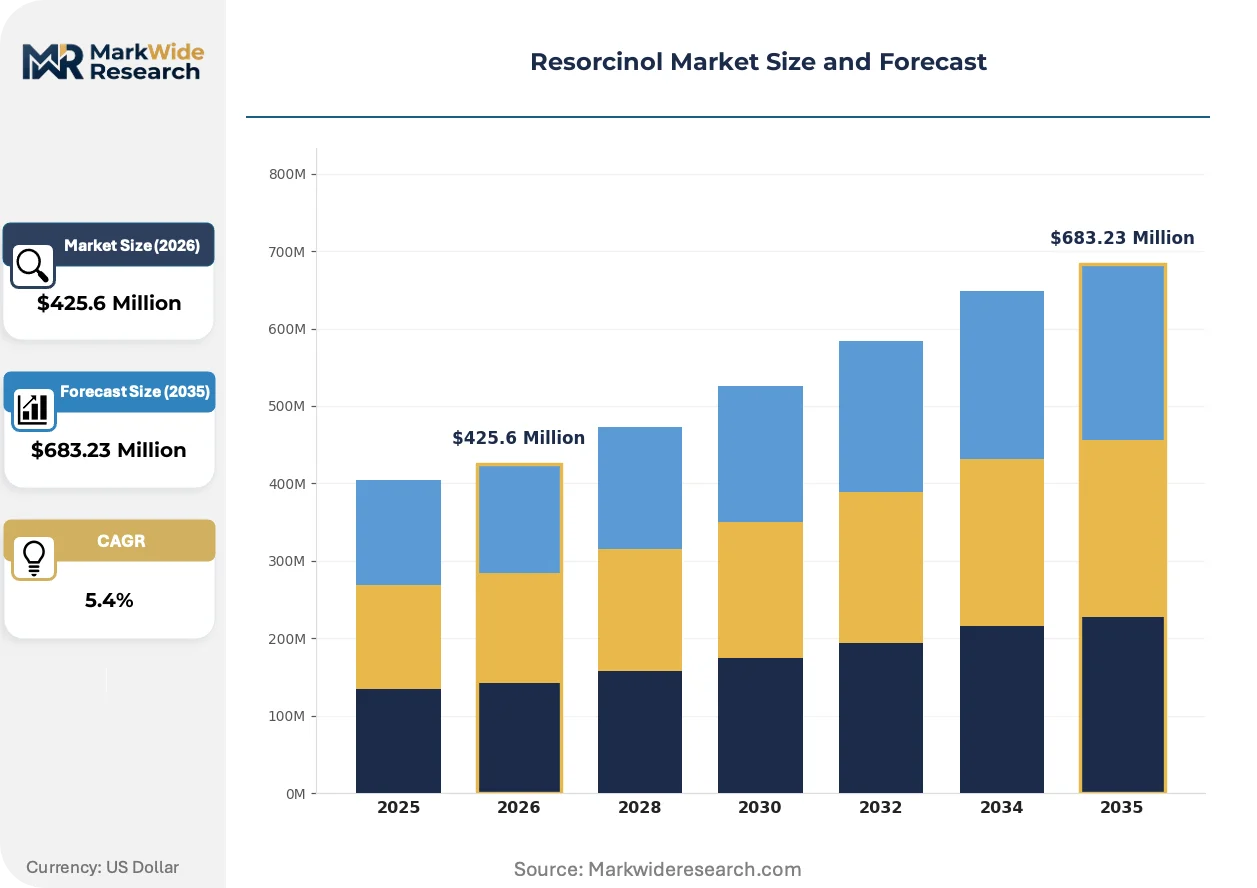
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $683.23 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin, Adhesive, Chemical Intermediary, Coating Application: Cosmetics, Pharmaceuticals, Agriculture, Rubber End User: Manufacturers, Retailers, R&D Institutions, Wholesalers Distribution Channel: Online, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Indspec Chemical Corporation, Sumitomo Chemicals, Mitsui Chemicals Inc., Atul Ltd., Lanxess, Akrochem Corporation, Alfa Aesar, Dynea AS, Jiangsu Zhongdan Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resorcinol Market Strategic Shifts & Innovations
Process intensification and regulatory stringency are reshaping competitive advantage toward integrated aromatics producers capable of certifying purity tiers across multiple end-use specifications simultaneously.
Continuous flow sulfonation reactor technology is decentralizing production scale economics away from large-batch alkali fusion plants. Mid-cap chemical processors in India and Germany adopt modular flow chemistry systems that slash solvent inventory and enable rapid grade switching between pharmaceutical and industrial purity tiers. This technology is decentralizing geographic production concentration by allowing smaller, regulated facilities to compete on specific purity segments rather than volume scale.
EU F-Gas Regulation amendments and REACH authorization sunset dates for certain phenol derivatives are compressing formulation windows for European adhesive manufacturers. Industrial users face reformulation costs or supply requalification as ECHA evaluates additional substance restrictions. Tire bonding compounders in Germany and Poland accelerate qualification of alternative crosslinking chemistries while maintaining resorcinol-formaldehyde systems for export markets with less stringent chemical safety protocols.
Specification-driven procurement now dominates pharmaceutical and automotive adhesive buying, displacing traditional spot-market volume contracting. Tier-one tire manufacturers in Japan and South Korea mandate batch-level purity certificates and chain-of-custody documentation, forcing traders to invest in analytical capabilities or exit premium segments. This behavioral shift is most visible in direct manufacturer-to-formulator relationships that bypass traditional chemical distributors for high-volume, specification-critical resorcinol grades.
Resorcinol Market Segmentation
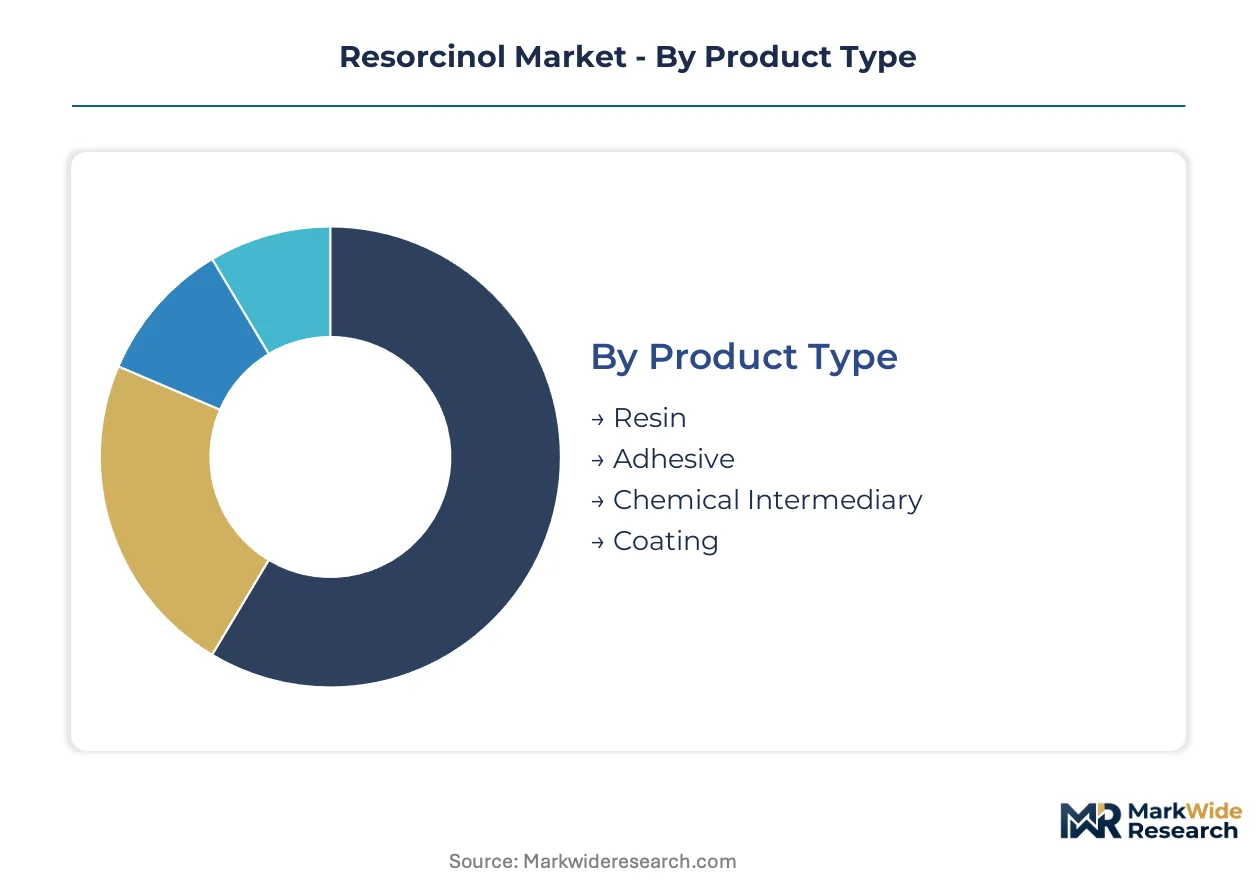
Resorcinol demand fragments across purity tiers and end-use specifications that dictate pricing power and regulatory compliance burdens. Segmentation reveals where pharmaceutical certification commands premiums versus where industrial-grade volumes anchor market stability.
Product Type:
Upgrade cycles in tire bonding chemistry and coating reformulation are pushing formulators toward higher-specification resorcinol derivatives that reduce solvent dependence.
- Resin:Phenol-formaldehyde condensation products with resorcinol modification deliver enhanced heat resistance for brake lining and foundry applications. Automotive OEMs in Germany and Japan specify these resins for under-the-hood components exposed to thermal cycling.
- Adhesive:Resorcinol-formaldehyde-latex systems create steel-to-rubber bonds in radial tire construction. Thai and Indonesian tire plants consume adhesive-grade volumes as passenger vehicle output scales across Southeast Asian manufacturing hubs.
- Chemical Intermediary:Feedstock for UV stabilizers, dyes, and specialty agrochemical synthesis. Pharmaceutical API manufacturers in India source high-purity intermediary grades for antiseptic compound production.
- Coating:Wood adhesive and corrosion-resistant formulations face displacement pressure from waterborne epoxy alternatives. European furniture manufacturers are reformulating away from solvent-based resorcinol resins under ECHA substance evaluations.
Volume placements concentrate in Adhesive; the faster expansion belongs to Chemical Intermediary as pharmaceutical synthesis demand climbs.
Application:
Cost-tier stratification separates pharmacopeial-grade buyers willing to absorb certification premiums from commodity purchasers optimizing per-kilogram economics.
- Cosmetics:Hair dye formulations and skin-lightening compounds utilize resorcinol derivatives at regulated concentration limits. Brazilian and South Korean cosmetic formulators drive demand for low-impurity grades meeting ANVISA and MFDS cosmetic safety standards.
- Pharmaceuticals:Antiseptic, topical anti-infective, and dermatological preparations require USP or EP monograph compliance. CDSCO in India and FDA in the United States enforce batch-level purity documentation that extends qualification timelines.
- Agriculture:Fungicide and plant growth regulator synthesis consumes technical-grade resorcinol. Chinese agrochemical manufacturers in Jiangsu province represent the primary demand cluster for this application tier.
- Rubber:Vulcanization acceleration and steel-cord adhesion dominate industrial consumption. Japanese tire manufacturers specify rubber-grade resorcinol with controlled moisture content for automated mixing lines.
Margin capture peaks in Pharmaceuticals; Rubber sustains the deepest volume base across the forecast window.
End User:
Customer-type concentration shapes procurement behavior, with integrated manufacturers bypassing distributors for specification-critical grades while smaller formulators rely on trader networks.
- Manufacturers:Tire plants, adhesive compounders, and pharmaceutical API producers purchase direct under annual contracts. Sumitomo Chemicals and Mitsui Chemicals serve these accounts with dedicated technical service teams.
- Retailers:Specialty chemical distributors stock industrial-grade resorcinol for smaller rubber processors and coating formulators. Indian domestic retailers face BIS certification requirements for import sourcing.
- R&D Institutions:Universities and corporate research centers procure gram-to-kilogram quantities for novel polymer synthesis. German and Swiss academic buyers prioritize EP-grade material for publication-grade reproducibility.
- Wholesalers:Bulk traders handle spot-market volumes for non-contracted industrial demand. Chinese wholesalers in Shandong province arbitrage price differentials between domestic and export markets.
Procurement is shifting toward direct manufacturer relationships; wholesaler intermediation is compressing to commoditized industrial grades.
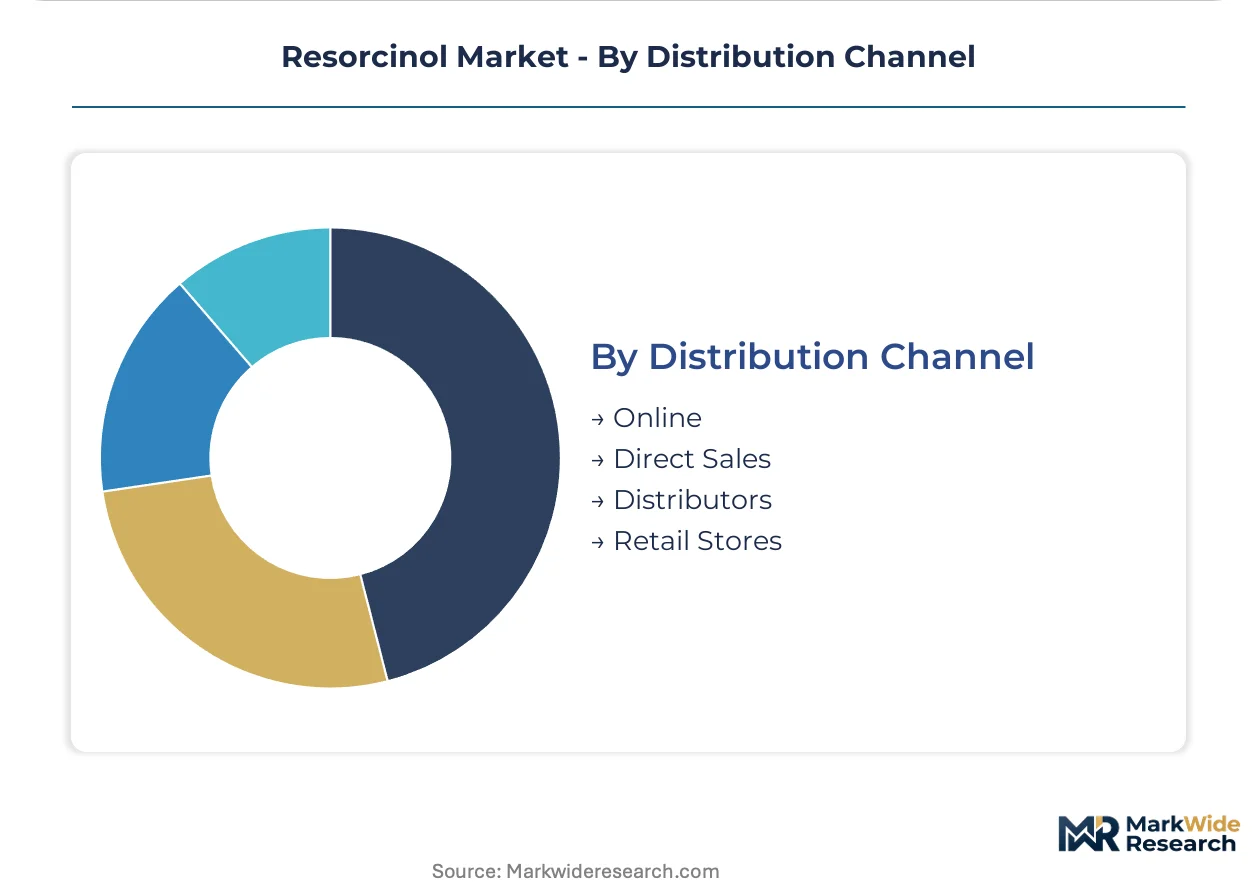
Distribution Channel:
Supply concentration in East Asian production clusters dictates logistics-heavy distribution architectures that favor bulk shipment modes.
- Online:E-procurement platforms serve small-volume R&D and specialty chemical buyers. Alibaba and specialty chemical marketplaces connect Indian formulators with Chinese producers for trial-batch quantities.
- Direct Sales:Long-term supply agreements link major tire manufacturers to integrated resorcinol producers. Bridgestone and Michelin procurement teams negotiate directly with benzene-integrated suppliers for adhesive-grade volumes.
- Distributors:Regional chemical distributors manage inventory and customs clearance for mid-tier manufacturers. Brenntag and Univar Solutions maintain European pharmaceutical-grade stocks with chain-of-custody documentation.
- Retail Stores:Limited to laboratory supply outlets serving academic and small-scale industrial users. Fisher Scientific and VWR International stock analytical-grade resorcinol for North American research institutions.
Direct Sales channels capture the largest value flow; Online penetration is climbing fastest among R&D and emerging-market small formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors the heaviest concentration of resorcinol manufacturing capacity, with chemical parks in Zibo and Dongying hosting sulfonation-based production lines serving Asian rubber adhesive formulators.
China
Jiangsu and Shandong provinces generate the bulk of industrial-grade resorcinol for tire bonding applications. MEE emissions standards enforce closed-loop waste recovery systems at chemical parks. Zibo's industrial cluster is retrofitting alkali fusion plants to meet dual carbon compliance timelines.
United States
Gulf Coast petrochemical corridors supply benzene feedstock to specialty chemical processors serving domestic tire manufacturers. EPA toxic substance reporting shapes handling protocols for resorcinol-formaldehyde adhesive compounders. Texas-based rubber chemical distributors manage inventory for Southeast Asian tire plant supply chains.
Germany
Rhine-Ruhr chemical complexes host REACH-registered producers supplying pharmaceutical-grade material to European dermatology formulators. ECHA authorization reviews for phenol derivatives compress formulation windows for adhesive manufacturers. Leverkusen and Ludwigshafen clusters are qualifying alternative crosslinking chemistries for export markets.
India
Maharashtra and Gujarat house backward-integrated phenol derivative producers serving domestic tire manufacturing expansion. BIS certification governs import quality thresholds for industrial chemical grades. Mumbai-based adhesive compounders leverage PLI scheme incentives for automotive component production.
Japan
Kansai region chemical producers specialize in rubber-bonding grade resorcinol with controlled moisture specifications for automated tire mixing lines. METI industrial standards coordinate with REACH-equivalent chemical safety protocols. Osaka-based manufacturers negotiate direct supply agreements with Bridgestone and Sumitomo Rubber for steel-belt adhesion systems.
Resorcinol Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tiers, with pharmaceutical-grade specialists capturing protected margin pools while industrial-grade suppliers compete on benzene feedstock economics. The supply base bifurcates into REACH-registered European and Japanese producers versus cost-optimized Chinese manufacturers serving rubber-bonding volumes. Three archetypes dominate: integrated aromatics majors with captive benzene supply, mid-cap specialty chemical processors with modular flow chemistry capabilities, and regional distributors managing spot-market industrial grades. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers seeking phenol derivative integration or tire manufacturer direct supply relationships.
Within the integrated aromatics tier, Sumitomo Chemicals and Mitsui Chemicals occupy positions anchored by upstream benzene control, while Atul Ltd. exemplifies the regional specialist archetype through domestic Indian market penetration. Jiangsu Zhongdan Group Co., Ltd. represents the scale-driven Chinese industrial-grade segment concentrated in Shandong and Jiangsu chemical parks. These three company groupings illustrate the geographic and tier-based stratification shaping procurement behavior across pharmaceutical and rubber adhesive end uses.
| Leading Market Players |
|---|
| Indspec Chemical Corporation |
| Sumitomo Chemicals |
| Mitsui Chemicals Inc. |
| Atul Ltd. |
| Lanxess |
| Akrochem Corporation |
| Alfa Aesar |
| Dynea AS |
| Jiangsu Zhongdan Group Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Benzene feedstock costs cascade through resorcinol production tiers, with captive aromatics supply anchoring margin protection for integrated producers while spot-market benzene exposure compresses returns for non-integrated processors serving rubber-bonding formulators in Thailand and Indonesia.
Pricing Analysis
Yield-based pricing anchors pharmaceutical-grade contracts, where dermatological purity certifications command premiums tied to batch-level USP and EP monograph compliance. Three-tier pricing structure across pharmaceutical, adhesive-grade, and technical tiers separates Sumitomo Chemicals' high-purity output from Chinese industrial-grade suppliers. Cost compression in adhesive-grade segments intensifies because Shandong producers arbitrage benzene price differentials into export markets. Rubber manufacturers exhibit highest price sensitivity, while pharmaceutical API buyers absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Container freight rates from Shandong ports to Southeast Asian tire plants directly influence landed cost competitiveness for adhesive-grade volumes. Supply concentrates in China, Japan, and India, with benzene, sulfuric acid, and caustic soda as critical inputs. Single-source vulnerability clusters in Jiangsu province sulfonation capacity, where MEE emissions enforcement could constrain export availability. Distribution runs through direct manufacturer-to-formulator channels for specification-critical grades, with regional distributors handling spot-market industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with upstream benzene supply control and downstream tire manufacturer direct relationships as the decisive levers separating margin-protected incumbents from commodity-exposed competitors.
For Market Incumbents: Hedge benzene price volatility through captive aromatics supply or long-term feedstock offtake agreements with Gulf Coast refiners. Accelerate REACH registration renewals ahead of ECHA phenol derivative sunset reviews to defend pharmaceutical-grade margin pools against emerging Indian competitors. Prioritize technical service embedding with Bridgestone and Michelin procurement teams to lock in steel-belt bonding specification adherence. For New Entrants and Emerging Players: Launch via modular flow chemistry systems serving R&D institutions and specialty pharmaceutical synthesis houses in Germany and Switzerland, where gram-scale EP-grade procurement tolerates premium pricing. Target Indian domestic tire manufacturing expansion under PLI scheme incentives, where adhesive-grade demand outpaces Atul Ltd.'s current capacity. Penetrate through analytical-grade certification partnerships with laboratory supply distributors bypassing established bulk chemical channels. For Investors and Strategic Acquirers: ECHA authorization timeline acceleration for resorcinol derivatives is the leading indicator that regulatory compliance capacity will command acquisition premiums. Five-to-ten-year viability favors integrated aromatics majors with pharmaceutical certification infrastructure over pure-play industrial-grade producers exposed to Chinese supply gluts. Monitor BIS import threshold tightening in India as the signal for domestic backward-integrated phenol derivative assets to appreciate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzene Supply | Captive aromatics feedstock insulates margin structure from crude oil price transmission volatility. |
| REACH Registration Renewal Investment | Extended pharmaceutical-grade market access in Germany and Poland depends on ECHA compliance maintenance. |
| Modular Flow Chemistry Adoption | Mid-scale Indian and German processors gain rapid grade-switching capability between purity tiers. |
| Direct Tire Manufacturer Supply Agreements | Bypassing distributor intermediation locks in volume commitments from Thai and Indonesian rubber plants. |
| Pharmacopeial Certification Expansion | USP and EP monograph qualification opens premium dermatology and antiseptic compound segments. |
Research Approach
Multi-period observation of benzene price spreads, REACH registration timelines, and tire production capacity additions anchored the trend analysis, supplemented by interviews with plant managers at sulfonation facilities, procurement leads at Japanese tire manufacturers, distribution channel partners in Indian chemical parks, and technical R&D directors at adhesive compounders. Customs and trade data from China and India, Cefic chemical industry reports, and SEC 10-K disclosures from integrated aromatics majors provided secondary validation. Bottom-up volume modeling triangulated against top-down value projections.
Input-output matrices mapped benzene feedstock availability through sulfonation capacity utilization rates to end-use demand across pharmaceutical, rubber, and coating segments. Segmentation dimensions included purity grade tier, end-use industry application, and regional production hub concentration. CAGRs derived from regression analysis of historical price-volume relationships and forward capacity expansion announcements. Forecast inputs incorporated MEE emissions enforcement intensity in Shandong and PLI scheme disbursement velocity in Maharashtra.
Feedstock price spikes, regulatory authorization delays, and tire sustainability mandate acceleration are the dominant revision risks that could compress or extend projected growth trajectories. Forecasts reflect documented assumptions about benzene supply continuity and REACH compliance maintenance. Stakeholders should weight assumptions against their own operating context and benzene procurement exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hypophosphorous Acid Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
China Amines Market
Chemicals
Global Lactate Salts Market
Chemicals
Global Butanediol Market
Chemicals
Industrial Odor Management Market
Chemicals
Deicing Fluid Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Allyl Chloride Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Fine Chemicals Market
Chemicals
Caustic Soda Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
India Methanol Market
Chemicals
Xanthates Market