
 Ethanolamine Market | 2026-2036
Ethanolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Ethanolamine Market Intelligence
Green surfactant chemistry is reconfiguring ethanolamine formulation standards across home care and industrial cleaning. BASF SE leverages its integrated ethylene oxide-ethanolamine chain to sustain cost-advantaged positions in European personal care supply. Dow anchors North American supply security through Gulf Coast manufacturing scale and captive ethylene oxide sourcing. Nouryon competes on specialty amine derivatives that command premium positioning in pharmaceutical-grade triethanolamine segments.
Ethanolamines comprise amino alcohols produced via ethylene oxide ammonolysis, with monoethanolamine, diethanolamine, and triethanolamine differing in amine-to-alcohol stoichiometry and subsequent functionality; these compounds serve primarily as pH regulators, emulsifiers, and gas-treatment absorbents across process industries. Monoethanolamine dominates volume through its role in gas sweetening and agrochemical intermediates, while triethanolamine captures disproportionate margin contribution from personal care and metalworking fluid formulations where cosmetic-grade certification commands price premiums. The detergents application segment leads absolute consumption, though pharmaceutical-grade specifications represent the fastest-growing qualification tier as USP and EP monograph compliance becomes mandatory for topical formulation excipients.
EPA New Chemicals Program reviews and REACH substance evaluation shape product entry barriers, with diethanolamine derivatives facing heightened scrutiny under California Proposition 65 listing protocols that restrict cosmetic formulations. OSHA permissible exposure limits and ECHA harmonized classification obligations compel manufacturers to invest in closed-system handling and purity upgrades. Stakeholders must monitor evolving nitrosamine impurity thresholds across pharmaceutical and personal care applications, as regulatory tightening in multiple jurisdictions will determine which producers retain formulation access versus face qualification exclusion.
Market Dynamics
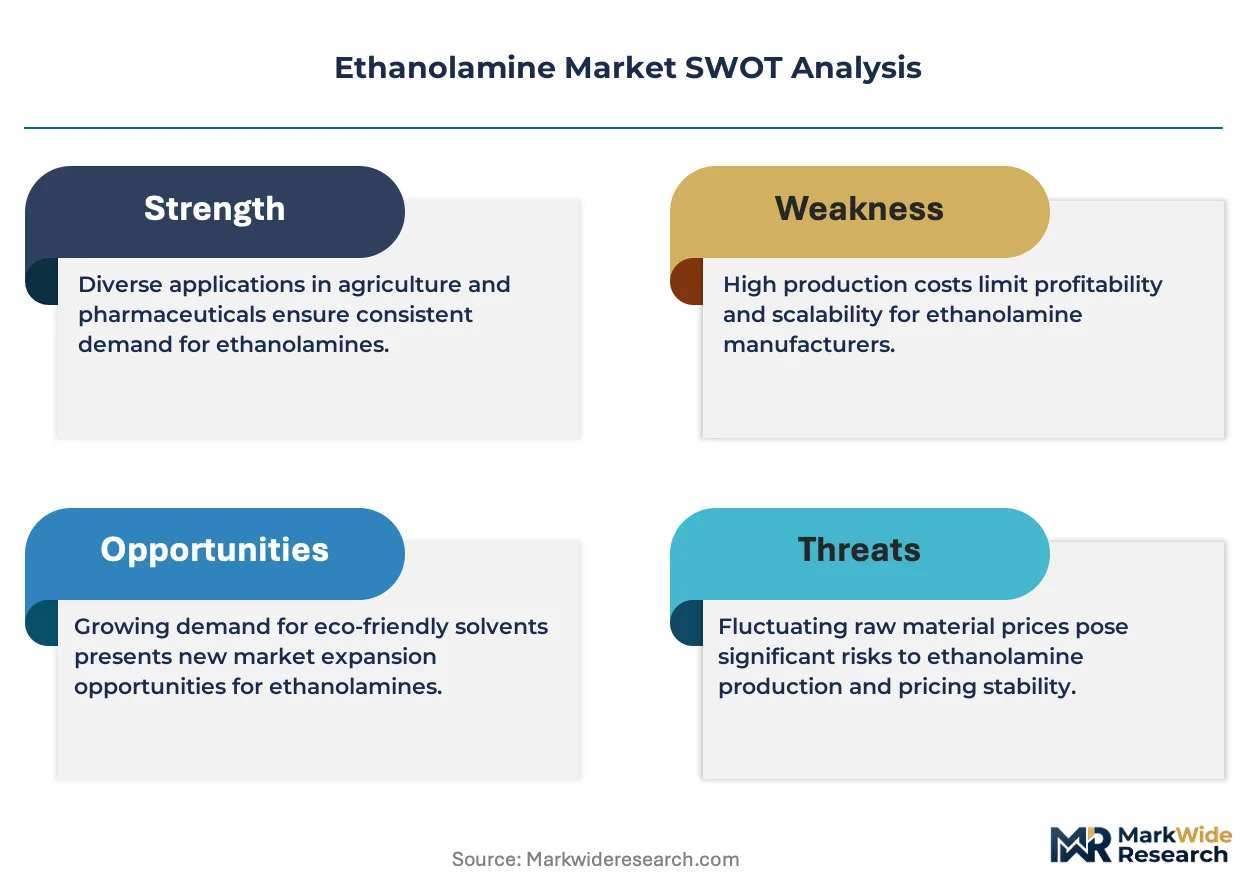
Ethylene oxide feedstock concentration in Gulf Coast and Yangtze River clusters is compressing margin buffers for non-integrated producers while REACH substance evaluation and EPA toxicity reviews simultaneously tighten purity thresholds across pharmaceutical and personal care applications.
Growth Catalysts
- Gas sweetening infrastructure buildout:Carbon capture mandates in Canada and Germany are accelerating monoethanolamine demand for acid gas removal systems in power generation and natural gas processing facilities.
- REACH registration tiering:The European Chemicals Agency's substance evaluation protocols are disqualifying low-purity imports, creating qualification moats for EU-registered producers serving cosmetic-grade triethanolamine segments.
- Agrochemical intermediate expansion:Glyphosate and herbicide manufacturing in China's Sichuan and Jiangsu provinces is anchoring regional ethanolamine consumption through captive ethylene oxide supply chains.
Market Restraints
- Ethylene oxide supply concentration:Feedstock production clusters on the US Gulf Coast and China's eastern seaboard expose non-integrated processors to transport cost penalties and force majeure vulnerability.
- California Proposition 65 friction:Diethanolamine's listing as a chemical of concern restricts cosmetic formulation access, forcing reformulation costs on personal care manufacturers serving the California market.
- Alkanolamine substitution in gas treatment:Methyl diethanolamine and sterically hindered amines are displacing conventional ethanolamines in selective hydrogen sulfide removal applications.
Strategic Opportunities
- Pharmaceutical-grade certification tier:USP and EP monograph compliance for topical excipients remains underpenetrated outside BASF's Ludwigshafen and Dow's Freeport operations.
- Green surfactant chemistry convergence:Biosourced ethylene oxide and renewable ammonia integration is opening qualification pathways for EU Green Deal-aligned home care formulations.
- Closed-system handling services:OSHA permissible exposure limit compliance is creating aftermarket revenue streams for engineering firms retrofitting metalworking fluid blending operations.
Industry Challenges
- Nitrosamine analytical capability gaps:Pharmaceutical and personal care buyers now require sub-ppm impurity documentation that exceeds standard QC infrastructure at commodity ethanolamine plants.
- Dual-use chemical licensing complexity:Triethanolamine's scheduled precursor status under international chemical weapons conventions adds customs clearance friction for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethanolamine Market |
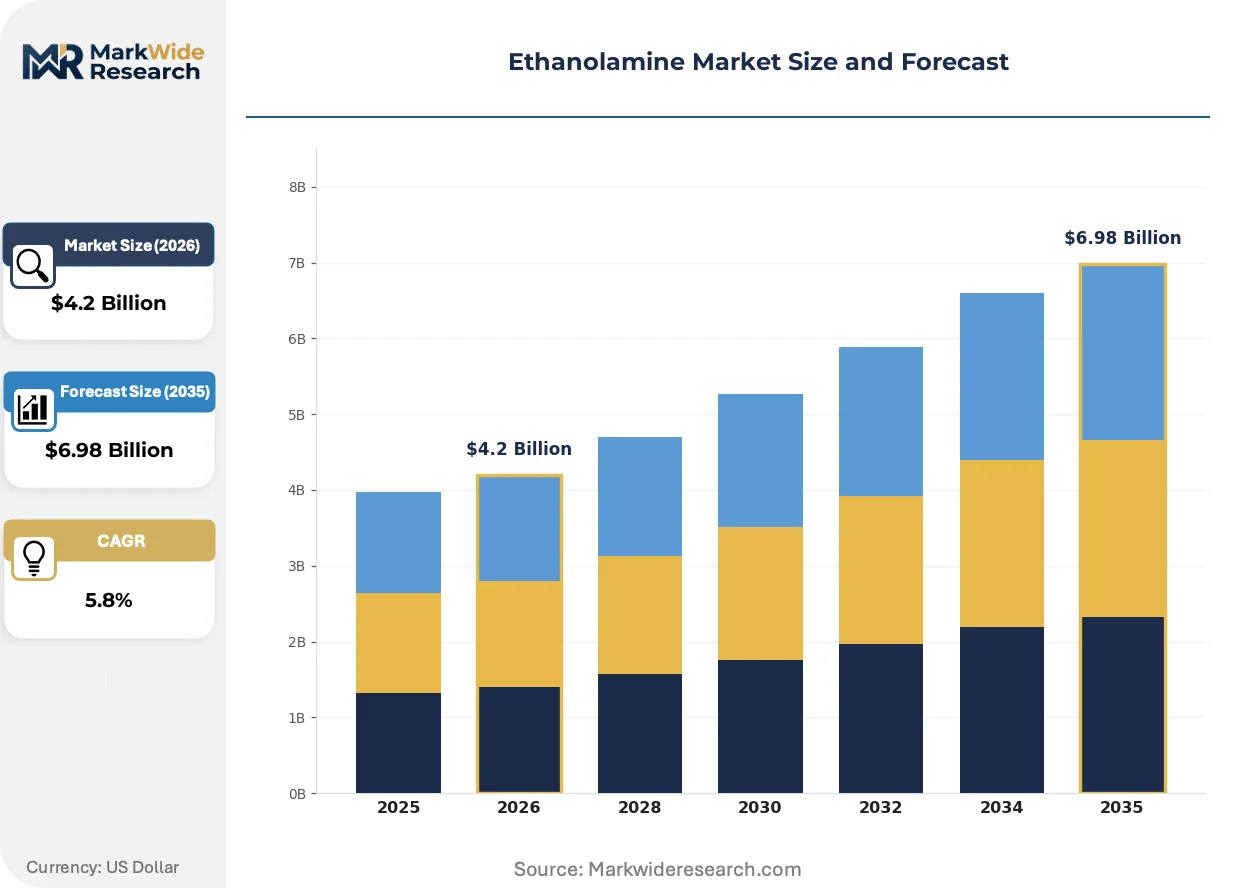
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoethanolamine, Diethanolamine, Triethanolamine, Ethanolamine Blends Application: Detergents, Personal Care Products, Pharmaceuticals, Agriculture End User: Chemical Industry, Agriculture Sector, Manufacturing, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Huntsman Corporation, Nouryon, Dow, LyondellBasell Industries N.V., Akzo Nobel N.V., BASF SE, SABIC, Nippon Shokubai Co., Ltd., INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethanolamine Market Strategic Shifts & Innovations
Formulation science and regulatory chemistry are compressing the viable specification window for ethanolamine products, forcing simultaneous investment in purity upgrades and green chemistry alternatives across the supply base.
Membrane-based ethylene oxide purification is collapsing the cost differential between standard and high-purity ethanolamine grades. Personal care compounders in Germany and South Korea are adopting membrane-refined feedstocks to preempt REACH authorization requirements. The technology is collapsing premium pricing power for legacy distillation-based producers serving cosmetic certification tiers.
EPA's evolving New Chemicals Program reviews under the Toxic Substances Control Act are extending diethanolamine derivative approval timelines by twelve to eighteen months. Industrial cleaning formulators are accelerating triethanolamine substitution to bypass review backlogs. Metalworking fluid blenders in Michigan and Ohio are most affected, with several reformulating to eliminate DEA-based corrosion inhibitors entirely.
Specification-driven procurement consolidation is concentrating ethanolamine buying among integrated home care multinationals with in-house toxicology capabilities. Regional distributors and toll blenders are losing formulation access as BASF and Nouryon establish direct supply relationships with Unilever and Henkel. The shift is most visible in Western European detergent manufacturing, where centralized purchasing has eliminated spot market participation for mid-tier surfactant houses.
Ethanolamine Market Segmentation
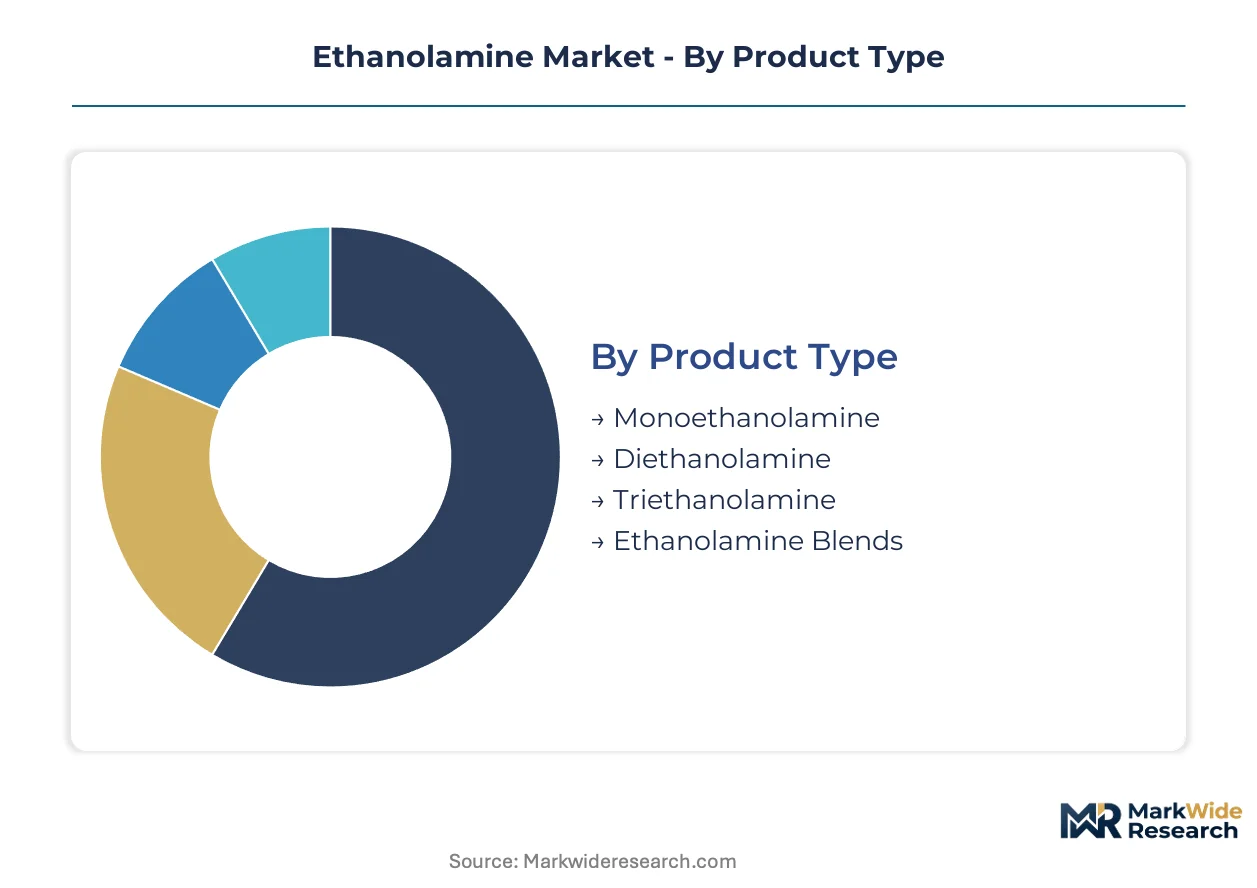
Ethanolamine segmentation reveals how product chemistry, application requirements, and regulatory thresholds create distinct commercial tiers. Buyers sort across these dimensions based on purity specifications, volume scale, and end-use qualification burdens.
Product Type:
Product chemistry determines functional versatility and margin structure across gas treatment, personal care, and agrochemical end-uses.
- Monoethanolamine:Primary amine with one hydroxyl group serves acid gas absorption in natural gas processing and carbon capture systems. Demand concentrates in Alberta's oil sands upgraders and Germany's power plant retrofits where post-combustion capture mandates are accelerating.
- Triethanolamine:Tertiary amine with three hydroxyl groups functions as pH buffer and emulsifier in cosmetic formulations and metalworking fluids. Personal care compounders in South Korea and France are driving pharmaceutical-grade qualification requirements that command substantial price premiums over industrial grades.
- Diethanolamine:Secondary amine intermediate faces formulation restrictions under California Proposition 65 protocols, limiting cosmetic access while sustaining demand in herbicide synthesis.
- Ethanolamine Blends:Custom ratios optimize performance in specialized gas-treatment and surfactant applications where single-species chemistry underperforms.
Monoethanolamine commands the established base. The steepest expansion runs through triethanolamine pharmaceutical-grade certification.
Application:
Application segmentation tracks how downstream formulation science and regulatory chemistry reshape procurement priorities across consumer and industrial markets.
- Detergents:Surfactant manufacturing represents the largest volume outlet, with ethanolamines serving as neutralizing agents and foam stabilizers in laundry and dish formulations.
- Personal Care Products:Cosmetic-grade triethanolamine functions as emulsifier and pH adjuster in skincare and haircare, with REACH registration and USP compliance now mandatory for European and North American supply.
- Pharmaceuticals:Topical excipient applications demand sub-ppm nitrosamine documentation and EP monograph adherence, creating qualification barriers that favor integrated producers with analytical capabilities.
- Agriculture:Glyphosate and herbicide intermediate synthesis in China's Sichuan province anchors regional consumption through captive ethylene oxide supply chains.
Detergents anchor volume throughput. Pharmaceuticals are climbing the fastest as excipient qualification tightens across multiple jurisdictions.
End User:
End-user categories reflect how technical sophistication and regulatory exposure differentiate procurement behavior across supply chain tiers.
- Chemical Industry:Integrated surfactant and amine derivative manufacturers purchase bulk volumes for downstream formulation, with specification requirements varying by end-market exposure.
- Agriculture Sector:Pesticide and herbicide producers in Jiangsu and Sichuan provinces drive regional demand concentration through ethylene oxide-integrated manufacturing complexes.
- Manufacturing:Metalworking fluid blenders and industrial cleaners represent fragmented mid-tier demand with varying purity requirements.
- Construction:Cement grinding aids and concrete admixtures utilize ethanolamine salts for performance enhancement in regional building material markets.
The chemical industry holds the volume foundation. Agriculture is gaining share fastest as Chinese agrochemical capacity expands.
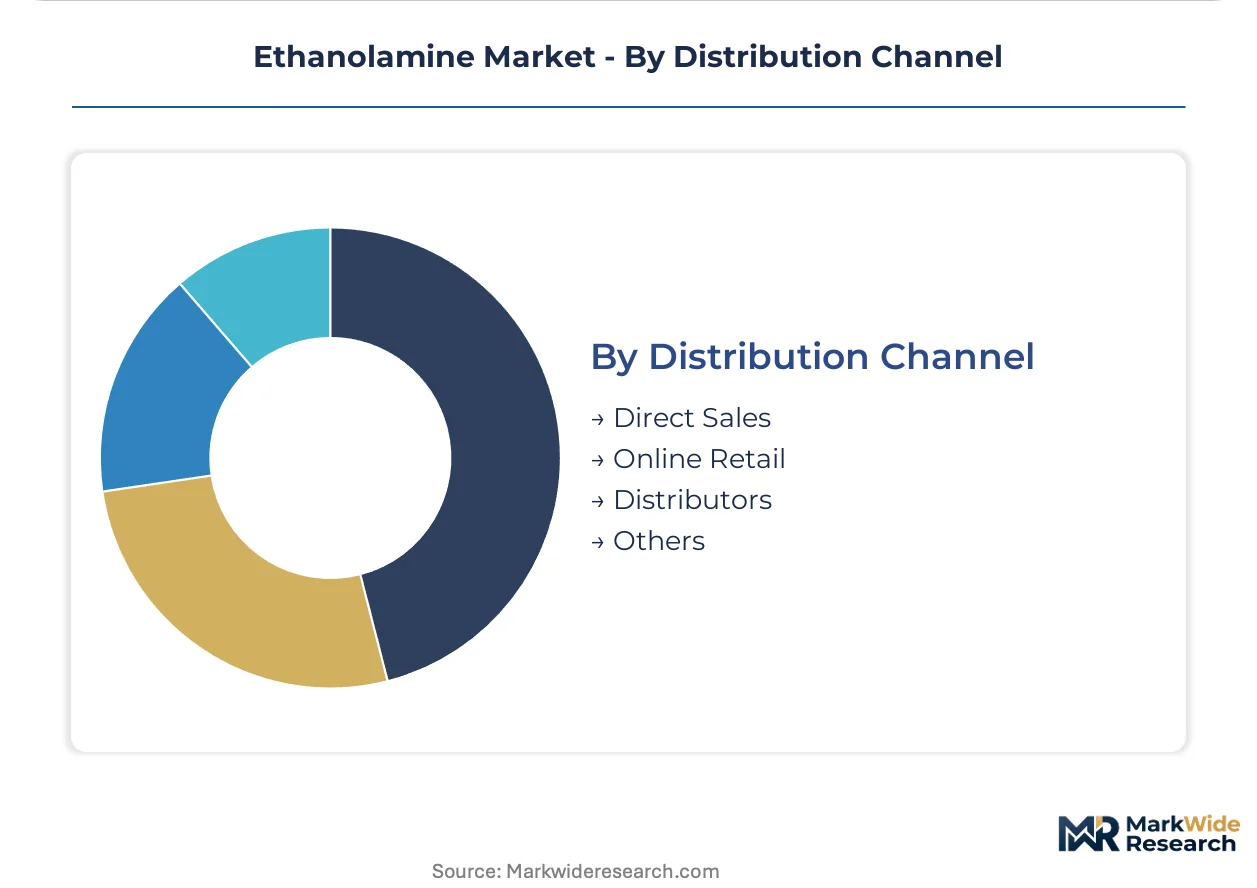
Distribution Channel:
Channel structure reveals how specification complexity and regulatory documentation are consolidating supply relationships away from spot-market intermediaries.
- Direct Sales:Integrated producers like BASF and Dow maintain direct relationships with Unilever and Henkel for detergent and personal care supply, eliminating distributor margins for qualified volumes.
- Distributors:Regional chemical distributors serve mid-tier manufacturers lacking toxicology capabilities, though REACH documentation requirements are squeezing their formulation access.
- Online Retail:E-procurement platforms capture small-volume industrial and laboratory demand with limited regulatory complexity.
- Others:Toll blending arrangements and contract manufacturing handle specialized formulations requiring custom ethanolamine derivatives.
Direct sales dominate qualified supply. Distributors face the steepest pressure as documentation burdens concentrate buying power with integrated multinationals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese ethanolamine production flows primarily to detergent and agrochemical buyers across Southeast Asia, while German exports serve pharmaceutical-grade triethanolamine demand in France and Switzerland. Trade corridors reflect feedstock integration advantages and regulatory qualification tiers.
United States
Gulf Coast ethylene oxide clusters supply monoethanolamine for carbon capture retrofits at Texas and Louisiana power facilities. EPA New Chemicals Program reviews under TSCA extend approval timelines for diethanolamine derivatives. Houston-area producers leverage captive feedstock access to serve metalworking fluid blenders across the Midwest.
Germany
Ludwigshafen chemical complexes anchor European pharmaceutical-grade triethanolamine supply for topical excipient markets. ECHA substance evaluation protocols under REACH disqualify low-purity imports from non-registered sources. BASF's integrated ethylene oxide-ethanolamine chain sustains cost-advantaged positions in cosmetic-grade segments.
China
Sichuan and Jiangsu province agrochemical manufacturers drive monoethanolamine consumption for glyphosate intermediate synthesis. SAMR oversight of chemical substance registration tightens documentation requirements for cosmetic-grade exports. Yangtze River Delta ethylene oxide availability supports downstream ethanolamine capacity serving domestic detergent producers.
Saudi Arabia
Jubail petrochemical complexes export ethanolamine derivatives to Indian and Pakistani surfactant manufacturers. SABIC's ethylene oxide integration provides feedstock security for regional amine production. Eastern Province industrial cities concentrate capacity serving Middle Eastern construction chemical markets.
South Korea
Ulsan petrochemical hubs supply triethanolamine for personal care compounders targeting pharmaceutical-grade certification. MFDS cosmetic ingredient regulations align with USP and EP monograph standards for topical formulations. Seoul Capital Area distributors face consolidation pressure as direct supply relationships with integrated producers expand.
Ethanolamine Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct specification tiers. The structure concentrates around integrated petrochemical majors with captive ethylene oxide supply and specialty amine houses with pharmaceutical-grade certification capabilities. Three archetypes dominate: Gulf Coast scale players with backward integration into feedstock, European quality specialists with REACH-registered cosmetic grades, and Asian agrochemical-integrated producers serving herbicide intermediates. Competitive moves center on membrane purification technology licensing and direct supply relationship establishment with home care multinationals.
Within the integrated major tier, BASF SE and Dow exemplify channel-control strategies through captive ethylene oxide sourcing and direct relationships with detergent and personal care formulators. Nouryon occupies a position representing the specialty derivative archetype, with emphasis on pharmaceutical-grade triethanolamine segments where analytical capabilities and regulatory documentation create qualification barriers. These three anchors illustrate how feedstock integration, geographic clustering, and certification tier specialization segment competitive positioning across the supply base.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Nouryon |
| Dow |
| LyondellBasell Industries N.V. |
| Akzo Nobel N.V. |
| BASF SE |
| SABIC |
| Nippon Shokubai Co., Ltd. |
| INEOS |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta ethylene oxide availability compresses margin buffers for non-integrated ethanolamine processors while simultaneously amplifying pricing power for backward-integrated majors serving pharmaceutical-grade triethanolamine segments.
Pricing Analysis
Membrane-refined versus distillation-based purification technology creates a widening pricing gap across ethanolamine grades. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects nitrosamine documentation burdens and REACH registration status as primary differentiation drivers. Cost compression in standard industrial grades is intensifying because membrane technology collapses legacy premium positions. Agrochemical intermediates buyers in Sichuan province exhibit highest price sensitivity, while personal care compounders in France and South Korea accept substantial premiums for USP-compliant supply.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for ethanolamine derivatives subject to dual-use chemical licensing. Production concentrates in China, Germany, and the United States, with feedstock sourcing drawing from Gulf Coast and Yangtze River ethylene oxide clusters. Supply chain vulnerability rests on single-source dependency for high-purity grades from Ludwigshafen and Freeport complexes. Distribution runs through direct sales relationships with integrated home care multinationals, squeezing regional distributor participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated home care multinationals with in-house toxicology capabilities, fragmenting spot-market access for mid-tier surfactant houses.
For Market Incumbents: Insulate pharmaceutical-grade positioning through captive membrane purification capacity and direct supply relationships with Henkel and Unilever. Alkanolamine substitution in selective hydrogen sulfide removal threatens monoethanolamine volumes in gas treatment; counter through carbon capture retrofit partnerships with Alberta oil sands and German power utilities. Backward integration into ethylene oxide remains the critical defensive lever. For New Entrants and Emerging Players: Pursue pharmaceutical-grade triethanolamine qualification outside BASF's Ludwigshafen and Dow's Freeport strongholds, where USP and EP monograph compliance remains underpenetrated. Green surfactant chemistry convergence offers the most penetrable entry vector through biosourced ethylene oxide partnerships with EU Green Deal-aligned formulators. Establish toll manufacturing arrangements with REACH-registered European facilities to bypass direct capital intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty amine houses with analytical capabilities exceeding standard QC infrastructure at commodity plants. Long-term viability hinges on nitrosamine testing infrastructure and regulatory documentation depth rather than volume scale alone. Watch for ECHA authorization timeline compression as the inflection signal separating qualified from excluded producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene oxide supply locks in margin control against feedstock concentration risk. |
| Pharmaceutical-Grade Certification | USP and EP monograph compliance commands price premiums in topical excipient markets. |
| Membrane Purification Licensing | Technology transfer collapses cost differential between standard and high-purity grades. |
| Long-term Supply Agreement | Direct relationships with home care multinationals eliminate distributor margin leakage. |
| Green Manufacturing Transition | Biosourced ethylene oxide integration opens EU Green Deal qualification pathways. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across ethanolamine value chain positions. Primary interviews captured plant managers at integrated ethylene oxide-ethanolamine facilities, procurement leads at detergent and personal care formulators, distribution channel partners in Western Europe and East Asia, and technical R&D directors specializing in surfactant chemistry. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of disclosed chemical producers, and ECHA substance evaluation dossiers. Bottom-up volume builds triangulated against top-down market sizing across grade tiers and application segments.
Calibration anchored historical consumption patterns to disclosed capacity utilization rates and feedstock cost structures across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry, certification grade, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory threshold tightening and substitution dynamics. Forecast inputs incorporated carbon capture mandate trajectories in Canada and Germany, plus REACH authorization timeline assumptions for cosmetic-grade segments.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese agrochemical-integrated producers or accelerated membrane technology licensing would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Azide Market
Chemicals
Lead Tetracetate Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
Quaternium-15 Market
Chemicals
Potassium Permanganate Market
Chemicals
Global Organobromine Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Tromethamine Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
N-Propanol Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Triethylenediamine Market
Chemicals
Sodium Tripolyphosphate (STPP) Market