
 Hexachloroethane Market | 2026-2036
Hexachloroethane Market Size, Share, and Industry Trends Forecast 2026-2036
Hexachloroethane Market Analytics
Consolidation among military procurement agencies is repositioning supplier relationships across the hexachloroethane value chain. Solvay SA leverages its integrated chlor-alkali platform to sustain cost advantages in European defense contracts. Merck KGaA anchors pharmaceutical-grade production through stringent purity protocols. Teja Matallurgicals and Chemicals competes on regional logistics strength across South Asian industrial corridors.
Hexachloroethane is a fully chlorinated ethane derivative with the molecular formula C2Cl6, produced via exhaustive chlorination of ethylene or acetylene in catalytic reactors, and serves primarily as a smoke-generating agent in military applications and as a chemical intermediate in specialty synthesis. The powder segment dominates military procurement due to controlled burn-rate requirements in smoke munitions, while the intermediate application captures margin pools from custom synthesis contracts in agrochemical precursors. The chemical industry end user segment leads volume absorption, though electronics-grade demand is gaining traction for specialized etching formulations.
The EPA regulates hexachloroethane under the Toxic Substances Control Act, restricting emissions from production facilities and mandating workplace exposure limits, while REACH classification in Europe imposes authorization requirements that constrain import volumes and elevate compliance costs for non-EU suppliers. China's MEE enforces discharge permits for chlorinated byproduct streams, affecting export-oriented manufacturers. Stakeholders must monitor evolving restriction proposals under the Stockholm Convention that could recategorize hexachloroethane persistence profiles.
Market Dynamics
Defense procurement consolidation is compressing supplier margins while EPA emission thresholds under the Toxic Substances Control Act force capital redeployment toward abatement infrastructure. This structural tension between military demand stability and environmental compliance cost escalation defines current competitive positioning.
Growth Catalysts
- REACH authorization requirements:European defense contracts now favor integrated chlor-alkali producers with captive hexachloroethane capacity, rewarding backward-linked suppliers.
- Munitions-grade powder specifications:Controlled burn-rate requirements in smoke grenades lock in technical barriers that sustain incumbent relationships.
- United States:Pentagon procurement centralization under consolidated acquisition commands is standardizing quality protocols across NATO-aligned suppliers.
Market Restraints
- Chlorine feedstock volatility:Energy-intensive chlor-alkali operations expose margins to natural gas price swings in European production clusters.
- Substitution threat from titanium tetrachloride:Alternative smoke formulations in civilian training applications erode non-military volume pools.
- China MEE discharge permits:Export-oriented manufacturers face rising treatment costs for chlorinated byproduct streams.
Strategic Opportunities
- Electronics-grade etching formulations:Semiconductor fabrication demand for ultra-pure chlorinated precursors opens premium pricing tiers.
- India:BIS certification alignment with defense indigenization programs creates entry points for qualified regional suppliers.
- Agrochemical intermediate synthesis:Custom contract manufacturing for specialty pesticide precursors diversifies revenue beyond smoke applications.
Industry Challenges
- Pharmaceutical-grade purity certification:Merck KGaA's established protocols set technical benchmarks that new entrants struggle to replicate within compliance timelines.
- Legacy equipment retrofitting:EPA-mandated emission controls require capital deployment that mid-scale producers cannot absorb without consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexachloroethane Market |
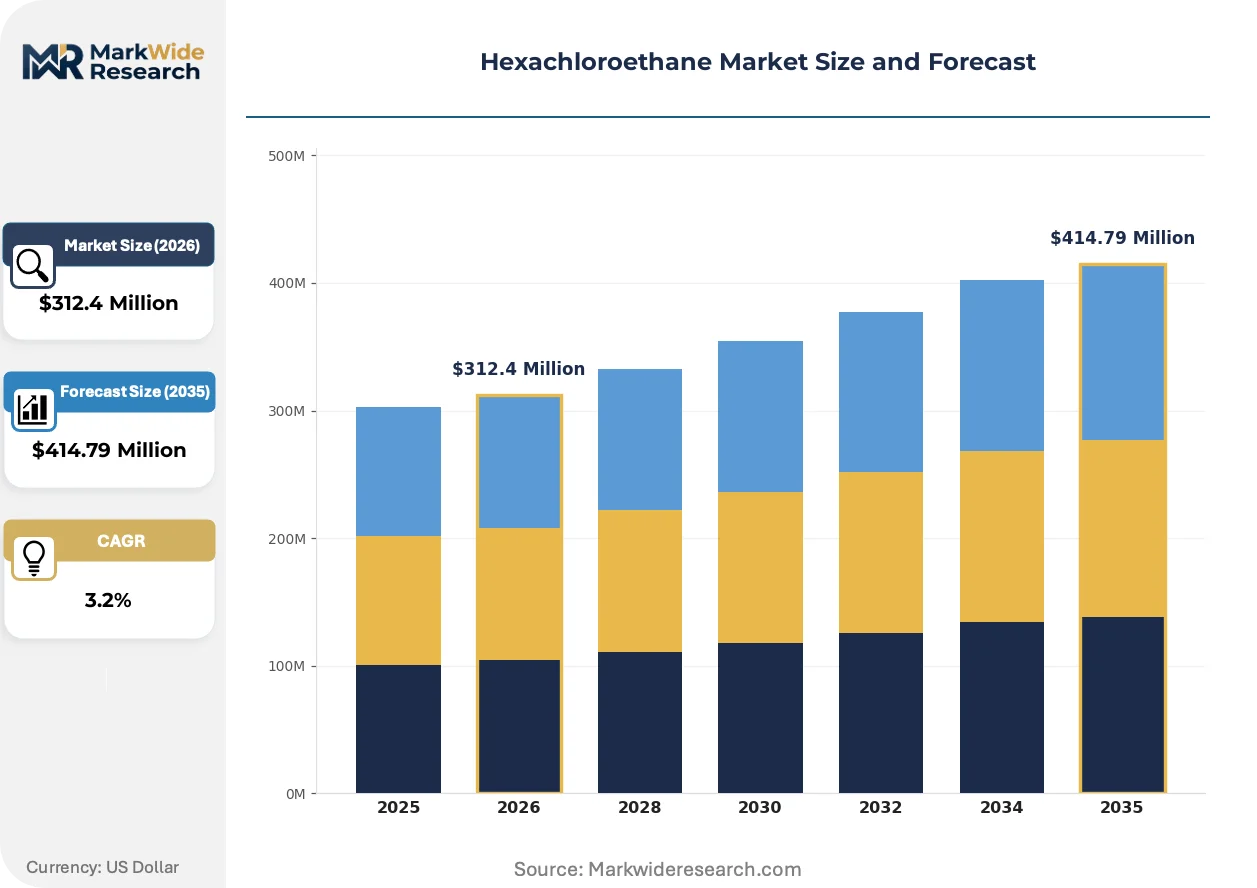
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $414.79 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Powder, Granules, Liquid Application: Solvent, Flame Retardant, Intermediate, Fumigant End User: Chemical Industry, Pharmaceuticals, Plastics, Electronics Packaging Type: Drums, Bags, Tankers, Bulk Containers |
| Companies Covered | Changshu Zhenfu New Materials, Nantong Donggang Chemical, Scottish Chemical Industries, Teja Matallurgicals and Chemicals, Mil-Spec Industries Corporation, Merck KGaA, Solvay SA, Akzo Nobel N.V, FabriChem, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexachloroethane Market Evolving Landscape
Continuous chlorination reactor design is displacing batch processing economics. Automation in quality assurance and real-time emission monitoring is compressing the gap between military specification compliance and operational efficiency.
Membrane cell chlor-alkali technology is integrating with hexachloroethane production streams to capture chlorine byproduct value. European defense contractors adopting this configuration report improved yield consistency. The technology is integrating upstream chemical synthesis with downstream military specification fulfillment, collapsing traditional supplier tiers.
REACH authorization sunset dates are accelerating substitution assessments across European chemical portfolios. Industrial consequence includes mandatory supply chain requalification for non-EU sources. Specialty chemical distributors in Germany and Belgium are responding by consolidating import volumes through authorized representative structures.
Defense procurement agencies are unbundling smoke munition specifications from integrated system contracts. Prime contractors now source hexachloroethane through tiered supplier qualification programs rather than captive production. This pattern is most visible in United States Army procurement, where separate material specifications enable multi-source qualification for strategic stockpile requirements.
Hexachloroethane Market Segmentation
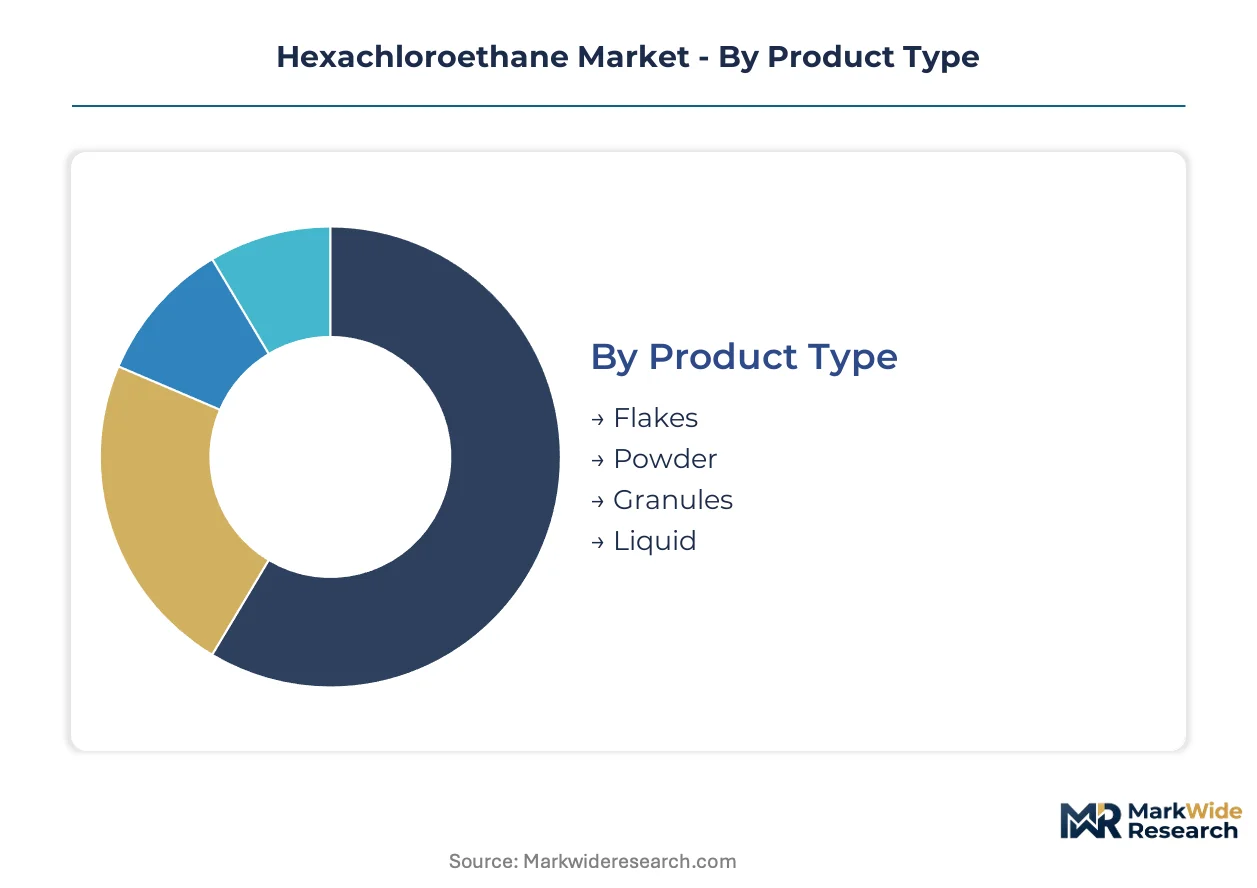
Hexachloroethane procurement cycles diverge sharply across product forms and end-use specifications, with military smoke munitions driving powder-grade replacement schedules while electronics and pharmaceutical applications impose distinct purity upgrade timelines. Segmentation discipline separates volume commodities from margin-rich specialty grades.
Product Type:
Upgrade cycles in smoke munitions procurement favor powder specifications, while industrial intermediates tolerate broader form-factor flexibility.
- Powder:Finely milled hexachloroethane with controlled particle size distribution meets military burn-rate specifications for smoke grenades and screening devices. Pentagon procurement centralization under consolidated acquisition commands standardizes powder-grade requirements across NATO-aligned defense contractors. Volume placements concentrate in Powder; the faster expansion belongs to Granules.
- Flakes:Crystalline plate morphology suits intermediate chemical synthesis where dissolution kinetics matter more than combustion control. Agrochemical precursor manufacturers in South Asian industrial corridors prefer flake form for reactor feeding efficiency. REACH authorization requirements favor European chlor-alkali producers with captive flake production capacity.
- Granules:Pelletized form reduces dust exposure during handling and enables automated dosing systems in continuous chlorination reactors.
- Liquid:Dissolved or molten states serve specialized etching formulations and solvent applications requiring homogeneous phase delivery.
Volume placements concentrate in Powder; the faster expansion belongs to Granules.
Application:
Cost tier differentiation separates military-specification smoke applications from commodity intermediate uses, with regulatory burden intensity inversely correlating with volume scale.
- Intermediate:Chemical feedstock role in specialty synthesis chains, particularly agrochemical precursor manufacturing, captures margin pools from custom contract manufacturing. Teja Matallurgicals and Chemicals competes on regional logistics strength for intermediate volumes across South Asian corridors. Electronics-grade etching formulations for semiconductor fabrication open premium pricing tiers within this application.
- Solvent:Carrier and cleaning applications in metal degreasing and precision equipment maintenance face substitution pressure from less regulated chlorinated alternatives.
- Flame Retardant:Additive applications in polymer systems require compatibility with host resin matrices and thermal stability thresholds.
- Fumigant:Pest control applications in grain storage and shipping containers confront tightening residue limits under EPA and REACH frameworks.
Military procurement locks volume leadership in smoke-screening applications; agrochemical intermediate synthesis climbs the fastest.
End User:
Customer type segmentation reveals divergent certification burdens, with pharmaceutical and electronics buyers imposing purity protocols that chemical industry volume purchasers rarely require.
- Chemical Industry:Bulk consumers in chlorinated solvent and intermediate synthesis drive baseline volume absorption, prioritizing supply security over specification granularity. EPA emission thresholds under the Toxic Substances Control Act force capital redeployment toward abatement infrastructure among producers serving this segment.
- Electronics:Semiconductor fabrication demand for ultra-pure chlorinated precursors creates entry barriers that sustain incumbent relationships through qualification timelines.
- Pharmaceuticals:Merck KGaA anchors pharmaceutical-grade production through stringent purity protocols that set technical benchmarks new entrants struggle to replicate.
- Plastics:Polymer additive applications in flame retardant compounding seek cost-optimized supply chains with less stringent documentation requirements.
Volume concentrates in Chemical Industry uptake; Electronics-grade demand gains share fastest.
Packaging Type:
Supply concentration in defense procurement favors drum and bulk configurations that align with strategic stockpile handling protocols.
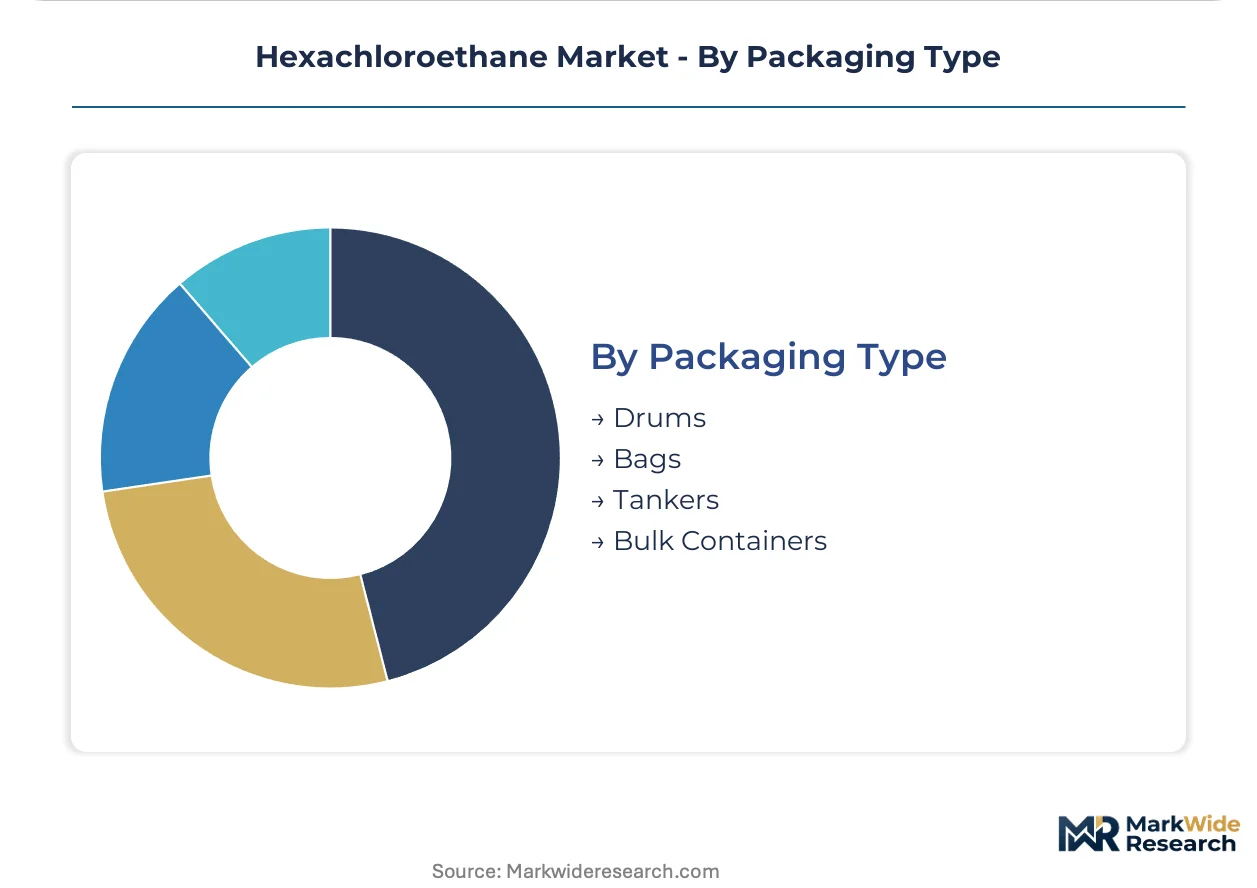
- Drums:Standardized steel and fiber containers dominate military logistics chains with established handling equipment and hazard classification compatibility.
- Bulk Containers:Intermediate bulk containers and flexible tank systems reduce per-unit handling costs for high-volume chemical industry consumers.
- Bags:Multi-layer polymer and paper sacks serve regional industrial distributors with fragmented downstream customer bases.
- Tankers:Dedicated bulk liquid transport enables continuous feedstock supply to integrated chlor-alkali production facilities.
Defense procurement patterns anchor drum volumes; bulk container adoption expands most quickly among cost-sensitive industrial buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement centralization in the United States drives the dominant share of munitions-grade hexachloroethane absorption. European REACH frameworks and Asian manufacturing cost structures create divergent competitive zones. Regulatory stringency separates premium-grade from commodity supply corridors.
United States
Pentagon acquisition commands standardize powder-grade specifications across NATO-aligned contractors. EPA Toxic Substances Control Act emission thresholds force capital redeployment toward abatement infrastructure. Production clusters in the Gulf Coast chemical corridor serve defense stockpile requirements with integrated chlor-alkali feedstock security.
Germany
REACH authorization sunset dates accelerate substitution assessments across chemical portfolios. ECHA mandates supply chain requalification for non-EU sources through authorized representative structures. The Rhine-Ruhr industrial basin hosts specialty chemical distributors consolidating import volumes for defense intermediate synthesis.
China
Export-oriented manufacturers face rising treatment costs for chlorinated byproduct streams under MEE discharge permit enforcement. The Yangtze River Delta concentration of chlor-alkali capacity supplies regional agrochemical precursor demand. Shandong Peninsula facilities retrofit continuous chlorination reactors to meet yield consistency targets.
India
BIS certification alignment with defense indigenization programs creates entry points for qualified regional suppliers. CDSCO pharmaceutical-grade protocols set purity benchmarks for custom synthesis contractors. Gujarat industrial corridors leverage regional logistics strength for intermediate volumes serving South Asian agrochemical markets.
Belgium
Integrated chlor-alkali platforms with captive hexachloroethane capacity capture European defense contract premiums. ECHA authorization requirements constrain import volumes from non-EU sources. The Port of Antwerp chemical cluster coordinates membrane cell technology deployment with downstream military specification fulfillment.
Hexachloroethane Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics-grade purification and regional defense indigenization contracts. The vendor base separates into three functional layers: integrated chlor-alkali operators with backward-linked feedstock control, specialty chemical distributors managing REACH compliance complexity, and regional fabricators competing on logistics proximity. Consolidation pressure intensifies as EPA-mandated emission controls require capital deployment beyond mid-scale producer absorption capacity. Dominant competitive moves include strategic partnerships with defense procurement agencies and portfolio diversification into agrochemical intermediate synthesis.
Among European integrated chemical groups, Solvay SA and Merck KGaA occupy positions reflecting distinct tier specializations. Solvay SA exemplifies the chlor-alkali-integrated archetype with captive capacity advantages in European defense contracting. Merck KGaA anchors the pharmaceutical-grade purification tier through established protocols that set technical benchmarks for new entrants. Teja Matallurgicals and Chemicals represents the regional logistics specialist model competing across South Asian industrial corridors. Scottish Chemical Industries and FabriChem, Inc. sit within the defense-focused fabrication segment serving munitions specification requirements.
| Leading Market Players |
|---|
| Changshu Zhenfu New Materials |
| Nantong Donggang Chemical |
| Scottish Chemical Industries |
| Teja Matallurgicals and Chemicals |
| Mil-Spec Industries Corporation |
| Merck KGaA |
| Solvay SA |
| Akzo Nobel N.V |
| FabriChem, Inc. |
| Others |
Value Network & Pricing Analysis
Pentagon procurement centralization anchors pricing power among integrated chlor-alkali producers serving NATO-aligned defense contracts. Cost compression in intermediate-grade supply reflects chlorine feedstock volatility and REACH-driven compliance burdens that commodity producers cannot absorb without consolidation.
Pricing Analysis
Volume placements concentrate in powder-grade military specifications where contract-based long-term offtake agreements lock in incumbent relationships through burn-rate certification requirements. Premium-mid-economy pricing differentiation separates pharmaceutical-grade purity protocols from commodity intermediate volumes, with electronics-grade etching formulations commanding the highest tier. Pricing pressure stems from EPA-mandated emission control investments that mid-scale producers cannot finance without margin erosion. Chemical industry bulk buyers exhibit highest price sensitivity due to substitution alternatives, while defense procurement agencies prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-defense channels handle strategic stockpile requirements through drum-standardized logistics chains with established hazard classification protocols. Geographic supply concentration centers on the United States, Germany, and China, with Gulf Coast chemical corridor clusters serving Pentagon acquisition commands. Raw material dependencies rest on chlorine feedstock from membrane cell chlor-alkali operations, acetylene or ethylene precursors, and catalytic reactor systems. Single-source vulnerability characterizes European defense contracting where REACH authorization requirements constrain non-EU import volumes. Distribution runs through specialty chemical distributors managing ECHA compliance complexity for regional industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlor-alkali capacity scarcity among REACH-authorized producers props pricing power for backward-integrated suppliers serving European defense contracts. This structural constraint rewards incumbents with captive feedstock security while elevating barriers for import-dependent competitors.
For Market Incumbents: Cement relationships with Pentagon acquisition commands through multi-source qualification programs for strategic stockpile requirements. Deepen upstream control over membrane cell chlor-alkali capacity to offset chlorine feedstock volatility. Invest in continuous chlorination reactor automation to compress the gap between military specification compliance and operational efficiency. Counter titanium tetrachloride substitution threats by locking in burn-rate certification protocols that alternative smoke formulations cannot replicate.
For New Entrants and Emerging Players: E-commerce-enabled specialty chemical distribution offers a low-capital route to bypass established distributor tiers in fragmented South Asian industrial corridors. Target agrochemical intermediate synthesis in Gujarat industrial corridors where BIS certification alignment with defense indigenization programs creates qualified supplier status. Pursue electronics-grade purification partnerships with semiconductor fabrication facilities seeking ultra-pure chlorinated precursor alternatives to incumbent supply. Leverage regional logistics strength to compete on delivery velocity rather than scale economics.
For Investors and Strategic Acquirers: The window for entry favors integrated chlor-alkali operators with captive hexachloroethane capacity and REACH authorization compliance. Mid-scale producers facing EPA-mandated emission control retrofit requirements represent consolidation targets with distressed valuation entry points. Long-term viability hinges on diversification beyond smoke applications into agrochemical intermediate synthesis and electronics-grade etching formulations. Watch for Stockholm Convention persistence profile recategorization proposals as a regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Captive chlorine supply insulates margins from natural gas price swings in European production clusters. |
| Continuous Chlorination Reactor Deployment | Automation in quality assurance compresses military specification compliance costs for powder-grade output. |
| REACH Authorized Representative Structure | Specialty chemical distributors in Germany and Belgium consolidate import volumes for non-EU source requalification. |
| Electronics-Grade Purification Investment | Semiconductor fabrication demand for ultra-pure precursors opens premium pricing tiers beyond smoke applications. |
| Joint Venture with Defense Procurement Agencies | Tiered supplier qualification programs separate material specifications from integrated system contracts. |
Research Methodology
Document review covered customs and trade data, EPA Toxic Substances Control Act filings, ECHA authorization registers, and chlor-alkali industry association reports, complemented by interviews with plant managers at integrated chemical facilities, procurement leads at defense contractors, distribution channel partners managing REACH compliance, and technical R&D directors in specialty synthesis. Bottom-up volume modeling triangulated against top-down demand aggregation from end-use sector absorption rates.
Cross-referencing historical price series against expert panel input on regulatory timeline probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, application tier, end-user industry, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for substitution elasticity and compliance cost pass-through assumptions. Industry-specific inputs incorporated chlorine feedstock cost trajectories and defense procurement centralization patterns.
The model holds under stable EPA emission threshold enforcement and REACH authorization continuity; deviation in Stockholm Convention recategorization timelines or Pentagon procurement decentralization would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Indonesia Nitric Acid Market
Chemicals
Aluminum Phosphide Market
Chemicals
Coagulant Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Cupric Chloride Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Morpholine Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Resorcinol Market
Chemicals
Cyclopentylamine Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
China Inorganic Iodide Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Valeryl Chloride Market
Chemicals
HATU Market