
 Disodium Laureth Sulfosuccinate Market | 2026-2036
Disodium Laureth Sulfosuccinate Market Size, Share, and Industry Trends Forecast 2026-2036
Disodium Laureth Sulfosuccinate Market Analytics
Specialty formulators serving sensitive-skin product lines is bifurcating demand away from conventional sulfate-based surfactants. BASF SE leverages its integrated ethoxylation capabilities to supply cosmetic-grade batches with consistent chain-length distribution. Croda International Plc anchors its position through lipid-compatible surfactant portfolios that pair sulfosuccinates with emollient systems. Stepan Company competes on manufacturing scale across North American personal care contract manufacturing channels.
Disodium Laureth Sulfosuccinate functions as an anionic surfactant produced through sulfosuccination of ethoxylated lauryl alcohol, yielding a C12-C14 alkyl chain with an average ethoxylation degree of 1-4 moles that imparts mildness and flash foam in aqueous systems. The liquid product type dominates current volume owing to ease of incorporation into cold-process formulations, while powder grades command margin premiums in solid shampoo bars and travel-format personal care where water reduction drives formulation economics. Foaming agent applications lead absolute consumption across body wash and facial cleanser segments, though pharmaceutical-grade specifications for topical delivery systems represent the fastest-expanding margin pool.
REACH registration requirements in Europe and EPA Safer Choice criteria in the United States constrain allowable levels of residual maleic anhydride and 1,4-dioxane, pushing manufacturers toward purified sulfosuccinate grades with tightened impurity profiles. ECHA substance evaluation protocols are extending testing obligations to ethoxylated surfactant metabolites, adding compliance layers for importers serving EU cosmetic brands. Stakeholders must monitor tightening biodegradability thresholds under EU Green Deal chemical sustainability targets while evaluating captive sulfosuccination investments versus merchant supply arrangements.
Market Dynamics
Personal care formulators are abandoning sulfate-based surfactants for milder alternatives, compressing demand for conventional anionic systems while redirecting procurement toward ethoxylated sulfosuccinate grades with verified impurity profiles and documented biodegradability credentials.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Biodegradability mandates under REACH registration protocols are forcing cosmetic brands to reformulate with ethoxylated sulfosuccinates that demonstrate rapid aquatic degradation.
- Sensitive-skin product proliferation:Dermatological testing protocols for hypoallergenic cleansers specify reduced irritation indices achievable only through sulfosuccinate-based surfactant systems.
- Cold-process formulation adoption:Liquid sulfosuccinate grades enable ambient-temperature manufacturing that eliminates energy-intensive heating stages in contract manufacturing operations.
Market Restraints
- Ethylene oxide feedstock volatility:Ethoxylated alcohol precursors track ethylene oxide spot markets, exposing margin stability to petrochemical cycle swings.
- Residual impurity testing burdens:EPA Safer Choice criteria and ECHA substance evaluation protocols mandate quantified 1,4-dioxane limits below 10 ppm, requiring capital-intensive purification investments.
- Amphoteric surfactant substitution:Cocamidopropyl betaine and alkyl polyglucoside systems capture mid-tier mildness applications at lower regulatory compliance cost.
Strategic Opportunities
- Pharmaceutical-grade topical delivery:Transdermal patch and medicated shampoo applications specify sulfosuccinate excipients with documented percutaneous absorption profiles.
- India personal care manufacturing expansion:CDSCO cosmetic ingredient registration harmonization with ASEAN standards enables export-platform production for Southeast Asian markets.
- Solid format personal care:Powder sulfosuccinate grades serve waterless shampoo bar formulations targeting airline travel retail and sustainability-conscious urban consumers.
Industry Challenges
- Ethoxylation degree control:Narrow chain-length distribution specifications for cosmetic-grade batches require continuous reactor monitoring capabilities scarce among mid-scale producers.
- REACH metabolite testing timelines:ECHA evaluation protocols extending to ethoxylated surfactant degradation products delay new supplier qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disodium Laureth Sulfosuccinate Market |
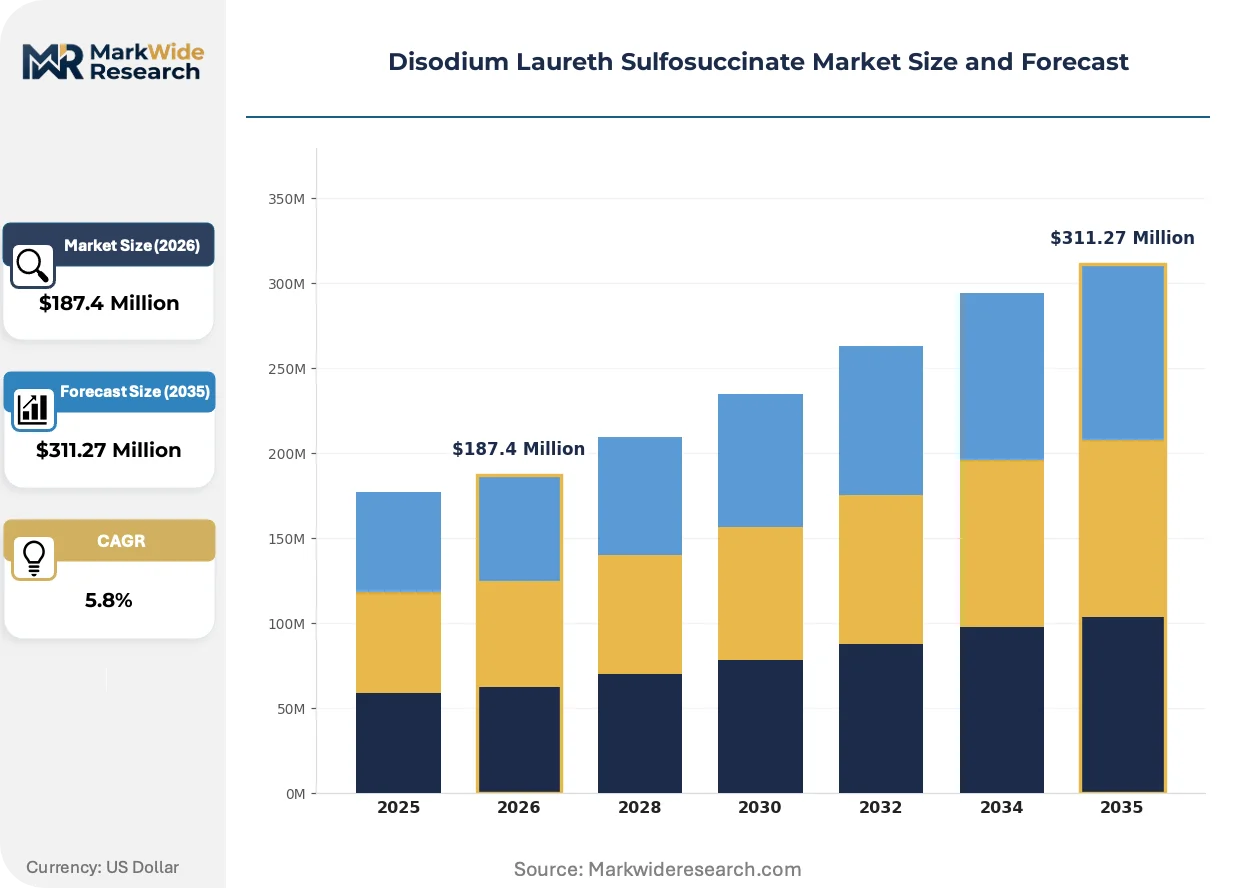
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Granule End User: Cosmetics, Personal Care, Pharmaceuticals, Household Products Application: Shampoos, Body Wash, Facial Cleansers, Foaming Agents Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Clariant AG, Solvay S.A., Stepan Company, Croda International Plc, Huntsman Corporation, Kao Chemicals, Lubrizol Corporation, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disodium Laureth Sulfosuccinate Market Evolving Landscape
Cold-process liquid grades are compressing thermal energy requirements across personal care manufacturing, while regulatory metabolite testing and pharmaceutical excipient qualification are creating tiered supplier stratification based on analytical capabilities.
Enzymatic sulfosuccination routes are supplanting conventional acid-catalyzed processes in pilot-scale operations. Specialty chemical producers in Germany's manufacturing corridor are adopting lipase-mediated esterification that operates at ambient temperature and pressure. This biotechnology is enabling residual maleic anhydride levels below detection limits without multi-stage vacuum distillation, compressing capital requirements for new market entrants.
REACH substance evaluation protocols are extending testing obligations to ethoxylated surfactant aquatic metabolites. ECHA's 2024-2026 rolling action plan prioritizes biodegradation intermediate screening for C12-C14 alkyl chain surfactants. Cosmetic ingredient importers serving EU brands are responding by commissioning OECD 308 sediment simulation studies ahead of regulatory deadlines to secure supply continuity.
Direct procurement relationships between personal care brands and sulfosuccinate manufacturers are displacing distributor-mediated purchasing. Large formulators in North America are establishing annual volume commitments with specified ethoxylation degrees and impurity certificates. This consolidation is most visible in body wash and facial cleanser segments where batch-to-batch consistency directly affects finished product foam aesthetics and skin feel profiles.
Disodium Laureth Sulfosuccinate Market Segmentation
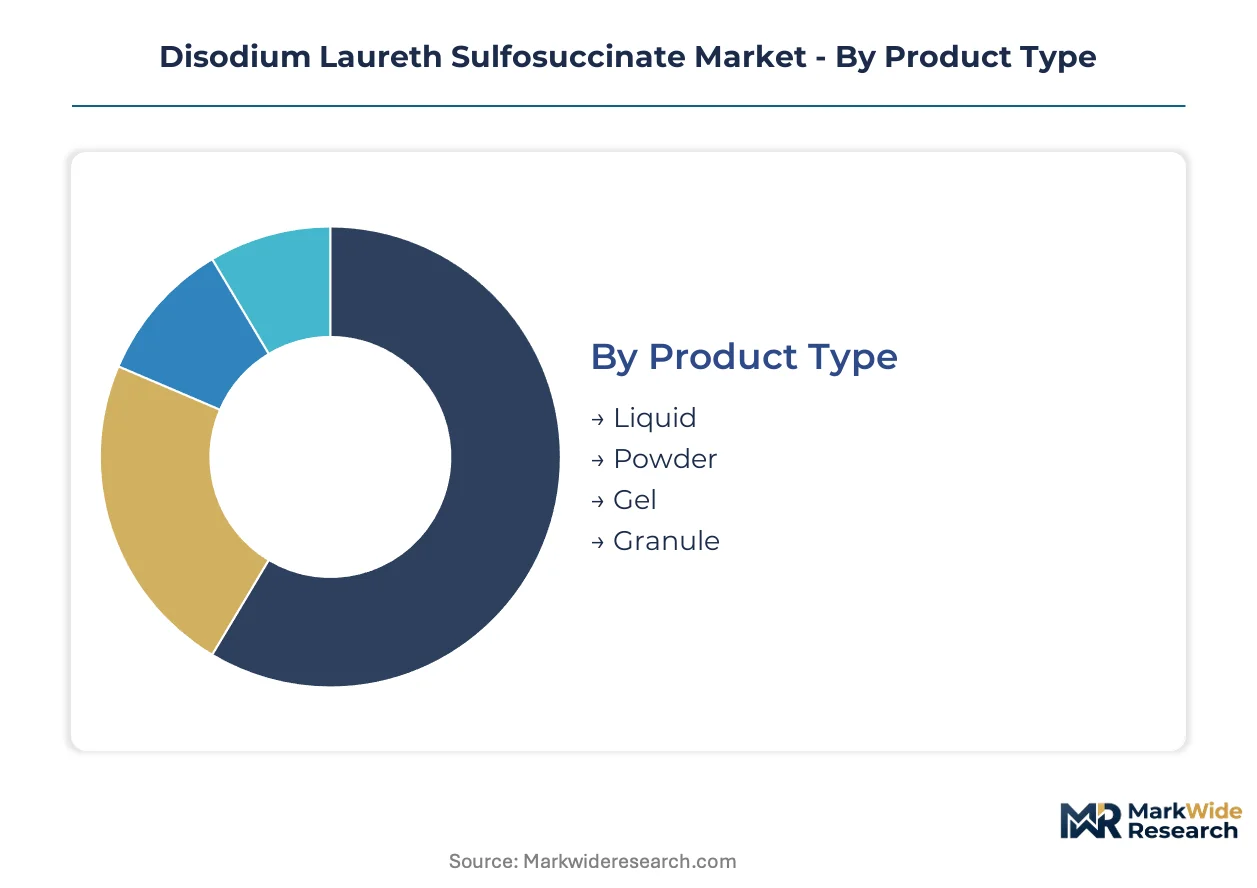
Disodium Laureth Sulfosuccinate procurement patterns diverge sharply across physical formats and regulatory exposure levels. Formulators select product types based on process temperature requirements, while end-use segments face distinct compliance burdens under REACH and EPA frameworks.
Product Type:
REACH registration protocols and EPA Safer Choice criteria create divergent purity requirements across physical formats, with liquid grades facing distinct metabolite testing timelines versus solid alternatives.
- Liquid:Dominates cold-process personal care manufacturing with C12-C14 alkyl chain distribution optimized for ambient-temperature incorporation. Demand concentrates in Germany's specialty chemical corridor where contract manufacturers eliminate heating stages to compress energy costs.
- Powder:Commands formulation economics in waterless shampoo bars and travel-format products where water reduction drives sustainability positioning. CDSCO registration harmonization with ASEAN standards accelerates adoption across India-based export platforms serving Southeast Asian markets.
- Gel:Enables precise dosing in pharmaceutical topical delivery systems with documented percutaneous absorption profiles.
- Granule:Serves industrial-scale household product manufacturing with reduced dust exposure during bulk handling operations.
Established volume favors Liquid; emerging adoption favors Powder.
End User:
Customer procurement scale determines supplier qualification depth, with pharmaceutical buyers demanding excipient-grade documentation that personal care formulators rarely require.
- Cosmetics:Hypoallergenic and sensitive-skin product lines specify reduced irritation indices achievable through sulfosuccinate-based surfactant systems with verified 1,4-dioxane levels below 10 ppm.
- Personal Care:Body wash and facial cleanser segments drive absolute consumption, with large formulators establishing direct annual volume commitments specifying ethoxylation degrees and impurity certificates.
- Pharmaceuticals:Transdermal patch and medicated shampoo applications require sulfosuccinate excipients with OECD 308 sediment simulation studies ahead of ECHA regulatory deadlines.
- Household Products:Cost-sensitive applications face substitution pressure from alkyl polyglucoside systems in mid-tier mildness segments.
Pharmaceuticals climbs the fastest on margin expansion; Personal Care retains absolute volume leadership.
Application:
Foam aesthetics and skin feel specifications create tiered supplier relationships based on batch-to-batch consistency capabilities.
- Shampoos:Solid format waterless bars represent the steepest expansion trajectory for powder sulfosuccinate grades targeting airline travel retail and urban sustainability positioning.
- Body Wash:Liquid grades enable flash foam characteristics that drive consumer preference testing outcomes in North American contract manufacturing channels.
- Facial Cleansers:Dermatological testing protocols specify sulfosuccinate systems for hypoallergenic positioning in sensitive-skin product lines.
- Foaming Agents:Pharmaceutical-grade specifications for topical delivery systems capture the fastest-expanding margin pool in transdermal applications.
Body Wash commands current formulation volumes; Shampoos gain share fastest on solid-format innovation.
Distribution Channel:
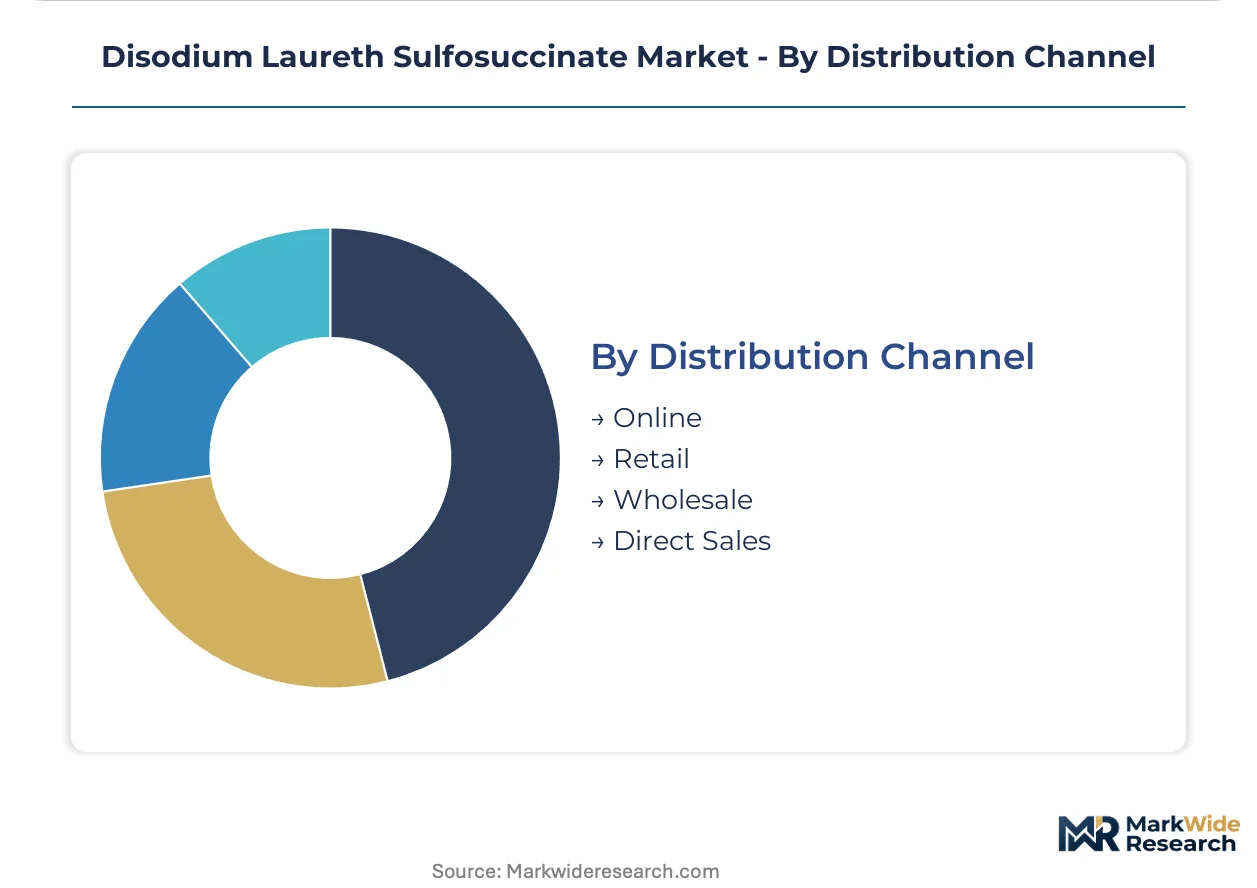
Direct procurement relationships are displacing intermediary purchasing as large formulators seek specified ethoxylation degrees with certificate-backed consistency.
- Online:Enables small-batch sampling for qualification trials ahead of annual volume commitments, particularly among specialty formulators testing enzymatic sulfosuccination grades.
- Retail:Serves mid-scale personal care manufacturers with standardized liquid grades for established cold-process formulations.
- Wholesale:Aggregates demand across fragmented household product manufacturers with less stringent impurity profile requirements.
- Direct Sales:Large North American formulators bypass distributors entirely, establishing captive supply arrangements with specified chain-length distribution and metabolite testing documentation.
Direct Sales deepens share among tier-one formulators; Online expands fastest for qualification-stage procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic ingredient procurement concentrates among specialty formulators seeking REACH-compliant sulfosuccinate grades with documented biodegradability credentials. Large personal care manufacturers in Germany, the United States, and India establish direct supply relationships specifying ethoxylation degrees and impurity profiles. Regulatory divergence across jurisdictions fragments supplier qualification timelines.
Germany
Specialty chemical manufacturers in North Rhine-Westphalia drive demand for cold-process liquid grades that eliminate energy-intensive heating stages. ECHA substance evaluation protocols under REACH mandate OECD 308 sediment simulation studies for ethoxylated surfactant metabolites. Leverkusen and Düsseldorf-based formulators are commissioning enzymatic sulfosuccination pilot plants to achieve residual maleic anhydride levels below detection limits.
United States
North American contract manufacturers specify liquid sulfosuccinate grades for body wash and facial cleanser segments with flash foam characteristics. EPA Safer Choice criteria enforce 1,4-dioxane limits below 10 ppm, requiring capital-intensive purification investments. New Jersey and Illinois-based personal care formulators are establishing annual volume commitments with certificate-backed consistency requirements.
India
Export-platform production for Southeast Asian markets accelerates following CDSCO cosmetic ingredient registration harmonization with ASEAN standards. Maharashtra and Gujarat-based manufacturers adopt powder sulfosuccinate grades for waterless shampoo bar formulations targeting airline travel retail. Mumbai specialty chemical corridors are expanding capacity to serve sustainability-conscious urban consumers across domestic and export channels.
China
Domestic personal care brands source sulfosuccinate systems for sensitive-skin product lines amid tightening environmental compliance under MEE guidelines. Yangtze River Delta chemical clusters face ethylene oxide feedstock volatility tracking petrochemical cycle swings. Shanghai and Zhejiang-based formulators are qualifying pharmaceutical-grade specifications for topical delivery systems with documented percutaneous absorption profiles.
France
Hypoallergenic cleanser demand from Paris-based dermatological brands specifies reduced irritation indices achievable through sulfosuccinate-based surfactant systems. ANSM cosmetic safety assessments align with ECHA biodegradability thresholds under EU Green Deal chemical sustainability targets. Île-de-France formulators are redirecting procurement toward purified grades with tightened impurity profiles ahead of metabolite testing deadlines.
Disodium Laureth Sulfosuccinate Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive ethoxylation capabilities and specialty surfactant houses with lipid-compatible portfolios. The competitive structure tiers around analytical sophistication, with suppliers stratified by REACH metabolite testing documentation and pharmaceutical excipient qualification capabilities. Dominant archetypes include integrated chemical majors, specialty surfactant specialists, and regional contract manufacturing suppliers. Competitive moves concentrate on enzymatic process licensing and direct procurement relationship consolidation with large formulators.
Within the integrated chemical major tier, BASF SE and Evonik Industries exemplify archetypes with ethoxylation capabilities supplying cosmetic-grade batches with consistent chain-length distribution. Among specialty surfactant specialists, Croda International Plc and Stepan Company occupy positions defined by lipid-compatible portfolios and manufacturing scale across North American personal care channels respectively. Solvay S.A. and Clariant AG represent European-based suppliers navigating ECHA evaluation protocol compliance. These named entities anchor industry-level commentary on sulfosuccinate supply without implying specific strategic actions or market positions beyond archetype representation.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Solvay S.A. |
| Stepan Company |
| Croda International Plc |
| Huntsman Corporation |
| Kao Chemicals |
| Lubrizol Corporation |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Captive ethoxylation capacity at integrated chemical majors compresses unit economics for cosmetic-grade sulfosuccinate batches, concentrating supply power among producers with in-house lauryl alcohol feedstock and vacuum distillation capabilities while establishing price floors that merchant suppliers struggle to undercut.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide spot markets dominate procurement arrangements for ethoxylated alcohol precursors, with price differentiation across pharmaceutical-grade, cosmetic-grade, and industrial-grade certification tiers. Cold-process liquid grades command premiums over powder alternatives due to batch-to-batch consistency requirements from large North American formulators. Pricing pressure intensifies in mid-tier personal care segments where cocamidopropyl betaine systems capture mildness applications at lower compliance cost. Household product manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize documentation over unit cost.
Supply Chain Analysis
Six-to-eight week lead times for OECD 308 sediment simulation documentation strain supplier qualification cycles, particularly among EU-bound cosmetic ingredient importers. Manufacturing concentrates in Germany's North Rhine-Westphalia corridor, the United States' New Jersey-Illinois axis, and India's Maharashtra-Gujarat chemical clusters. Raw material flows draw from ethylene oxide crackers, lauryl alcohol fractionation units, and maleic anhydride producers. Single-source vulnerability persists for high-purity grades with sub-10 ppm 1,4-dioxane specifications. Distribution runs through direct annual volume commitments between large formulators and integrated producers, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where REACH metabolite testing timelines and ECHA evaluation protocols create switching costs that cement incumbent positions.
For Market Incumbents: Compound analytical capabilities through in-house OECD 308 sediment simulation infrastructure to compress supplier qualification timelines for EU cosmetic brands. Expand captive sulfosuccination capacity in Germany's manufacturing corridor to capture enzymatic process efficiencies. Alkyl polyglucoside substitution in mid-tier segments threatens volume erosion; defend through lipid-compatible surfactant portfolio bundling with emollient systems. For New Entrants and Emerging Players: CDSCO-ASEAN harmonization certification fast-tracks enable export-platform positioning from India to Southeast Asian markets with reduced regulatory friction. Waterless shampoo bar formulations represent the most penetrable white-space, with powder sulfosuccinate grades serving sustainability-conscious urban consumers and airline travel retail channels. Target pharmaceutical-grade topical delivery specifications where percutaneous absorption documentation commands margin premiums unavailable to commodity suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty surfactant houses with enzymatic sulfosuccination pilot capabilities over commodity ethoxylators lacking purification expertise. Five-to-ten year viability rests on regulatory metabolite testing depth rather than scale economies alone. Acquisition targets should demonstrate OECD 308 study commissioning relationships and direct procurement contracts with tier-one personal care formulators. Watch for ECHA rolling action plan announcements on C12-C14 alkyl chain surfactants as inflection signals for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Lipase-mediated esterification achieves residual maleic anhydride levels below detection limits without vacuum distillation. |
| Backward Integration into Ethoxylation | In-house ethylene oxide conversion secures chain-length distribution control for cosmetic-grade batch consistency. |
| Pharmaceutical Excipient Qualification | OECD 308 sediment simulation documentation opens transdermal patch and medicated shampoo margin pools. |
| Direct Procurement Relationship Consolidation | Annual volume commitments with specified ethoxylation degrees displace distributor-mediated purchasing channels. |
| CDSCO-ASEAN Registration Harmonization | Export-platform production from India accelerates Southeast Asian market access with unified compliance standards. |
Research Methodology
Cross-validation between primary interviews with specialty chemical plant managers, personal care procurement leads, and regulatory affairs directors anchors the qualitative findings against secondary validation from ECHA substance evaluation protocols, CDSCO cosmetic ingredient registration guidelines, and customs trade data. Bottom-up triangulation across sulfosuccinate production capacity disclosures and top-down demand modeling from personal care formulation volumes ensures analytical coherence.
Sensitivity analysis across ethylene oxide feedstock volatility scenarios and REACH compliance timeline variations informs the projection framework. Segmentation dimensions modeled include physical format, end-use industry, application, and regional regulatory cluster. CAGRs derive from ethoxylated surfactant demand elasticity and cold-process formulation adoption curves. Industry-specific inputs incorporate enzymatic sulfosuccination pilot scale-up trajectories and pharmaceutical-grade excipient qualification pipelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal chemical sustainability enforcement or abrupt ethylene oxide supply disruptions would require recalibration. Forecasts reflect documented assumptions on biodegradability threshold tightening and metabolite testing protocol expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Lauramide DEA Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Sulfosuccinate Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Procream Market
Surfactants
Global Demulsifiers Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Surfactant EOR Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Global Methyl Ester Sulfonate Market