
 Nonaisoprenol Market | 2026-2036
Nonaisoprenol Market Size, Share, and Industry Trends Forecast 2026-2036
Nonaisoprenol Market Analytics
Project finance for multi-step fermentation facilities is rewriting competitive entry barriers in the nonaisoprenol space. BASF SE leverages backward integration into microbial strain development to secure cost-advantaged feedstock positions. Zhejiang Yixin Pharmaceutical Co., Ltd. anchors its presence through dedicated pharmaceutical-grade production lines serving CDMO networks. Sigma-Aldrich competes on catalog breadth and analytical certification, sustaining premium positioning among research institutions.
Nonaisoprenol denotes a C9 isoprenoid alcohol serving as a chiral building block for terpenoid synthesis, typically manufactured via microbial fermentation or semi-synthetic extraction with specified optical purity exceeding 98%. The compound functions primarily as a pharmaceutical intermediate for vitamin E analogs, fragrance precursors, and crop protection actives requiring defined stereochemistry. Liquid formulations dominate current volume owing to ease of handling in continuous chemical processing, while powder grades command margin premiums in pharmaceutical applications where moisture-sensitive stability protocols apply. Cosmetics and agrochemical end-uses represent the fastest-expanding demand pools as formulators replace petroleum-derived emollients and adjuvants with bio-based alternatives.
REACH registration requirements in Europe mandate full toxicological dossiers for isoprenoid alcohol imports above one-tonne thresholds, directly shaping supplier qualification timelines. China's NMPA and SAMR enforce pharmaceutical intermediate GMP standards that constrain spot-market sourcing for drug-manufacturing customers. ISO 17025 analytical certification has become a baseline requirement for distributor acceptance across regulated end-uses. Stakeholders must monitor fermentation yield improvements and regulatory reciprocity agreements to assess which production geographies will capture margin expansion from tightening purity mandates.
Market Dynamics
Fermentation yield improvements are compressing unit economics for microbial-derived nonaisoprenol, enabling domestic producers in China and India to challenge incumbent semi-synthetic suppliers on cost and optical purity simultaneously.
Growth Catalysts
- REACH registration thresholds:ECHA's one-tonne import dossier requirements favor qualified suppliers with existing toxicological data, accelerating customer consolidation toward certified producers.
- Agrochemical formulators:Crop protection manufacturers in Brazil and India are substituting petroleum-derived adjuvants with bio-based isoprenoid alcohols to meet residue limits in export markets.
- Continuous flow chemistry:Adoption of flow reactors for terpenoid coupling reactions is expanding addressable volume for liquid-grade nonaisoprenol intermediates.
Market Restraints
- Sugar feedstock volatility:Corn and molasses price swings directly impact fermentation economics, squeezing margin buffers for non-captive producers without long-term agricultural supply contracts.
- Zhejiang cluster concentration:Over half of Asian pharmaceutical-grade capacity sits within a 200-kilometer radius, creating geographic risk exposure to regional environmental enforcement actions or logistics disruptions.
- Petroleum-derived farnesol competition:Synthetic C15 alcohols from naphtha cracking offer lower unit costs for fragrance applications where stereochemical precision matters less.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building dedicated isoprenoid intermediate suites to serve Western pharma outsourcing demand.
- EU Green Deal bio-based mandates:Cosmetic formulators face renewable content targets that create preferential procurement channels for fermentation-derived alcohols with verified carbon footprints.
- CRISPR strain engineering:Converging gene-editing tools with high-throughput metabolomics is opening pathways to 20%+ yield improvements in industrial yeast platforms.
Industry Challenges
- Optical purity certification timelines:ISO 17025 chiral chromatography validation for new production batches extends qualification cycles by 8-12 weeks, constraining spot-market responsiveness.
- Downstream integration complexity:Pharma customers require locked-down supply chains with audit rights over fermentation facilities, forcing capital-intensive GMP retrofits on intermediate producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonaisoprenol Market |
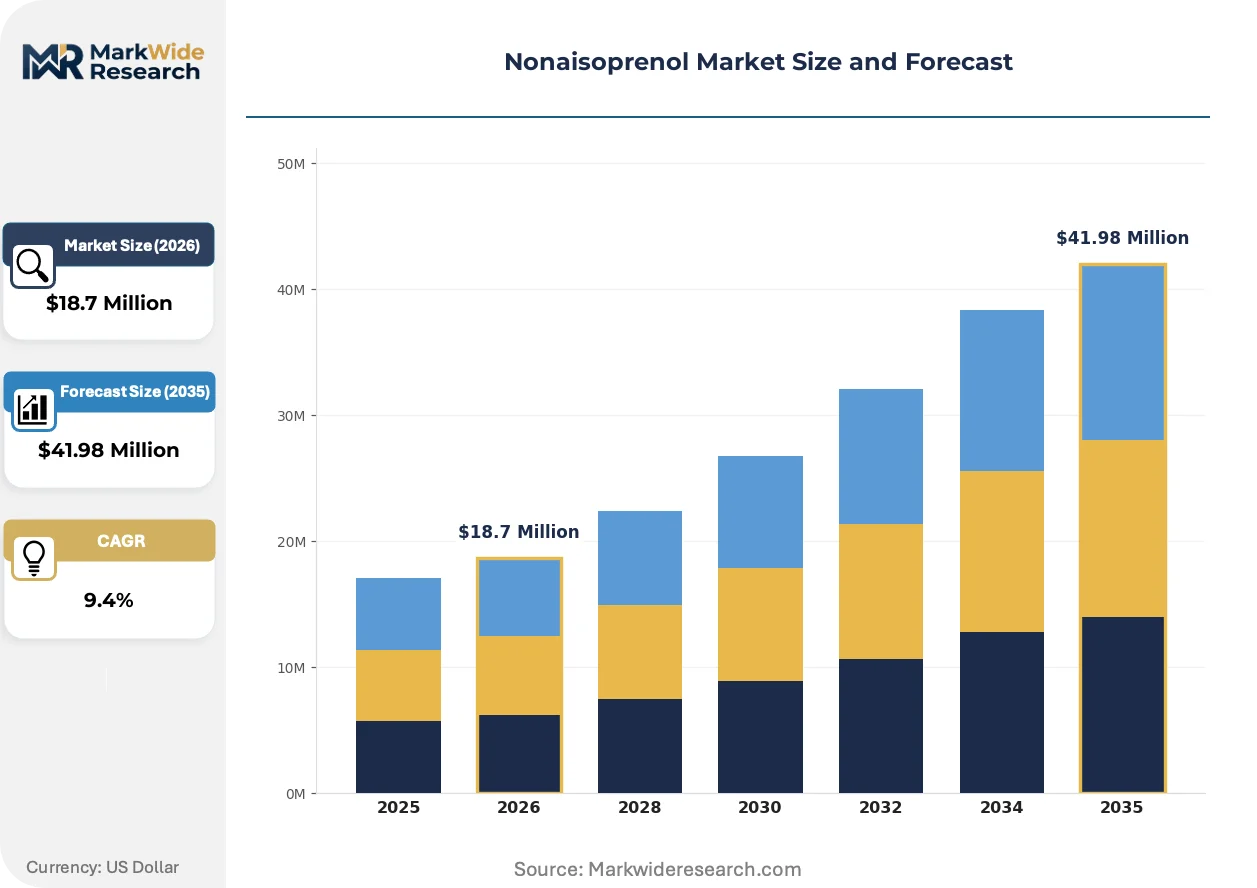
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Emulsion, Granule Application: Cosmetics, Pharmaceuticals, Agrochemicals, Food Additives Form: Raw Material, Intermediate, Finished Product, Blends End User: Manufacturers, Distributors, Retailers, Research Institutions |
| Companies Covered | Sigma-Aldrich, ExtRx Corporation, Zhejiang Yixin Pharmaceutical Co., Ltd., TCI Chemical, Toronto Research Chemicals, Sanming Huajian Bioengineering, BASF SE, Spectrum Chemical Manufacturing Corp., Tokyo Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonaisoprenol Market Evolving Landscape
Microbial engineering advances are collapsing the cost premium between fermentation-derived and petrochemical routes, while regulatory frameworks in Europe and Asia are hardening purity verification requirements.
Precision fermentation using engineered Yarrowia lipolytica strains is collapsing the historical 40-60% cost gap against semi-synthetic extraction from plant essential oils. Agrochemical formulators in Brazil and Southeast Asia are adopting these microbial grades for pyrethroid precursor synthesis. The technology is collapsing barriers to entry for mid-scale producers who previously lacked access to tropical plantation feedstocks.
REACH Annex VIII extended one-generation reproductive toxicity study requirements now apply to isoprenoid alcohol imports above 10 tonnes annually, extending registration timelines by 18-24 months for new market entrants. The regulation is forcing Chinese and Indian exporters to pre-position EU-based legal entities and testing consortium memberships. Fragrance compounders with existing REACH dossiers are capturing incremental market share from spot-market traders lacking compliance infrastructure.
Direct procurement contracts between fermentation facilities and pharmaceutical CDMOs are displacing traditional distributor intermediaries for volumes above 500 kilograms annually. CDMOs in Germany and Switzerland now require batch-specific carbon-14 dating and isotopic fingerprinting to verify bio-based content claims. This pattern is most visible in vitamin E analog synthesis, where Swiss and German pharma manufacturers have eliminated two distribution layers since 2022.
Nonaisoprenol Market Segmentation
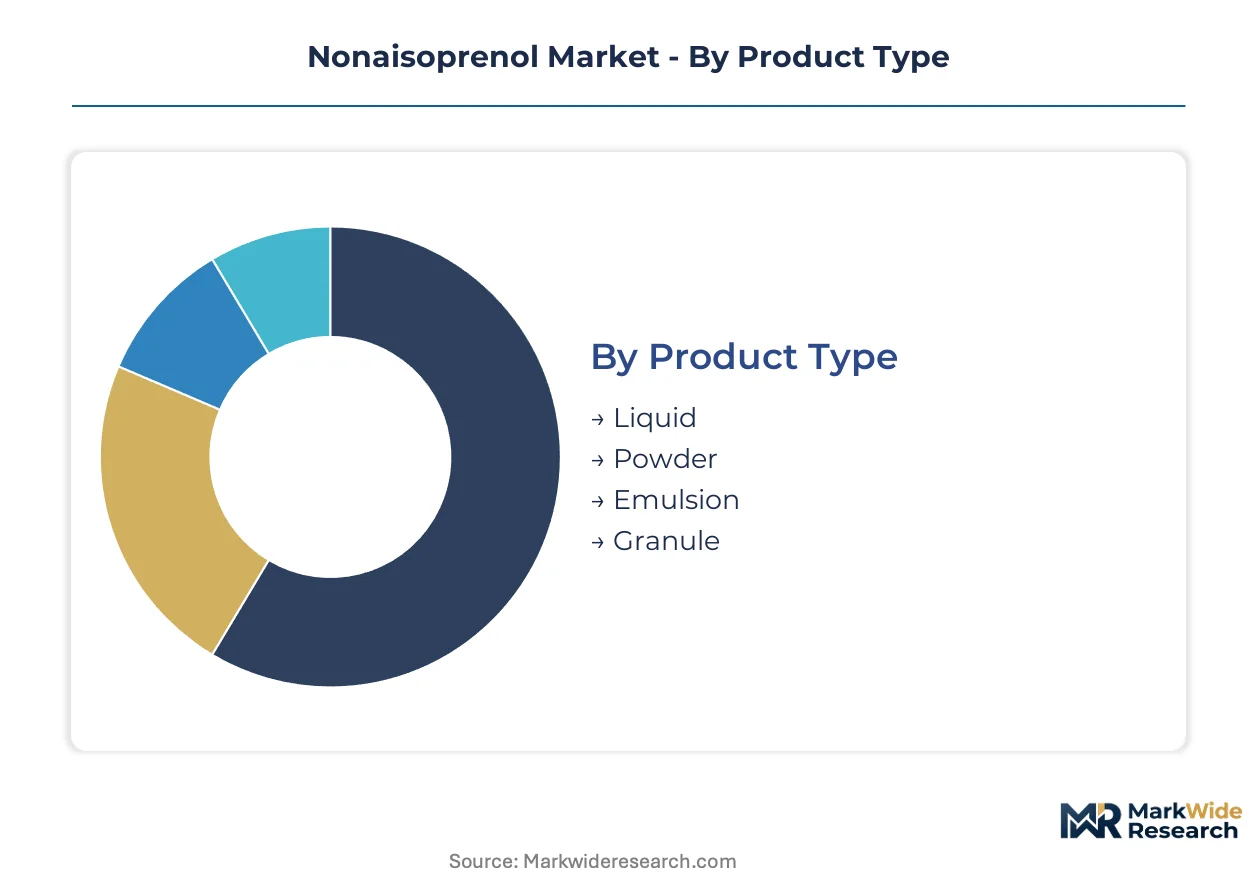
Nonaisoprenol procurement patterns diverge sharply across product grades and end-use specifications. Pharmaceutical formulators prioritize optical purity certification while agrochemical buyers optimize for fermentation yield economics.
Product Type:
Physical form dictates handling protocols, stability requirements, and margin capture across the value chain.
- Liquid:Dominates continuous chemical processing with simplified metering and dissolution characteristics. Agrochemical manufacturers in Brazil and India specify liquid grades for pyrethroid precursor synthesis, though cold-chain logistics constrain remote sourcing.
- Powder:Commands premium positioning through moisture-sensitive stability protocols and extended shelf life. Swiss and German pharmaceutical CDMOs require powder grades for vitamin E analog manufacturing with locked-down GMP supply chains.
- Emulsion:Serves cosmetic formulators seeking pre-dispersed bioactive delivery systems with reduced processing steps.
- Granule:Targets specialty food additive applications requiring controlled-release functionality and dust-free handling.
Established volume favors liquid; emerging adoption favors powder.
Application:
End-use chemistry determines purity thresholds, regulatory pathways, and supplier qualification intensity.
- Cosmetics:EU Green Deal renewable content mandates are accelerating procurement of fermentation-derived grades with verified carbon footprints. Formulators face binding bio-based targets that exclude petroleum-derived alternatives.
- Pharmaceuticals:NMPA and SAMR enforce GMP standards for vitamin E analog intermediates, constraining spot-market sourcing. CDMOs require batch-specific isotopic fingerprinting and audit rights over fermentation facilities.
- Agrochemicals:Expanding most quickly as Brazilian and Southeast Asian formulators substitute petroleum-derived adjuvants to meet export residue limits.
- Food Additives:Faces stringent toxicological dossier requirements under EFSA novel food regulations, limiting supplier pool to established REACH registrants.
Pharmaceuticals anchor current revenue; agrochemicals are climbing the fastest.
Form:
Supply chain position determines capital intensity, margin distribution, and customer integration depth.
- Raw Material:Fermentation-derived C9 alcohol with specified stereochemistry serves as feedstock for multi-step terpenoid synthesis. Chinese domestic producers scale microbial routes to serve regional fine-chemical networks.
- Intermediate:Partially functionalized derivatives for fragrance and crop protection actives requiring defined chiral centers.
- Finished Product:Pharmaceutical-grade nonaisoprenol meeting USP/EP monograph specifications for direct formulation use.
- Blends:Pre-formulated mixtures with co-solvents or stabilizers for cosmetics compounders seeking reduced processing complexity.
Intermediate form captures widest volume; finished product commands steepest margin expansion.
End User:
Procurement scale and technical capability shape channel structure and pricing negotiation leverage.
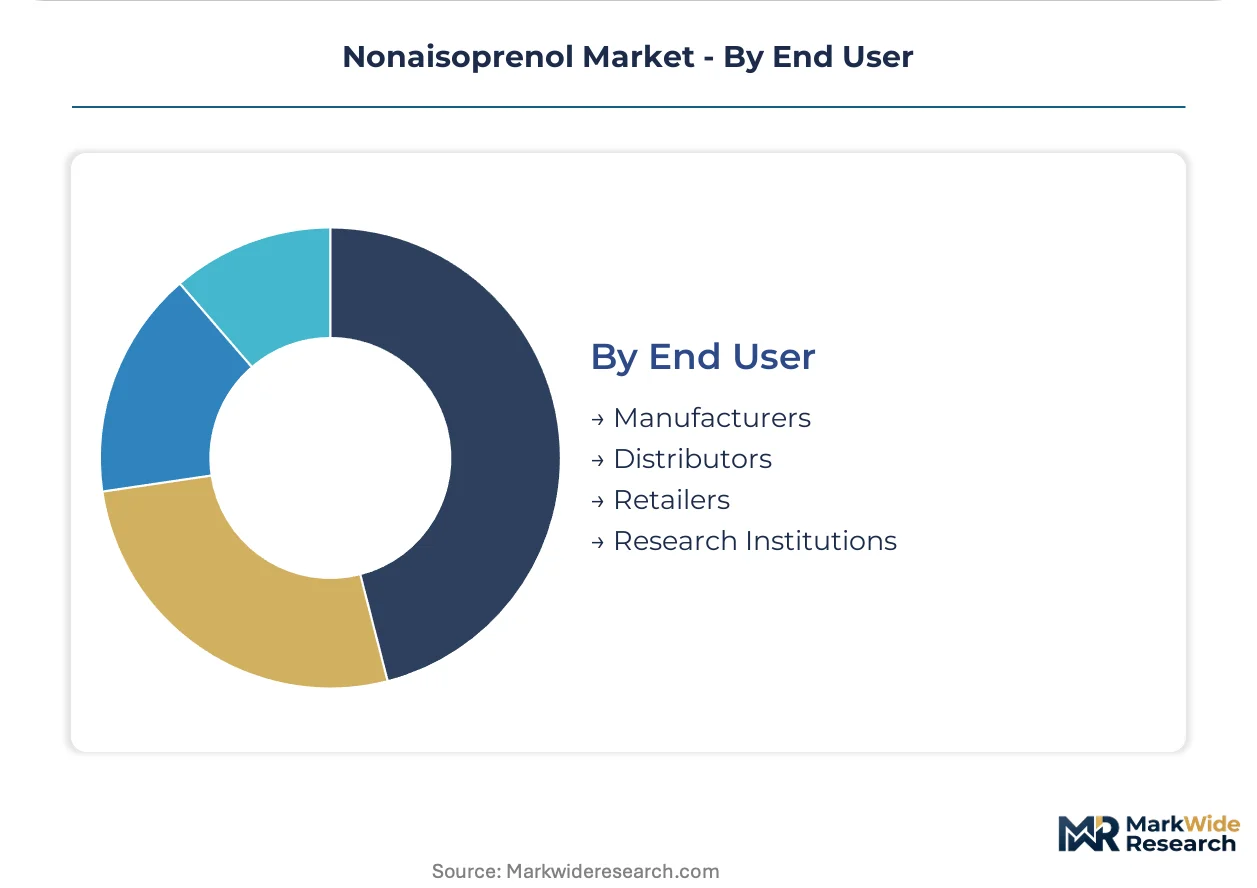
- Manufacturers:Direct fermentation facility contracts above 500 kilograms annually displace traditional distributor layers. CDMOs in Hyderabad and Ahmedabad build dedicated isoprenoid suites for Western pharma outsourcing.
- Distributors:ISO 17025 analytical certification has become baseline for acceptance across regulated end-uses, constraining spot-market traders.
- Retailers:Minimal direct engagement given technical specification complexity and batch certification requirements.
- Research Institutions:Sigma-Aldrich competes on catalog breadth and analytical certification, sustaining premium positioning for gram-scale procurement.
Manufacturers drive volume consolidation; research institutions sustain premium catalog positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical CDMOs in Germany and Switzerland anchor premium-grade procurement, while agrochemical formulators in Brazil and Southeast Asia drive volume expansion for fermentation-derived grades.
China
Domestic fine-chemical producers scale microbial fermentation routes to serve regional vitamin E analog and fragrance precursor supply chains. SAMR enforces pharmaceutical intermediate GMP standards that constrain spot-market sourcing for drug-manufacturing customers. The Zhejiang province cluster concentrates over half of Asian pharmaceutical-grade capacity within a 200-kilometer radius.
Germany
Swiss and German pharmaceutical manufacturers eliminated two distribution layers since 2022 through direct fermentation facility contracts above 500 kilograms annually. REACH Annex VIII extended one-generation reproductive toxicity study requirements apply to isoprenoid alcohol imports above 10 tonnes annually. The Rhine-Ruhr industrial corridor hosts CDMOs requiring batch-specific carbon-14 dating and isotopic fingerprinting.
Brazil
Crop protection manufacturers substitute petroleum-derived adjuvants with bio-based isoprenoid alcohols to meet residue limits in export markets. ANVISA enforces import registration requirements for agrochemical intermediates that favor qualified suppliers with existing toxicological data. São Paulo state anchors pyrethroid precursor synthesis demand for regional formulators.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad build dedicated isoprenoid intermediate suites to serve Western pharma outsourcing demand. CDSCO aligns pharmaceutical intermediate standards with ICH guidelines, extending qualification timelines for new suppliers. The Gujarat pharmaceutical cluster scales fermentation-derived production for regional agrochemical networks.
Switzerland
Swissmedic enforces GMP standards for vitamin E analog intermediates that require locked-down supply chains with audit rights over fermentation facilities. Swiss pharmaceutical CDMOs command powder grades with moisture-sensitive stability protocols and extended shelf life. The Basel biopharma corridor concentrates procurement leverage for high-purity chiral building blocks.
Nonaisoprenol Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. BASF SE leverages backward integration into microbial strain development to secure cost-advantaged feedstock positions. Three strategic archetypes dominate: integrated chemical conglomerates with fermentation capabilities, dedicated pharmaceutical-grade producers serving CDMO networks, and catalog distributors competing on analytical certification breadth. Capacity expansion in precision fermentation and strategic partnerships for REACH compliance infrastructure represent the dominant competitive moves.
Among German-integrated chemical conglomerates, BASF SE occupies a position exemplifying backward integration into microbial strain development. Zhejiang Yixin Pharmaceutical Co., Ltd. anchors the dedicated pharmaceutical-grade producer archetype through production lines serving CDMO networks. Sigma-Aldrich sits within the catalog distributor tier, representing premium positioning based on analytical certification and research institution procurement relationships.
| Leading Market Players |
|---|
| Sigma-Aldrich |
| ExtRx Corporation |
| Zhejiang Yixin Pharmaceutical Co., Ltd. |
| TCI Chemical |
| Toronto Research Chemicals |
| Sanming Huajian Bioengineering |
| BASF SE |
| Spectrum Chemical Manufacturing Corp. |
| Tokyo Chemical Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor carries fermentation-derived nonaisoprenol cargoes whose freight cost swings directly amplify price spreads between Zhejiang cluster producers and European pharmaceutical CDMOs. This logistics chokepoint concentrates pricing power with integrated suppliers possessing cold-chain capabilities, while spot-market traders absorb margin compression from sugar feedstock volatility and extended ISO 17025 certification timelines.
Pricing Analysis
Cost-plus contracts indexed to corn and molasses futures dominate procurement above 500 kilograms annually, with BASF and Zhejiang Yixin anchoring long-term offtake agreements. Price differentiation rests on optical purity certification and GMP audit rights, with pharmaceutical grades commanding substantial premiums over agrochemical specifications. Pricing pressure stems from petroleum-derived farnesol competition in fragrance applications where stereochemical precision matters less. Agrochemical formulators in Brazil and India exhibit highest price sensitivity, while Swiss CDMOs prioritize supply security over unit cost.
Supply Chain Analysis
Upstream corn and molasses feedstock markets in China, India, and Brazil anchor fermentation economics for nonaisoprenol production. Raw material dependencies center on agricultural sugar streams, engineered Yarrowia lipolytica strains, and chiral chromatography reagents for optical purity verification. Single-source vulnerability concentrates in the Zhejiang province cluster, where environmental enforcement actions or logistics disruptions threaten over half of Asian pharmaceutical-grade capacity. Distribution runs through direct fermentation facility contracts for manufacturers above volume thresholds, with Sigma-Aldrich and TCI Chemical serving research-scale procurement through certified catalog channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce CRISPR strain engineering capabilities and locked-down GMP supply chains separate viable competitors from marginal players in this market. Mastery of high-throughput metabolomics platforms represents the critical asset gap determining long-term positioning.
For Market Incumbents: Build regulatory moats through REACH Annex VIII dossier completion and EU-based legal entity pre-positioning. BASF should deepen backward integration into microbial strain development to defend against yield improvements from emerging Chinese producers. Incumbents must secure long-term agricultural supply contracts to buffer sugar feedstock volatility squeezing non-captive producers. For New Entrants and Emerging Players: Build out dedicated isoprenoid intermediate suites serving Hyderabad and Ahmedabad CDMO networks before Western pharma outsourcing demand saturates. The most penetrable white space sits in fermentation-derived grades for Brazilian agrochemical formulators seeking bio-based adjuvants. A precision fermentation platform with verified carbon footprints unlocks EU Green Deal procurement channels closed to petroleum-derived alternatives. For Investors and Strategic Acquirers: Precision fermentation specialists with existing ISO 17025 certification and CDMO audit relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on 20%+ yield improvements from CRISPR strain engineering reaching commercial scale. Watch for fermentation yield breakthroughs collapsing the cost premium against semi-synthetic extraction as the inflection signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Engineered Yarrowia lipolytica platforms collapse the 40-60% cost gap against plant extraction routes. |
| REACH Compliance Infrastructure | ECHA dossier completion and EU legal entity pre-positioning lock out spot-market traders from 10+ tonne volumes. |
| CDMO Supply Chain Integration | Direct fermentation facility contracts above 500 kilograms annually eliminate distributor margin layers. |
| Carbon-14 Verification Capability | Batch-specific isotopic fingerprinting meets Swiss and German pharma requirements for bio-based content claims. |
| CRISPR Strain Engineering Partnership | Gene-editing collaborations with academic metabolomics labs accelerate pathway to 20%+ yield improvements. |
Research Methodology
A standing panel of fermentation plant managers, pharmaceutical procurement leads at CDMOs, agrochemical formulators, and analytical certification specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from ECHA registration databases, SAMR GMP inspection records, customs trade data for isoprenoid alcohol flows, and SEC filings from integrated chemical conglomerates. Bottom-up volume estimates from identified production facilities triangulated against top-down demand aggregation from end-use applications.
Scenario-bracketing around sugar feedstock price bands, fermentation yield improvement trajectories, and regulatory reciprocity timelines bounded the projection envelope. Segmentation dimensions modeled include physical form, end-use application, supply chain position, and geographic production hub. CAGRs derived from fitted growth curves incorporating capacity expansion announcements, CDMO contract awards, and REACH registration timelines. Industry-specific forecast inputs encompassed CRISPR strain engineering adoption curves and EU Green Deal bio-based mandate implementation schedules.
Stress conditions across corn and molasses price volatility, Zhejiang cluster environmental enforcement intensity, and REACH Annex VIII timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fermentation yield improvements and regulatory reciprocity agreements. Cross-checking against ECHA registration progression and CDSCO GMP inspection outcomes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
N-Propanol Market
Chemicals
Solder Flux Market
Chemicals
Global Amines Market
Chemicals
Power Plant Chemicals Market
Chemicals
Whitening Ingredients Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Global Butanediol Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Photographic Chemicals Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Elemental Fluorine Market
Chemicals
Global Syringaldehyde Market
Chemicals
Methanol to Gasoline Market
Chemicals
Amine Oxide Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market