
 Cyclopentylamine Market | 2026-2036
Cyclopentylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclopentylamine Market Outlook
Technical-grade specification services is restructuring procurement patterns for cyclopentylamine buyers who now contract for certified purity tiers rather than commodity spot purchases. BASF SE leverages its integrated amine platform to sustain supply security for European pharmaceutical customers. Evonik Industries anchors its position through specialized high-purity grades that differentiate it in pharmaceutical intermediate applications. Sumitomo Chemical competes on manufacturing scale across Asian agrochemical channels.
Cyclopentylamine is a primary aliphatic amine with formula C5H11N, typically synthesized via catalytic hydrogenation of cyclopentanone oxime or reductive amination routes, and serves as a critical building block for pesticides, pharmaceuticals, and rubber chemicals. The compound's primary industrial purpose centers on its nucleophilic amine functionality, which enables cyclization and coupling reactions in active ingredient synthesis. Pharmaceutical intermediates command premium positioning due to stringent pharmacopeial compliance requirements, while pesticide applications occupy higher volume tiers with thinner margins. Cyclopentylamine hydrochloride salt forms dominate formulation-ready segments where handling stability and solubility parameters matter most.
EPA registration requirements for pesticide precursors and REACH substance authorization in Europe shape product specifications and market access conditions for cyclopentylamine suppliers. China's MEE environmental compliance audits and India's CDSCO pharmaceutical chemical standards add parallel regulatory layers that manufacturers must navigate simultaneously. Stakeholders should monitor how tightening purity thresholds and carbon-intensity disclosures reshape supplier qualification criteria across end-use sectors.
Market Dynamics
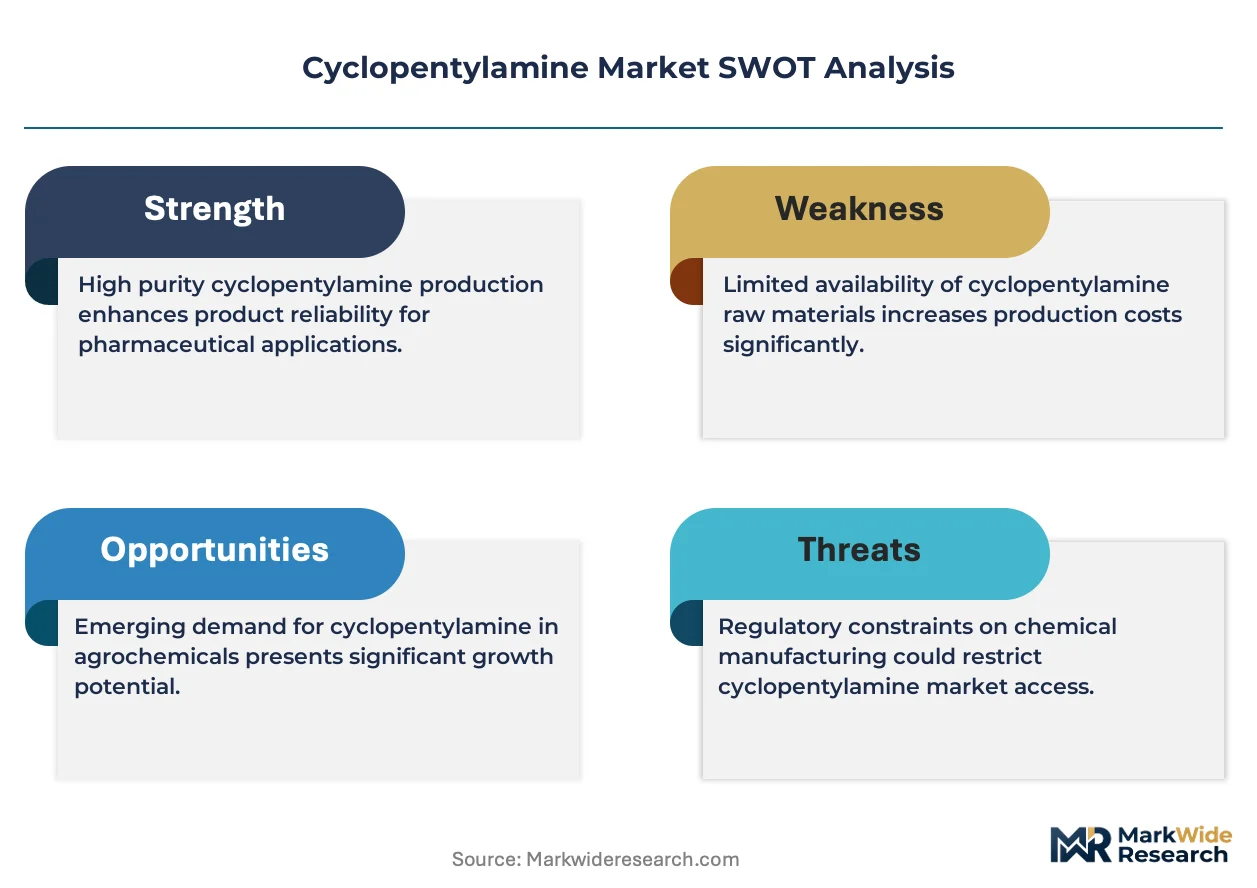
Pharmaceutical intermediate specifications are tightening purity thresholds faster than production capacity can adapt, forcing cyclopentylamine suppliers to requalify existing assets or exit high-margin segments entirely.
Growth Catalysts
- REACH substance authorization:European pharmaceutical manufacturers now require certified impurity profiles for all amine precursors, creating premium tier demand that rewards compliant suppliers with multi-year contracts.
- Agrochemical formulation expansion:India's CDSCO-registered contract manufacturers are scaling cyclopentylamine derivatives for export-oriented pesticide synthesis, absorbing regional production surpluses.
- Catalytic hydrogenation yield improvements:Continuous-flow reactor adoption is compressing batch cycle times and reducing solvent waste volumes in cyclopentanone oxime conversion.
Market Restraints
- Cyclopentanone feedstock volatility:Petroleum-derived ketone prices track naphtha spreads, exposing amine producers to margin compression without pass-through contract structures.
- Jiangsu-Zhejiang supply concentration:Over half of technical-grade cyclopentylamine originates from China's eastern chemical belt, creating single-point vulnerability to MEE environmental enforcement actions.
- Reductive amination technical ceiling:Selectivity limits in direct amination routes cap yields below catalytic hydrogenation benchmarks, constraining process flexibility.
Strategic Opportunities
- Brazilian agrochemical import substitution:ANVISA registration pathways for locally synthesized amine precursors could displace Chinese import dependence in Latin American pesticide formulation.
- Biocatalytic amination convergence:Transaminase enzyme platforms paired with immobilized cell reactors promise ambient-pressure synthesis routes with reduced carbon intensity disclosures.
- PLI scheme pharmaceutical chemicals:India's production-linked incentive framework subsidizes capital investment in active pharmaceutical ingredient intermediates, attracting greenfield cyclopentylamine capacity.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF and EP monograph compliance for cyclopentylamine hydrochloride requires 18-24 month validation cycles that delay commercialization.
- Specialized amine handling expertise:Moisture-sensitive primary amine storage and toxic vapor containment demand process safety engineering talent that chemical manufacturers struggle to recruit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclopentylamine Market |
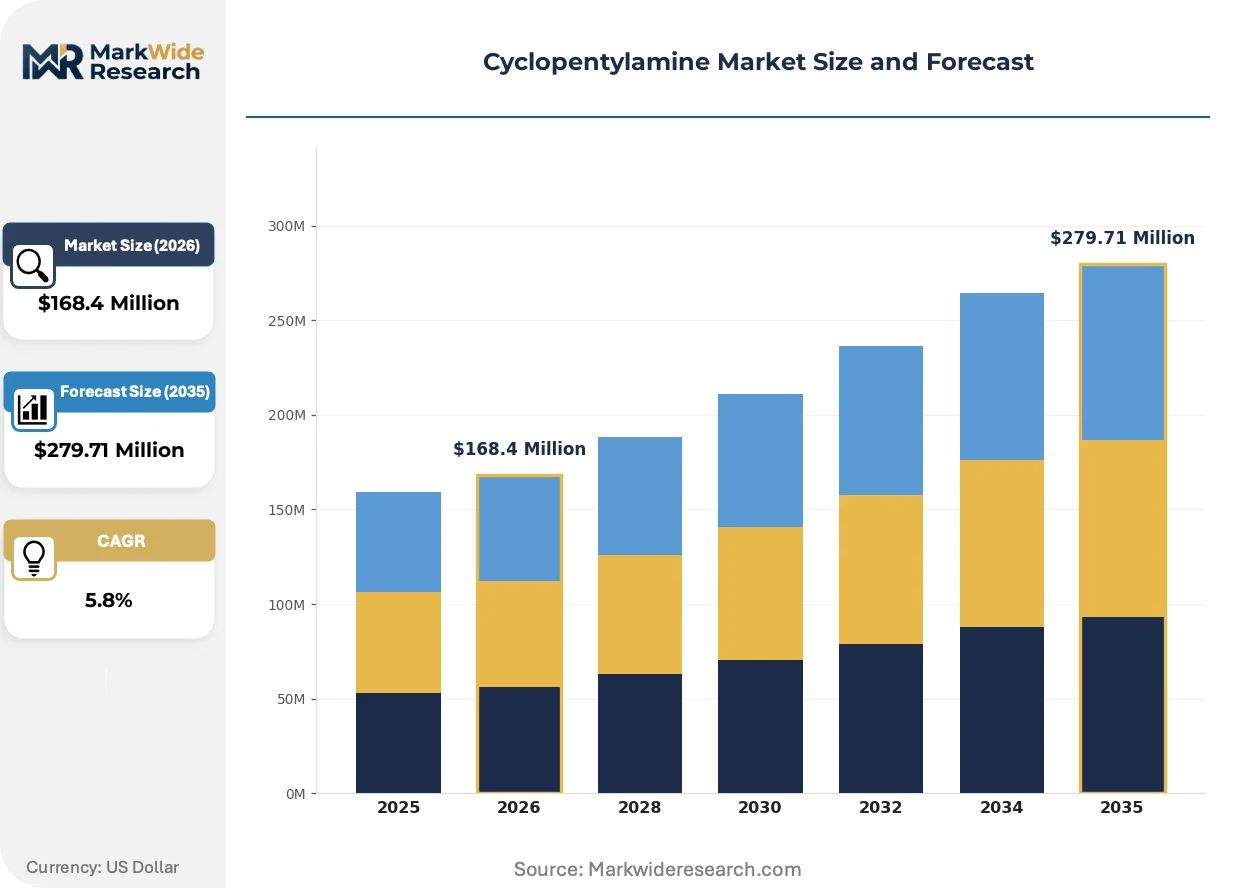
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $279.71 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclopentylamine Hydrochloride, Cyclopentylamine Sulfate, Cyclopentylamine Nitrate, Cyclopentylamine Acetate End Use Industry: Agriculture, Pharmaceuticals, Chemical Manufacturing, Food Additives Form: Liquid, Solid, Powder, Solution Application: Pesticide, Intermediates, Pharmaceutical Formulations, Additives |
| Companies Covered | BASF SE, Evonik Industries, Merck KGaA, Lanxess, Solvay, Sumitomo Chemical, Vinati Organics, Shandong Hualu Hengsheng Chemical, Hubei Xingfa Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclopentylamine Market Strategic Shifts
Process intensification and regulatory disclosure requirements are converging to reshape how cyclopentylamine is manufactured, certified, and procured across pharmaceutical and agrochemical value chains.
Continuous-flow catalytic hydrogenation is unifying reaction, separation, and purification stages into single-unit operations that pharmaceutical contract manufacturers are adopting to compress batch release timelines. This integration eliminates intermediate storage of pyrophoric catalyst slurries and enables real-time impurity monitoring that satisfies FDA process analytical technology guidance.
REACH Article 33 extended supply chain disclosure obligations now require downstream formulators to document Substances of Very High Concern in pesticide and pharmaceutical precursors above 0.1% w/w thresholds. European agrochemical distributors are demanding certified analytical data packages from cyclopentylamine suppliers, shifting procurement qualification from spot testing to supplier quality system audits.
Certified purity tier contracting is displacing commodity spot purchasing as large pharmaceutical intermediates buyers consolidate supplier panels and negotiate multi-year offtake agreements with guaranteed impurity specifications. This concentration is most visible among German and Swiss active pharmaceutical ingredient manufacturers who now source cyclopentylamine exclusively through qualified supplier lists rather than merchant markets.
Cyclopentylamine Market Segmentation
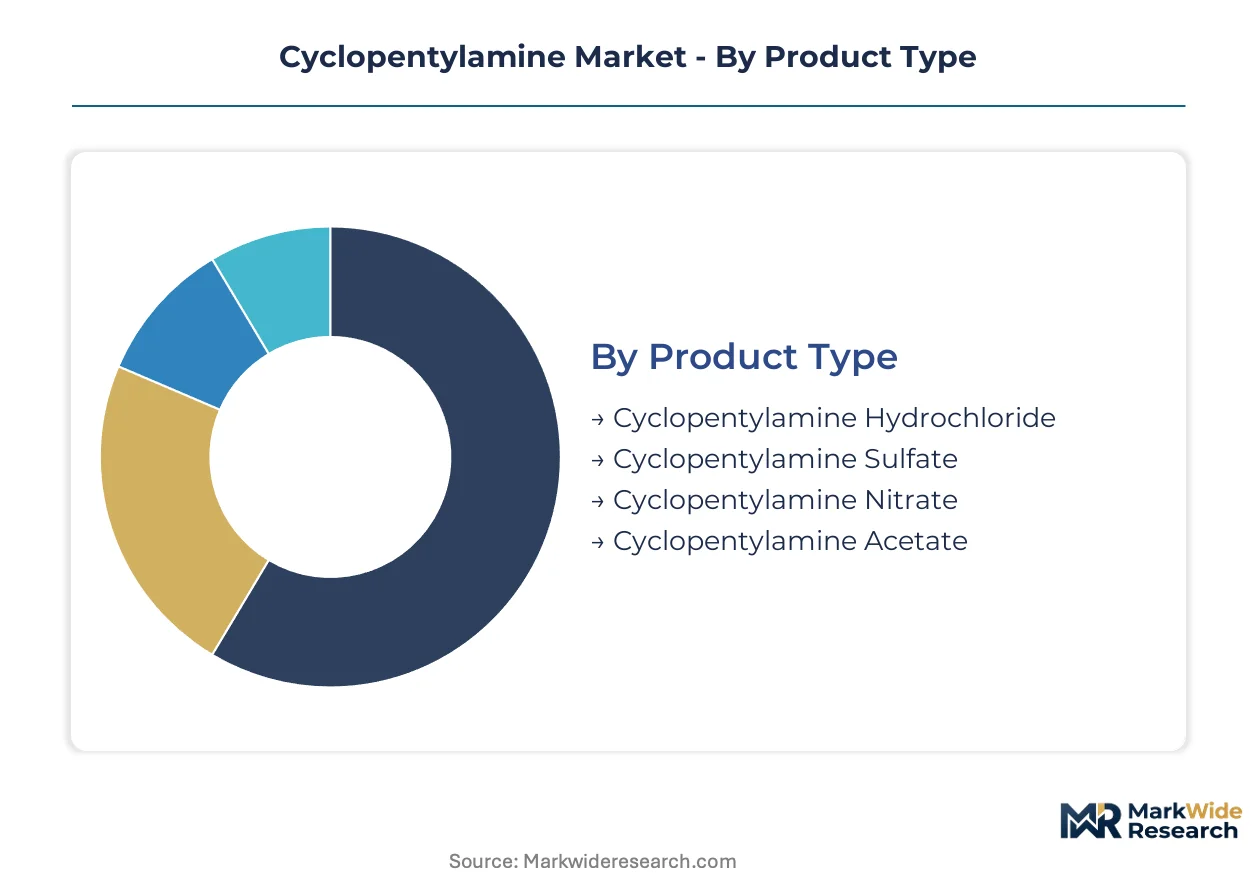
Cyclopentylamine procurement decisions hinge on impurity tolerances and handling requirements that vary sharply across pharmaceutical versus agrochemical channels. Buyers now segment suppliers by certified purity tiers rather than accepting commodity-grade material, forcing producers to qualify assets for specific end-use specifications.
Product Type:
Certification grade determines contract pricing and supplier qualification timelines for pharmaceutical versus technical applications.
- Cyclopentylamine Hydrochloride:Salt form delivers superior moisture stability and handling safety for active pharmaceutical ingredient synthesis. Demand concentrates among German and Swiss contract manufacturers who require USP-NF or EP monograph compliance for nucleophilic coupling reactions in cardiovascular and central nervous system drug pipelines.
- Cyclopentylamine Sulfate:Alternative salt specification offers modified solubility parameters for aqueous formulation environments. Agrochemical formulators in India and Brazil specify sulfate grades for pesticide suspension concentrates where ionic compatibility with adjuvant systems matters.
- Cyclopentylamine Nitrate:Specialized oxidizer-compatible grade serves energetic materials and specialty chemical synthesis with controlled thermal stability profiles.
- Cyclopentylamine Acetate:Organic salt variant provides pH-buffered environments for biocatalytic amination processes and enzyme-coupled synthesis routes.
Volume sits with Cyclopentylamine Hydrochloride; growth tilts toward Cyclopentylamine Sulfate as agrochemical channels expand in Latin America and South Asia.
End Use Industry:
Regulatory burden intensity separates margin structures across these verticals, with pharmaceutical compliance costs recouped through multi-year offtake premiums.
- Pharmaceuticals:Active pharmaceutical ingredient intermediates command pharmacopeial-grade material with certified impurity profiles below 0.1% thresholds. REACH substance authorization and FDA process analytical technology guidance force 18-24 month qualification cycles that lock in qualified suppliers.
- Agriculture:Pesticide precursor applications absorb higher volumes at thinner margins, with EPA registration and ANVISA compliance requirements varying by end-market geography. India's CDSCO-registered contract manufacturers are scaling derivative production for export-oriented synthesis.
- Chemical Manufacturing:Rubber chemical and polymer additive applications utilize technical-grade specifications with less stringent analytical certification, concentrating procurement among Chinese and Indian merchant producers.
- Food Additives:Niche segment requiring FSSAI or FDA food contact compliance for specific flavor precursor applications with limited volume contribution.
Margin concentrates in Pharmaceuticals; volume expansion is accelerating most quickly in Agriculture as Brazilian and Indian agrochemical formulation capacity scales.
Form:
Logistics infrastructure and moisture sensitivity dictate form selection for long-haul supply chains versus just-in-time pharmaceutical delivery.
- Liquid:Bulk tanker delivery suits high-volume agrochemical channels with dedicated storage and handling infrastructure at formulation plants.
- Solid:Crystalline or flake form enables extended shelf stability for pharmaceutical intermediate shipments requiring precise dosing in batch synthesis.
- Powder:Micronized specification serves rapid-dissolution requirements in continuous-flow reactor feeding systems and powder blending operations.
- Solution:Pre-dissolved aqueous or solvent-based preparations eliminate on-site handling of pyrophoric neat material for smaller-scale pharmaceutical contract manufacturers.
Procurement weighting favors Solid for pharmaceutical security of supply; Solution formats are gaining share fastest among mid-scale contract manufacturers lacking specialized amine handling infrastructure.
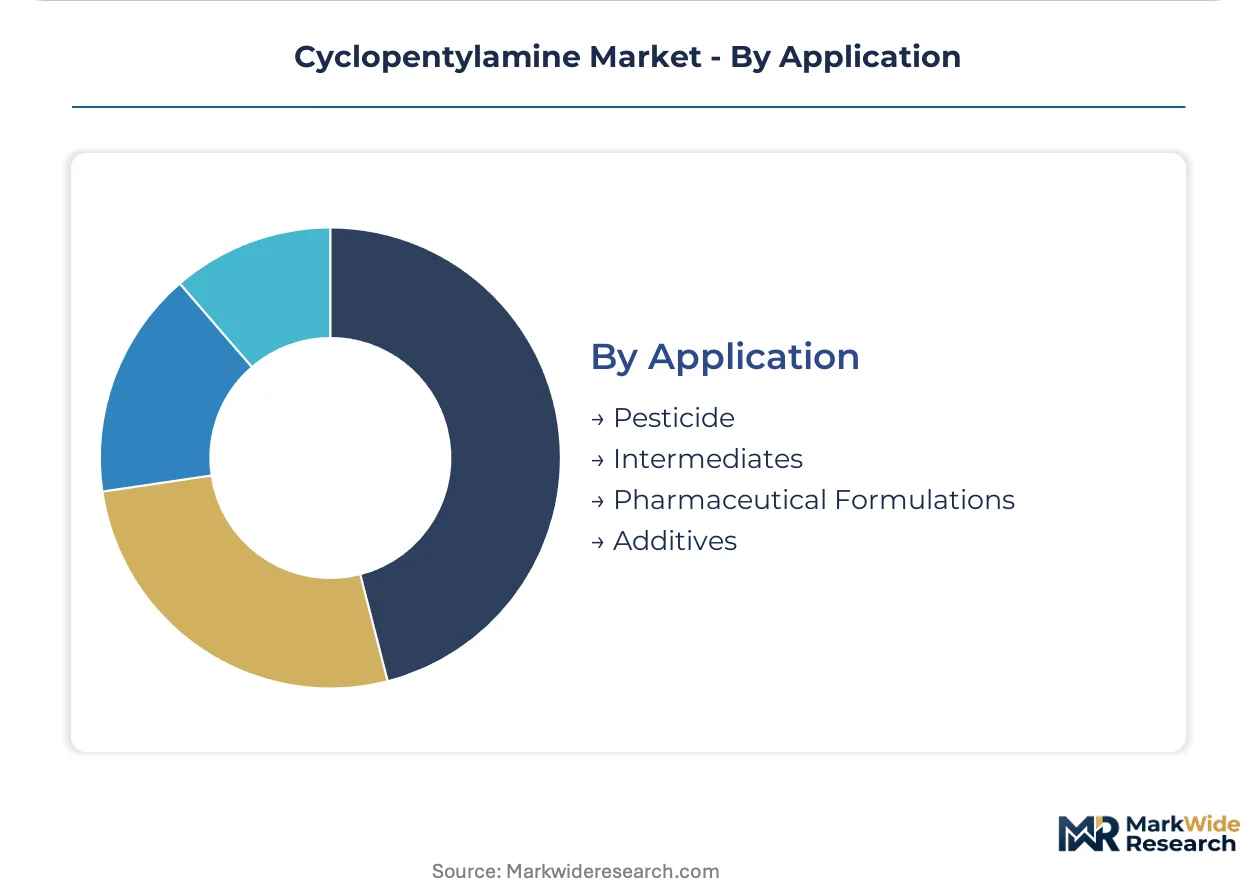
Application:
Functional chemistry requirements—cyclization versus coupling versus formulation—determine purity and specification thresholds.
- Intermediates:Building-block applications in multi-step synthesis demand consistent lot-to-lot quality for yield predictability in pharmaceutical and agrochemical active ingredient routes.
- Pesticide:Direct incorporation into herbicide and fungicide formulations requires stability under field storage conditions and compatibility with surfactant systems.
- Pharmaceutical Formulations:Final-dosage-form applications face the steepest purity barriers with full pharmacopeial monograph compliance and stability data packages.
- Additives:Rubber vulcanization accelerators and polymer processing aids utilize technical grades with performance-based rather than purity-based specifications.
Revenue pools deepest in Intermediates; Pharmaceutical Formulations are climbing the fastest as oncology and neurological drug pipelines expand nucleophilic amine coupling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of technical-grade cyclopentylamine while Germany, Switzerland, and the United States absorb premium pharmaceutical volumes. This production-consumption divide shapes logistics costs and supplier qualification requirements across major demand centers.
China
Jiangsu and Zhejiang provinces host concentrated cyclopentylamine capacity serving agrochemical and rubber chemical channels. MEE environmental audits forced facility upgrades and temporary closures in 2023-2024, tightening technical-grade supply. The Ningbo-Zhoushan chemical cluster now dominates export-oriented production with integrated cyclopentanone feedstock supply.
Germany
Pharmaceutical intermediate demand from Ludwigshafen and Leverkusen chemical corridors drives high-purity cyclopentylamine consumption. REACH substance authorization and ECHA compliance requirements lock qualified suppliers into multi-year contracts. BASF SE anchors domestic supply security through backward integration into captive amine production.
United States
EPA-registered pesticide precursor applications absorb steady volumes in Gulf Coast and Midwest formulation plants. FDA process analytical technology guidance shapes pharmaceutical procurement from New Jersey and Massachusetts active pharmaceutical ingredient developers. Domestic production remains limited, forcing reliance on import qualification programs.
India
CDSCO-registered contract manufacturers in Gujarat and Maharashtra scale cyclopentylamine derivative production for export-oriented pesticide synthesis. The PLI scheme subsidizes capital investment in pharmaceutical chemical intermediates, attracting greenfield amine capacity. Dahej and Mundra industrial zones concentrate new project announcements.
Brazil
ANVISA registration pathways for locally synthesized amine precursors could reduce Chinese import dependence in Latin American pesticide formulation. São Paulo state agrochemical distributors currently source technical-grade material through merchant markets. Domestic synthesis projects remain pre-commercial pending regulatory clarity.
Cyclopentylamine Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade supply, while commodity producers compete on cyclopentanone feedstock access and batch scale. The vendor base stratifies into three functional tiers: integrated petrochemical majors with captive ketone supply, specialized amine houses with pharmacopeial certification assets, and regional merchant producers serving technical applications. Consolidation pressure concentrates among mid-scale European and Asian players lacking REACH compliance infrastructure. Dominant competitive moves include backward integration into cyclopentanone production and multi-year offtake contracting with pharmaceutical intermediates buyers.
Among German chemical majors, BASF SE and Evonik Industries exemplify divergent positioning archetypes—BASF leverages integrated amine platform breadth while Evonik occupies specialized high-purity grades. Sumitomo Chemical represents Asian manufacturing scale across agrochemical channels. These three anchors illustrate how geographic origin and corporate structure map to competitive specialization in pharmaceutical versus technical-grade segments.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Merck KGaA |
| Lanxess |
| Solvay |
| Sumitomo Chemical |
| Vinati Organics |
| Shandong Hualu Hengsheng Chemical |
| Hubei Xingfa Chemicals |
| Others |
Value Chain & Pricing Dynamics
Continuous-flow reactor adoption is compressing unit production costs while simultaneously concentrating supply among capital-rich operators capable of financing integrated hydrogenation assets. This technological transition rewards pharmaceutical-grade producers with multi-year contract pricing power while squeezing technical-grade margins in China's eastern chemical belt.
Pricing Analysis
Margin tightening in technical-grade segments reflects cyclopentanone feedstock volatility tracking naphtha spreads. Three-tier pricing structure across pharmacopeial, technical, and commodity grades separates certified impurity profiles from spot-tested material. Cost-down pressure on agrochemical channels accelerates because Indian and Brazilian formulators consolidate supplier panels. Pharmaceutical intermediates buyers show lowest price sensitivity due to 18-24 month requalification barriers.
Supply Chain Analysis
Direct-to-formulator channels handle high-volume agrochemical demand while distributor-mediated procurement serves mid-scale pharmaceutical contract manufacturers. Supply concentrates in China, Germany, and India with Jiangsu-Zhejiang capacity dominating technical grades. Cyclopentanone oxime and catalytic hydrogenation catalysts constitute critical input dependencies. Single-source vulnerability in China's eastern chemical belt exposes buyers to MEE environmental enforcement disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocatalytic amination platforms are displacing legacy batch hydrogenation, creating asymmetric opportunity windows for technology-advantaged operators.
For Market Incumbents: Deepen backward integration into cyclopentanone production to insulate margins from petroleum-derived ketone volatility. Lock pharmaceutical customers through REACH-certified impurity profiling and multi-year offtake structures before biocatalytic rivals achieve pharmacopeial qualification. For New Entrants and Emerging Players: Contract research organizations in India and Brazil offer partnership pathways into pesticide precursor supply without capital-intensive hydrogenation assets. Target agrochemical formulation channels with sulfate-grade specifications where certification barriers remain lowest. For Investors and Strategic Acquirers: Re-rating potential sits with specialized amine houses possessing pharmacopeial certification infrastructure given REACH substance authorization tightening. Monitor ECHA compliance disclosure timelines as inflection indicators for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclopentanone | Captive ketone supply insulates BASF and Evonik from naphtha spread volatility. |
| Continuous-Flow Reactor Deployment | Real-time impurity monitoring satisfies FDA process analytical technology guidance. |
| REACH Certification Investment | ECHA substance authorization locks German pharmaceutical customers into multi-year contracts. |
| Biocatalytic Amination R&D | Transaminase platforms promise ambient-pressure synthesis with reduced carbon intensity disclosures. |
| Long-term Supply Agreement | Consolidated offtake structures displace spot purchasing among Swiss API manufacturers. |
Study Parameters
Multi-period observation of cyclopentanone feedstock spreads, MEE enforcement actions, and REACH certification timelines anchored the trend analysis, supplemented by interviews with plant managers at hydrogenation facilities, procurement leads at agrochemical formulators, pharmaceutical intermediate buyers, and distribution channel partners. Secondary validation drew from customs trade data, Cefic chemical industry reports, ECHA substance authorization databases, and SEC filings of listed chemical producers. Bottom-up capacity modeling and top-down demand segmentation were triangulated against cross-referenced sources.
Segment-weighting across grade tier, end-use industry, and regional production hub shaped the analytical framework. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements throughout the forecast period. Industry-specific inputs included pharmacopeial certification pipeline durations and agrochemical formulation capacity buildouts in India and Brazil.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration in China, abrupt feedstock price shocks, and biocatalytic technology commercialization timelines. Forecasts reflect assumptions about sustained REACH enforcement intensity and stable pharmaceutical pipeline activity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Formalin Vials Market
Chemicals
Barbituric Acid Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Japan Methanol Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Perchloric Acid Market
Chemicals
Global Cresols Market
Chemicals
Laboratory Chemicals Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Industrial Odor Management Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Methanol Market
Chemicals
Sodium Hydride Market
Chemicals
Global Organobromine Market
Chemicals
Carcinogenic Chemical Alternatives Market