
 Waterborne Curing Agents Market | 2026-2036
Waterborne Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Waterborne Curing Agents Market Analytics
Asset-light leasing models for specialty chemical production are tilting competitive dynamics toward firms that can access toll manufacturing without owning fixed assets. Evonik Industries leverages its multi-site European network to sustain flexible supply agreements for amine-based curing agents. Huntsman Corporation anchors its position through backward integration into epoxy intermediates, while BASF competes on proprietary polyamide dispersion technologies.
Waterborne curing agents are aqueous-phase compounds, typically amine-functional or polyamide-modified, that crosslink epoxy resins at ambient or elevated temperatures to form thermoset networks with adhesion ratings exceeding 5 MPa on steel substrates. Their primary purpose is to enable industrial coating and adhesive systems with near-zero volatile organic compound emissions. Polyamide dispersions command the widest margin pools in architectural coatings, whereas UV curing technology represents the fastest-expanding segment in automotive refinishing due to line-speed requirements. Amine-functional products dominate marine applications where pot life and corrosion resistance specifications remain stringent.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based alternatives, while REACH restricts specific amine hardeners in European formulations. China's MEE enforces comparable VOC limits in the Yangtze River Delta manufacturing corridor, reshaping import qualification criteria. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with regional compliance timelines.
Market Dynamics
Formulation chemistry is pivoting from solvent-borne to aqueous-phase systems as regulatory pressure on volatile organic compound emissions intensifies across manufacturing jurisdictions. This structural shift is compressing traditional curing agent margins while rewarding producers with dispersion technology capabilities and toll manufacturing flexibility.
Growth Catalysts
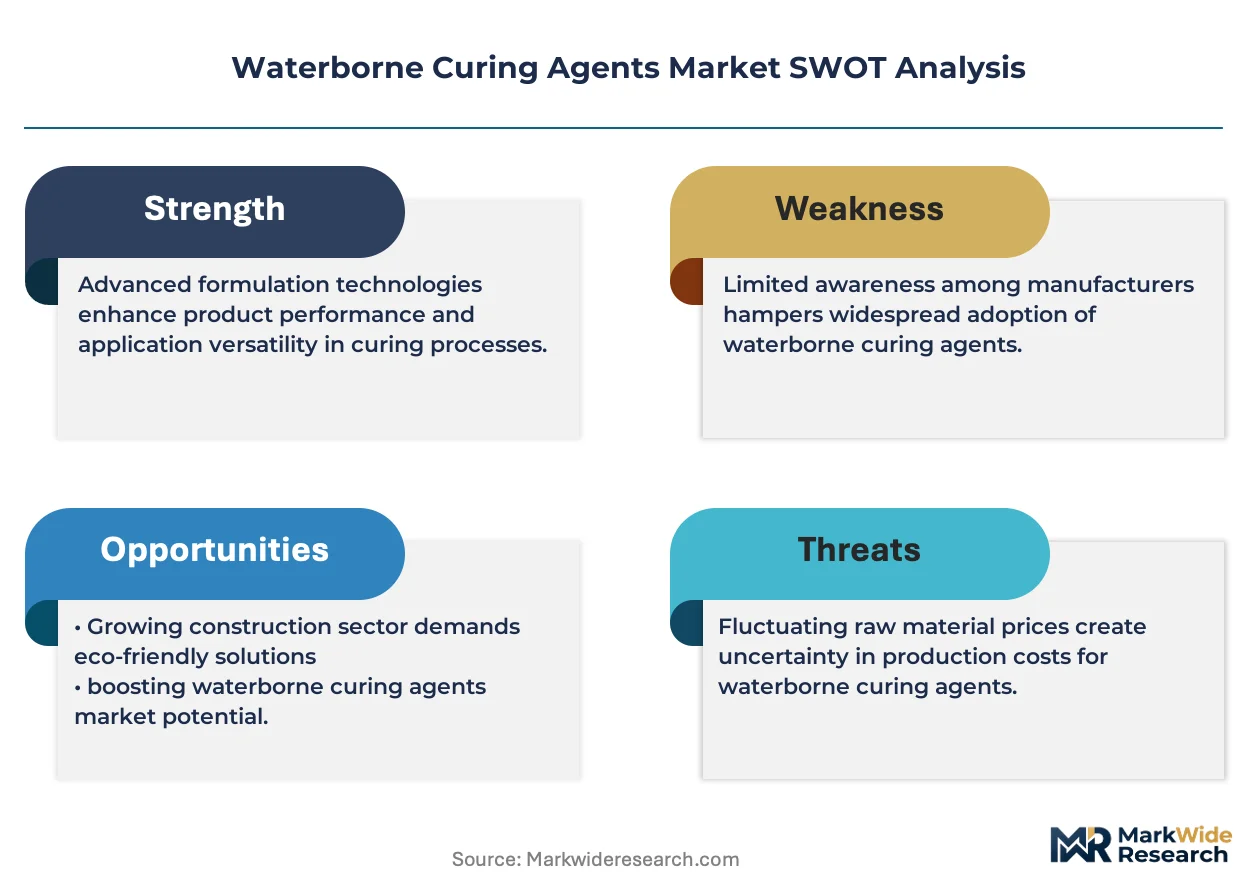
- REACH Phase-Out Mandates:ECHA restrictions on solvent-based hardeners in European industrial coatings are redirecting specification demand toward polyamide and amine-functional waterborne alternatives.
- Construction Coatings Specification:Architectural and protective coatings for infrastructure projects are adopting aqueous epoxy systems to meet site safety and environmental compliance requirements.
- Yangtze River Delta Manufacturing Corridor:China's MEE enforcement of VOC emission limits in Jiangsu and Zhejiang provinces is accelerating domestic production capacity for waterborne curing agents.
Market Restraints
- Epoxy Resin Price Volatility:Bisphenol-A and epichlorohydrin feedstock fluctuations create margin compression for curing agent producers without backward integration into intermediates.
- Technical Performance Gap:Waterborne systems exhibit reduced pot life and slower cure rates versus solvent-borne alternatives in sub-ambient temperature marine applications.
- Amine Hardener Substitution:Cycloaliphatic amine alternatives face regulatory friction under REACH substance evaluation procedures, constraining formulation flexibility.
Strategic Opportunities
- India Industrial Corridor Expansion:BIS adoption of VOC emission standards for protective coatings in Gujarat and Maharashtra creates qualification windows for imported waterborne technologies.
- UV-Waterborne Hybrid Convergence:Automotive refinishing lines are integrating aqueous base coats with UV-curable topcoats to achieve line-speed targets without solvent emissions.
- Asset-Light Toll Manufacturing:Specialty chemical leasing models enable mid-scale producers to access multi-site European production networks without fixed capital deployment.
Industry Challenges
- Formulation Chemist Shortage:Crosslinking chemistry expertise for aqueous-phase systems remains concentrated among legacy epoxy specialists, constraining R&D velocity.
- Dual Registration Burden:Separate EPA PMN and REACH dossier requirements for new amine-functional products extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterborne Curing Agents Market |
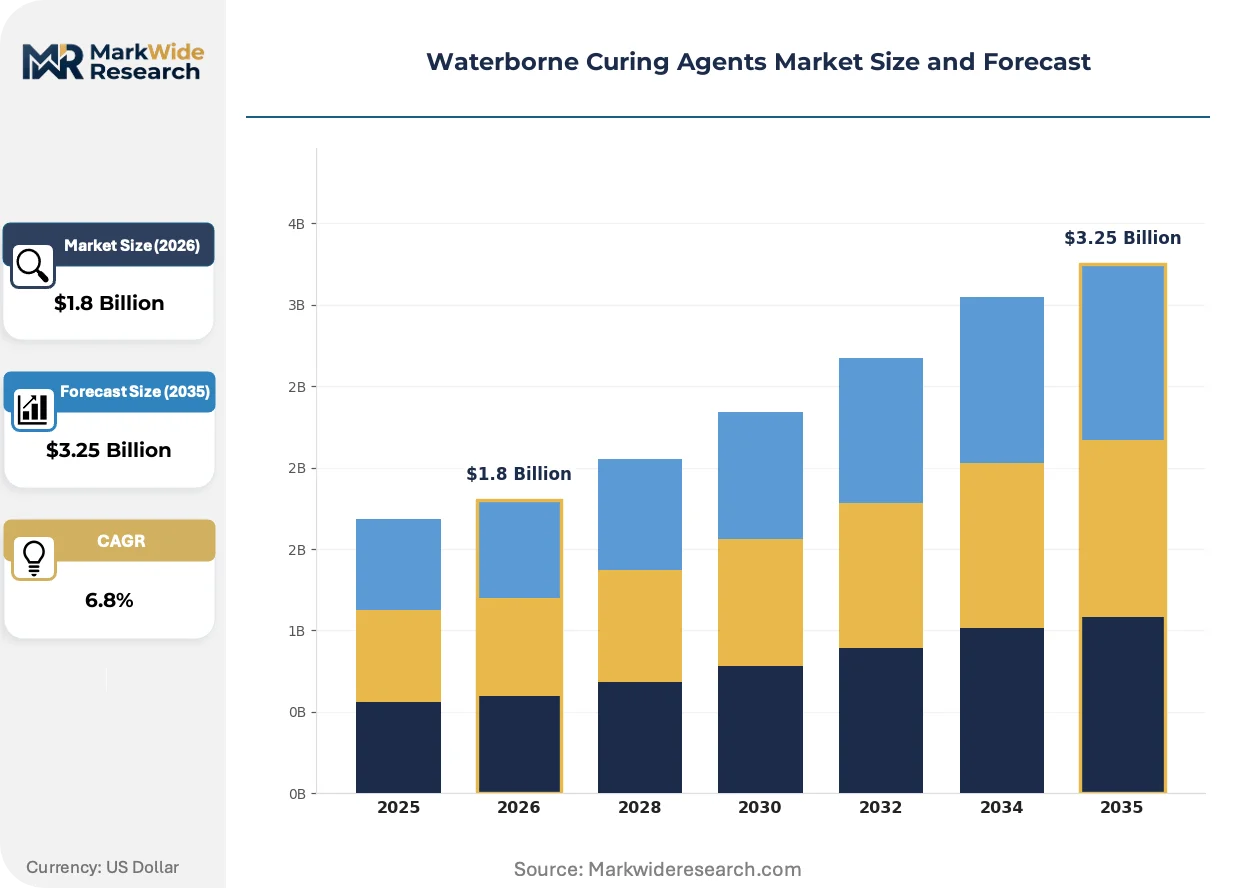
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amines, Polyamides, Polyols, Others End User: Construction, Automotive, Aerospace, Marine Technology: UV Curing, Thermal Curing, Electron Beam Curing, Chemical Curing Application: Coatings, Adhesives, Sealants, Composites |
| Companies Covered | Evonik Industries, Huntsman Corporation, BASF, Kukdo Chemical, Cardolite Corporation, Olin Corporation, Hexion Inc., Westlake Corporation, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterborne Curing Agents Market Evolving Landscape
Digital process control and predictive formulation modeling are compressing product development cycles while regulatory data management platforms reshape compliance workflows. These intersecting forces are elevating technical service capabilities as a competitive differentiator.
Smart manufacturing systems with inline viscosity and cure-monitoring sensors are digitizing quality assurance protocols for waterborne curing agent batch production. Coating manufacturers in Germany and the United States are deploying these platforms to reduce formulation rework rates. The technology is digitizing specification documentation trails required for EPA and REACH audit compliance.
EPA National Emission Standards for Hazardous Air Pollutants are tightening facility-level VOC thresholds for industrial coating operations. Manufacturing plants in Ohio, Texas, and Michigan are retrofitting spray booths and curing ovens to capture fugitive emissions. Marine and protective coatings segments face the steepest compliance cost escalation, driving specification shifts toward waterborne systems.
Buyers are consolidating supplier relationships around full-service formulation partners capable of joint development programs. Automotive OEM coating divisions are reducing their hardener vendor base from multiple suppliers to two or three strategic partners. This concentration pattern is most visible in the United States, where line approval processes for waterborne primers now require 12-18 month qualification cycles.
Waterborne Curing Agents Market Segmentation
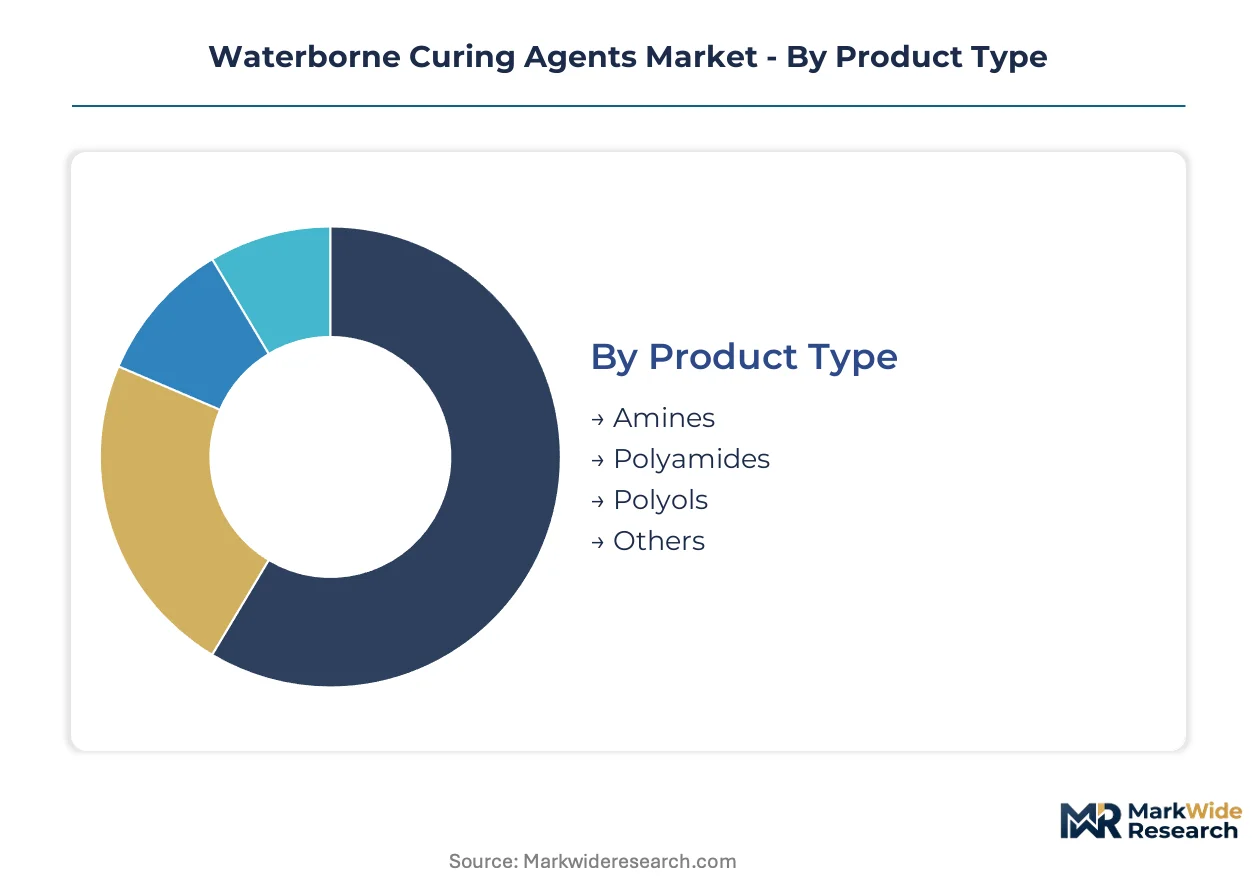
Waterborne curing agents serve distinct performance requirements across formulation chemistries and end-use specifications. Segmentation reveals where technical service intensity concentrates and which technology platforms command premium positioning.
Product Type:
After-sales technical support requirements vary sharply across curing agent chemistries, with amine-functional products demanding the highest formulation troubleshooting engagement.
- Amines:Aqueous-phase amine-functional compounds crosslink epoxy resins through nucleophilic addition at ambient temperatures. Marine coating specifications in Germany and the United States specify these products for corrosion resistance exceeding 5 MPa adhesion on steel. REACH substance evaluation procedures constrain cycloaliphatic variants, redirecting demand toward modified aliphatic alternatives.
- Polyamides:Polyamide dispersions deliver extended pot life and flexibility in architectural coating systems. Construction coatings in China's Yangtze River Delta manufacturing corridor specify these products for infrastructure projects requiring site safety compliance. Margin pools concentrate here due to proprietary dispersion technology barriers.
- Polyols:Hydroxyl-terminated prepolymers enable polyurethane-epoxy hybrid networks with enhanced chemical resistance.
- Others:Ketimine and dicyandiamide derivatives serve niche high-temperature curing applications in industrial maintenance coatings.
By volume, polyamide dispersions lead. By growth pace, amine-functional products are ahead.
End User:
Cost tier differentiation separates specification-grade automotive and aerospace demand from volume construction applications.
- Construction:Protective and architectural coatings for infrastructure projects specify aqueous epoxy systems to meet EPA and MEE VOC limits. BIS adoption of emission standards in Gujarat and Maharashtra creates qualification windows for imported waterborne technologies in India's industrial corridor expansion.
- Automotive:OEM coating divisions consolidate hardener vendor relationships around full-service formulation partners. Line approval processes for waterborne primers require 12-18 month qualification cycles in the United States, concentrating procurement among strategic suppliers.
- Aerospace:MRO coating specifications prioritize corrosion resistance and weight reduction in fuel-efficient airframe designs.
- Marine:Sub-ambient temperature applications face technical performance gaps versus solvent-borne alternatives in pot life and cure rate.
Construction absorbs the highest volume. Automotive refinishing delivers the steepest expansion trajectory.
Technology:
Application velocity requirements determine technology selection, with line-speed manufacturing favoring accelerated cure mechanisms.
- UV Curing:Photoinitiated polymerization achieves line-speed targets in automotive refinishing without solvent emissions. Aqueous base coats integrate with UV-curable topcoats in hybrid convergent systems. This segment is expanding most quickly due to throughput advantages in high-volume coating operations.
- Thermal Curing:Elevated temperature crosslinking dominates industrial maintenance coatings where substrate heating is operationally feasible.
- Electron Beam Curing:Radiation-induced polymerization serves specialized composite manufacturing with instant cure and minimal thermal stress.
- Chemical Curing:Ambient temperature amine-epoxy reactions remain the default for field-applied protective coatings.
Thermal curing holds the largest installed base. UV curing platforms are gaining share fastest.
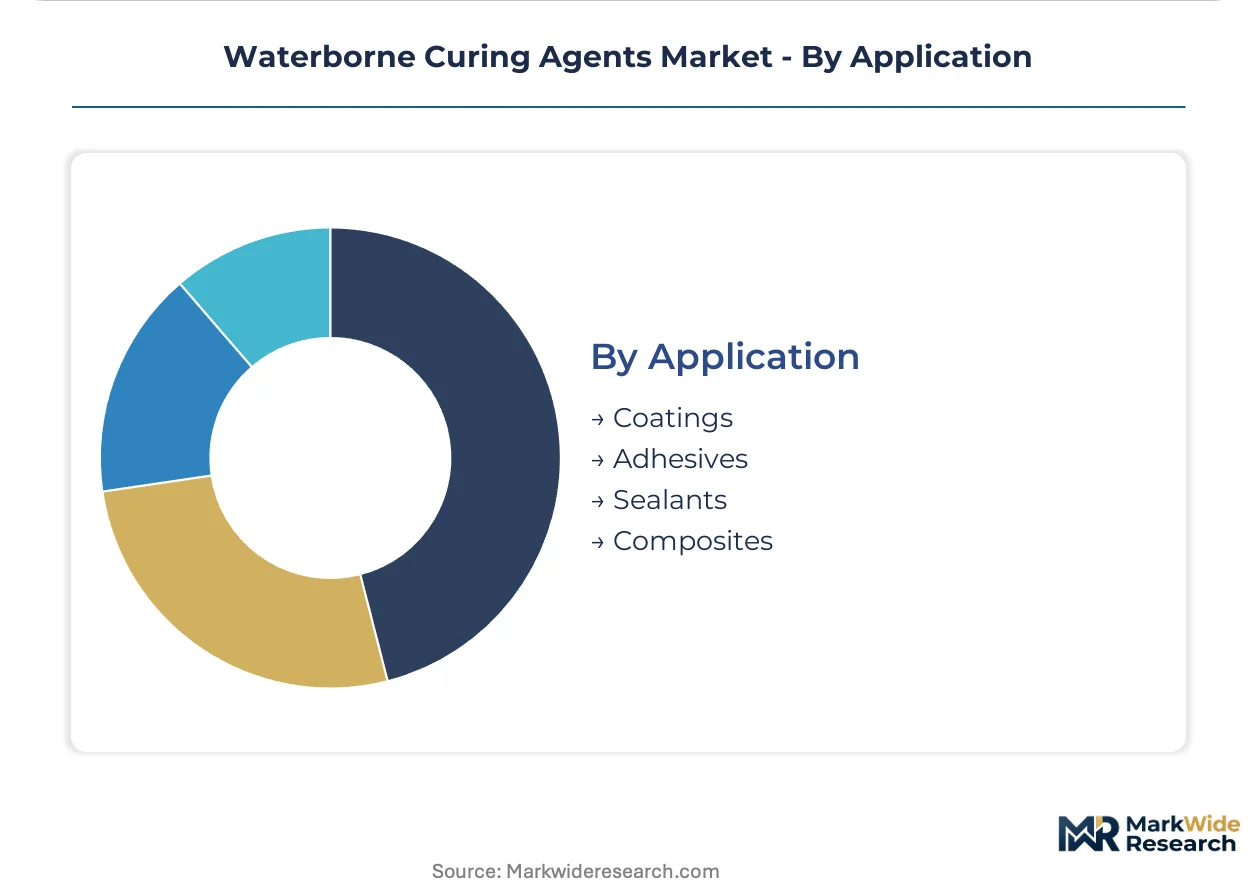
Application:
Customer type stratification separates specification-driven coatings procurement from commodity adhesive purchasing.
- Coatings:Industrial, protective, and automotive coating systems represent the dominant value pool. Smart manufacturing systems with inline viscosity monitoring digitize quality assurance for batch production in Germany and the United States. EPA National Emission Standards for Hazardous Air Pollutants tighten facility-level VOC thresholds, retrofitting spray booths in Ohio, Texas, and Michigan.
- Adhesives:Structural bonding applications in transportation assembly specify waterborne systems for workplace safety compliance. Formulation chemistry expertise for aqueous-phase crosslinking remains concentrated among legacy epoxy specialists.
- Sealants:Joint sealing and waterproofing applications in infrastructure projects adopt aqueous technologies for site environmental compliance.
- Composites:Fiber-reinforced polymer manufacturing integrates waterborne curing agents for reduced emissions in closed-mold processes.
Coatings dominate by revenue contribution. Adhesives demonstrate the strongest volume momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialty amine hardeners is narrowing as regional production networks mature. Export flows from German and Chinese manufacturing hubs now supply adjacent markets with qualified waterborne grades. Domestic formulation capacity is expanding fastest in jurisdictions with enforceable VOC limits.
United States
Automotive OEM coating divisions in Michigan and Ohio are consolidating hardener vendor relationships around full-service partners. EPA National Emission Standards for Hazardous Air Pollutants tighten facility-level thresholds, retrofitting spray booths in Texas and Ohio. Industrial coating operations in the Midwest are digitizing quality assurance with inline viscosity monitoring.
Germany
Marine coating specifications in Hamburg and Bremerhaven specify amine-functional products for corrosion resistance exceeding 5 MPa adhesion on steel. REACH substance evaluation procedures constrain cycloaliphatic variants, redirecting demand toward modified aliphatic alternatives. Smart manufacturing systems in Bavaria are compressing batch production rework rates.
China
Construction coatings in the Yangtze River Delta manufacturing corridor specify polyamide dispersions for infrastructure projects requiring site safety compliance. MEE enforcement of VOC emission limits in Jiangsu and Zhejiang provinces accelerates domestic production capacity. Coating manufacturers in Shanghai are scaling aqueous epoxy system output.
India
Protective coatings procurement in Gujarat and Maharashtra is adopting waterborne technologies as BIS implements VOC emission standards. Infrastructure project specifications in the industrial corridor expansion create qualification windows for imported curing agent technologies. Domestic formulation capacity remains concentrated in Western India.
Waterborne Curing Agents Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with proprietary dispersion technologies. The vendor base separates into consolidated multi-site producers and mid-scale toll manufacturing partners. Three archetypes dominate: backward-integrated epoxy intermediate producers, proprietary polyamide dispersion technology holders, and asset-light toll manufacturing specialists. Competitive moves center on strategic partnerships for regional qualification and capacity expansion in high-growth manufacturing corridors.
Within the backward-integrated tier, Evonik Industries and Huntsman Corporation exemplify archetypes with multi-site production networks and captive intermediate supply. BASF anchors the proprietary technology vector with dispersion capabilities. These three entities represent the dominant competitive positions without claiming specific market shares or strategic actions.
| Leading Market Players |
|---|
| Evonik Industries |
| Huntsman Corporation |
| BASF |
| Kukdo Chemical |
| Cardolite Corporation |
| Olin Corporation |
| Hexion Inc. |
| Westlake Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Value Network & Pricing Analysis
German polyamide dispersion technology holders capture the widest margin pools in waterborne curing agents, with proprietary formulation barriers concentrating pricing power among three multi-site producers. This upstream technology concentration feeds downstream into how industrial coating buyers negotiate contract structures across construction and automotive segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered adjustments. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant grades from standard formulations and commodity amine alternatives. Pricing pressure stems from bisphenol-A and epichlorohydrin feedstock volatility compressing margins for non-integrated producers. Construction coatings procurement teams demonstrate highest price sensitivity due to project-based budgeting, while automotive OEM coating divisions prioritize qualification reliability over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations as both jurisdictions scale domestic waterborne curing agent capacity. Production gravity centers on Germany, China, and the United States as industrial coating hubs retrofit aqueous-phase systems. Feedstock dependencies rest on epichlorohydrin, bisphenol-A, and specialty amine intermediates sourced from integrated petrochemical complexes. Single-source vulnerability concentrates in cycloaliphatic amine hardeners facing REACH substance evaluation constraints. Distribution runs through regional toll manufacturing networks and direct technical service partnerships with formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waterborne curing agents market tracks a cyclical recovery as construction coatings specification rebounds alongside infrastructure investment cycles in industrial corridors.
For Market Incumbents: Harden proprietary dispersion technology moats through captive R&D investment in modified aliphatic amine alternatives, as REACH restrictions on cycloaliphatic variants threaten formulation portfolios. Expand toll manufacturing partnerships in India's Gujarat and Maharashtra industrial corridors before BIS qualification windows narrow. Capacity addition in the Yangtze River Delta manufacturing corridor secures proximity to China's fastest-growing construction coatings demand. For New Entrants and Emerging Players: India's industrial corridor expansion offers the most penetrable geographic entry point as domestic formulation capacity remains concentrated in Western India. Target protective coatings procurement in Gujarat infrastructure projects where BIS VOC standards create first-mover qualification advantages. Partner with European toll manufacturers for asset-light supply agreements rather than fixed capital deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale specialty chemical producers lacking backward integration into epoxy intermediates. Five-to-ten year viability hinges on regulatory compliance technology rather than commodity scale. Monitor ECHA substance evaluation timelines for cycloaliphatic amine restrictions as inflection indicators for portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Intermediates | Huntsman Corporation anchors competitive positioning through captive bisphenol-A and epichlorohydrin supply. |
| Green Manufacturing Transition | Evonik Industries leverages multi-site European networks to sustain REACH-compliant aqueous-phase production. |
| Joint Venture | BASF's proprietary polyamide dispersion technology partnerships concentrate margin pools in architectural coatings. |
| Long-term Supply Agreement | Automotive OEM coating divisions consolidate vendor relationships around full-service formulation partners with 12-18 month qualification cycles. |
| Capacity Expansion | Shanghai coating manufacturers scale aqueous epoxy system output to meet MEE VOC enforcement in Jiangsu and Zhejiang provinces. |
Research Methodology
A standing panel of plant managers at waterborne curing agent production facilities, procurement leads at downstream industrial coating OEMs, distribution channel partners in specialty chemical networks, and technical R&D directors in epoxy formulation provided ongoing calibration across the analysis. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, EPA National Emission Standards documentation, and SEC 10-K filings from publicly traded chemical producers. Bottom-up segment sizing triangulated against top-down market estimates.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions including curing agent chemistry type, end-use industry vertical, technology platform, and regional production hub. CAGRs derived from regression analysis of historical volume trends against regulatory compliance timelines and feedstock cost indices. Industry-specific forecast inputs incorporated REACH substance evaluation schedules and MEE enforcement patterns in China's Yangtze River Delta manufacturing corridor.
Practitioners should monitor ECHA restriction proposals, MEE VOC limit revisions, and bisphenol-A price volatility for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Etching Chemicals Market
Chemicals
Hexamine Market
Chemicals
Global Construction Chemical Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Valeryl Chloride Market
Chemicals
Global Aldehyde Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Global Calcium Hypochlorite Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Piroctone Olamine Market
Chemicals
Global Glycol Ether Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Perchloric Acid Market