
 India Methanol Market | 2026-2036
India Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
India Methanol Market Insights
BIS certification under IS 517 is reorganizing competitive access for domestic methanol suppliers. Gujarat Narmada Valley Fertilizer & Chemicals Limited leverages its integrated ammonia-methanol complex to dominate bulk chemical supply. Deepak Fertilizers and Petrochemicals sustains position through specialized high-purity grades for pharmaceutical solvents. Rashtriya Chemicals and Fertilizers anchors strategic supply to public sector energy projects.
Methanol (CH₃OH) is a light, volatile alcohol produced primarily via steam methane reforming of natural gas or coal gasification, with specifications grading purity from industrial grade (99.85%) to high-purity electronic grades above 99.99%; it serves as foundational feedstock for formaldehyde, acetic acid, and methyl tert-butyl ether production, while emerging as a hydrogen carrier and marine fuel alternative. Chemical methanol occupies the largest value pool given its entrenched role in formaldehyde and acetic acid chains, though biomethanol represents the fastest-expanding category as sugarcane bagasse and agricultural residue feedstocks gain policy support under India's biofuel mandates. Fuel methanol applications in transportation are structurally constrained by blending infrastructure gaps, yet energy storage applications are attracting capital as grid-scale battery alternatives.
Central Electricity Authority (CEA) grid standards and Petroleum and Natural Gas Regulatory Board (PNGRB) pipeline specifications shape methanol's energy pathway eligibility, while DGFT import monitoring controls overseas supply penetration. BIS quality enforcement and the PLI scheme for chemical manufacturing collectively determine which producers qualify for public procurement and subsidy access. Stakeholders must track how the Bureau of Energy Efficiency's industrial decarbonization mandates redirect methanol demand from conventional chemicals toward hydrogen economy intermediates.
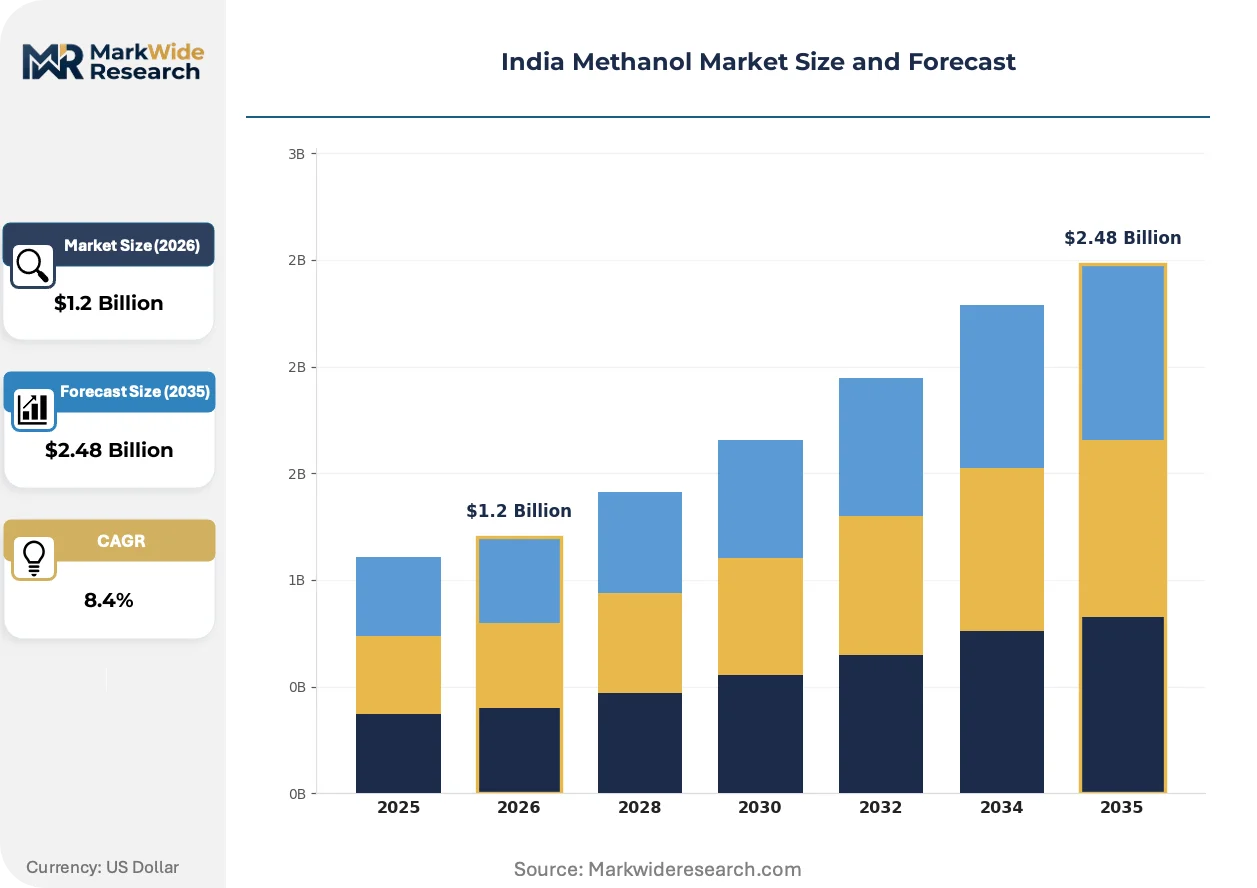
Market Dynamics
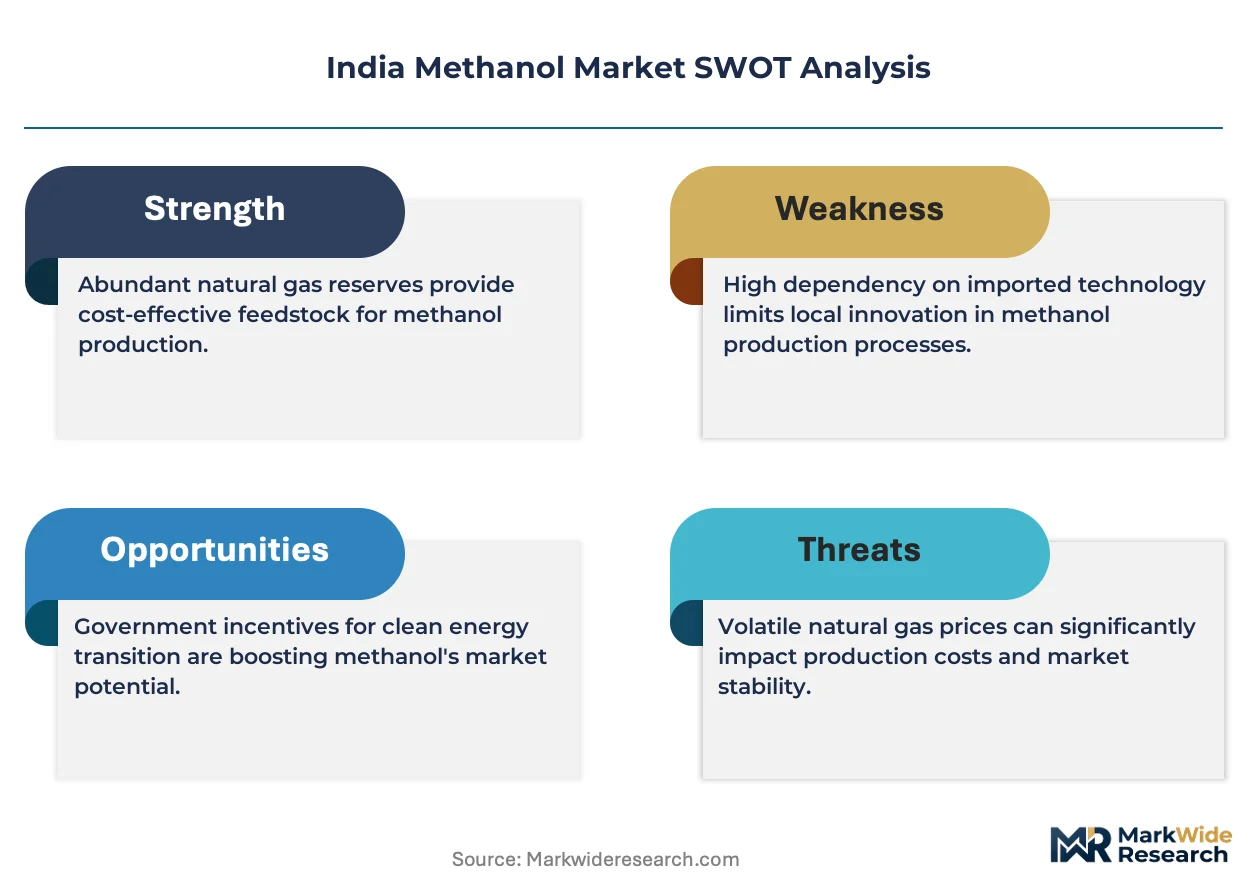
India's methanol sector is compressing around feedstock-advantaged production clusters as natural gas pricing reforms and BIS certification mandates force merchant suppliers toward integrated manufacturing models or exit.
Growth Catalysts
- Biofuel Mandate Expansion:Agricultural residue-to-methanol pathways under India's biofuel policy are redirecting capital toward bagasse gasification projects in Maharashtra and Uttar Pradesh.
- Marine Fuel Specification:The International Maritime Organization's sulfur caps are positioning Indian methanol as a bunker fuel alternative at Gujarat port complexes.
- CEA Grid Integration:Central Electricity Authority standards for methanol-fired turbines are opening procurement channels for grid-scale energy storage applications.
Market Restraints
- Natural Gas Price Volatility:Domestic gas allocation under the Administered Price Mechanism creates input cost unpredictability for steam methane reforming operations.
- Import Dependency Concentration:Middle Eastern suppliers control over half of merchant methanol flows through Hazira and Dahej port terminals.
- Coal Gasification Efficiency Gap:Indian coal's high ash content limits syngas conversion yields versus international benchmarks.
Strategic Opportunities
- Assam-Bengal Feedstock Corridor:Untapped natural gas reserves in the northeastern region offer greenfield methanol-ammonia complex potential with pipeline connectivity to Bangladesh markets.
- Hydrogen Carrier Applications:Methanol-to-hydrogen reforming is converging with fuel cell bus trials in Delhi and Mumbai metropolitan transport authorities.
- PLI Chemical Manufacturing:Production-linked incentive schemes for specialty chemicals are subsidizing high-purity methanol capacity for pharmaceutical solvent grades.
Industry Challenges
- BIS IS 517 Certification Timelines:Bureau of Indian Standards testing protocols for fuel-grade methanol extend qualification periods by 8-14 months versus industrial chemical grades.
- Pipeline Infrastructure Capex Burden:PNGRB-mandated city gas distribution networks require methanol-compatible materials retrofits at distribution terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Methanol Market |
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Methanol, Chemical Methanol, Biomethanol, Industrial Methanol End User: Automotive, Chemical Manufacturing, Energy Production, Plastics Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Application: Energy Storage, Solvent, Feedstock, Transportation |
| Companies Covered | Gujarat Narmada Valley Fertilizer & Chemicals Limited, Deepak Fertilizers and Petrochemical Corporation, Rashtriya Chemicals and Fertilizers, Assam Petrochemicals Limited, National Fertilizers Limited, Methanex Corporation, BASF SE, LyondellBasell Industries N.V., Celanese Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Methanol Market Trends and Innovations
Electrification of chemical process heating and carbon accounting transparency are forcing methanol producers to reengineer both feedstock sourcing and plant energy balances.
Biomethanol production from sugarcane bagasse gasification is displacing fossil-derived methanol in formaldehyde applications. Fertilizer cooperatives in western Maharashtra are piloting integrated bioethanol-biomethanol complexes. This displacement is compressing the premium for certified low-carbon methanol grades in export-oriented chemical manufacturing.
CEA notification on methanol firing standards for thermal power plants is mandating flue gas treatment retrofits. Plant operators must install selective catalytic reduction systems to meet nitrogen oxide limits. Grid-connected units in Gujarat and Tamil Nadu are prioritizing methanol co-firing trials over dedicated biomass investments.
Direct procurement contracts between methanol producers and formaldehyde manufacturers are shortening traditional distributor channels. Large consumers in the wood panel and resin sectors are negotiating pipeline-connected supply agreements. This channel compression is most visible in the Vapi-Ankleshwar industrial belt where integrated chemical parks enable direct metering infrastructure.
India Methanol Market Segmentation
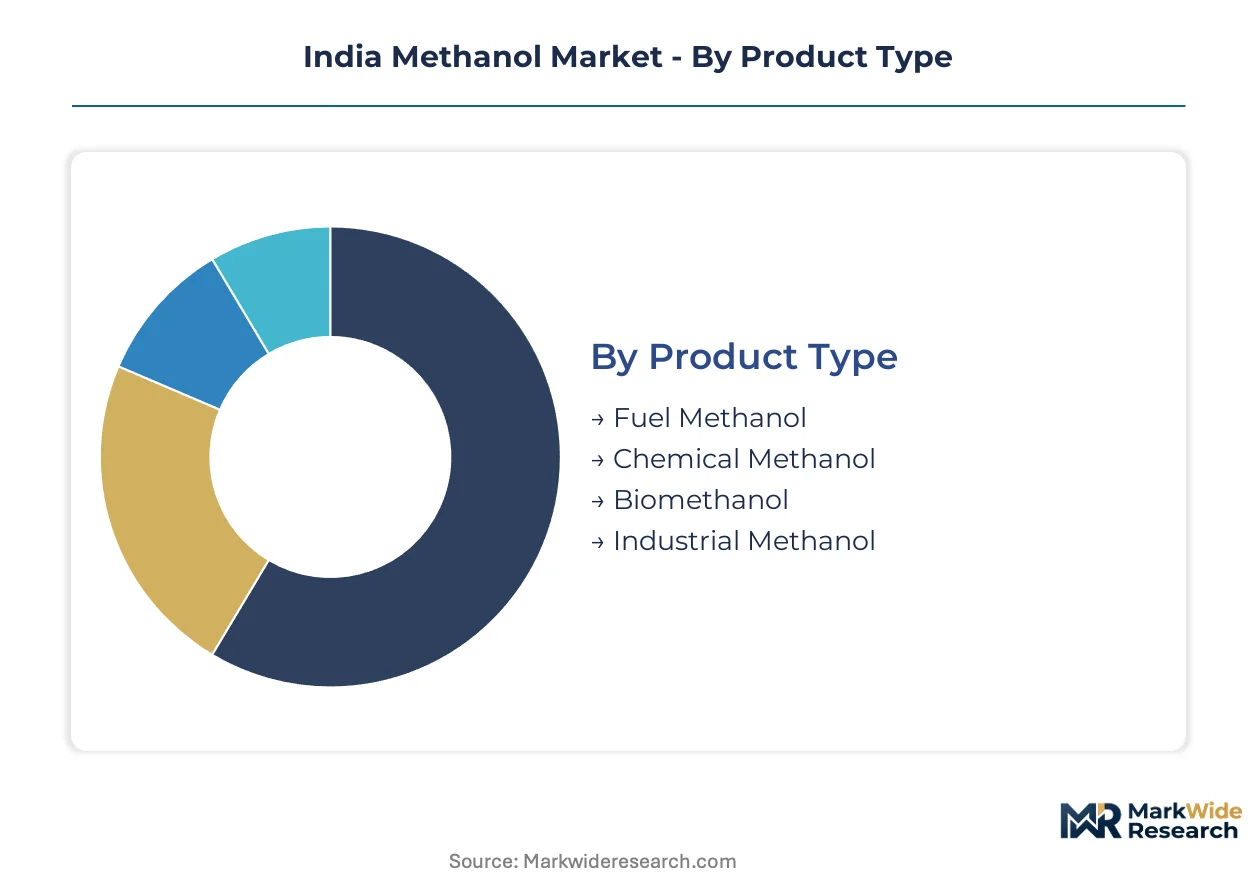
Methanol demand fragments across fuel substitution pathways, chemical synthesis requirements, and emerging hydrogen carrier applications. Each segment carries distinct BIS certification burdens and feedstock intensity profiles that determine competitive access.
Product Type:
Fuel-grade and biomethanol variants face acute substitution pressure from compressed natural gas and battery-electric alternatives in transport applications.
- Chemical Methanol:Industrial-grade purity specifications (99.85% minimum) serve formaldehyde and acetic acid synthesis. Demand concentrates in Gujarat's petrochemical corridor where pipeline-connected formaldehyde manufacturers anchor offtake volumes under long-term contracts.
- Biomethanol:Agricultural residue gasification yields carbon-intensity advantages for export-oriented chemical manufacturers. Maharashtra and Uttar Pradesh bagasse projects are gaining PLI scheme support, though scale economics trail fossil-derived production.
- Fuel Methanol:M15 and M85 blending grades for automotive use face infrastructure constraints at retail dispensing networks. BIS IS 517 certification timelines extend market entry for new suppliers.
- Industrial Methanol:Broad-spectrum solvent applications in paints and coatings require lower purity thresholds. Price sensitivity drives procurement through distributor channels rather than direct supply agreements.
Chemical methanol retains volume leadership; biomethanol holds the steepest expansion curve.
End User:
Customer concentration varies sharply by margin tier, with chemical manufacturers capturing value through captive consumption while automotive blenders operate on thinner conversion economics.
- Chemical Manufacturing:Formaldehyde, acetic acid, and methyl tert-butyl ether producers constitute the anchor demand pool. Integrated ammonia-methanol complexes in Gujarat and Maharashtra dominate supply relationships through pipeline-connected delivery infrastructure.
- Energy Production:CEA grid standards for methanol-fired turbines are opening procurement channels for grid-scale storage applications. Tamil Nadu and Gujarat plant operators are piloting co-firing configurations alongside selective catalytic reduction retrofits.
- Automotive:Fuel blending mandates under biofuel policy are redirecting R&D investment toward M15-compatible engine retrofits. OEM trials remain concentrated in commercial vehicle segments where fleet conversion economics prove favorable.
- Plastics:Specialty resin manufacturers require high-purity grades for polymerization catalyst systems. Pharmaceutical-grade solvent specifications command premium pricing through direct sales channels.
Chemical manufacturing commands the dominant value share; energy production is gaining share fastest.
Distribution Channel:
Channel selection tracks shipment scale and certification complexity, with bulk chemical offtake favoring direct relationships while fragmented industrial demand flows through intermediaries.
- Direct Sales:Pipeline-connected supply agreements between methanol producers and formaldehyde manufacturers are displacing traditional distributor relationships. Vapi-Ankleshwar chemical parks enable direct metering infrastructure that compresses working capital cycles.
- Distributors:Regional chemical traders manage inventory for small-batch industrial consumers across Maharashtra and Gujarat. BIS certification documentation requirements add administrative overhead relative to direct channels.
- Online Sales:Digital procurement platforms are emerging for standardized industrial grades below container-load quantities. Price transparency pressures traditional distributor margins in solvent applications.
- Retail:Fuel-grade methanol at dispensing stations remains structurally constrained by blending infrastructure gaps. City gas distribution networks under PNGRB mandates require material retrofits for methanol compatibility.
Direct sales channels dominate volume throughput; online platforms are expanding most quickly.
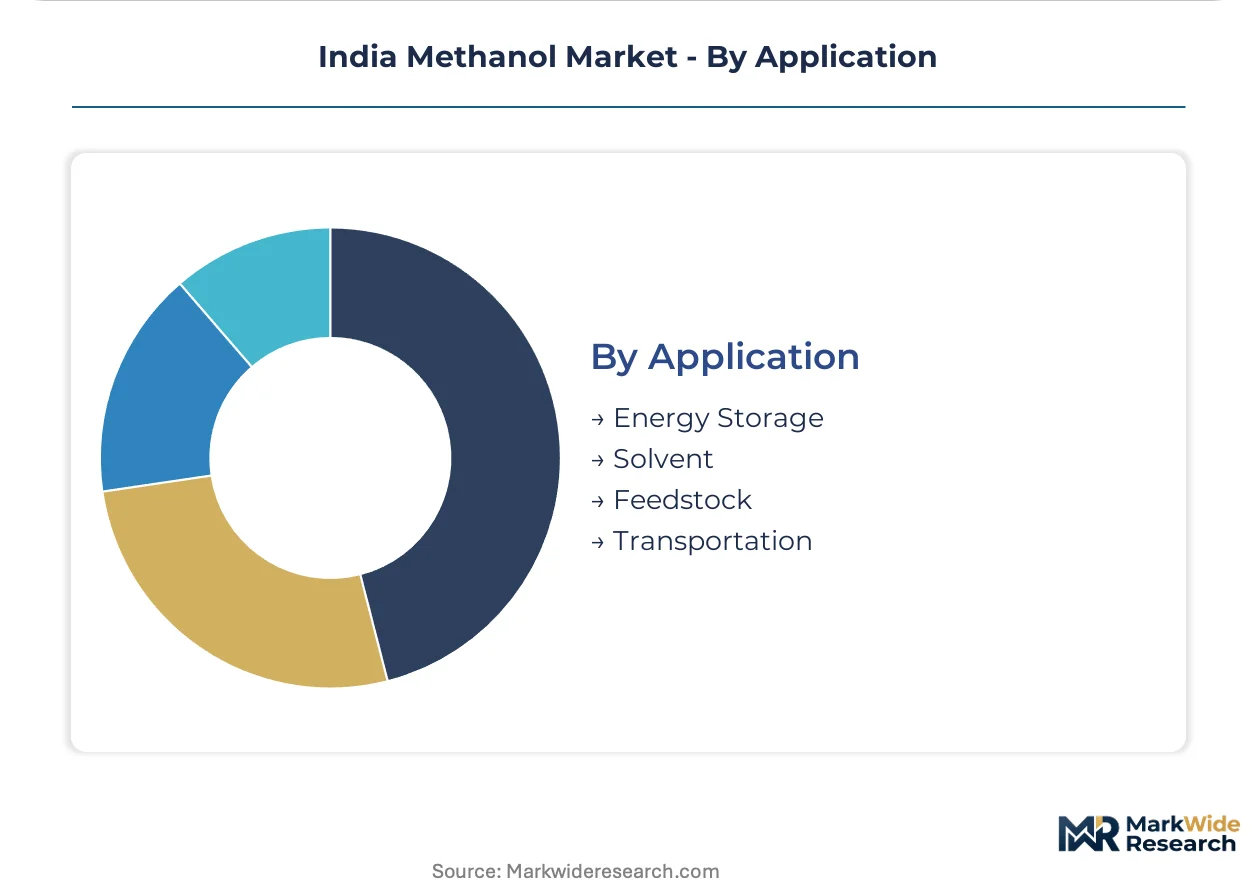
Application:
Application segmentation reveals a tension between mature chemical synthesis demand and emerging energy pathway opportunities with divergent capital intensity requirements.
- Feedstock:Formaldehyde production for wood panel and resin applications anchors methanol consumption. Deepak Fertilizers and Gujarat Narmada Valley Fertilizer sustain supply relationships through dedicated pipeline infrastructure.
- Solvent:Pharmaceutical and electronics manufacturing require electronic-grade purity above 99.99%. High-purity capacity expansion is attracting PLI scheme subsidies for specialty chemical manufacturing.
- Transportation:Marine fuel bunkering at Gujarat port complexes is positioning Indian methanol as an IMO sulfur cap compliance pathway. Fuel cell bus trials in Delhi and Mumbai metropolitan transport authorities are testing methanol-to-hydrogen reforming configurations.
- Energy Storage:Grid-scale methanol storage for peaking power applications is converging with CEA turbine firing standards. Co-firing trials are prioritizing methanol over dedicated biomass investments in Tamil Nadu.
Feedstock applications retain volume leadership; transportation holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formaldehyde manufacturers and fertilizer cooperatives dominate methanol procurement, clustering around feedstock-advantaged production belts and pipeline-connected chemical parks.
Gujarat
Integrated ammonia-methanol complexes at Dahej and Hazira anchor national supply volumes. BIS IS 517 certification requirements accelerate formal sector consolidation around port-connected storage terminals. The Vapi-Ankleshwar chemical belt enables direct pipeline metering between producers and formaldehyde manufacturers.
Maharashtra
Fertilizer cooperatives in western districts pilot bagasse gasification for biomethanol production. PLI scheme subsidies redirect capital toward high-purity pharmaceutical solvent grades. Mumbai metropolitan transport authorities test methanol-to-hydrogen configurations for fuel cell bus fleets.
Tamil Nadu
CEA grid standards for methanol-fired turbines attract peaking power investment. Plant operators install selective catalytic reduction systems to meet nitrogen oxide limits. Co-firing trials prioritize methanol over dedicated biomass at thermal units near Chennai industrial corridors.
Assam
Untapped natural gas reserves in the northeastern region offer greenfield methanol-ammonia complex potential. Pipeline connectivity to Bangladesh markets extends offtake geography. Assam Petrochemicals Limited anchors strategic supply to public sector energy projects.
Uttar Pradesh
Agricultural residue availability supports bagasse gasification projects under national biofuel mandates. Sugar mill cooperatives explore integrated bioethanol-biomethanol complexes. Demand concentrates in resin and wood panel manufacturing clusters along the Delhi-Mumbai industrial corridor.
India Methanol Market Competitive Landscape
Player mix skews toward state-affiliated fertilizer enterprises with captive feedstock access. The vendor base compresses around integrated manufacturing complexes as BIS certification mandates force merchant suppliers toward consolidation or exit. Three archetypes dominate: ammonia-methanol integrated producers, high-purity specialty chemical specialists, and import-dependent trading houses. Capacity expansion and backward integration into natural gas allocation represent the dominant competitive vectors.
Among domestic integrated producers, Gujarat Narmada Valley Fertilizer & Chemicals Limited and Deepak Fertilizers and Petrochemicals exemplify the ammonia-methanol complex archetype. Rashtriya Chemicals and Fertilizers occupies a position within the public sector supply tier, anchoring strategic relationships with government energy projects. These three entities represent the consolidation pattern reshaping competitive access as BIS quality enforcement tightens.
| Leading Market Players |
|---|
| Gujarat Narmada Valley Fertilizer & Chemicals Limited |
| Deepak Fertilizers and Petrochemical Corporation |
| Rashtriya Chemicals and Fertilizers |
| Assam Petrochemicals Limited |
| National Fertilizers Limited |
| Methanex Corporation |
| BASF SE |
| LyondellBasell Industries N.V. |
| Celanese Corporation |
| Others |
Pricing and Supply Chain Analysis
BIS IS 517 certification gates both supply qualification and price differentiation simultaneously, forcing merchant methanol suppliers to absorb extended testing timelines while integrated producers capture premium pricing through pipeline-connected delivery certainty.
Pricing Analysis
Cost-plus contracts indexed to Administered Price Mechanism natural gas allocations dominate bulk chemical supply, with Gujarat Narmada Valley Fertilizer and Deepak Fertilizers leveraging captive feedstock access to maintain margin stability. Price differentiation hinges on purity grade certification and volume scale, where electronic-grade specifications above 99.99% command substantial premiums over industrial-grade 99.85% material. Cost compression in fuel-grade methanol is intensifying because BIS IS 517 timelines extend market entry for new suppliers, concentrating pricing power among incumbent certified producers. Small-batch industrial consumers exhibit highest price sensitivity, while formaldehyde manufacturers with pipeline-connected supply agreements demonstrate lowest sensitivity due to integrated logistics savings.
Supply Chain Analysis
Middle Eastern producers and domestic integrated complexes anchor methanol supply, with Saudi Arabian and Qatari merchant flows controlling terminal access at Hazira and Dahej ports alongside Gujarat's ammonia-methanol integrated facilities. Indian supply chains draw from natural gas allocations under APM pricing, coal gasification syngas, and emerging bagasse gasification feedstocks. Single-source vulnerability concentrates at Hazira port terminals where import dependency exceeds half of merchant supply. Distribution runs through pipeline-connected direct sales for bulk chemical offtake, with regional distributors managing fragmented industrial solvent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as biofuel mandate expansion and marine fuel specification shifts create specialized demand niches outside incumbent strongholds.
For Market Incumbents: Consolidate around pipeline-connected formaldehyde supply relationships in the Vapi-Ankleshwar belt to defend against biomethanol entrants capturing carbon-intensity premiums. Deepen backward integration into Assam natural gas reserves to secure feedstock allocation ahead of PLI scheme subsidy competition. Prioritize BIS IS 517 certification maintenance as regulatory enforcement tightens qualification windows. For New Entrants and Emerging Players: Lead with bagasse gasification biomethanol targeting export-oriented chemical manufacturers seeking carbon-intensity advantages under evolving sustainability procurement standards. Maharashtra and Uttar Pradesh sugar cooperatives offer the most penetrable production geography given existing agricultural residue aggregation infrastructure. Pursue direct procurement contracts with formaldehyde manufacturers to bypass distributor channel compression. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity pharmaceutical solvent grades as PLI scheme subsidies attract specialty chemical manufacturing investment. Long-term viability favors integrated ammonia-methanol complexes with captive natural gas allocation over merchant traders exposed to import dependency concentration. Watch CEA grid integration standards for methanol-fired turbines as the signal indicating energy storage demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Allocation | APM feedstock access secures margin stability against Middle Eastern import volatility. |
| Bagasse Gasification Capacity Buildout | Maharashtra sugar cooperatives leverage PLI scheme support for biomethanol production scale-up. |
| BIS IS 517 Certification Investment | Fuel-grade methanol qualification opens automotive blending procurement channels under biofuel mandates. |
| Pipeline-Connected Supply Agreement | Direct metering infrastructure in Gujarat chemical parks compresses working capital cycles. |
| Joint Venture with Fertilizer Cooperative | Integrated ammonia-methanol complexes share feedstock infrastructure and distribution terminals. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at integrated methanol-ammonia complexes, procurement leads at formaldehyde manufacturers, distribution channel partners in Maharashtra and Gujarat, and technical R&D directors at specialty chemical producers, then refined against customs and trade data, BIS certification records, CEA grid standards documentation, and SEC filings from listed chemical companies. Bottom-up capacity assessments and top-down demand modeling were triangulated to validate volume estimates.
Variance decomposition across feedstock type, purity grade tier, end-use industry, and regional production hub shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated natural gas pricing regime assumptions, biofuel mandate implementation pace, and marine fuel specification adoption timelines.
The analysis sits within stated boundaries; outcomes outside sustained APM natural gas allocation, BIS enforcement consistency, or biofuel policy continuity would require recalibration. Forecasts reflect assumptions about regulatory implementation and feedstock availability rather than guaranteed outcomes. Recalibration cycles align with material shifts in PLI scheme disbursement patterns and CEA grid standard notifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Copper Oxychloride Market
Chemicals
Cumene Market
Chemicals
Global N-Butanol Market
Chemicals
Household Insecticides Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Sodium Ethylate Market
Chemicals
Methanol Market
Chemicals
Triethylenediamine Market
Chemicals
Europe Hydrazine Market
Chemicals
North America Construction Chemicals Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Amine Oxide Market
Chemicals
Thioacetic Acid Market
Chemicals
North America Ethylene Dichloride (EDC) Market