
 Dimethyl Phosphate Market | 2026-2036
Dimethyl Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Phosphate Market Outlook
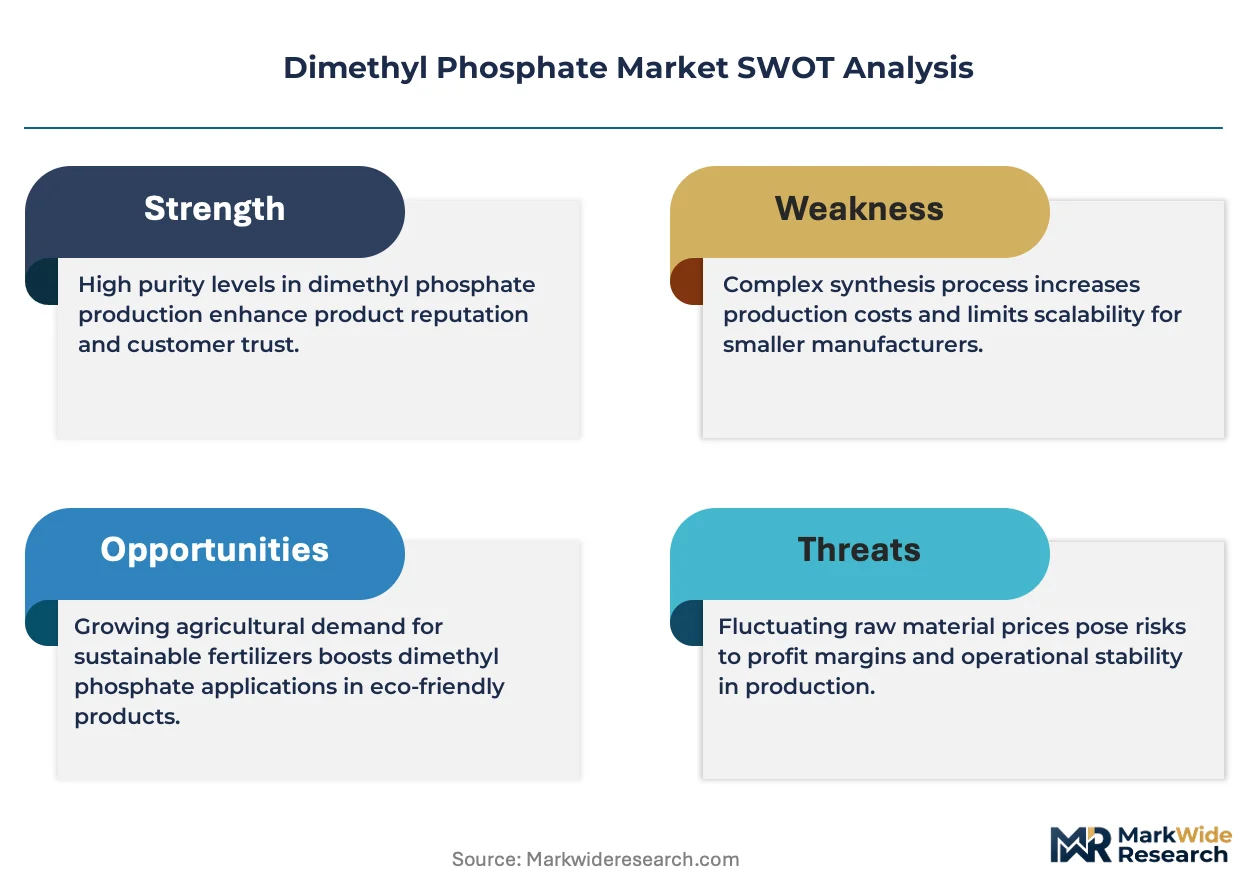
REACH is hardening the cost-of-entry calculus for dimethyl phosphate suppliers seeking European market access. Merck KGaA leverages its analytical standards portfolio to anchor premium positioning in regulated jurisdictions. Lanxess AG sustains flame retardant supply chains through backward integration into phosphorus chemistry. Biosynth AG specializes in research-grade custom synthesis, occupying a defensible niche below commodity scale.
Dimethyl phosphate refers to organophosphate esters formed by methyl substitution on phosphoric acid, typically presenting as colorless to pale yellow liquids with specific gravities near 1.2 g/cm³ and serving primarily as phosphorylating agents, flame retardant precursors, and intermediates in agrochemical synthesis. Mono dimethyl phosphate leads volume consumption through its role in halogen-free flame retardant formulations for electronics manufacturing, while di dimethyl phosphate captures expanding demand as a plasticizer intermediate in polymer compounding. Tri dimethyl phosphate remains a specialized research chemical with concentrated margin pools in pharmaceutical process development.
EPA oversight in the United States governs pesticide intermediate registration under FIFRA, while REACH in Europe mandates full substance dossiers for import volumes above one tonne annually. China's MEE enforces wastewater discharge limits on phosphorus-containing effluents from chemical processing zones. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation strategies or unified product platforms offer superior capital efficiency.
Market Dynamics
REACH dossier requirements are compressing supplier margins while Indian agrochemical formulators absorb expanding phosphate ester volumes for pesticide intermediates. China's phosphorus processing dominance creates upstream leverage that downstream compounders must navigate through long-term offtake agreements or captive integration.
Growth Catalysts
- Halogen-free flame retardant mandates:Electronics manufacturers in Germany and Taiwan are reformulating PCBs to eliminate brominated compounds, pulling mono dimethyl phosphate into laminates and encapsulants as a phosphorus-based alternative.
- India's PLI scheme for agrochemicals:Domestic pesticide intermediate production incentives are accelerating local dimethyl phosphate consumption for phosphoramidate synthesis, reducing import dependence from Chinese suppliers.
- Phosphorylation chemistry advances:Continuous-flow reactor designs are improving selectivity in dimethyl phosphate-derived reagents, enabling cost-competitive routes to nucleotide analogs in pharmaceutical process development.
Market Restraints
- Phosphate rock supply concentration:Moroccan and Chinese state-controlled mining entities control roughly three-quarters of merchant-grade phosphate rock, exposing dimethyl phosphate producers to raw material availability shocks and export quota volatility.
- REACH registration cost barriers:Full substance dossiers for import volumes above one tonne annually impose six-figure euro compliance burdens that exclude smaller traders from European market participation.
- Aliphatic phosphate ester substitution:Triethyl phosphate and triphenyl phosphate formulations are capturing share in select flame retardant applications where higher thermal stability outweighs dimethyl phosphate's cost advantage.
Strategic Opportunities
- Brazilian agrochemical localization:ANVISA registration pathways for imported pesticide intermediates remain underpenetrated by dimethyl phosphate suppliers, creating first-mover advantages for dossier-ready entrants establishing São Paulo technical sales offices.
- Battery electrolyte additive development:Dimethyl phosphate derivatives are emerging as flame-retardant electrolyte co-solvents for lithium-ion cells, with Korean and Japanese battery material suppliers actively evaluating pilot-scale qualification batches.
- EU Green Deal phosphorus recovery mandates:Circular economy regulations requiring phosphorus recycling from sewage sludge are stimulating investment in recovered phosphate purification, potentially diversifying upstream feedstock sources for European dimethyl phosphate producers.
Industry Challenges
- Organophosphate toxicology expertise scarcity:Qualified toxicologists capable of generating REACH-compliant mammalian study data for phosphate ester registrations command premium compensation, elongating dossier preparation timelines for mid-scale suppliers.
- Multi-jurisdictional label harmonization:Divergent hazard communication requirements between EPA FIFRA, REACH CLP, and China's GB 15258 standards force manufacturers to maintain parallel packaging and documentation systems, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Phosphate Market |
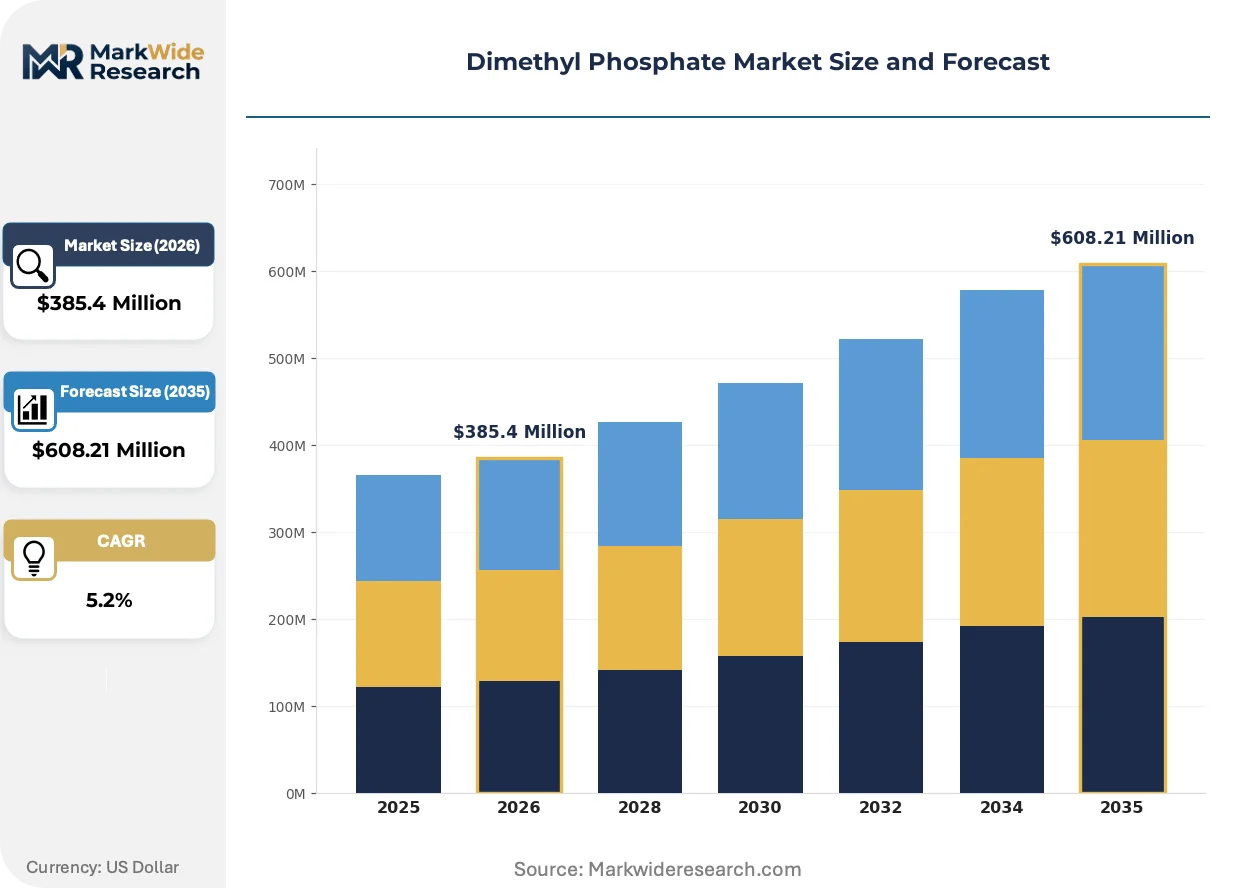
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono Dimethyl Phosphate, Di Dimethyl Phosphate, Tri Dimethyl Phosphate, Mixed Phosphates Application: Flame Retardants, Plasticizers, Pesticide Intermediates, Corrosion Inhibitors, Surfactants End Use Industry: Construction, Agriculture, Electronics Manufacturing, Chemical Processing, Paints & Coatings Packaging Type: Drums, IBC Containers, Bulk Tankers, Bottles, Flexitanks |
| Companies Covered | Otto Chemie Pvt. Ltd., Toronto Research Chemicals, Merck KGaA, Clearsynth, AccuStandard, Inc., Lanxess AG, Biosynth AG, BLDpharm, Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Phosphate Market Strategic Shifts
Process intensification and regulatory chemistry are reshaping how dimethyl phosphate derivatives reach end-use formulations. Synthesis route selection now prioritizes wastewater phosphorus recovery and carbon intensity metrics alongside traditional yield optimization.
Continuous-flow phosphorylation reactor systems are displacing batch vessel operations in pharmaceutical intermediate manufacturing. Contract development and manufacturing organizations in Switzerland and Massachusetts are installing microreactor trains that cut dimethyl phosphate reagent residence times from hours to minutes. This hardware shift is converging with real-time analytical control to enable just-in-time phosphorylating agent production at customer sites.
ECHA's 2024 update to REACH substance evaluation criteria is tightening impurity profiling requirements for organophosphate esters. Registrants must now submit extended one-generation reproductive toxicity studies for dimethyl phosphate variants above ten tonne annual tonnage bands. Agrochemical intermediate suppliers serving European formulators are responding by segregating production campaigns and investing in dedicated analytical laboratories capable of sub-ppm organophosphorus impurity detection.
Japanese electronics assemblers are consolidating phosphorylating agent procurement through nominated distributor arrangements rather than direct manufacturer relationships. Trading houses in Osaka and Tokyo are absorbing inventory risk and providing technical application support for flame retardant compounders. This channel restructuring is most pronounced in high-volume PCB laminate supply chains where just-in-delivery requirements exceed in-house logistics capabilities of specialty chemical producers.
Dimethyl Phosphate Market Segmentation
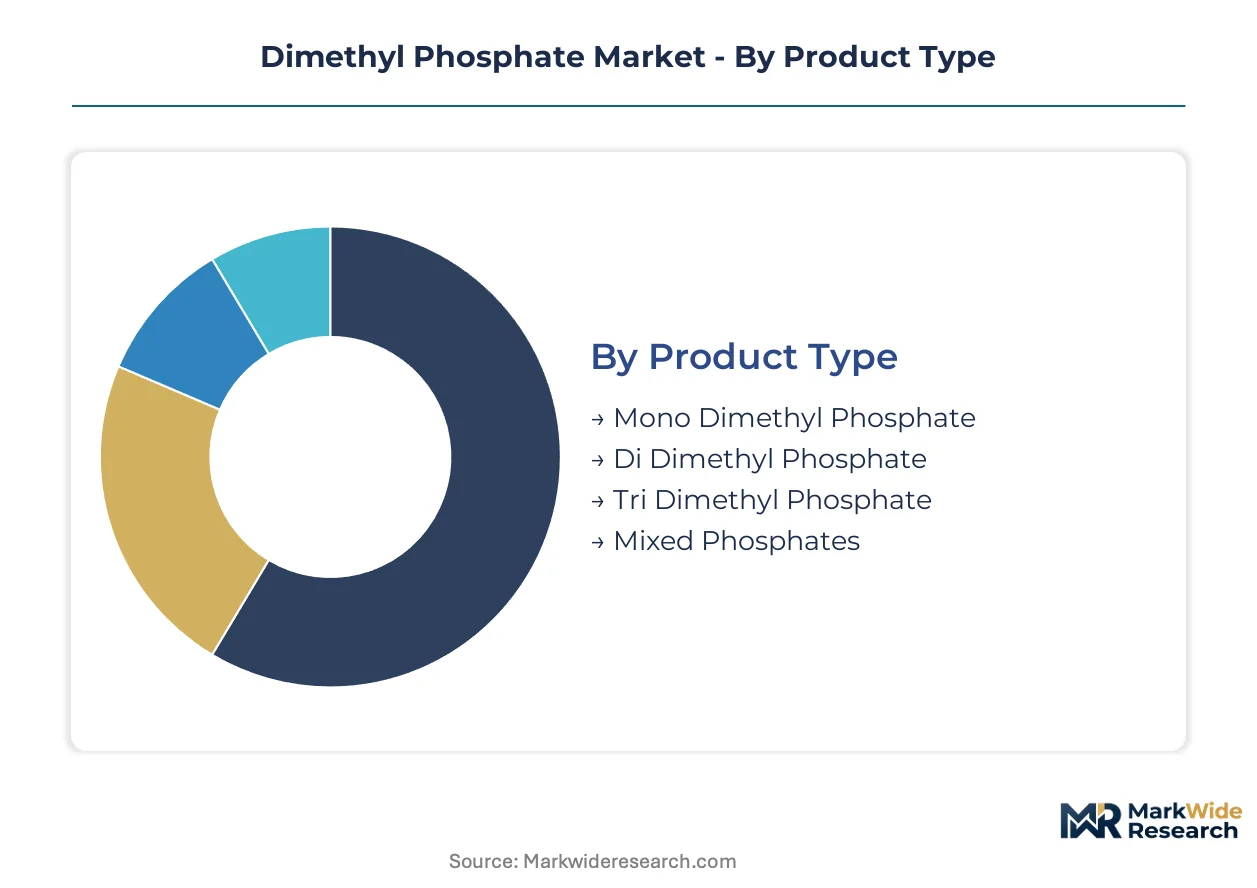
Dimethyl phosphate derivatives occupy distinct positions across standalone additive markets and embedded chemical systems. Segmentation reveals where value capture concentrates versus where commodity pricing prevails.
Product Type:
Integration depth varies sharply: mono and di variants function primarily as embedded intermediates in downstream formulations, while tri derivatives and mixed grades serve standalone research and specialty blending applications.
- Mono Dimethyl Phosphate:This phosphorus monoester delivers reactive phosphoryl functionality for halogen-free flame retardant synthesis in PCB laminates. German electronics manufacturers and Taiwan-based laminate producers absorb the majority of merchant supply, driven by RoHS and REACH restrictions on brominated alternatives.
- Di Dimethyl Phosphate:The diester configuration functions as a plasticizer intermediate and corrosion inhibitor precursor, embedding into polymer compounding workflows rather than standing alone as a finished additive. Indian agrochemical formulators increasingly specify this grade for phosphoramidate pesticide synthesis under domestic PLI incentives.
- Tri Dimethyl Phosphate:A specialized research chemical serving pharmaceutical process development and nucleotide analog synthesis, commanding concentrated margin pools in contract manufacturing.
- Mixed Phosphates:Blended ester compositions for industrial metalworking fluid applications where specification flexibility outweighs purity premiums.
Volume placements concentrate in Mono Dimethyl Phosphate; the faster expansion belongs to Di Dimethyl Phosphate.
Application:
Cost tier stratification separates specification-grade pharmaceutical and electronics applications from bulk industrial uses where price sensitivity dominates procurement decisions.
- Flame Retardants:Phosphorus-based halogen-free formulations for electronics encapsulants and wire insulation, embedding dimethyl phosphate derivatives into reactive systems rather than deploying them as standalone additives.
- Plasticizers:Polymer flexibility enhancement in PVC and engineering thermoplastics, where di dimethyl phosphate intermediates integrate into compounding operations.
- Pesticide Intermediates:Phosphoramidate synthesis for organophosphate agrochemicals, with Indian domestic production expanding fastest under import substitution policies.
- Corrosion Inhibitors:Metal surface protection in industrial cooling systems and oilfield chemicals, a mid-tier application segment.
- Surfactants:Specialized wetting agents and emulsifiers in agrochemical formulations, capturing smaller volume share.
Revenue margins peak in Flame Retardants; volume scale belongs to Pesticide Intermediates.
End Use Industry:
Customer type fragmentation separates project-driven construction procurement from continuous manufacturing demand in electronics and agriculture.
- Construction:Flame retardant and plasticizer incorporation into insulation, sealants, and flooring materials, with demand tied to commercial building cycles.
- Agriculture:Pesticide intermediate consumption concentrated in Indian and Brazilian formulator supply chains, representing the largest volume sink.
- Electronics Manufacturing:PCB laminate and semiconductor encapsulant applications in Germany, Taiwan, and Japan, where REACH and RoHS compliance premiums apply.
- Chemical Processing:Captive internal consumption and merchant sales to specialty chemical synthesis operations.
- Paints & Coatings:Corrosion protection and surface treatment formulations, a smaller but specification-intensive segment.
Procurement concentration sits with Agriculture; specification intensity peaks in Electronics Manufacturing.
Packaging Type:
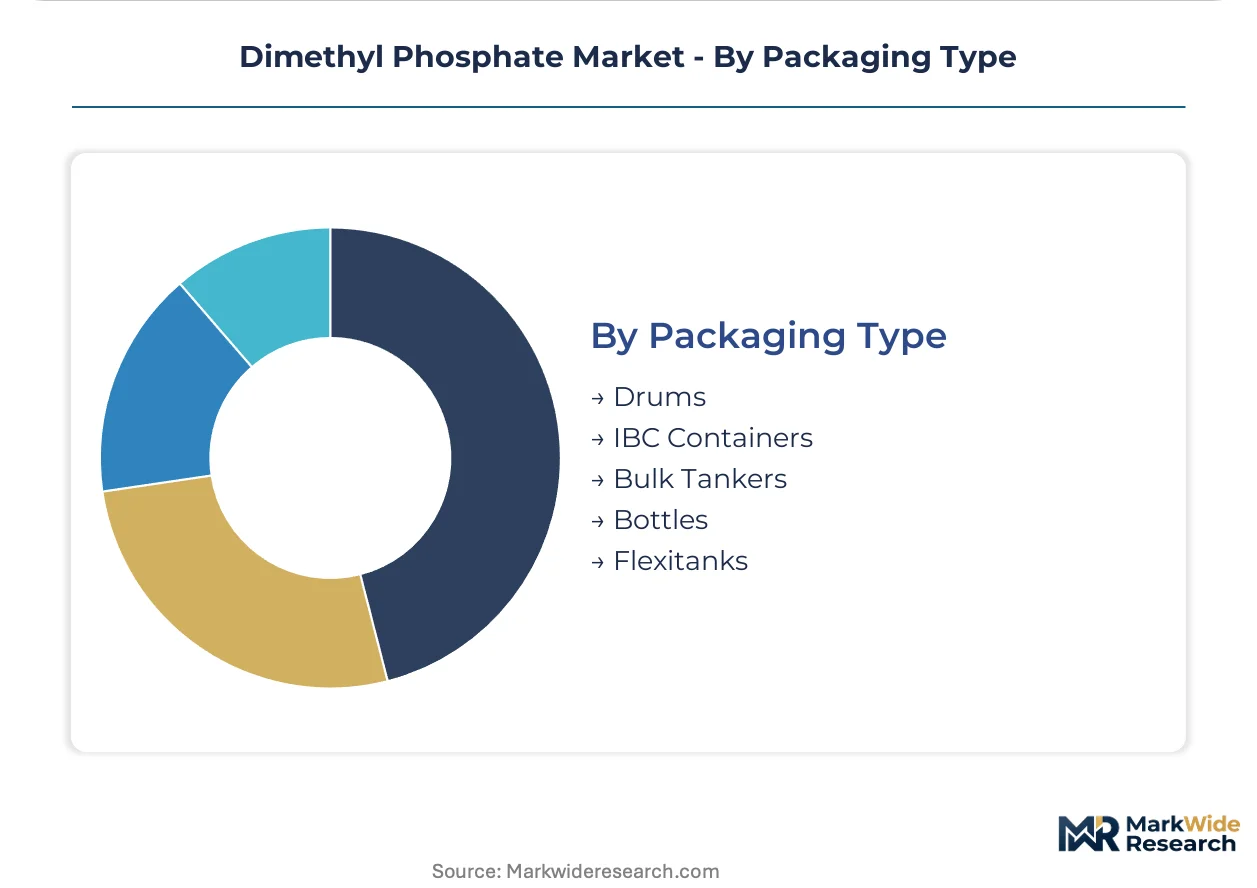
Supply chain configuration ranges from bulk continuous delivery for integrated chemical processors to precision-packaged units for research and pharmaceutical applications.
- Drums:Standard 200-liter steel and polyethylene containers for mid-volume industrial shipments, dominating agrochemical and coatings distribution.
- IBC Containers:Intermediate bulk totes for chemical processing and electronics manufacturing customers with moderate consumption rates.
- Bulk Tankers:Dedicated and multi-product tank trucks for large-volume flame retardant and plasticizer compounders with direct pipeline connections.
- Bottles:Laboratory and pilot-scale packaging for research-grade tri dimethyl phosphate and pharmaceutical process development samples.
- Flexitanks:Single-use flexible containers for cost-sensitive international bulk shipments, particularly into Indian and Brazilian ports.
Shipment value concentrates in Bulk Tankers; packaging flexibility requirements expand fastest in Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian agrochemical formulators absorb the largest phosphate ester volumes for pesticide intermediate production, while German electronics manufacturers and Chinese upstream processors concentrate supply chain leverage in their respective tiers.
China
Phosphate rock processing capacity concentrates in Guizhou and Yunnan provinces, where state-controlled mining entities supply merchant-grade feedstock to downstream ester manufacturers. MEE wastewater discharge limits enforce phosphorus recovery investments in chemical processing zones. Yangtze River Delta compounders negotiate long-term offtake agreements to secure raw material availability against export quota volatility.
India
Domestic pesticide intermediate production accelerates under PLI scheme incentives, pulling dimethyl phosphate consumption into phosphoramidate synthesis for organophosphate agrochemicals. DGFT import monitoring tracks phosphate ester arrivals from Chinese suppliers. Gujarat and Maharashtra host the fastest-expanding formulator clusters, with technical-grade consumption rising fastest in Ahmedabad and Mumbai chemical corridors.
Germany
Electronics manufacturers in Bavaria and Baden-Württemberg reformulate PCB laminates to eliminate brominated flame retardants, embedding mono dimethyl phosphate into RoHS-compliant encapsulants. REACH substance dossiers impose six-figure euro compliance burdens that filter supplier participation. Lanxess AG maintains backward integration into phosphorus chemistry from its Cologne-Rheinland production base.
United States
EPA FIFRA oversight governs pesticide intermediate registration, with merchant demand concentrated in Gulf Coast chemical processing corridors. Continuous-flow reactor adoption advances in Massachusetts pharmaceutical contract manufacturing. California electronics assemblers consolidate procurement through nominated distributor arrangements rather than direct manufacturer relationships.
Brazil
ANVISA registration pathways for imported pesticide intermediates remain underpenetrated by dimethyl phosphate suppliers, creating first-mover positioning opportunities. São Paulo technical sales offices anchor agrochemical distribution networks. Domestic formulators in Minas Gerais and Paraná seek local supply alternatives to reduce import dependence for phosphoramidate production.
Dimethyl Phosphate Market Competitive Environment
Chinese producers anchor the upstream phosphate rock processing tier; European specialists hold premium positioning in REACH-regulated jurisdictions. The vendor base stratifies across three archetypes: integrated phosphorus chemistry majors, research-grade custom synthesis boutiques, and analytical standards laboratories. Capacity expansion and strategic partnerships dominate competitive moves as suppliers navigate regulatory divergence between EPA, REACH, and MEE jurisdictions.
Within the research-grade synthesis tier, Otto Chemie Pvt. Ltd. and Toronto Research Chemicals exemplify the custom manufacturing archetype serving pharmaceutical process development. Merck KGaA occupies a position in analytical standards distribution, leveraging its portfolio to anchor premium positioning in regulated European markets. Lanxess AG represents the integrated phosphorus chemistry model, sustaining flame retardant supply chains through captive upstream control.
| Leading Market Players |
|---|
| Otto Chemie Pvt. Ltd. |
| Toronto Research Chemicals |
| Merck KGaA |
| Clearsynth |
| AccuStandard, Inc. |
| Lanxess AG |
| Biosynth AG |
| BLDpharm |
| Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Backward integration into phosphate rock processing anchors supply position and pricing power for Chinese state-controlled mining entities, while European compounders absorb REACH-driven purity premiums that separate specification-grade from technical-grade tiers. Indian agrochemical formulators negotiate contract-based long-term offtakes to buffer against export quota volatility from upstream suppliers.
Pricing Analysis
Volume placements concentrate in technical-grade mono dimethyl phosphate for flame retardant applications, while margin pools concentrate in research-grade tri derivatives for pharmaceutical process development. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European supply from Indian technical-grade and Chinese commodity streams. Cost compression in standard-grade technical material is intensifying because Indian domestic production under PLI incentives is reducing import dependence. Agrochemical formulators in Gujarat and Maharashtra exhibit highest price sensitivity; German electronics manufacturers purchasing RoHS-compliant laminates show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German electronics assemblers and Japanese trading houses mandate multi-supplier qualification for mono dimethyl phosphate feedstocks. Merchant supply concentrates in China, India, and Germany, with phosphate rock extraction anchored in Guizhou and Yunnan provinces. Downstream production draws from merchant-grade phosphate rock, methylating agents, and specialized phosphorylation catalysts. Single-source vulnerability persists around Moroccan state-controlled mining entities controlling merchant-grade phosphate rock. Distribution runs through nominated distributor arrangements in Osaka and Tokyo rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halogen-free flame retardant chemistry is displacing legacy brominated formulations in PCB laminates, compressing timelines for suppliers to reposition around phosphorus-based alternatives.
For Market Incumbents: Acquire continuous-flow phosphorylation reactor assets to defend against batch-process competitors losing selectivity advantages. Secure REACH-compliant mammalian study data through captive toxicology partnerships before ECHA's extended one-generation reproductive toxicity requirements tighten. Backward integration into phosphorus chemistry from Cologne-Rheinland or comparable production bases sustains flame retardant supply chain control against raw material availability shocks.
For New Entrants and Emerging Players: Brazilian agrochemical formulators seeking phosphoramidate production alternatives represent the most penetrable buyer archetype, with ANVISA registration pathways remaining underdeveloped by incumbent suppliers. Establish São Paulo technical sales offices to capture first-mover positioning in pesticide intermediate localization. Battery electrolyte additive development for Korean and Japanese lithium-ion cell suppliers offers parallel qualification pathways through pilot-scale batch evaluation.
For Investors and Strategic Acquirers: Exit pathways concentrate in research-grade custom synthesis boutiques serving pharmaceutical nucleotide analog development, where concentrated margin pools justify premium multiples. Five-to-ten year viability hinges on regulatory chemistry capabilities rather than commodity scale. Watch ECHA substance evaluation criteria updates as the inflection signal—tightened impurity profiling requirements would accelerate consolidation among REACH-registered suppliers versus unregistered traders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Lanxess AG's captive phosphorus chemistry control insulates flame retardant supply from Moroccan export quota volatility. |
| Green Manufacturing Transition | EU Green Deal phosphorus recovery mandates stimulate investment in sewage sludge purification for European feedstock diversification. |
| Long-term Supply Agreement | Yangtze River Delta compounders negotiate multi-year offtakes to secure raw material availability against Chinese export restrictions. |
| Joint Venture | Swiss and Massachusetts CDMOs partner on microreactor train installations for just-in-time phosphorylating agent production. |
| Regulatory Certification Investment | Merck KGaA leverages analytical standards portfolio to anchor premium positioning in REACH-regulated jurisdictions. |
Study Parameters
Multi-period observation of phosphate rock export quotas, REACH registration timelines, and PLI scheme uptake rates anchored the trend analysis, supplemented by interviews with plant managers at Indian agrochemical formulators, procurement leads at German electronics manufacturers, distribution channel partners in São Paulo, and technical R&D directors at Swiss CDMOs. Secondary validation drew from Chinese MEE wastewater discharge filings, Indian DGFT import monitoring data, ECHA substance evaluation updates, and SEC 10-K disclosures from integrated phosphorus chemistry majors. Bottom-up volume builds across mono, di, and tri derivative grades triangulated against top-down phosphate ester consumption estimates from national chemical industry associations.
Input-output matrices mapped demand drivers including halogen-free flame retardant mandates, PLI scheme incentives, and continuous-flow reactor adoption against supply constraints around phosphate rock concentration and REACH compliance costs. Segmentation modeling spanned product type, application, end-use industry, packaging format, and regional production hub. CAGRs were derived from regression analysis of historical consumption patterns projected across the analysis window, with specific adjustments for Indian domestic production acceleration and Brazilian ANVISA registration pathway development.
Revisions become necessary when Moroccan or Chinese phosphate rock export quotas tighten beyond historical volatility bands, when ECHA extends reproductive toxicity study requirements to lower tonnage bands, or when Korean battery material suppliers accelerate electrolyte additive qualification timelines. Deviation in upstream mining policy or REACH evaluation criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Ferric Fluoride Market
Chemicals
Glyoxylic Acid Market
Chemicals
Coal Tar Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Aluminium Chloride Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Quaternium-15 Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Malic Acid Market