
 Wood Preservative Market | 2026-2036
Wood Preservative Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Preservative Market Intelligence
The traditional procurement model centered on large-scale industrial buyers for utility poles and railway sleepers is collapsing as demand shifts towards smaller, more frequent purchases by deck installers and residential construction firms. Koppers Performance Chemicals leverages its extensive distribution network to serve this fragmented customer base. Lonza Group AG specializes in high-performance formulations for niche construction applications. Meanwhile, LANXESS competes on the basis of its broad portfolio of both traditional and next-generation preservative chemistries.
Wood preservatives are chemical formulations that prevent degradation in timber from fungal rot, insect infestation, and moisture. Active ingredients like micronized copper azole, creosote, or borates are impregnated into the wood's cellular structure using pressure treatment. While creosote maintains a legacy position in applications like railway sleepers, copper-based and borate preservatives are expanding rapidly in residential construction. The construction frames segment commands significant volume, driven by building codes that mandate treated lumber for durability.
Regulatory bodies like the US Environmental Protection Agency (EPA) and Europe's ECHA directly control which preservative chemistries can be sold. Industry standards from the American Wood Protection Association (AWPA) and China's GB standards further govern treatment specifications for various end uses. Suppliers must now decide whether to invest in developing bio-based alternatives or reformulate existing chemistries to meet tightening restrictions on specific active ingredients.
Market Dynamics
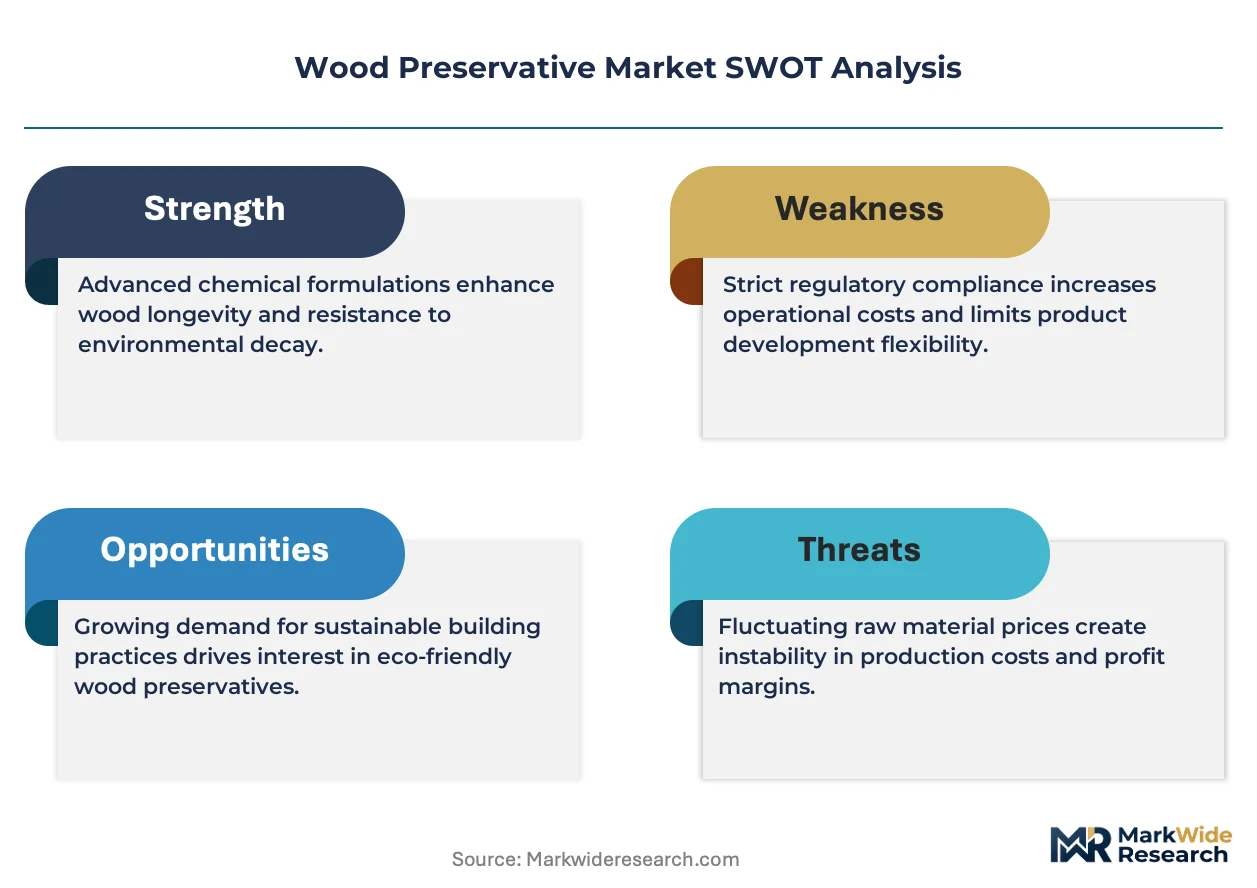
The fundamental dynamic shaping the wood preservative market is the conflict between durability mandates in construction and intensifying regulatory scrutiny over chemical toxicity. This pressure from bodies like the EPA and ECHA is forcing a structural migration from legacy preservatives to next-generation formulations.
Growth Catalysts
- Building Code Requirements:In the United States and Canada, building codes frequently mandate the use of pressure-treated lumber for critical structural components like sill plates and floor joists, creating a stable, high-volume demand base.
- Infrastructure Modernization:Government-backed projects to upgrade railway networks and electrical grids in countries like Germany and India sustain demand for traditional preservatives like creosote for sleepers and utility poles.
- Micronized Copper Technology:The development of micronized copper azole (MCA) preservatives provides a lower-toxicity alternative that meets performance standards, accelerating its adoption in residential decking and fencing applications.
Market Restraints
- Regulatory De-Registration Risk:Ongoing reviews by the US EPA and Europe's ECHA under the Biocidal Products Regulation can lead to the removal of established active ingredients from the market, creating uncertainty for formulators.
- Composite Material Substitution:The encroachment of wood-plastic composites (WPCs) and aluminum in the decking and fencing segments presents a direct substitution threat, capping growth in certain residential applications.
- Input Cost Volatility:The price of copper, a primary active ingredient in many modern preservatives, is subject to global commodity market fluctuations, directly impacting formulator cost structures and profitability.
Strategic Opportunities
- Bio-Based Formulations:Developing preservatives from renewable sources, such as essential oils or plant-based extracts, presents an opportunity to capture demand for sustainable building materials and bypass certain regulatory hurdles.
- Fire-Retardant Integration:Combining preservative properties with fire retardancy in a single treatment offers a high-value product for commercial construction, where building codes often require both protections.
- Emerging Asian Markets:Rapid growth in the construction sectors of Indonesia and Vietnam, coupled with a prevalence of wood-based building, offers significant untapped potential for preservative suppliers.
Industry Challenges
- Treatment Specification Compliance:Ensuring that treating plants consistently meet the precise penetration and retention specifications outlined by standards bodies like the AWPA for new formulations is a persistent operational hurdle.
- End-of-Life Disposal:Managing the disposal and recycling of treated wood at the end of its service life is a growing environmental challenge, with increasing landfill restrictions and public concern.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Preservative Market |
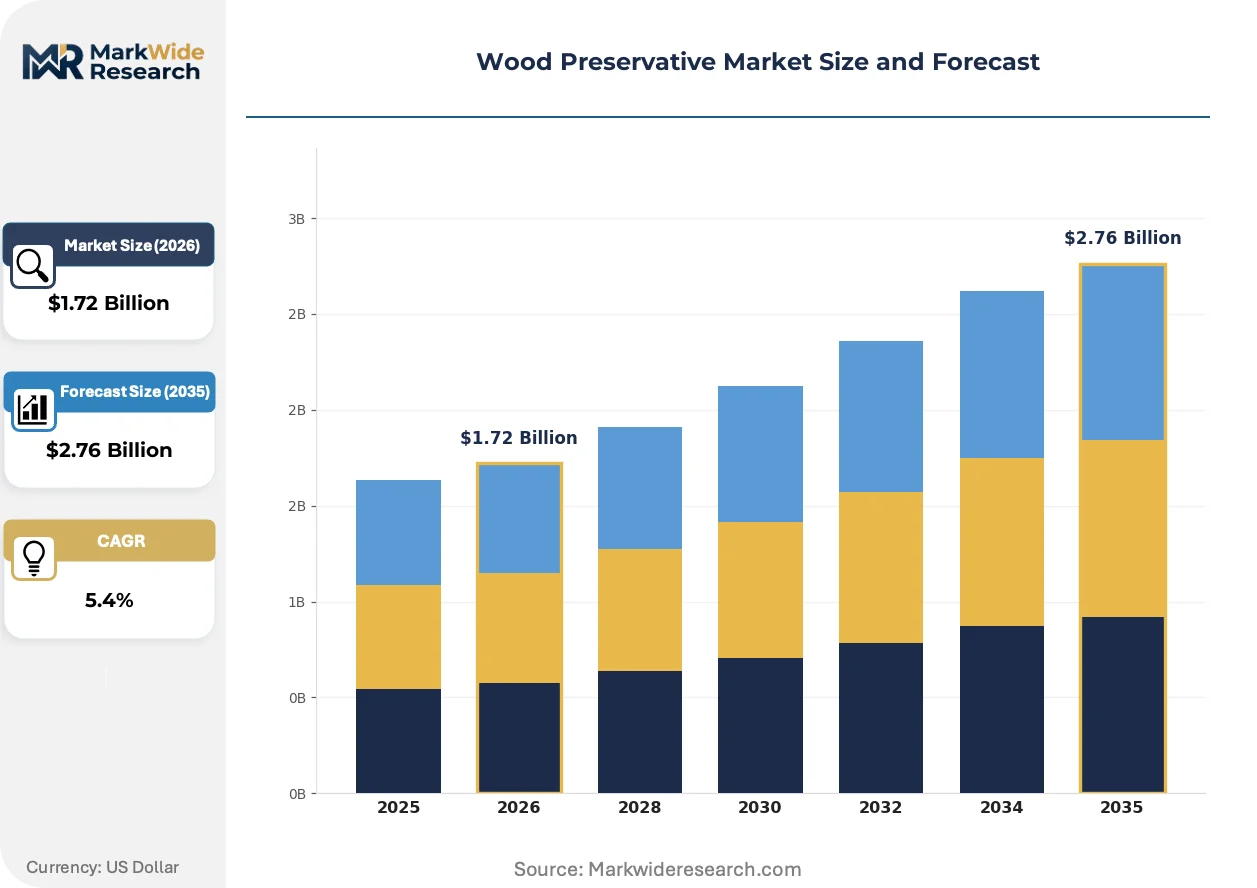
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $2.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creosote, Copper Naphthenate, Borate, Zinc Naphthenate, Organic Solvent Preservatives Application: Furniture Manufacturing, Utility Poles, Railway Sleepers, Flooring, Construction Frames End User Industry: Woodworking Facilities, Outdoor Equipment Fabricators, Cabin Builders, Deck Installers, Panel Manufacturers Form: Liquid, Powder, Emulsion, Paste, Concentrate |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., Koppers Performance Chemicals, RPM International Inc., The Sherwin-Williams Company, LANXESS, BASF SE, Jotun A/S, Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Preservative Market Strategic Shifts & Innovations
A primary trend involves the industry-wide reformulation of products to balance efficacy against environmental and health profiles. This imperative drives innovation in both active ingredients and the delivery systems used to impregnate wood, altering performance and cost equations.
Micronized copper preservatives utilize finely ground particles of copper carbonate suspended in a liquid carrier to protect wood. Residential construction and decking installers are rapidly adopting these systems due to their improved safety profile and lower corrosivity to fasteners. This technology is displacing older soluble copper formulations, which had greater potential for environmental leaching and soil contamination.
Europe's Biocidal Products Regulation (BPR) mandates a rigorous, data-intensive authorization process for all preservative active ingredients and treated articles sold in the EU. This has increased compliance costs substantially, forcing a market consolidation around fewer, well-documented chemistries. The residential decking segment is most affected, with treaters reformulating products to use BPR-authorized preservatives to maintain market access.
A clear shift in purchasing behavior sees the decline of large, cyclical contracts from utility and railway operators as the market's primary demand driver. The customer base is fragmenting towards smaller, more frequent orders from residential building material distributors and deck installation contractors. This pattern is most pronounced in the robust housing renovation markets of the United States and Germany.
Wood Preservative Market Segmentation

The wood preservative market exhibits diverse requirements driven by varying wood types, environmental exposures, and regulatory mandates across applications. Understanding these distinct segments is crucial for suppliers to tailor product offerings and navigate complex compliance landscapes effectively.
Product Type:
The wood preservative market faces significant substitution pressure across its product types, driven by evolving environmental regulations and performance demands.
- Borate:Borate preservatives utilize boron compounds, typically sodium borates, which are effective against fungi and insects and have a low mammalian toxicity profile. Demand for borate treatments is expanding rapidly in residential construction, particularly for framing lumber and interior applications in the United States.
- Copper Naphthenate:Copper naphthenate is an oil-borne preservative known for its effectiveness against decay fungi and termites, often used in non-pressure applications. Its adoption is increasing in niche outdoor applications and for utility poles in Canada, where creosote restrictions are tightening.
- Creosote:Creosote is a tar-based preservative primarily used for heavy-duty applications like railway sleepers and utility poles, maintaining a legacy position despite regulatory scrutiny.
- Zinc Naphthenate:Zinc naphthenate provides fungicidal and insecticidal protection, often applied to wood products where a clear finish or paintability is desired.
- Organic Solvent Preservatives:These formulations use organic solvents to deliver active ingredients, offering clean treatment and paintable surfaces for various wood products.
Creosote retains volume leadership in specific heavy-duty applications; borate treatments hold the steepest expansion curve in residential construction.
Application:
The wood preservative market exhibits significant application diversity, each with distinct performance requirements and treatment specifications.
- Construction Frames:This segment covers lumber treated for structural components in residential and commercial buildings, including sill plates, joists, and decking supports. Building codes in the United States and Canada frequently mandate treated lumber for these critical applications, ensuring consistent demand.
- Utility Poles:Preservatives for utility poles prevent degradation from fungal rot and insect infestation, ensuring the longevity and safety of electrical and telecommunication infrastructure. Government-backed projects in countries like Germany and India sustain demand for these long-service-life treated wood products.
- Railway Sleepers:Preservatives impregnate railway sleepers to protect against decay and insect damage, critical for maintaining rail network integrity.
- Flooring:Treated wood for flooring applications, particularly for outdoor decking, requires protection against moisture and biological degradation.
- Furniture Manufacturing:This application involves treating wood for outdoor furniture, ensuring durability and resistance to environmental elements.
Construction frames represent the largest volume segment, while flooring applications show significant growth potential driven by outdoor living trends.
End User Industry:
Procurement patterns within the wood preservative market are undergoing a structural shift, impacting various end-user industries differently.
- Deck Installers:These professionals purchase treated lumber and associated preservatives for residential and commercial outdoor decking projects, often favoring lower-toxicity micronized copper formulations. Demand is fragmenting towards more frequent, smaller orders from these contractors, particularly in robust housing renovation markets like the United States.
- Woodworking Facilities:These facilities procure preservatives for a diverse range of products, from garden furniture components to specialized architectural elements requiring enhanced durability. Compliance with diverse regional building codes and environmental regulations dictates the choice of preservative chemistries for these varied applications.
- Cabin Builders:Cabin builders utilize wood preservatives for log homes and rustic structures, ensuring long-term protection against decay and insects in exposed environments.
- Outdoor Equipment Fabricators:This segment applies preservatives to wood components used in playgrounds, park benches, and other exterior equipment, prioritizing safety and weather resistance.
- Panel Manufacturers:Panel manufacturers treat engineered wood products like plywood and OSB for specific applications requiring enhanced resistance to moisture and biological agents.
Demand from woodworking facilities remains broadly distributed; however, the customer base of deck installers is concentrating in key renovation markets.
Form:
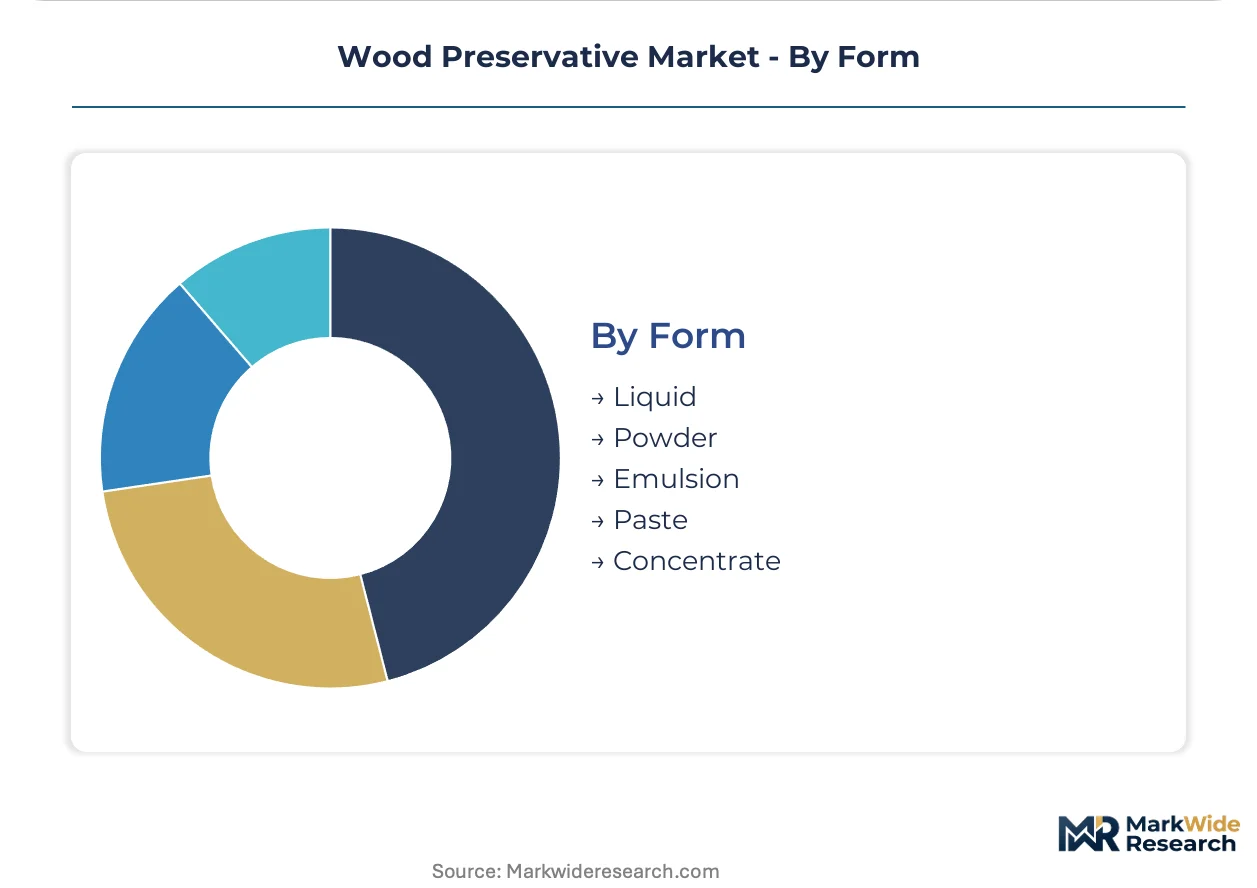
The choice of preservative form is dictated by the treating process and desired penetration, influencing supply chain logistics.
- Liquid:Liquid preservatives are ready-to-use solutions, often pre-diluted for direct application in pressure treatment cylinders, ensuring consistent chemical uptake. This form minimizes on-site mixing requirements, streamlining operations for high-volume treating plants in North America.
- Concentrate:Concentrates are highly potent formulations that require dilution with water or oil before application, offering cost efficiencies in shipping and storage for large-scale industrial users. Treating plants often purchase concentrates to achieve specific retention levels for diverse wood species and end-use applications.
- Powder:Powdered preservatives, typically borates, are dissolved on-site, offering flexibility in formulation strength and ease of transport.
- Emulsion:Emulsion forms allow oil-borne active ingredients to be dispersed in water, facilitating cleaner application and broader wood penetration.
- Paste:Paste preservatives are often used for remedial treatments or localized protection of wood in service, applied directly to affected areas.
Liquid forms offer immediate operational efficiency for treaters; concentrates provide greater flexibility for customized formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized wood preservative formulations often flow from manufacturing centers in Europe and North America to robust construction markets globally. This trade supports diverse applications, from residential decking in the United States to infrastructure projects in India. The interplay of regulatory frameworks and local building practices shapes regional demand.
United States
Robust housing renovation and new build activity drives demand for treated lumber. Building codes frequently mandate pressure-treated lumber for structural components like sill plates and floor joists. The Pacific Northwest, with its extensive timber industry, sees high demand for micronized copper azole treatments.
Germany
Infrastructure modernization projects sustain demand for traditional preservatives for railway sleepers and utility poles. Europe's Biocidal Products Regulation (BPR) influences the chemistries available for residential applications. Bavaria, a region with strong construction activity, prioritizes BPR-authorized preservatives for outdoor wood.
India
Government-backed initiatives to upgrade railway networks and electrical grids create consistent demand for heavy-duty preservatives. The Bureau of Indian Standards (BIS) governs treatment specifications for various timber applications. Major urban centers like Mumbai and Delhi require preservative-treated wood for public infrastructure.
Canada
Building codes frequently mandate pressure-treated lumber for critical structural components, similar to the United States. Health Canada's Pest Management Regulatory Agency (PMRA) oversees the approval of wood preservative active ingredients. British Columbia, with its significant forestry sector, utilizes copper naphthenate for utility poles.
Indonesia
Rapid growth in the construction sector, particularly for wood-based building, offers significant untapped potential for preservative suppliers. Local regulations guide the use of treated timber to ensure durability in tropical climates. Jakarta's expanding urban development projects require treated wood for various building elements.
Wood Preservative Market Key Industry Players
Player mix skews toward diversified chemical manufacturers and specialized performance chemical providers. The market exhibits a tiered structure, with large global players alongside niche formulators. Strategic archetypes include those focusing on regulatory compliance and those emphasizing bio-based alternatives. Portfolio diversification and geographic expansion are common competitive moves.
Specialists in high-performance formulations include Lonza Group AG, which focuses on niche construction applications. Koppers Performance Chemicals exemplifies a player leveraging an extensive distribution network to serve a fragmented customer base. LANXESS, a diversified chemical company, anchors a broad portfolio of both traditional and next-generation preservative chemistries.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| Koppers Performance Chemicals |
| RPM International Inc. |
| The Sherwin-Williams Company |
| LANXESS |
| BASF SE |
| Jotun A/S |
| Lonza Group AG |
| Others |
Cost & Logistics Intelligence
Europe's Biocidal Products Regulation (BPR) gates both supply qualification and price differentiation, mandating rigorous authorization processes for wood preservative chemistries. This regulatory framework significantly impacts market access and cost structures for formulators.
Pricing Analysis
The technology-generation pricing gap differentiates legacy creosote treatments from next-generation micronized copper azole formulations. Pricing predominantly follows a per-unit transactional model for residential construction, shifting to contract-based long-term offtake for utility poles. Price differentiation stems from performance against specific degradation types and BPR authorization status. Input cost volatility, particularly for copper, creates pricing pressure. Deck installers exhibit high price sensitivity, while utility companies prioritize long-term performance for critical infrastructure.
Supply Chain Analysis
Inbound logistics costs for active ingredients like copper and borates impact formulator profitability, particularly from major production hubs in Europe and North America. The supply chain for wood preservatives draws from key chemical manufacturing centers, with raw material dependencies on copper, borate minerals, and creosote feedstocks. Regulatory restrictions on specific active ingredients, such as those from the US EPA and ECHA, pose a significant structural risk. Distribution runs through a fragmented network of specialized chemical distributors and building material suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood preservative market exhibits a defensive-moat story, primarily due to regulatory entrenchment. Extensive authorization processes under frameworks like Europe's BPR create high barriers to entry and significant switching costs for formulators.
For Market Incumbents: Shield core market share by actively investing in bio-based R&D to counter regulatory de-registration risk. Incumbents should deepen channel control through their extensive distribution networks, particularly in fragmented residential markets. Pursue strategic acquisitions of niche formulators specializing in BPR-authorized chemistries to consolidate portfolio breadth. This approach mitigates the threat from composite material substitution in key applications like decking.
For New Entrants and Emerging Players: Anchor in emerging Asian markets, particularly Indonesia's rapidly growing residential construction sector. Develop bio-based formulations that offer a multi-functional value proposition, combining preservation with fire retardancy for commercial construction. Target woodworking facilities and cabin builders with sustainable, compliant solutions. This strategy leverages underpenetrated geographies and unmet demand for integrated protection.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across next-generation preservative formulation development, driven by R&D and regulatory compliance costs. The market offers long-term viability due to stable demand from building codes and infrastructure modernization projects. Investors should target specialized performance chemical providers with robust intellectual property in bio-based or low-toxicity chemistries. The signal to watch is the pace of new active ingredient approvals by the US EPA and Europe's ECHA.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Preservative R&D | Develops sustainable alternatives to meet tightening ECHA and EPA restrictions on traditional chemistries. |
| Micronized Copper Capacity Expansion | Addresses growing demand from residential decking installers in the United States and Germany. |
| Regulatory Compliance Investment | Ensures market access for formulations under Europe's Biocidal Products Regulation and AWPA standards. |
| Integrated Fire Retardant Development | Creates high-value products for commercial construction, where building codes mandate dual protection. |
| Distribution Network Optimization | Serves the fragmented customer base of deck installers and residential construction firms efficiently. |
Research Approach
A standing panel of wood treaters, chemical formulators, building code officials, and residential contractors provided ongoing calibration for primary insights. This was combined with exhaustive secondary research, including regulatory filings from the US EPA and Europe's ECHA, industry association reports like AWPA standards, and global trade statistics. Outputs were validated through a rigorous bottom-up and top-down triangulation process, ensuring robust market sizing.
Outputs were consistently validated against external benchmarks and macro-economic indicators throughout the forecast period. The analytical framework modeled market dynamics across product type, application, end user industry, form, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected shifts in market fundamentals. Key forecast inputs included construction spending trends and global raw material commodity prices.
Decision-makers should treat outputs as directional under assumptions of a stable regulatory environment and consistent global construction activity; material deviation would warrant model refresh. Forecasts reflect these base assumptions. Unforeseen regulatory bans or severe economic downturns represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Chlorine Trifluoride Market