
 P-Hydroxybenzoic Acid (PHBA) Market | 2026-2036
P-Hydroxybenzoic Acid (PHBA) Market Size, Share, and Industry Trends Forecast 2026-2036
P-Hydroxybenzoic Acid (PHBA) Market Analytics
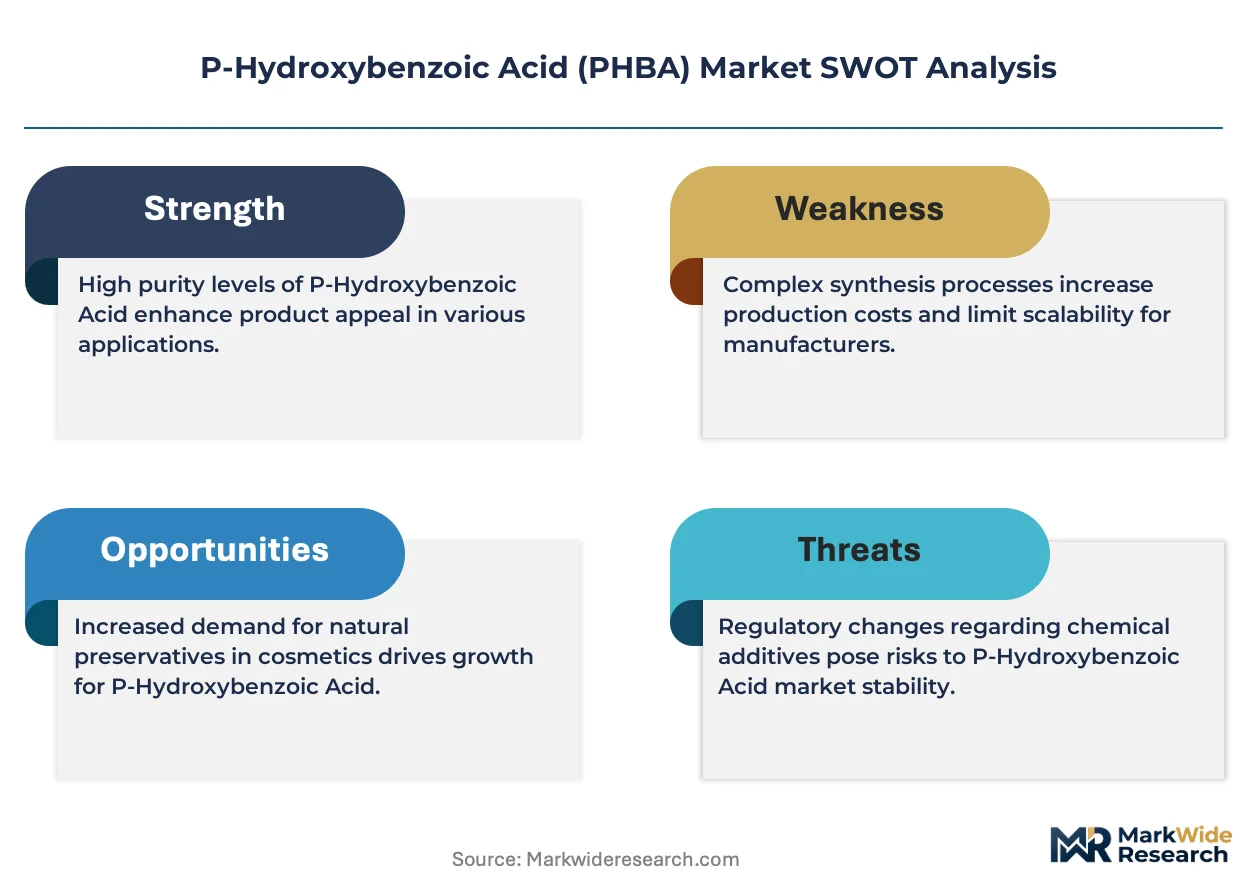
A shortage of process chemists skilled in Kolbe-Schmitt carboxylation is redrawing competitive boundaries for high-purity PHBA output. Zhejiang Shengxiao Chemicals leverages captive salicylic acid supply to anchor cost positions in pharmaceutical-grade batches. Ueno Fine Chemicals sustains Japanese market presence through exacting cosmetic-grade specifications. Leuna Carboxylation Plant GmbH dominates European technical-grade channels with integrated phenol-to-acid capability.
P-Hydroxybenzoic Acid is a monohydroxybenzoic acid isomer with a hydroxyl group at the para position, typically synthesized via Kolbe-Schmitt electrolytic carboxylation of sodium phenoxide under elevated temperature and pressure, yielding a white crystalline powder used primarily as a precursor for paraben preservatives, liquid crystal polymers, and pharmaceutical intermediates. Pharmaceutical-grade PHBA commands the deepest margin pool due to USP and EP certification burdens, while cosmetic-grade volume accelerates fastest as clean-label preservative demand from Southeast Asian formulators intensifies. Industrial-grade supply remains structurally commoditized, with price tension concentrated in Chinese bulk export channels.
FDA oversight of paraben safety in topical formulations and EPA industrial chemical reporting under TSCA shape product liability and market access thresholds for US-bound shipments. ECHA REACH registration requirements and the EU Cosmetics Regulation restrict non-compliant cosmetic-grade imports, forcing third-country exporters to upgrade analytical certification. REACH Article 33 supply-chain communication obligations are extending testing costs downstream to distributors. Stakeholders must monitor evolving paraben restriction proposals in European member states and calibrate grade-mix investments accordingly.
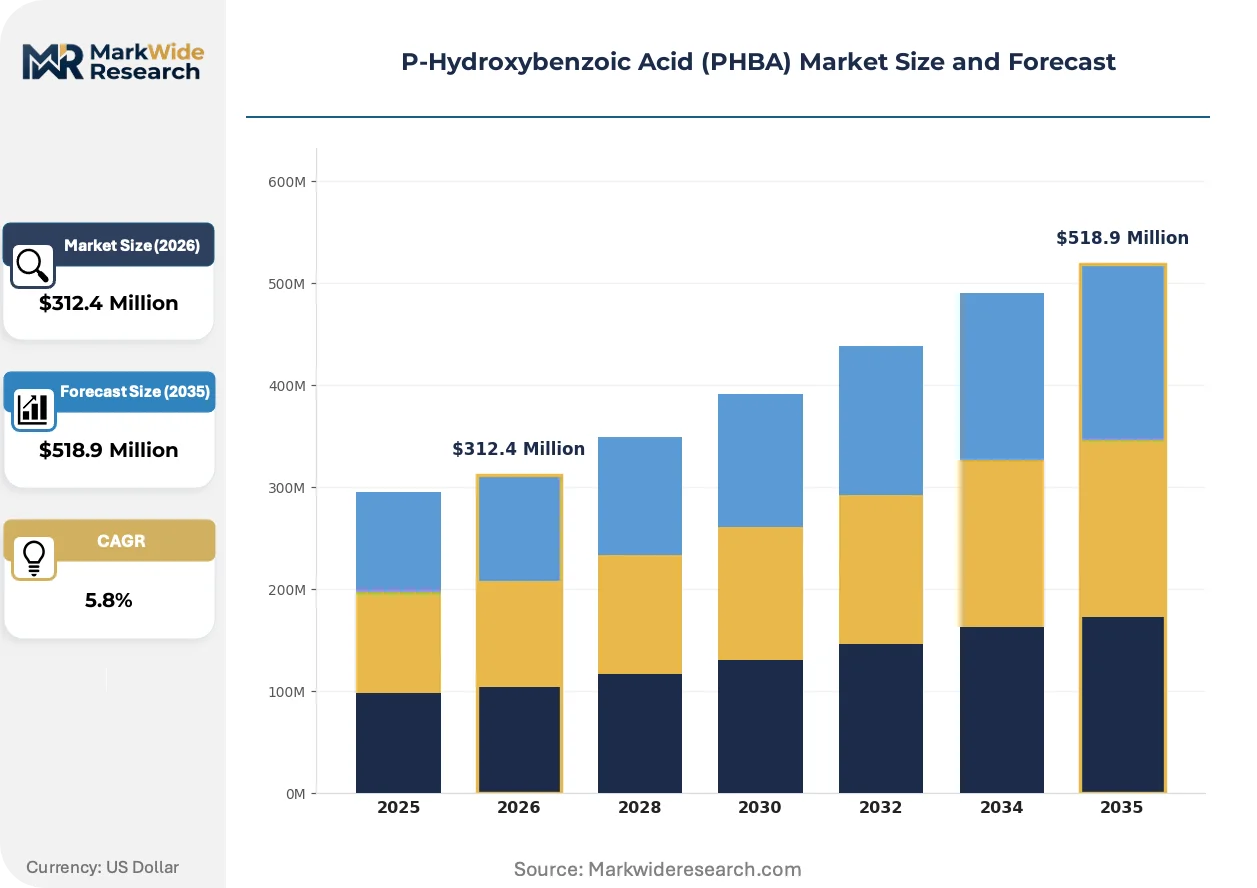
Market Dynamics
Kolbe-Schmitt carboxylation capacity scarcity is compressing pharmaceutical-grade supply chains, forcing formulators to secure multi-year offtake agreements with phenol-integrated producers.
Growth Catalysts
- Paraben preservative demand from Southeast Asian cosmetics:Clean-label formulations in Thailand and Vietnam are absorbing cosmetic-grade PHBA volumes faster than regional salicylic acid supply can expand.
- REACH Article 33 supply-chain communication:Downstream distributors across Germany and France now demand certified analytical documentation, filtering out non-compliant bulk exporters and tightening legitimate supply channels.
- Liquid crystal polymer feedstock qualification:Japanese and Korean electronics manufacturers are qualifying PHBA-derived monomers for next-generation display substrates, opening a high-specification demand vertical.
Market Restraints
- Phenol price volatility:Crude benzene derivative costs swing with refinery operating rates, compressing margins for non-integrated carboxylation operators.
- Salicylic acid supply concentration:Captive production in Zhejiang and Shandong provinces leaves third-party PHBA producers exposed to input allocation decisions by integrated phenol-salicylic acid complexes.
- Paraben substitution by phenoxyethanol and organic acids:EU member state restriction proposals are accelerating preservative reformulation in rinse-off personal care, eroding PHBA derivative demand in cosmetic applications.
Strategic Opportunities
- Indian pharmaceutical intermediate export expansion:CDSCO-compliant manufacturers in Hyderabad and Ahmedabad are scaling USP-grade batches for generic API producers targeting FDA-regulated markets.
- Biobased phenol feedstock integration:Lignin-derived phenol pilot plants in Finland and Canada could decouple PHBA production from petrochemical benzene exposure.
- Dual-carbon policy alignment in China:MEE emissions intensity targets are rewarding electrolytic carboxylation operators with carbon-accounted product certification for EU-bound shipments.
Industry Challenges
- Process chemist scarcity in Kolbe-Schmitt optimization:Retirement waves among European and Japanese technical specialists are extending batch qualification timelines for pharmaceutical-grade output.
- USP and EP certification timeline compression:Analytical method validation for residual phenol and isomeric purity now requires 18-24 months, delaying new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | P-Hydroxybenzoic Acid (PHBA) Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Cosmetic Grade, Industrial Grade Application: Preservative, Flavoring Agent, Aromatic Compound, Stabilizer End User: Pharmaceuticals, Food & Beverage, Cosmetics, Chemicals Packaging Type: Drums, Bags, Bottles, Tubes |
| Companies Covered | Zhejiang Shengxiao Chemicals Co., Ltd., Ueno Fine Chemicals, San Fu Chemical, Leuna Carboxylation Plant GmbH, Jiangsu Bvco, Suqian 3E New Material, Salicylates and Chemicals, Alta Laboratories Ltd, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P-Hydroxybenzoic Acid (PHBA) Market Evolving Landscape
Electrochemical process intensification and regulatory compliance automation are redrawing technical boundaries for PHBA production economics.
Continuous-flow electrolytic carboxylation is decomposing the batch-scale bottleneck that has constrained Kolbe-Schmitt throughput for decades. German and Swiss engineering firms are installing modular reactor skids for pharmaceutical-grade campaigns. This technology is decomposing the minimum efficient scale threshold, enabling mid-volume producers to achieve cost parity with legacy phenol-integrated complexes.
ECHA REACH restriction dossiers on propylparaben and butylparaben are forcing cosmetic formulators toward methyl- and ethyl-paraben blends with lower hazard classifications. The EU Cosmetics Regulation amendment timeline is compressing reformulation windows to 24 months. Southeast Asian exporters are responding by upgrading analytical certification infrastructure to retain European market access.
Direct procurement from carboxylation plant operators is displacing layered distributor networks for pharmaceutical-grade volumes. Large generic API manufacturers in India and China now negotiate annual contracts with phenol-integrated producers, bypassing regional trading houses. This pattern is most visible in Gujarat and Jiangsu provinces, where backward-integrated pharmaceutical conglomerates are consolidating supply relationships.
P-Hydroxybenzoic Acid (PHBA) Market Segmentation
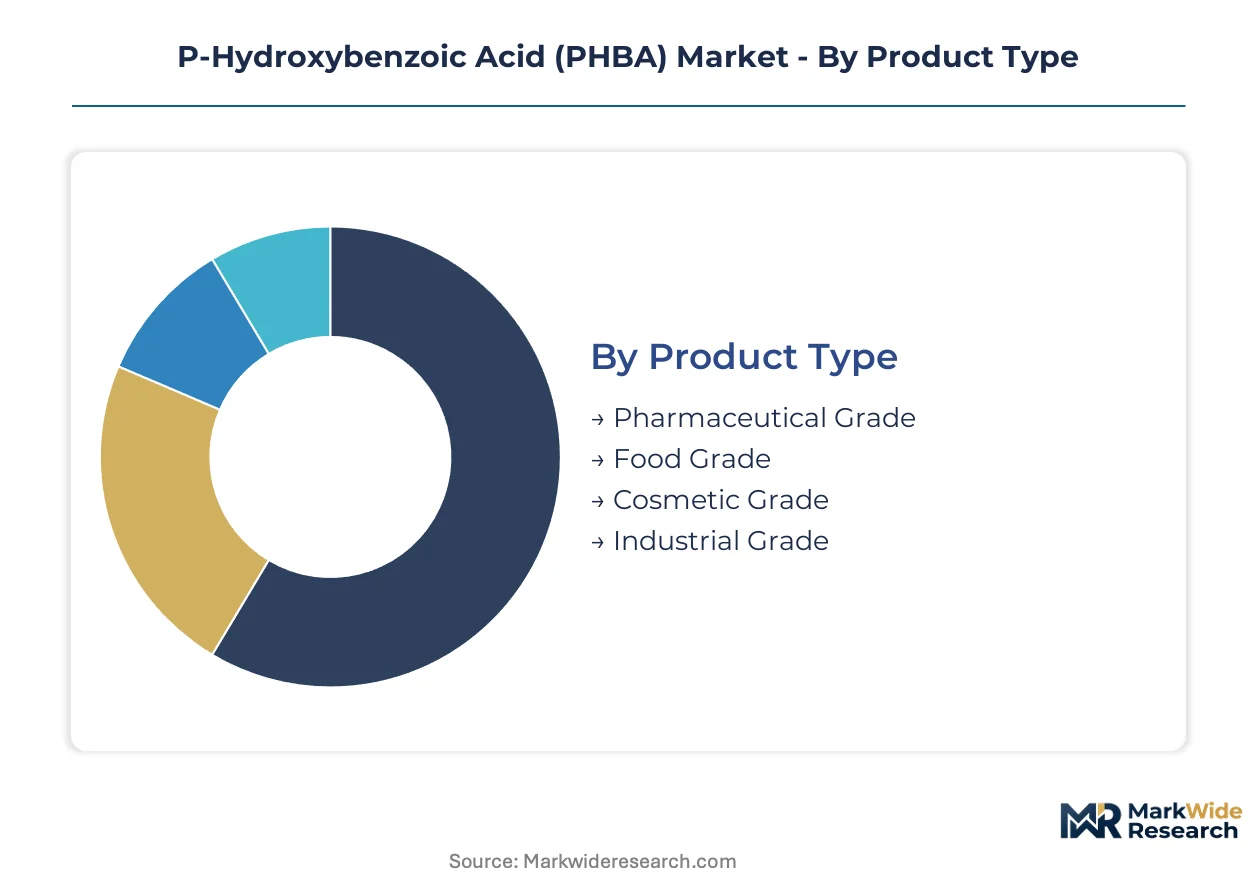
PHBA market segmentation reflects divergent purity requirements across regulatory jurisdictions and end-use applications. Each grade tier commands distinct certification burdens and geographic demand patterns that reshape supplier competitive positioning.
Product Type:
Pharmaceutical-grade batches dominate export-led channels to FDA-regulated markets, while cosmetic-grade supply concentrates in domestic formulations across Southeast Asian manufacturing clusters.
- Pharmaceutical Grade:USP and EP-certified batches require residual phenol below 0.1% and isomeric purity exceeding 99.5%. Demand concentrates in Indian generic API manufacturers supplying FDA-regulated markets, with CDSCO-compliant facilities in Hyderabad scaling output for paraben-based preservative systems. Certification timelines now extend 18-24 months, filtering out non-specialized producers.
- Cosmetic Grade:REACH and RoHS-compliant specifications govern European market access, with hazard classification restrictions on propylparaben and butylparaben derivatives forcing reformulation toward methyl- and ethyl-paraben blends. Southeast Asian formulators in Thailand and Vietnam are absorbing volumes faster than regional salicylic acid supply can expand.
- Food Grade:FSSAI and FDA food additive regulations restrict deployment to specific flavoring applications with strict migration limits.
- Industrial Grade:Technical specifications for liquid crystal polymer feedstock and chemical intermediate use dominate Japanese and Korean electronics supply chains.
Pharmaceutical Grade holds the largest share; momentum sits with Cosmetic Grade as clean-label preservative demand intensifies.
Application:
Cost tier stratification separates high-specification pharmaceutical and electronics applications from commoditized industrial uses.
- Preservative:Paraben-based systems in topical pharmaceuticals and personal care formulations command premium pricing due to antimicrobial efficacy against gram-positive and gram-negative organisms. EU Cosmetics Regulation amendments are compressing reformulation windows, while phenoxyethanol substitution erodes share in rinse-off products.
- Aromatic Compound:Liquid crystal polymer monomer qualification for display substrates requires exacting thermal stability specifications. Japanese and Korean electronics manufacturers are qualifying PHBA-derived feedstocks for next-generation substrate production.
- Flavoring Agent:Limited food-grade deployment under strict regulatory thresholds constrains volume expansion.
- Stabilizer:Industrial polymer and coating applications operate on price-sensitive procurement with minimal certification overhead.
Preservative applications command the deepest margin pool; aromatic compound qualification is climbing the fastest as electronics demand verticalizes.
End User:
Customer type fragmentation separates regulated pharmaceutical procurement from discretionary cosmetic and industrial purchasing.
- Pharmaceuticals:Generic API manufacturers in Gujarat and Jiangsu provinces negotiate direct annual contracts with phenol-integrated carboxylation operators, bypassing distributor networks. USP and EP certification burdens create procurement stickiness once supplier relationships are established.
- Cosmetics:Southeast Asian formulators prioritize REACH-compliant documentation to retain European market access, upgrading analytical certification infrastructure rapidly.
- Food & Beverage:Regulatory restrictions on direct food contact limit deployment primarily to flavoring agent intermediates with migration testing requirements.
- Chemicals:Technical-grade procurement for liquid crystal polymer and specialty chemical synthesis operates on spot-market dynamics with benzene derivative price exposure.
Pharmaceuticals holds the largest share; Cosmetics is gaining share fastest as regional manufacturing clusters scale.
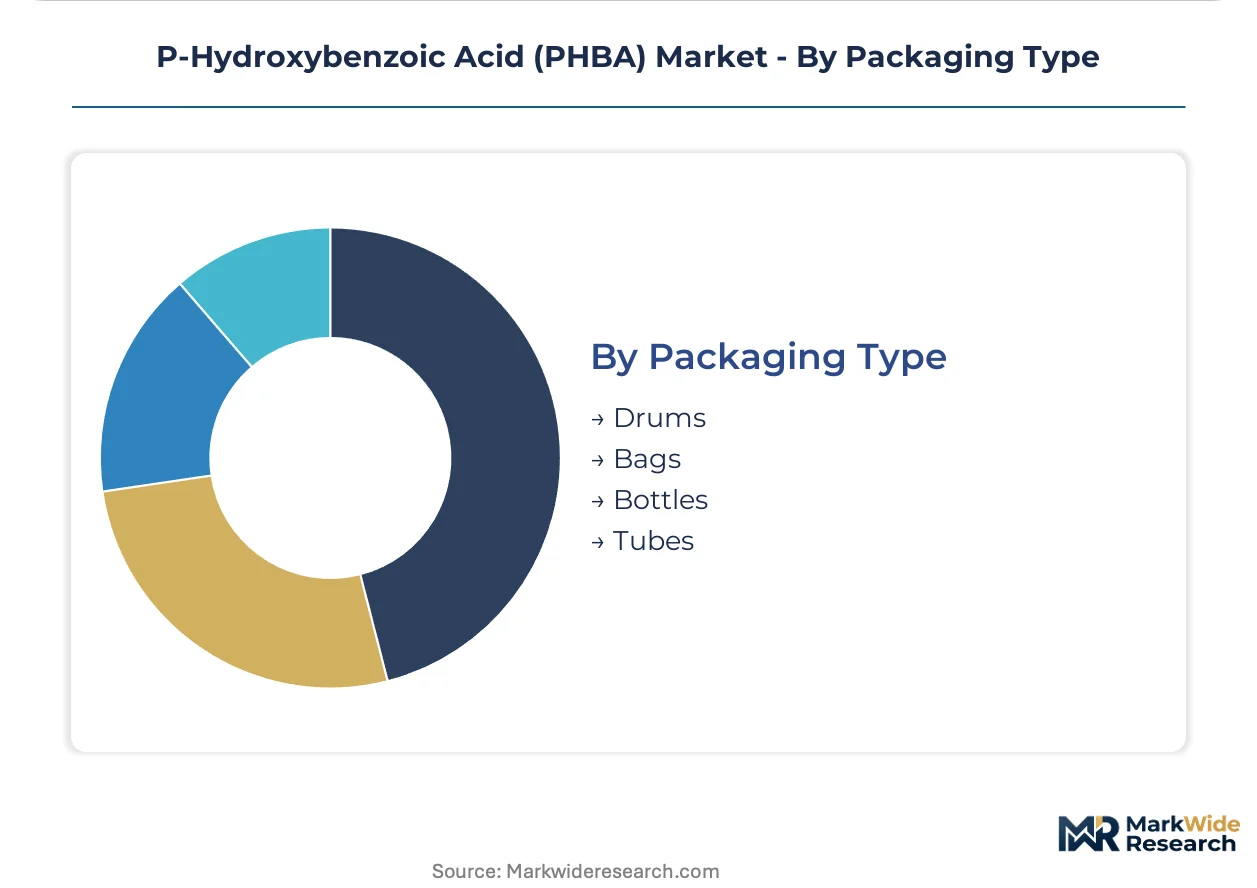
Packaging Type:
Supply concentration in bulk formats reflects the commodity chemistry economics of industrial-grade distribution.
- Drums:Standard 200-liter steel and HDPE containers dominate pharmaceutical and cosmetic-grade shipments requiring moisture protection and batch traceability. German and French distributors now demand REACH Article 33 supply-chain communication documentation for drum-level shipments.
- Bags:Multi-layer laminated sacks with nitrogen flushing serve food-grade and select cosmetic applications requiring oxidation protection.
- Bottles:Laboratory-scale and sampling quantities for analytical method validation and new product development.
- Tubes:Minimal deployment for specialized pharmaceutical compounding applications.
Drums holds the largest share; Bags represent the steepest expansion trajectory as Southeast Asian logistics infrastructure upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European formulators absorb cosmetic-grade volumes under tightening hazard classifications, while Indian pharmaceutical clusters scale USP-certified output for generic API export. Chinese manufacturing bases feed both electronics-grade monomer demand and bulk preservative intermediates.
China
Yangtze River Delta chemical complexes dominate electrolytic carboxylation capacity for pharmaceutical and electronics-grade batches. MEE emissions intensity targets under dual-carbon policy reward carbon-accounted product certification for EU-bound shipments. Zhejiang and Jiangsu provinces anchor phenol-integrated production clusters with captive salicylic acid supply.
India
Hyderabad and Ahmedabad CDSCO-compliant facilities scale USP-grade output for paraben-based preservative systems targeting FDA-regulated markets. FSSAI food additive regulations constrain domestic flavoring agent deployment to strict migration limits. Gujarat-based pharmaceutical conglomerates negotiate direct annual contracts with carboxylation operators, bypassing distributor networks.
Germany
Leuna chemical complex dominates European technical-grade channels with integrated phenol-to-acid capability. ECHA REACH Article 33 supply-chain communication obligations extend testing costs downstream to distributors. German and French distributors now demand certified analytical documentation for drum-level pharmaceutical and cosmetic-grade shipments.
Japan
Kanto and Kansai electronics manufacturers qualify PHBA-derived liquid crystal polymer monomers for next-generation display substrates. METI industrial standards govern high-specification feedstock qualification timelines. Ueno Fine Chemicals sustains domestic market presence through exacting cosmetic-grade specifications.
United States
FDA oversight of paraben safety in topical formulations shapes product liability thresholds for imported preservative intermediates. EPA industrial chemical reporting under TSCA constrains non-compliant bulk shipments. Generic API manufacturers in New Jersey and Puerto Rico secure multi-year offtake agreements with phenol-integrated producers.
P-Hydroxybenzoic Acid (PHBA) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in PHBA supply. Phenol-captive carboxylation operators command cost positions in pharmaceutical-grade batches, while regional specialists serve cosmetic and technical specifications. Three archetypes dominate: integrated phenol-salicylic acid complexes, standalone carboxylation specialists, and diversified fine chemical conglomerates. Competitive moves center on backward integration into salicylic acid supply and multi-year offtake contracting with generic API manufacturers.
Among Chinese producers, Zhejiang Shengxiao Chemicals Co., Ltd. exemplifies the integrated archetype with apparent captive feedstock positioning. Ueno Fine Chemicals occupies a specialist tier position serving exacting specification markets. Leuna Carboxylation Plant GmbH anchors European technical-grade supply from its namesake industrial complex.
| Leading Market Players |
|---|
| Zhejiang Shengxiao Chemicals Co., Ltd. |
| Ueno Fine Chemicals |
| San Fu Chemical |
| Leuna Carboxylation Plant GmbH |
| Jiangsu Bvco |
| Suqian 3E New Material |
| Salicylates and Chemicals |
| Alta Laboratories Ltd |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Phenoxyethanol substitution in European rinse-off cosmetics is redrawing supply geography toward Southeast Asian methyl-paraben hubs while compressing pricing power for commodity-grade exporters locked into legacy propylparaben channels. This dual displacement forces Chinese bulk producers to absorb benzene derivative volatility without recourse to premium-grade certification premiums.
Pricing Analysis
Long-term offtake contracts now dominate pharmaceutical-grade procurement as Indian generic API manufacturers bypass spot markets to secure phenol-integrated supply from Jiangsu and Gujarat producers. Price differentiation separates USP-certified batches with 18-24 month validation timelines from technical-grade spot transactions. Cost compression in cosmetic-grade channels intensifies as REACH Article 33 documentation burdens filter out non-compliant exporters. Spot-market buyers in industrial applications exhibit highest price sensitivity; pharmaceutical procurement committees prioritize supply continuity over unit economics.
Supply Chain Analysis
Strategic stockpiling of salicylic acid feedstock distinguishes phenol-integrated operators from third-party carboxylation specialists exposed to allocation decisions. Supply concentrates in China, India, and Germany, with Yangtze River Delta complexes and Leuna anchoring pharmaceutical and technical-grade output respectively. Raw material dependencies center on benzene derivatives, sodium phenoxide, and electrolytic carbon dioxide. Single-source vulnerability in Kolbe-Schmitt process chemist expertise extends batch qualification timelines. Distribution runs through direct procurement relationships displacing layered distributor networks for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The P-Hydroxybenzoic Acid market sits in early-cycle expansion as liquid crystal polymer feedstock qualification by Japanese electronics manufacturers opens a high-specification demand vertical with limited incumbent penetration.
For Market Incumbents: Fortify backward integration into captive salicylic acid supply to anchor cost positions against phenol price volatility. Secure multi-year offtake agreements with CDSCO-compliant Indian pharmaceutical manufacturers before USP certification timelines extend further. Invest in continuous-flow electrolytic carboxylation modular reactors to decompose minimum efficient scale thresholds and defend against mid-volume entrants achieving cost parity.
For New Entrants and Emerging Players: Lead with cosmetic-grade methyl-paraben blend specialization targeting Southeast Asian formulators upgrading REACH-compliant documentation infrastructure. Penetrate the Thai and Vietnamese clean-label preservative clusters where regional salicylic acid supply lags demand absorption. Establish go-to-market partnerships with German and French distributors demanding certified analytical documentation under Article 33 obligations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European carboxylation specialists holding stranded Kolbe-Schmitt capacity without phenol integration. Long-term viability over the next decade hinges on qualification for pharmaceutical-grade or liquid crystal polymer feedstock tiers. Monitor ECHA restriction dossier timelines on propylparaben and butylparaben as inflection indicators for cosmetic-grade demand mix shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salicylic Acid | Zhejiang and Shandong phenol complexes secure captive feedstock against allocation risk. |
| Continuous-Flow Reactor Installation | German and Swiss engineering skids enable mid-volume pharmaceutical-grade cost parity. |
| REACH Article 33 Documentation Infrastructure | Southeast Asian exporters upgrade certification to retain European cosmetics market access. |
| Long-Term Offtake Agreements | Indian generic API manufacturers in Gujarat bypass distributor networks for supply security. |
| Liquid Crystal Polymer Monomer Qualification | Japanese electronics manufacturers qualify PHBA-derived feedstocks for display substrate production. |
Research Methodology
Operator-level perspectives from plant managers at phenol-integrated carboxylation facilities, procurement leads at Indian generic API manufacturers, distribution channel partners in German and French cosmetic supply chains, and technical R&D directors at Japanese electronics manufacturers anchored the qualitative base. Secondary validation drew from ECHA REACH registration databases, CDSCO facility inspection records, customs and trade flow data, and SEC filings from diversified fine chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across grade tiers.
Sensitivity analysis tested forecast robustness against phenol price volatility bands, paraben substitution rates in European cosmetics, and liquid crystal polymer adoption timelines in display manufacturing. The analytical framework segmented by grade tier, end-use application, packaging format, and regional production hub across the analysis window. CAGRs derived from regression against historical pharmaceutical intermediate demand and electronics materials qualification cycles. Industry-specific inputs included Kolbe-Schmitt batch qualification timelines and dual-carbon policy compliance premiums for EU-bound Chinese shipments.
The analysis sits within stated boundaries; outcomes outside sustained phenol-integrated capacity expansion and REACH regulatory stability would require recalibration. Forecasts reflect assumptions on certification timeline trajectories and substitution elasticity in preservative reformulation. Revision becomes warranted when ECHA restriction proposals on paraben hazard classifications cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Phenothiazine Market
Chemicals
Photographic Chemicals Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Thioacetic Acid Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Pyrimidine Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Thiourea Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Caustic Soda Market
Chemicals
Menadione Market