
 Global Creosote Oil Market | 2026-2036
Global Creosote Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Creosote Oil Market Foresight
Specialty chemical distribution is fragmenting as regional timber treatment networks bypass traditional bulk intermediaries. Koppers Inc. dominates North American rail tie preservation through captive treatment facilities. Himadri Specialty Chemicals Ltd. leverages its Kolkata-based coal tar distillation complex to anchor supply for Asian marine coating formulators. ArcelorMittal S.A. competes through integrated coke-oven byproduct recovery at its European steelworks.
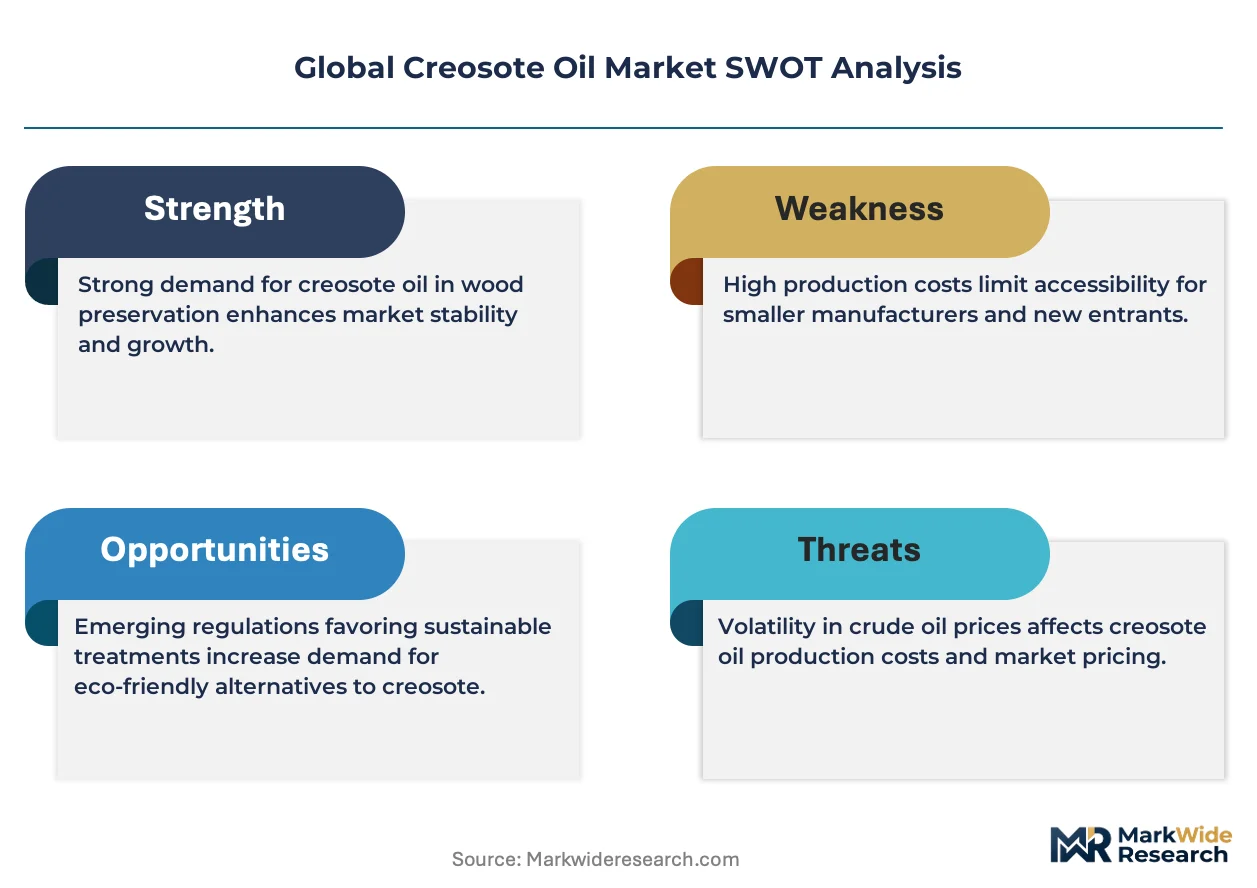
Creosote oil is a complex mixture of polycyclic aromatic hydrocarbons distilled from coal tar or wood tar, with a boiling range of 200–400°C and phenolic content that imparts biocidal and water-repellent properties. Its primary industrial purpose is pressure-impregnating timber to prevent fungal decay and insect attack in heavy civil infrastructure. Coal tar oil leads product type revenue due to established railroad and utility pole specifications, while refined oil segments attract premium positioning from marine anti-fouling formulators seeking lower PAH formulations. Wood preservation commands the largest application share, though agricultural chemicals represent a faster-growing outlet as legacy organochlorine pesticides face phase-outs.
EPA registration requirements under FIFRA constrain product entry for wood preservatives in the United States, while REACH authorization processes in Europe restrict certain PAH compositions in consumer-contact applications. China's MEE enforces emission controls on coal tar distillation that reshape regional supply availability. Stakeholders must monitor regulatory divergence between jurisdictions to determine where formulation investments align with compliant market access.
Market Dynamics
EPA and REACH restrictions on alternative biocides are redirecting timber treatment demand back toward creosote oil formulations, tightening supply availability as coal tar distillation capacity contracts under emission mandates.
Growth Catalysts
- Infrastructure replacement cycles:Aging railroad networks in the United States and Germany require continuous tie replacement, sustaining pressure-treatment demand for heavy-duty wood preservation.
- REACH authorization constraints:European restrictions on creosote alternatives limit substitution options, preserving market share for compliant PAH-based formulations in marine and utility applications.
- Coal tar distillation yield improvements:Advanced fractionation technologies at integrated steelworks are recovering higher-grade creosote fractions suitable for refined marine coating specifications.
Market Restraints
- Feedstock concentration:Coal tar supply depends on coke-oven operations at integrated steel mills, creating vulnerability to blast furnace closures in China and Europe.
- PAH toxicity thresholds:ECHA's restriction proposals on polycyclic aromatic hydrocarbons threaten formulation flexibility for consumer-contact applications.
- Biocide substitution:Copper-based wood preservatives and thermal modification processes are capturing specification share in residential and light commercial construction segments.
Strategic Opportunities
- Indian rail electrification:Indian Railways' track expansion programs create incremental demand for pressure-treated hardwood ties in tropical climate conditions.
- Refined oil marine positioning:Lower-PAH creosote fractions command premium placement in anti-fouling coatings as IMO regulations tighten biocide discharge standards.
- Carbon capture integration:Steel producers deploying CCUS at coke-oven facilities may qualify for EU ETS allowances, offsetting distillation compliance costs.
Industry Challenges
- Specialized chemical handling certification:Pressure-treatment facility operators face extended training timelines for OSHA-compliant PAH exposure protocols.
- Legacy equipment retrofit costs:Timber treatment plants must upgrade emission control systems to meet MEE standards in China and state-level air quality mandates in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Creosote Oil Market |
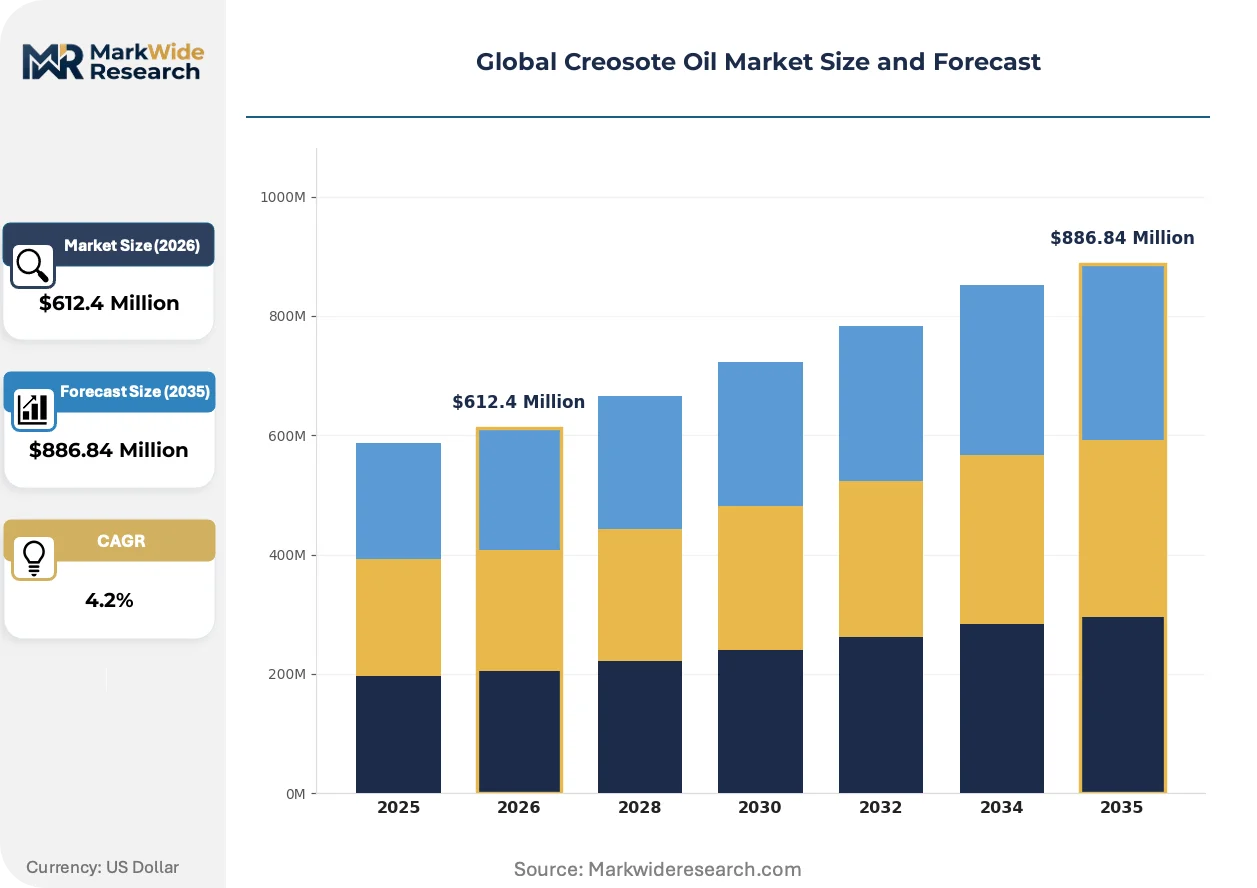
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $886.84 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pine Oil, Coal Tar Oil, Wood Tar Oil, Mixed Oil, Refined Oil Application: Wood Preservation, Marine Anti-fouling, Agricultural Chemicals, Insecticide Production, Industrial Solvents End User: Timber Treatment Facilities, Chemical Manufacturers, Shipyards, Agricultural Farms Packaging Type: Drums, Bulk Containers, Barrels, Intermediate Bulk Containers |
| Companies Covered | Koppers Inc., ArcelorMittal S.A., Mitsubishi Chemical Corporation, Himadri Specialty Chemicals Ltd., JFE Chemical Corporation, RUTGERS Group, KMG Chemicals, Sandvik Materials Technology, Stella-Jones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Creosote Oil Market Shifts & Advancements
Digital process control and regulatory chemistry are converging to transform how creosote oil is fractionated, specified, and applied across heavy infrastructure value chains.
Sensor-based distillation monitoring is digitizing quality control at coal tar processing facilities. Integrated steelworks in Germany and Japan are deploying real-time chromatography to standardize phenolic content across batches. This precision is compressing specification rejection rates for railroad tie treatments and enabling just-in-time delivery to captive treatment plants.
REACH authorization processes are tightening compositional requirements for creosote oil placed on the European market. ECHA's ongoing evaluation of PAH restrictions is forcing formulators to document sourcing chain-of-custody for marine coating applications. Baltic Sea port authorities are now requiring certified low-PAH formulations for dock and pier installations.
Direct procurement relationships between railroad operators and integrated steelworks are displacing traditional chemical distribution channels. Union Pacific and Deutsche Bahn are negotiating long-term offtake agreements with coke-oven byproduct recovery units. This channel compression is most advanced in Germany and the United States, where treatment facility ownership concentrates among infrastructure asset holders.
Global Creosote Oil Market Segmentation
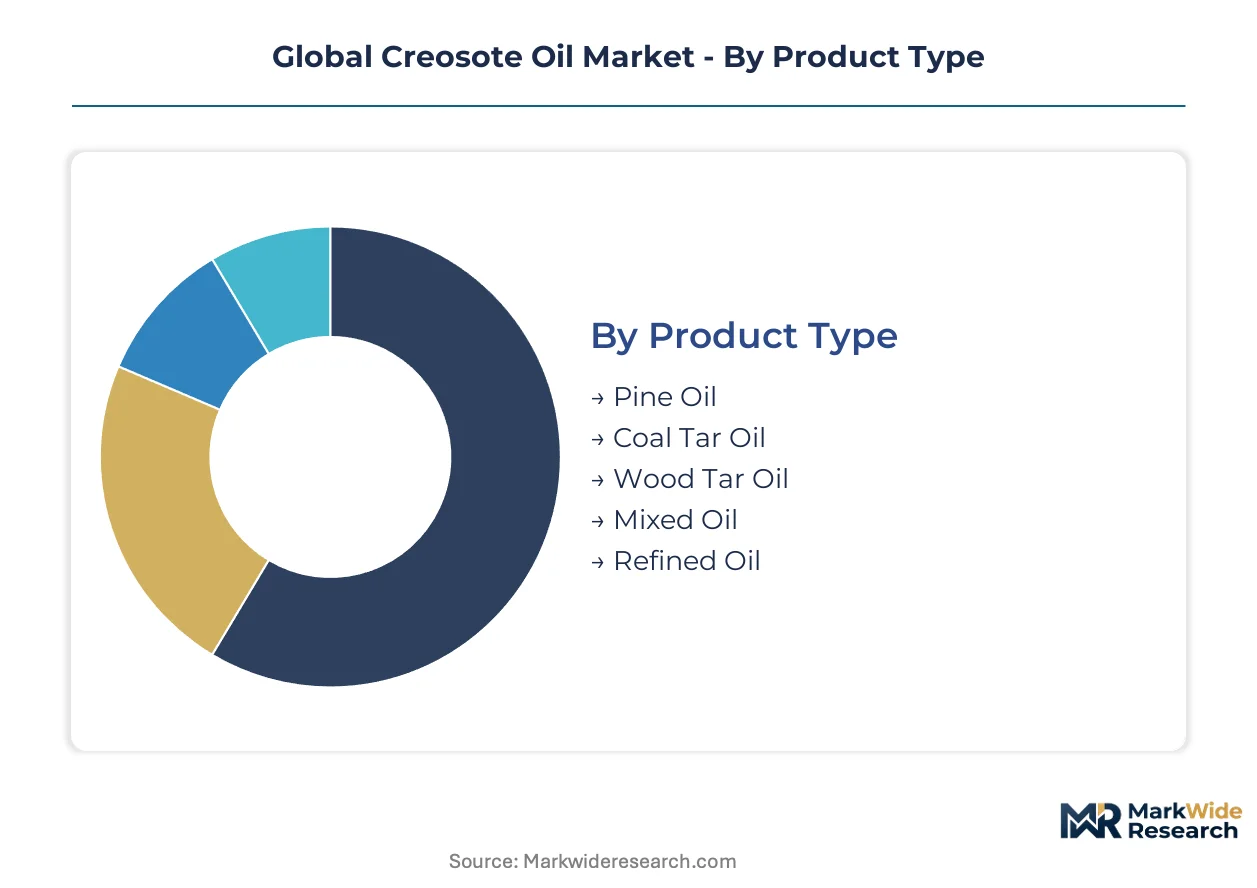
Creosote oil specifications diverge sharply across end-use requirements, from heavy-duty railroad ties demanding high phenolic content to marine coatings requiring refined low-PAH fractions. Segmentation reveals how formulation chemistry, packaging logistics, and customer procurement power reshape competitive positioning within each tier.
Product Type:
Pressure-treatment specifications and marine coating formulators demand distinct chemical profiles across the boiling range and PAH spectrum.
- Coal Tar Oil:Derived from coke-oven byproduct recovery, this fraction carries the heavy polycyclic aromatic hydrocarbon load required by Class A railroad tie specifications in the United States and Germany. Integrated steelworks at ArcelorMittal and Koppers anchor supply through captive distillation, locking in infrastructure maintenance demand.
- Refined Oil:Advanced fractionation strips lower-molecular-weight PAHs to meet Baltic Sea port authority requirements for dock and pier installations. Himadri Specialty Chemicals positions this grade for Asian marine coating formulators facing IMO discharge standard tightening.
- Pine Oil:Turpentine-based alternative with limited creosote replacement penetration in specialty timber applications.
- Wood Tar Oil:Hardwood distillation product serving niche traditional preservation markets in Northern Europe.
- Mixed Oil:Blended formulations optimizing cost-performance for utility pole treatment in cost-sensitive markets.
The dominant share belongs to Coal Tar Oil, while Refined Oil is closing the gap fastest.
Application:
Regulatory authorization constraints and infrastructure replacement cycles concentrate volume in heavy civil applications while opening premium niches elsewhere.
- Wood Preservation:Pressure-impregnation of railroad ties, utility poles, and marine pilings consumes the bulk of creosote oil volume. Union Pacific and Deutsche Bahn long-term offtake agreements with coke-oven operators compress distribution channels and standardize specification requirements across North America and Germany.
- Marine Anti-fouling:Lower-PAH formulations command premium placement as ECHA authorization processes tighten compositional requirements. Baltic and North Sea port authorities now mandate certified chain-of-custody documentation for dock installations.
- Agricultural Chemicals:Legacy organochlorine pesticide phase-outs redirect biocide demand toward creosote-based alternatives in tropical crop protection.
- Insecticide Production:Niche termite and pest control applications facing substitution pressure from synthetic pyrethroids.
- Industrial Solvents:Declining outlet as hydrocarbon solvent regulations tighten across manufacturing jurisdictions.
Wood Preservation holds the volume anchor, though Marine Anti-fouling claims the steepest margin expansion trajectory.
End User:
Procurement scale and captive treatment infrastructure determine pricing power and specification influence across the value chain.
- Timber Treatment Facilities:Captive rail tie preservation plants at Koppers and independent utility pole treaters in the United States drive specification standardization. These operators face extended OSHA training timelines for PAH exposure protocols and emission control retrofit mandates.
- Chemical Manufacturers:Marine coating formulators in Germany and Japan leverage real-time chromatography to batch-standardize phenolic content, compressing rejection rates for just-in-time delivery.
- Shipyards:Korean and Chinese builders specify low-PAH refined fractions for newbuild anti-fouling systems.
- Agricultural Farms:Fragmented demand across tropical plantation operators with limited specification leverage.
Timber Treatment Facilities command the dominant procurement volume, while Chemical Manufacturers are expanding their formulation influence fastest.
Packaging Type:
Logistics economics and handling certification requirements segment the market by shipment scale and geographic reach.
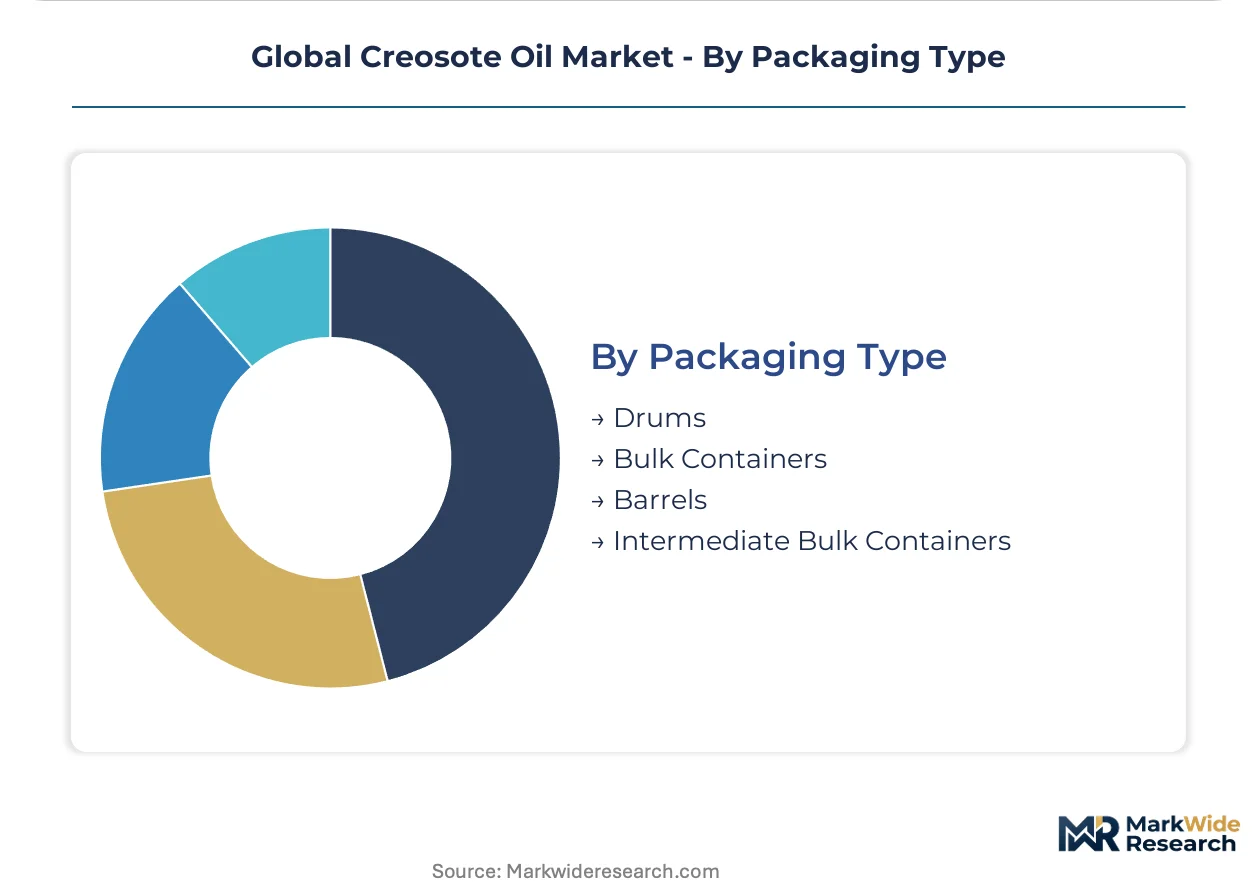
- Bulk Containers:Rail-mounted tank cars and dedicated tanker trucks serve captive treatment plants with continuous offtake agreements. This format dominates North American and German railroad tie preservation networks where Union Pacific and Deutsche Bahn integrate directly with coke-oven recovery units.
- Intermediate Bulk Containers:Flexible logistics for marine coating formulators requiring just-in-time delivery of refined fractions to Baltic and North Sea ports.
- Drums:Standard 200-liter units for agricultural chemical blending and small-batch industrial applications.
- Barrels:Legacy format retaining niche presence in traditional wood preservation markets.
Bulk Containers capture the dominant logistics share, while Intermediate Bulk Containers are gaining traction fastest among marine coating formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration under FIFRA and REACH authorization processes are redrawing competitive access across the three largest national markets. Infrastructure replacement cycles and marine coating specifications concentrate procurement power in specific industrial corridors.
United States
Union Pacific and BNSF Railway drive continuous tie replacement demand across the Midwest and Southern rail networks. EPA wood preservative registrations constrain product entry, locking in incumbent suppliers with established treatment protocols. The Gulf Coast petrochemical corridor anchors coal tar distillation supply for domestic pressure-treatment facilities.
Germany
Deutsche Bahn's infrastructure maintenance programs sustain heavy-duty wood preservation volume through the Rhine-Ruhr industrial belt. ECHA's ongoing PAH restriction evaluations force documentation of supply chain custody for marine applications. Hamburg port authorities now mandate certified low-PAH formulations for dock installations.
China
State-backed rail expansion and utility pole networks absorb coal tar creosote fractions from integrated steelworks. MEE emission controls on distillation facilities reshape regional supply availability, particularly around Tangshan and Baotou steel clusters. Yangtze River Delta marine coating formulators source refined fractions for export-facing shipyards.
India
Indian Railways' track electrification programs generate incremental demand for pressure-treated hardwood ties in tropical conditions. Central Pollution Control Board standards on coal tar processing emissions are tightening around the Kolkata-Haldia industrial hub. Himadri Specialty Chemicals anchors supply from its West Bengal distillation complex.
Japan
JFE Steel's coke-oven byproduct recovery supplies domestic timber treatment networks for coastal infrastructure. METI industrial chemical regulations standardize phenolic content specifications across batches. Chubu region integrated steelworks deploy real-time chromatography to compress rejection rates for just-in-time delivery.
Global Creosote Oil Market Competitive Landscape
On the supply side, the industry is consolidating around integrated steelworks with captive coke-oven byproduct recovery and specialty chemical distributors with fractionation expertise. Two strategic archetypes dominate: steel-integrated producers leveraging blast furnace economics, and independent refiners targeting premium marine coating specifications. Capacity rationalization and direct offtake negotiations with railroad operators constitute the primary competitive moves reshaping channel structures.
Among steel-integrated producers, ArcelorMittal S.A. and JFE Chemical Corporation exemplify the archetype of blast furnace-coupled supply, while Koppers Inc. occupies a position bridging captive treatment infrastructure with North American rail network relationships. Himadri Specialty Chemicals Ltd. represents the independent refiner model anchored to Asian marine coating demand.
| Leading Market Players |
|---|
| Koppers Inc. |
| ArcelorMittal S.A. |
| Mitsubishi Chemical Corporation |
| Himadri Specialty Chemicals Ltd. |
| JFE Chemical Corporation |
| RUTGERS Group |
| KMG Chemicals |
| Sandvik Materials Technology |
| Stella-Jones |
| Others |
Supply & Pricing Matrix
Tangshan and Baotou steel cluster concentration in China anchors global coal tar creosote supply, concentrating margin capture with integrated coke-oven operators while downstream treatment facilities face compressed negotiation leverage on long-term offtake terms.
Pricing Analysis
Three-tier pricing structure across refined low-PAH marine grades, standard railroad tie specifications, and economy blended utility pole formulations dominates transactional dynamics. Price differentiation hinges on ECHA certification tier for Baltic Sea port access and Union Pacific volume scale for Class A tie contracts. Cost compression in standard grades intensifies because Chinese MEE emission controls are contracting distillation capacity. Agricultural chemical blenders exhibit highest price sensitivity; marine coating formulators absorbing premium refined fractions show least elasticity.
Supply Chain Analysis
Tariff exposure between European Union and United Kingdom post-Brexit customs regimes complicates just-in-time delivery scheduling for North Sea marine coating networks. Geographic supply concentration centers on China, Germany, and United States where ArcelorMittal and Koppers operate captive coke-oven recovery. Raw material dependencies encompass metallurgical coal feedstock, phenolic fraction yield rates, and specialized tank car logistics. Single-source vulnerability runs through Tangshan steelworks emission-controlled output. Distribution runs through direct railroad operator offtake agreements displacing traditional chemical distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA FIFRA registration and ECHA REACH authorization processes fragments specification requirements, creating niche formulation opportunities for compliant regional specialists.
For Market Incumbents: Harden captive treatment infrastructure ownership against copper-based wood preservative substitution threatening residential construction specifications. Deepen backward integration into coal tar distillation capacity at German and United States steelworks to secure feedstock priority. Lock Deutsche Bahn and Union Pacific into decade-long offtake structures with price-adjustment clauses tied to phenolic content benchmarking. For New Entrants and Emerging Players: Indian Railways track electrification programs in tropical hardwood preservation represent the most penetrable entry point given limited incumbent treatment facility saturation. Baltic Sea port authority low-PAH certification gaps for dock installations offer second-tier marine coating formulation access. Partner with Himadri Specialty Chemicals for Kolkata-distilled refined fraction tolling arrangements to bypass capital-intensive distillation buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed timber treatment facility roll-ups in United States Midwest rail corridors lacking captive coke-oven supply integration. Five-to-ten year viability hinges on railroad infrastructure replacement cycle durability outpacing composite tie substitution rates. Monitor Indian Central Pollution Control Board emission standard tightening around Kolkata-Haldia hub as inflection indicator for Asian supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coke-Oven Recovery | ArcelorMittal secures coal tar feedstock priority as Chinese MEE controls contract rival distillation capacity. |
| Long-term Supply Agreement with Railroad Operators | Union Pacific direct offtake compresses distribution margin capture by traditional chemical intermediaries. |
| Green Manufacturing Transition to Low-PAH Fractionation | ECHA authorization processes reward Baltic Sea port-compliant refined oil with premium positioning. |
| Joint Venture with Marine Coating Formulators | Hamburg port authority chain-of-custody requirements favor integrated formulation-supply partnerships. |
| Capacity Expansion in Indian Rail Corridor | Indian Railways electrification programs absorb incremental pressure-treatment volume from Kolkata-based supply. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA authorization registries preceded structured interviews with coke-oven plant managers, timber treatment facility operators, marine coating procurement leads, and railroad infrastructure maintenance directors. Bottom-up volume triangulation across coal tar distillation yield rates and top-down value reconciliation against railroad tie replacement cycle data validated segmentation outputs.
Assumptions held fixed include EPA FIFRA registration continuity and REACH authorization scope; variables tested encompass Chinese MEE emission control enforcement intensity and Indian rail electrification program pacing. Modeled dimensions span product type tier, application specification, end-user procurement scale, and regional regulatory cluster. CAGRs derived from segment-level volume build-ups applied to standard price points across the projection horizon. Industry-specific inputs incorporated phenolic content specification evolution and IMO marine biocide discharge standard tightening.
Practitioners should monitor blast furnace closure announcements in Europe and China, ECHA PAH restriction proposal advancement, and Union Pacific capital expenditure disclosures for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Global Wax Market
Oleochemicals
1-Decene Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Global Palm Wax Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Butyl Stearate Market