
 Hexamethylenetetramine (HMTA) Market | 2026-2036
Hexamethylenetetramine (HMTA) Market Size, Share, and Industry Trends Forecast 2026-2036
Hexamethylenetetramine (HMTA) Market Foresight
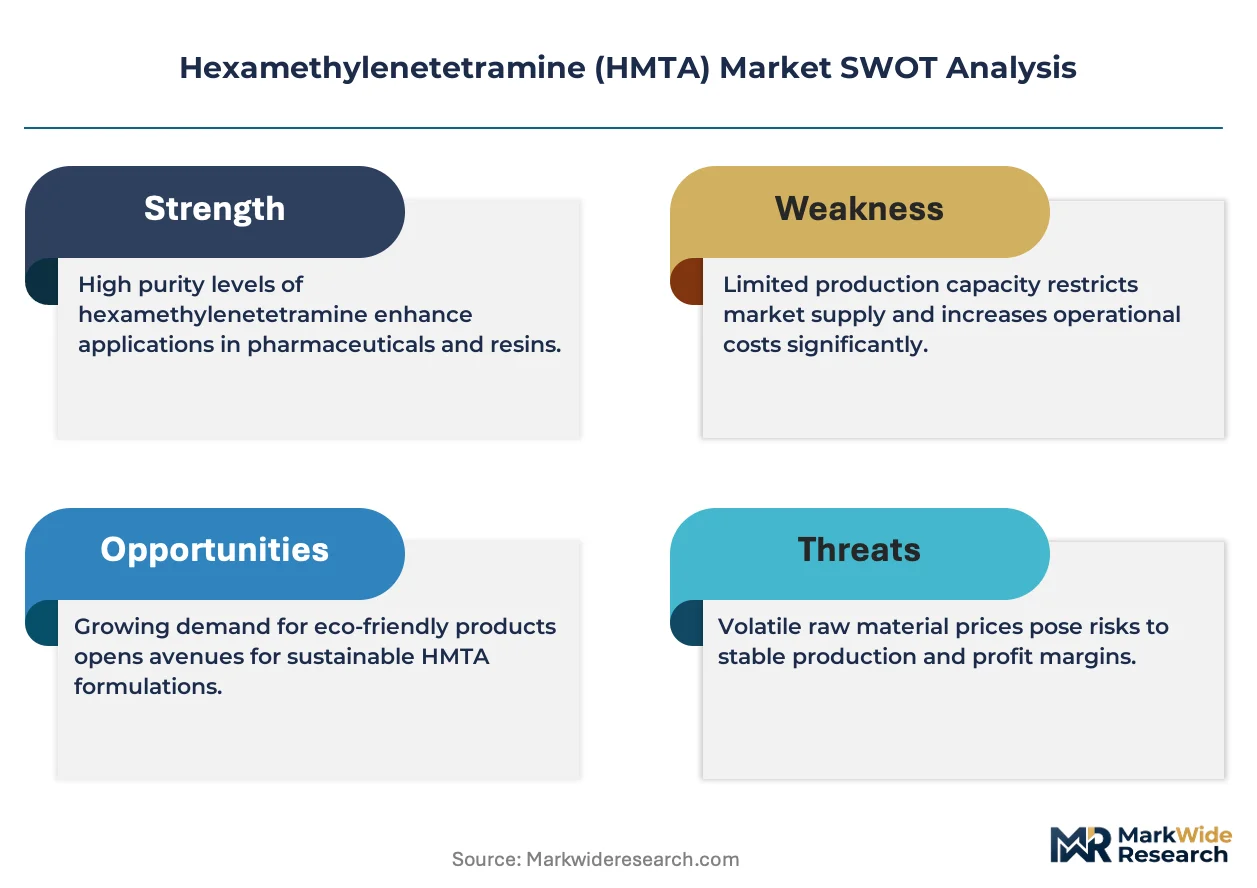
Asset-light leasing models for specialty chemical production facilities is rewriting competitive entry barriers for HMTA manufacturers. Mitsubishi Gas Chemical Company leverages captive methanol supply chains to sustain cost advantages across Asian markets. INEOS Group Holdings S.A. anchors its position through backward integration into formaldehyde feedstock production. Merck KGaA differentiates via pharmaceutical-grade certification that commands premium positioning in regulated end uses.
Hexamethylenetetramine is a heterocyclic organic compound with the formula C₆H₁₂N₄, synthesized via the condensation of formaldehyde and ammonia under controlled pH conditions; it functions primarily as a curing agent for phenolic resins and as a solid fuel component in military and recreational applications. The pharmaceutical formulations segment occupies the highest margin pool, driven by stringent USP-grade requirements that filter out commodity producers. Powder and crystal grades dominate volume throughput, though solution formats are gaining traction in automated adhesive blending operations where dosing precision reduces waste.
EPA oversight of formaldehyde emissions shapes HMTA manufacturing standards in the United States, while REACH registration requirements in Europe restrict non-compliant imports. China's MEE enforces dual carbon goals that pressure coal-based ammonia feedstock pathways. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which purity grades and process certifications will determine market access.
Market Dynamics
Formaldehyde feedstock volatility and ammonia supply chain restructuring are compressing margin structures across HMTA value chains, forcing producers to recalibrate backward integration strategies and regional sourcing footprints.
Growth Catalysts
- Phenolic resin curing demand:Aerospace and automotive composite manufacturers are expanding phenolic matrix consumption for fire-resistant applications, pulling HMTA volumes into high-specification supply tiers.
- REACH registration completion:European ECHA compliance deadlines for formaldehyde derivatives are filtering out unregistered imports, consolidating volume among certified producers.
- China's MEE dual carbon enforcement:Coal-to-chemical capacity controls are accelerating ammonia plant modernization, improving feedstock purity for pharmaceutical-grade HMTA output.
Market Restraints
- Methanol price volatility:Natural gas feedstock swings and shipping rate fluctuations transmit directly into formaldehyde production economics, squeezing HMTA converter margins without forward-contract hedging.
- Feedstock concentration in Shandong and Jiangsu:Domestic Chinese ammonia production clusters expose global buyers to single-province logistics disruptions and environmental shutdown cycles.
- Paraformaldehyde substitution in adhesive curing:Lower-molecular-weight aldehyde donors are displacing HMTA in some wood-panel applications where extended pot life is not required.
Strategic Opportunities
- Indian pharmaceutical excipient expansion:CDSCO's accelerated API manufacturing incentives are creating demand for USP-grade HMTA as tablet disintegrant and urinary acidifier inputs.
- Automated adhesive blending systems:Solution-format HMTA dosing in continuous phenolic resin production is digitizing process control and reducing waste for European automotive Tier-1 suppliers.
- EU Green Deal carbon border adjustments:Embedded emissions accounting for imported chemicals will favor European producers with renewable ammonia pilots and biogenic methanol pathways.
Industry Challenges
- USP-grade certification timelines:FDA drug master file compilation and analytical method validation for pharmaceutical HMTA batches extend commercialization cycles by 18-24 months.
- Legacy phenolic resin plant retrofit costs:Continuous reactor upgrades to handle solution-grade HMTA instead of powder feedstock demand capital deployment that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hexamethylenetetramine (HMTA) Market |
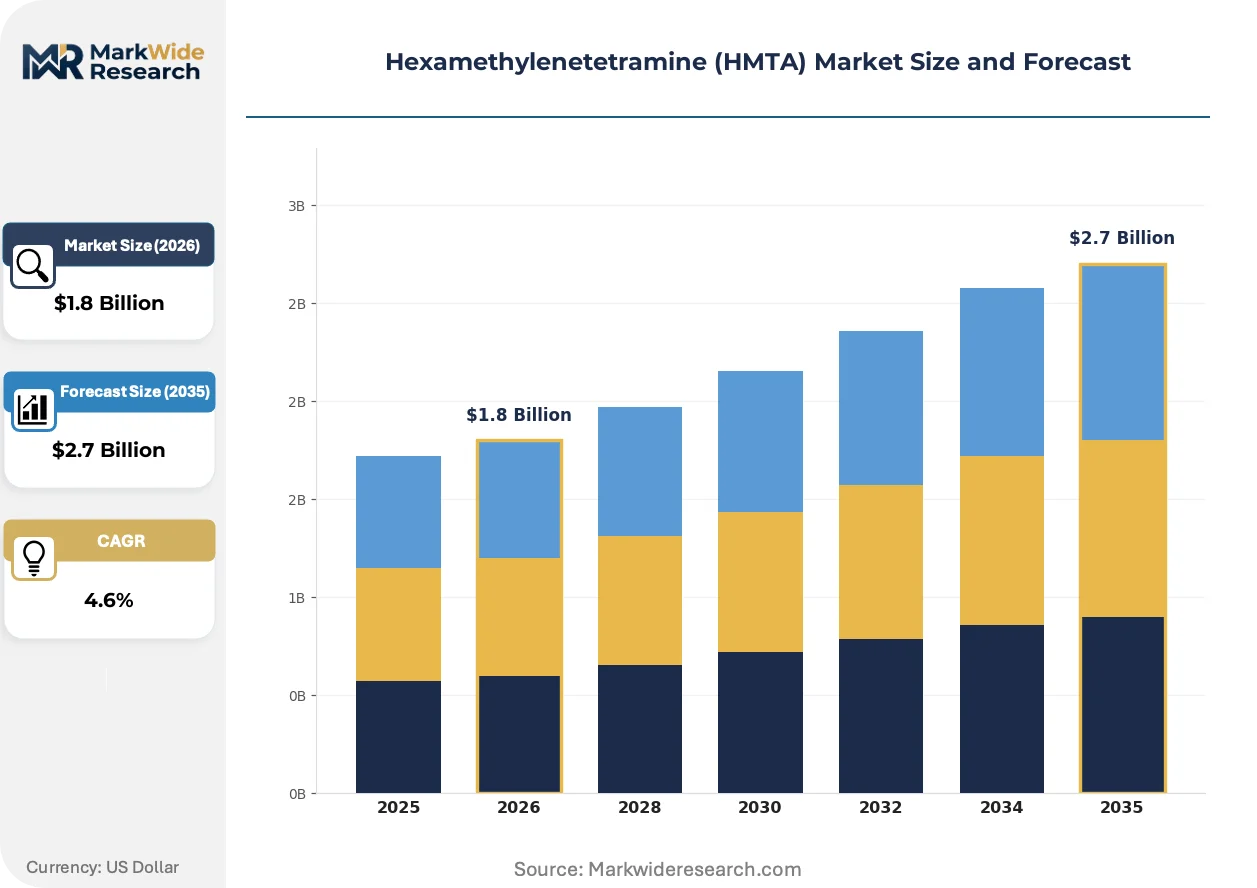
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
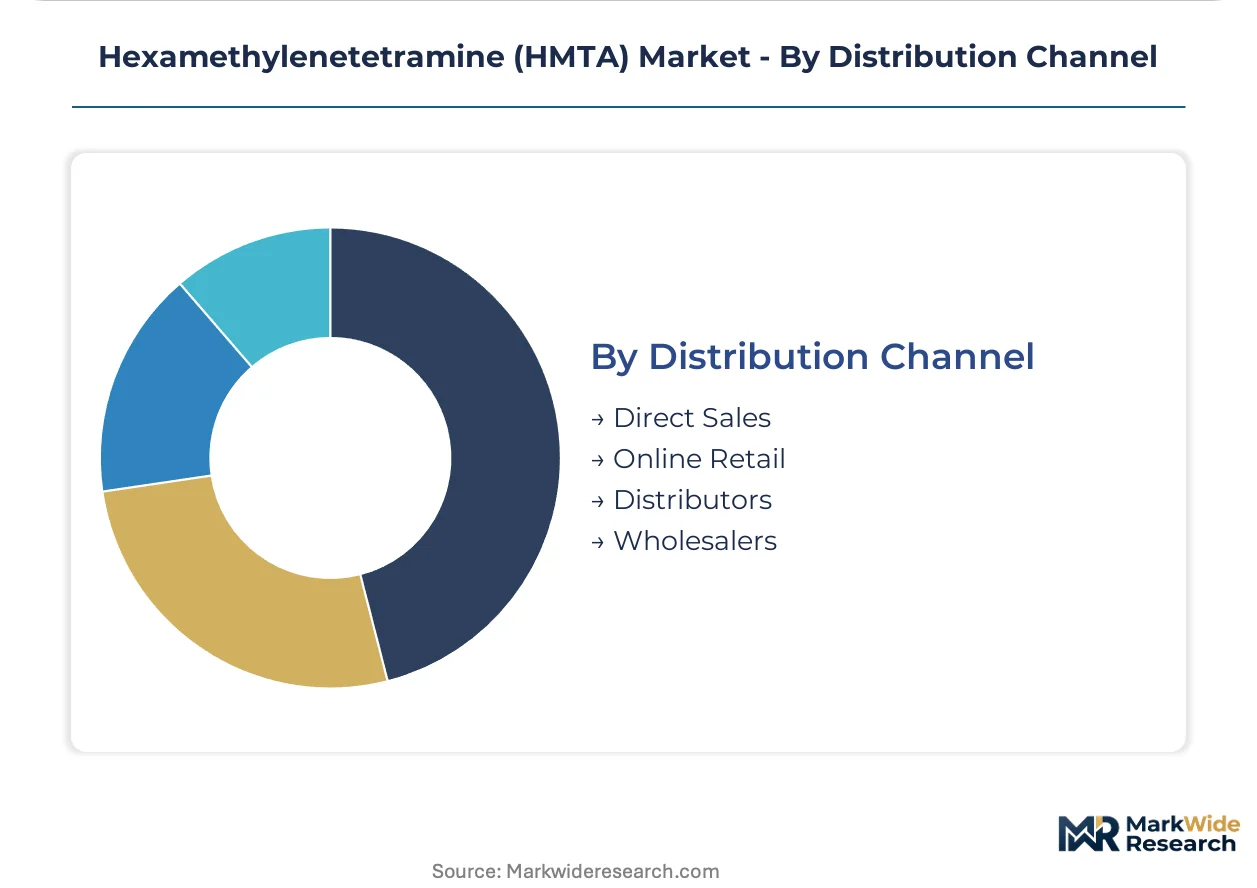
| Segmentation | Product Type: Granules, Crystals, Powder, Solution Application: Medical Uses, Pharmaceutical Formulations, Industrial Adhesives, Fuel Additives End User: Pharmaceutical Companies, Chemical Manufacturers, Research Laboratories, Healthcare Facilities Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Mitsubishi Gas Chemical Company, Merck KGaA, INEOS Group Holdings S.A., SABIC, Alfa Aesar, Hexion Inc., Simalin Chemical Industries Pvt. Ltd., KCI Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hexamethylenetetramine (HMTA) Market Shifts & Advancements
Process analytical technology and closed-loop formaldehyde recovery systems are redefining acceptable purity thresholds and emission profiles across HMTA manufacturing, compressing the gap between commodity and specialty grades.
Inline Raman spectroscopy for real-time condensation monitoring is digitizing batch consistency in formaldehyde-ammonia reactors. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these systems to reduce out-of-specification losses. The technology is digitizing quality assurance workflows, collapsing the time between synthesis completion and certificate-of-analysis release.
REACH Annex XVII restrictions on formaldehyde emissions in consumer goods are tightening residual monomer limits for HMTA destined for European phenolic resin applications. Manufacturers are responding with multi-stage vacuum stripping and catalytic oxidation of off-gases. Wood-panel producers in Poland and Romania face the steepest compliance ramps as they supply IKEA and other retail chains with EU Ecolabel certification requirements.
Specification-driven procurement consolidation is concentrating HMTA purchasing among large adhesive formulators and pharmaceutical CMOs with dedicated supplier audit programs. Smaller regional distributors are losing shelf space to direct mill relationships. The shift is most visible in China's Yangtze River Delta, where Sinopec-affiliated phenolic resin producers are integrating backward into captive HMTA units to secure pharmaceutical-grade supply chains.
Hexamethylenetetramine (HMTA) Market Segmentation
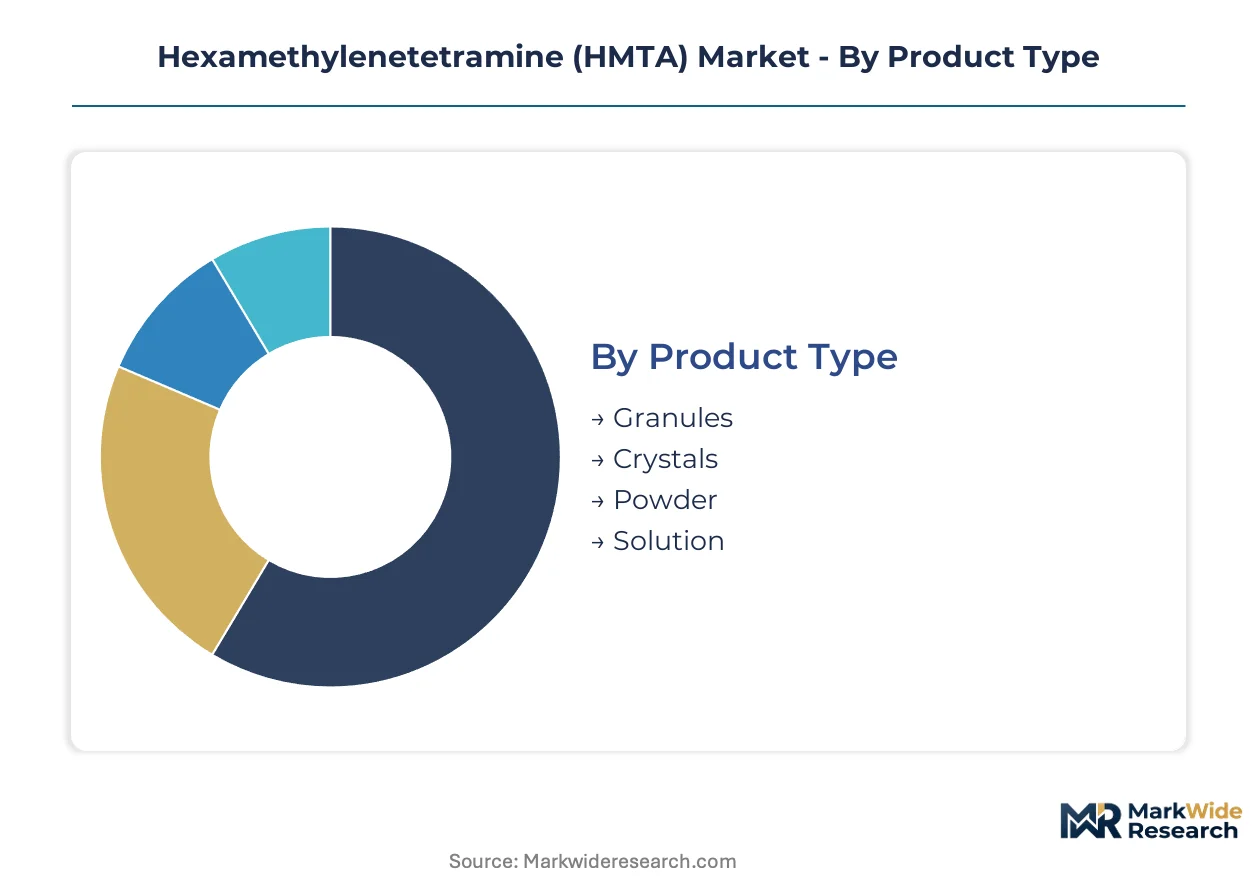
Segmentation in HMTA markets separates commodity-grade converters from pharmaceutical-certified suppliers, with each tier demanding distinct technical service intensity and regulatory documentation. Understanding these divides reveals where margin pools concentrate and which customer relationships require dedicated account engineering.
Product Type:
After-sales service intensity varies sharply across physical forms, with solution grades demanding continuous technical support for automated dosing systems while powder shipments require minimal post-delivery engagement.
- Granules:Low-dust handling characteristics suit bulk phenolic resin production in continuous reactor environments. Aerospace composite manufacturers in Germany specify granule formats for precise metering in automated curing lines where airborne particulate control is mandatory.
- Crystals:High-purity crystalline grades achieve tight particle size distributions required for pharmaceutical tablet disintegrant applications. CDSCO-registered excipient manufacturers in India source crystal grades for urinary acidifier formulations where USP dissolution standards filter out commodity suppliers.
- Powder:Standard industrial grades dominate legacy phenolic resin curing with established handling protocols and minimal technical support requirements.
- Solution:Aqueous formats enable precision dosing in continuous adhesive blending operations, reducing waste and enabling closed-loop process control for automotive Tier-1 suppliers.
By volume, Powder leads. By growth pace, Solution is ahead.
Application:
Cost tier stratification separates pharmaceutical-grade certification premiums from commodity industrial pricing, with regulatory compliance costs creating insurmountable barriers between adjacent segments.
- Medical Uses:Urinary tract antiseptic applications leverage HMTA's formaldehyde-release mechanism for targeted bacterial suppression. Hospital procurement networks in France specify analytical-grade material for sterile irrigation solutions where ANSM pharmacovigilance requirements mandate batch-level traceability.
- Pharmaceutical Formulations:Tablet disintegrant and excipient functions command the highest purity premiums, with FDA drug master file validation extending commercialization timelines. Swiss contract manufacturers adopt inline Raman spectroscopy to collapse quality assurance cycles for certified batches.
- Industrial Adhesives:Phenolic resin curing for wood panel and automotive composite bonding represents the volume anchor, with REACH Annex XVII formaldehyde limits tightening residual monomer specifications for EU-bound shipments.
- Fuel Additives:Solid fuel tablet applications for military and recreational camping sustain steady demand with standardized military specifications and limited purity differentiation.
Industrial Adhesives captures the largest volume share. Pharmaceutical Formulations claims the steepest expansion trajectory as CDSCO and FDA accelerate excipient qualification programs.
End User:
Customer type determines procurement modality, with large chemical manufacturers integrating backward into captive HMTA production while research laboratories rely on specialized distributors for small-lot certified material.
- Pharmaceutical Companies:USP-grade procurement concentrates among CDSCO-registered API manufacturers and FDA-inspected facilities with dedicated supplier audit programs. Direct mill relationships are displacing regional distributors in China's Yangtze River Delta as Sinopec-affiliated producers secure pharmaceutical-grade supply chains.
- Chemical Manufacturers:Phenolic resin and adhesive formulators drive industrial-grade volume, with backward integration into formaldehyde feedstock production anchoring cost positions for integrated players.
- Research Laboratories:Analytical-grade and reagent-tier demand supports specialized distributors with certificate-of-analysis documentation for method validation studies.
- Healthcare Facilities:Direct procurement of medical-grade HMTA for antiseptic formulations operates through hospital purchasing consortia with consolidated supplier panels.
Chemical Manufacturers dominate tonnage. Pharmaceutical Companies are climbing the fastest as excipient outsourcing accelerates.
Distribution Channel:
Supply concentration shapes channel selection, with direct sales capturing pharmaceutical-grade volume while distributors retain relevance in fragmented industrial markets.
- Direct Sales:Pharmaceutical-grade and large-volume industrial contracts bypass intermediaries for dedicated account management and regulatory documentation flow. INEOS and Mitsubishi Gas Chemical anchor European and Asian direct relationships with formaldehyde-integrated supply chains.
- Distributors:Regional chemical distributors retain position in mid-scale phenolic resin and adhesive markets where lot sizes and technical requirements do not justify direct mill contracts.
- Wholesalers:Bulk commodity grades flow through wholesale networks for standard industrial curing applications with minimal specification differentiation.
- Online Retail:Reagent-grade and small-lot specialty formats support research laboratory procurement with digital certificate access and rapid fulfillment.
Direct Sales leads by volume. Online Retail is expanding most quickly in research-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE dual carbon enforcement and India's CDSCO pharmaceutical incentives are redirecting HMTA investment toward pharmaceutical-grade capacity. Germany's REACH Annex XVII implementation and EPA formaldehyde standards in the United States are tightening residual monomer specifications across industrial applications.
China
Shandong and Jiangsu province chemical clusters supply both domestic phenolic resin manufacturers and export markets. MEE coal-to-chemical capacity controls are accelerating ammonia plant modernization, improving feedstock purity for pharmaceutical-grade output. Sinopec-affiliated producers in the Yangtze River Delta are integrating backward into captive HMTA units to secure certified supply chains for tablet excipient customers.
Germany
Aerospace composite manufacturers in Bavaria specify granule-grade HMTA for automated phenolic curing lines with mandatory airborne particulate control. REACH registration deadlines for formaldehyde derivatives filter unregistered imports, consolidating volume among ECHA-certified producers. Wood-panel suppliers in Poland and Romania face steep compliance ramps to meet IKEA's EU Ecolabel certification requirements for bound shipments.
United States
EPA formaldehyde emission standards shape manufacturing protocols for phenolic resin applications across automotive Tier-1 suppliers. FDA drug master file validation extends commercialization timelines for USP-grade material by 18-24 months. Houston-Gulf Coast methanol and ammonia infrastructure anchors formaldehyde-integrated HMTA production for domestic adhesive and pharmaceutical markets.
India
CDSCO accelerated API manufacturing incentives create demand for USP-grade HMTA as tablet disintegrant and urinary acidifier inputs. Gujarat and Maharashtra pharmaceutical clusters source crystal grades where USP dissolution standards filter out commodity suppliers. Domestic chemical manufacturers scale production for both excipient outsourcing contracts and export to regulated markets.
Switzerland
Swissmedic pharmaceutical-grade certification requirements support premium positioning for analytical-grade HMTA in sterile irrigation solutions. Basel-area contract manufacturers adopt inline Raman spectroscopy to collapse quality assurance cycles between synthesis completion and certificate-of-analysis release. ANSM pharmacovigilance requirements in neighboring France drive batch-level traceability specifications across cross-border supply relationships.
Hexamethylenetetramine (HMTA) Market Competitive Landscape
On the supply side, the industry is consolidating around formaldehyde-integrated producers and pharmaceutical-certified specialists. Three archetypes dominate: methanol-captive Asian conglomerates, European REACH-registered chemical majors, and pharmaceutical-grade certification specialists. Competitive moves center on backward integration into ammonia feedstock production and automated solution-format capacity for adhesive blending systems.
Among methanol-captive producers, Mitsubishi Gas Chemical Company exemplifies supply chain control through integrated formaldehyde production. INEOS Group Holdings S.A. anchors European industrial-grade positioning through feedstock integration. Merck KGaA occupies the pharmaceutical-grade tier where USP certification and FDA drug master file validation create insurmountable barriers for commodity converters.
| Leading Market Players |
|---|
| Mitsubishi Gas Chemical Company |
| Merck KGaA |
| INEOS Group Holdings S.A. |
| SABIC |
| Alfa Aesar |
| Hexion Inc. |
| Simalin Chemical Industries Pvt. Ltd. |
| KCI Ltd. |
| BASF SE |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion and container rate volatility transmit directly into HMTA landed costs, amplifying the spread between pharmaceutical-grade premiums and commodity industrial pricing. Formaldehyde feedstock concentration in Shandong and Jiangsu provinces concentrates upstream bargaining power among methanol-captive producers, forcing downstream converters to absorb logistics premiums or cede volume to integrated competitors.
Pricing Analysis
Certification level creates the primary spread, with USP-grade pharmaceutical material commanding substantial premiums over industrial phenolic resin grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by analytical purity, FDA drug master file validation status, and batch-level traceability documentation. Price compression runs through commodity powder grades as paraformaldehyde substitution erodes volume in wood-panel adhesive applications. Pharmaceutical companies exhibit lowest price sensitivity due to regulatory lock-in costs, while mid-scale phenolic resin converters face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Formaldehyde and ammonia feedstock availability anchors supply chain configuration, with production clustering in China, Germany, and the United States. Methanol draws from natural gas and coal-to-chemical pathways; ammonia rests on Haber-Bosch capacity tied to regional energy economics. Single-province concentration risk in Shandong and Jiangsu exposes global buyers to environmental shutdown cycles and logistics disruptions. Distribution runs through direct mill relationships for pharmaceutical-grade volume, while regional chemical distributors retain position in fragmented industrial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for automated solution-grade dosing systems expand faster than commodity powder shipments, creating recurring revenue pools that hardware margins cannot match. After-sales engineering for continuous phenolic resin blending operations commands multi-year attach rates.
For Market Incumbents: Entrench pharmaceutical-grade certification barriers through accelerated FDA drug master file compilation and inline analytical technology deployment. Deepen captive methanol positions in Shandong and Jiangsu to neutralize feedstock volatility exposure. Paraformaldehyde substitution in wood-panel curing threatens volume retention; respond with solution-format capacity for automotive Tier-1 adhesive contracts. For New Entrants and Emerging Players: Pursue Indian pharmaceutical excipient outsourcing as CDSCO accelerates API manufacturing incentives. Gujarat and Maharashtra clusters offer penetrable entry points where USP dissolution standards filter incumbent commodity suppliers. Target solution-grade toll manufacturing for European automated adhesive blending systems, leveraging technical service intensity that commodity distributors cannot replicate. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core HMTA units lacking pharmaceutical-grade certification infrastructure. Five-to-ten-year viability hinges on feedstock integration depth and regulatory compliance moats. Monitor ECHA REACH registration completion rates as consolidation signal; unregistered import filtration will determine which assets capture European volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Mitsubishi Gas Chemical and INEOS anchor cost positions through captive methanol and formaldehyde supply chains. |
| Pharmaceutical-Grade Certification Investment | Merck KGaA commands premium positioning via USP validation and FDA drug master file documentation. |
| Solution-Format Capacity Expansion | Automated dosing systems for European automotive Tier-1 suppliers reduce waste and enable closed-loop process control. |
| Inline Raman Spectroscopy Deployment | Swiss and German contract manufacturers collapse quality assurance cycles between synthesis completion and certificate release. |
| Regional Distribution Consolidation | Direct mill relationships displace regional distributors in China's Yangtze River Delta pharmaceutical supply chains. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with chemical plant managers, pharmaceutical procurement leads, adhesive formulator technical directors, and distribution channel partners; and secondary validation through customs trade data, ECHA REACH registration databases, SEC 10-K filings, and CDSCO excipient approval records. Bottom-up volume triangulation across product grades and end-use applications was cross-checked against top-down market sizing from feedstock consumption patterns and phenolic resin production estimates.
Forecast inputs considered grade tier stratification, end-use industry growth differentials, regional regulatory cluster evolution, and packaging format shifts across the projection horizon. CAGRs were derived from segmented volume modeling and value-per-ton escalation assumptions tied to certification premium trajectories. Key industry-specific inputs included REACH Annex XVII formaldehyde emission limit enforcement timelines and CDSCO pharmaceutical manufacturing incentive program uptake rates.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, shipping rate volatility, or currency movements across Asian export corridors would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and feedstock pathway economics. Cross-checking against ECHA registration completion statistics and CDSCO excipient approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
1, 4 Butanediol Market
Chemicals
Fluorine Derivatives Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Spirodiclofen Market
Chemicals
China Inorganic Iodide Market
Chemicals
Brazil Methanol Market
Chemicals
6 Hexanediol Market
Chemicals
Ferric Chloride Market
Chemicals
Calcium Hydroxide Market
Chemicals
Iso Nonanol Market