
 FRP Grating Market | 2026-2036
FRP Grating Market Size, Share, and Industry Trends Forecast 2026-2036
FRP Grating Market Analysis
The EU Green Deal is pivoting European industrial buyers toward corrosion-resistant infrastructure materials. Strongwell Corporation leverages its pultrusion expertise to dominate North American utility and wastewater applications. Bedford Reinforced Plastics anchors its position through deep manufacturing scale across standard and custom grating profiles. Exel Composites specializes in thermoset profiles for marine and offshore environments where salt degradation destroys conventional steel.
Fiber-reinforced polymer grating consists of glass fiber reinforcement embedded in thermoset resin matrices, typically achieving 30-40% glass content by weight and load ratings exceeding 500 pounds per square foot in industrial grades. Its primary purpose is to replace steel and aluminum in corrosive environments where electrochemical degradation compromises structural integrity over five-to-ten-year service cycles. Molded grating leads volume shipments for chemical processing and marine platforms due to lower tooling costs and bidirectional strength uniformity. Pultruded grating commands premium positioning in architectural and safety-critical installations where unidirectional span capabilities and tighter dimensional tolerances justify higher resin formulation costs.
EMA and ECHA frameworks under REACH and the EU Green Deal shape material compliance, restricting certain styrene emissions in polyester production and pushing vinyl ester and phenolic formulations toward broader adoption. EPA corrosion prevention standards and OSHA walkway safety regulations in the United States reinforce specification requirements for slip-resistant, fire-retardant industrial flooring. Stakeholders must monitor how evolving carbon border adjustment mechanisms and resin feedstock volatility reshape total cost of ownership calculations against traditional metallic alternatives.
Market Dynamics
Corrosion-driven asset replacement cycles are compressing specification timelines across chemical processing, offshore energy, and wastewater infrastructure. Buyers now prioritize total lifecycle cost over first-cost procurement, forcing resin formulation upgrades and accelerated certification testing.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:The framework accelerates steel substitution in Rhine corridor chemical plants. Vinyl ester and phenolic formulations gain preference under tightened styrene emission limits.
- Offshore platform walkway refurbishment:North Sea and Gulf of Mexico operators expand FRP procurement for salt-resistant elevated decking. Salt degradation destroys conventional steel within five-year service windows.
- Pultrusion automation advances:Continuous fiber alignment technology reduces dimensional tolerance variation. Architectural and safety-critical installations specify pultruded profiles for unidirectional span reliability.
Market Restraints
- Resin feedstock price volatility:Styrene and vinyl ester monomer costs fluctuate with crude oil derivatives. Formulation cost uncertainty compresses margin visibility for multi-year infrastructure contracts.
- Specialized mold tooling concentration:High-performance grating dies concentrate among German and Chinese precision manufacturers. Tooling lead times extend specification cycles for custom load-rated profiles.
- Thermoplastic composite substitution:Long-fiber reinforced thermoplastics penetrate light-duty industrial flooring. Lower scrap rates and recyclability attract sustainability-focused buyers in packaging and logistics.
Strategic Opportunities
- US inland waterway lock rehabilitation:Army Corps of Engineers specifications favor corrosion-resistant materials for submerged gate walkways. FRP grating penetrates steel-dominated federal infrastructure procurement.
- Green hydrogen electrolyzer facility construction:Alkaline and PEM cell housings require chemically resistant elevated platforms. German and Dutch project developers specify phenolic formulations for caustic vapor exposure.
- Direct-to-fabricator digital channels:Configurator platforms bypass traditional distributor markups for standard molded profiles. US municipal wastewater authorities leverage e-procurement for maintenance grating.
Industry Challenges
- Pultrusion operator skill scarcity:Die temperature control and fiber tension calibration require specialized technicians. Workforce gaps constrain capacity expansion at mid-scale manufacturers.
- Fire certification timeline compression:ASTM E-84 and UL 94 testing protocols extend product qualification cycles. Accelerated project schedules force parallel certification and production ramp-up.
- Legacy steel specification inertia:Structural engineers default to familiar metallic load tables. FRP suppliers invest in design software integration to automate composite-specific calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FRP Grating Market |
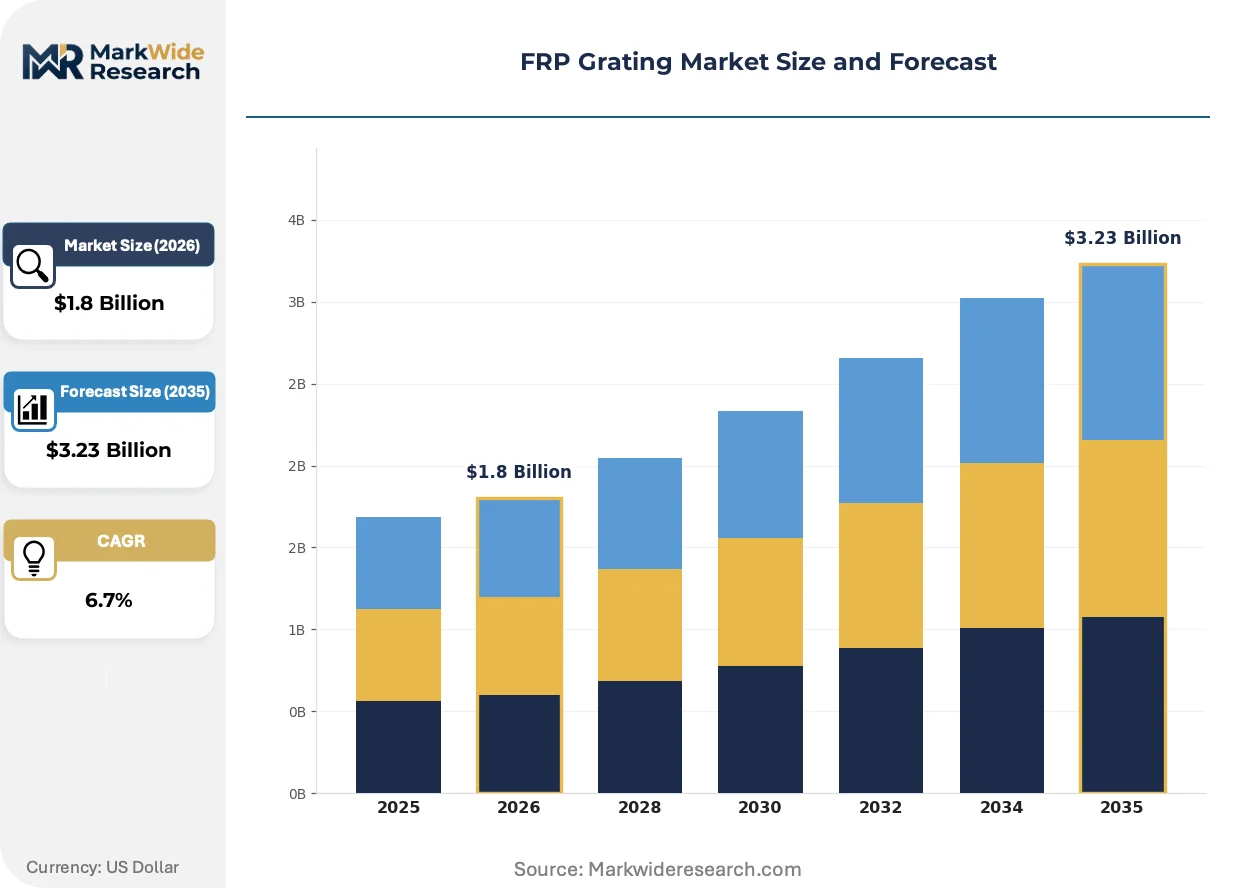
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pultruded Grating, Molded Grating, Architectural Grating, Safety Grating End User: Aerospace, Marine, Chemicals, Food Processing Application: Walkways, Platforms, Trench Covers, Stairs Material: Polyester, Vinyl Ester, Epoxy, Phenolic |
| Companies Covered | Strongwell Corporation, Fibergrate Composite Structures Inc, Bedford Reinforced Plastics, Meiser GmbH, Exel Composites, Ferrotech International FZE, Techno-Composites Domine GmbH, AGC Matex Co Ltd, Fibrolux GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FRP Grating Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are rewriting formulation priorities. Manufacturers now compete on validated service life data rather than commodity pricing.
Phenolic resin systems with enhanced fire-retardant properties are absorbing specification share from standard polyester in enclosed industrial environments. Offshore platform operators and tunnel infrastructure engineers specify phenolic formulations for low smoke toxicity under IMO and NFPA protocols. The technology is absorbing premium positioning in safety-critical applications where evacuation visibility determines regulatory approval.
REACH Annex XVII restrictions on styrene emissions are forcing reformulation across European polyester production. ECHA enforcement is elevating vinyl ester and epoxy vinyl ester resin adoption despite 15-25% raw material cost premiums. German chemical processing buyers now require full material disclosure documentation for imported grating, shifting procurement toward EU-based pultruders with verified supply chain transparency.
Asset owner engineering teams are consolidating specifications around ISO 14122 machinery safety standards for permanent means of access. Oil majors and chemical conglomerates now mandate third-party witnessed load testing for all elevated walkway materials. This certification-driven preference shift concentrates procurement among manufacturers with captive testing laboratories, compressing vendor qualification lists in Norwegian and US Gulf Coast project markets.
FRP Grating Market Segmentation
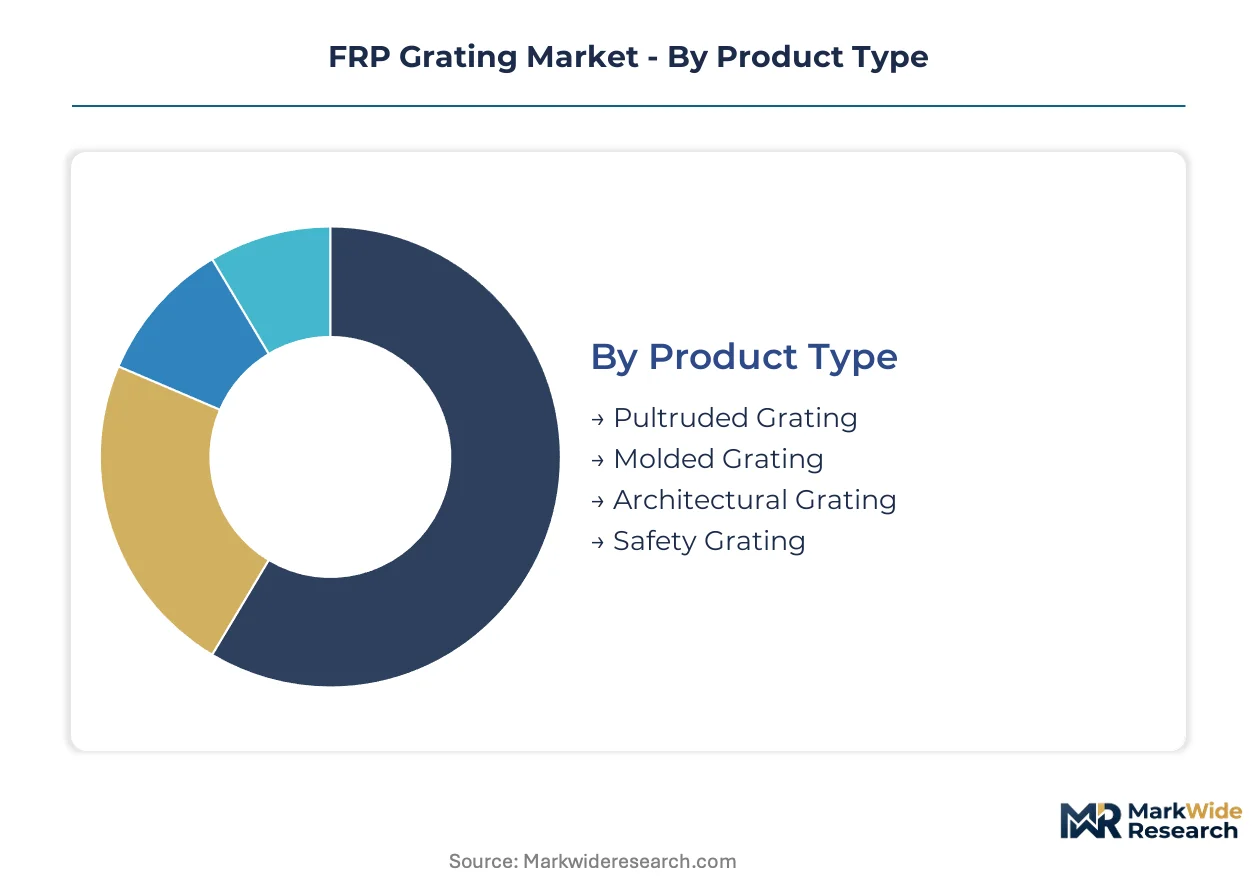
FRP grating procurement decisions pivot on corrosion exposure severity, load-bearing requirements, and fire safety mandates. Specification engineers match resin chemistry and manufacturing process to asset lifecycle cost targets across chemical plants, offshore platforms, and food processing facilities.
Product Type:
Standardization dominates high-volume molded production while pultrusion serves architectural and span-critical customization needs.
- Pultruded Grating:Continuous glass fiber alignment through heated dies produces unidirectional strength profiles with tight dimensional tolerances. German chemical processors specify pultruded walkways for Rhine corridor facilities under EU Green Deal corrosion mandates. Premium positioning reflects resin formulation costs and automation investment.
- Molded Grating:Interwoven glass rovings in heated molds create bidirectional strength uniformity at lower tooling costs. Marine platform operators in the North Sea favor molded decking for salt-resistant elevated surfaces requiring rapid procurement turnaround.
- Architectural Grating:Custom color matching and surface finishes serve aesthetic-driven commercial installations. Municipal wastewater authorities in the Netherlands specify architectural profiles for publicly visible treatment infrastructure.
- Safety Grating:Aggressive slip-resistant surfaces and high-visibility edges target OSHA-compliant industrial flooring. Food processing facilities in Belgium require safety grating for wet washdown environments.
Most installed capacity flows through Molded Grating. Expansion is steepest in Pultruded Grating.
End User:
Corrosion severity and regulatory exposure intensity determine vertical prioritization across buyer categories.
- Chemicals:Caustic vapor exposure and spill containment drive specification of vinyl ester and phenolic formulations. German processors along the Rhine corridor anchor European demand under REACH styrene emission restrictions.
- Marine:Salt spray degradation destroys conventional steel within five-year service windows. North Sea and Gulf of Mexico platform operators mandate FRP for elevated walkway refurbishment cycles.
- Aerospace:Lightweight maintenance platforms and chemical-resistant hangar flooring serve MRO facilities. French aerospace clusters specify phenolic formulations for low smoke toxicity in enclosed environments.
- Food Processing:USDA and EFSA hygiene mandates require corrosion-resistant, cleanable elevated surfaces. Belgian and Dutch dairy processors favor molded grating for washdown-resistant drainage platforms.
Volume concentrates in Chemicals end users. Aerospace climbs fastest on fire certification upgrades.
Application:
Load distribution patterns and traffic frequency shape product selection across structural use cases.
- Walkways:Elevated personnel access routes demand slip-resistant surfaces and span-rated load capacity. Offshore operators specify phenolic walkways under IMO fire safety protocols for platform evacuation routes.
- Platforms:Equipment support surfaces require uniform load distribution and chemical spill containment. German electrolyzer facilities specify platforms for green hydrogen production under EU industrial decarbonization timelines.
- Trench Covers:Removable access panels for underground utilities prioritize weight reduction and corrosion immunity. US Army Corps of Engineers specifies trench covers for inland waterway lock rehabilitation.
- Stairs:Vertical access systems integrate nosings and handrail anchorage points. Dutch tunnel infrastructure engineers mandate phenolic stair systems under NFPA low smoke toxicity requirements.
Platform installations absorb the largest share. Stair applications gain share fastest on tunnel construction activity.
Material:
Resin chemistry selection balances raw material cost against fire performance and chemical resistance specifications.
- Vinyl Ester:Superior chemical resistance and hydrolytic stability justify 15-25% cost premiums over standard polyester. German chemical processors specify vinyl ester for caustic exposure under ECHA enforcement timelines.
- Phenolic:Low smoke toxicity and fire retardancy command premium positioning in safety-critical enclosed environments. Offshore platform operators specify phenolic formulations under IMO and NFPA evacuation visibility standards.
- Polyester:General-purpose corrosion resistance serves cost-sensitive industrial flooring applications. REACH Annex XVII styrene emission restrictions are compressing polyester specification share in European markets.
- Epoxy:Exceptional adhesive properties and dimensional stability serve specialized structural bonding applications. Belgian composite fabricators specify epoxy for custom architectural installations requiring tight tolerance adherence.
Polyester retains the largest installed base. Phenolic expands most quickly on fire safety mandate tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FRP grating production scaled first in German chemical corridors during the 1970s, then dispersed to US Gulf Coast petrochemical hubs and Japanese industrial zones as corrosion engineering matured.
United States
Army Corps of Engineers lock rehabilitation projects drive procurement for submerged walkway systems. EPA corrosion prevention standards and OSHA walkway safety regulations reinforce federal specification requirements. Gulf Coast petrochemical clusters in Texas and Louisiana anchor demand for salt-resistant elevated decking.
Germany
Rhine corridor chemical processors expand vinyl ester and phenolic formulation procurement under tightened emission limits. ECHA enforcement of REACH Annex XVII styrene restrictions accelerates resin chemistry transitions. North Rhine-Westphalia's industrial belt concentrates specification engineering for electrolyzer facility platforms.
China
Coastal refinery expansion and port infrastructure modernization absorb molded grating volumes for corrosion-resistant access systems. MIIT industrial material standards and GB construction codes shape product certification requirements. Yangtze River Delta chemical parks specify FRP for caustic vapor exposure environments.
Netherlands
Rotterdam port authority maintenance cycles and tunnel infrastructure upgrades sustain safety grating demand for low smoke toxicity applications. EU Green Deal industrial decarbonization timelines compress steel substitution procurement decisions. Randstad metropolitan wastewater treatment facilities specify architectural profiles for publicly visible infrastructure.
United Arab Emirates
Offshore platform refurbishment in Arabian Gulf fields drives salt-resistant walkway replacement cycles. Local content requirements and federal infrastructure procurement codes influence vendor qualification processes. Dubai industrial free zones concentrate distribution logistics for Middle East project markets.
FRP Grating Market Vendor Landscape
Premium-margin players sit above commodity-margin players across resin formulation complexity and certification depth. The vendor base separates into three functional tiers: captive pultruders with in-house testing laboratories, regional molders serving standard industrial grades, and specialized fabricators for architectural custom work. Two dominant competitive moves shape positioning: backward integration into resin compounding to secure formulation control, and captive testing laboratory investment to compress fire certification timelines.
Among German-based fabricators, Meiser GmbH and Techno-Composites Domine GmbH occupy positions within the precision-molding tier, while Exel Composites represents the specialist archetype for thermoset profile engineering. Strongwell Corporation anchors the North American premium-positioned segment. These named entities exemplify how geographic concentration near petrochemical demand clusters reinforces supply chain proximity advantages.
| Leading Market Players |
|---|
| Strongwell Corporation |
| Fibergrate Composite Structures Inc |
| Bedford Reinforced Plastics |
| Meiser GmbH |
| Exel Composites |
| Ferrotech International FZE |
| Techno-Composites Domine GmbH |
| AGC Matex Co Ltd |
| Fibrolux GmbH |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between phenolic fire-rated systems and standard polyester grating manifests in parallel supply chain configurations. German and Dutch chemical processors absorb 15-25% resin cost premiums for vinyl ester formulations under ECHA enforcement timelines, while commodity buyers in municipal wastewater procurement drive molded grating toward distributor-heavy fulfillment models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs FRP grating procurement. Fire certification grade and resin chemistry formulation serve as the primary price differentiation drivers, with phenolic systems commanding substantial premiums over polyester alternatives. Cost compression in standard polyester grades is intensifying because REACH Annex XVII styrene emission restrictions are compressing specification share. Municipal wastewater authorities exhibit highest price sensitivity, while offshore platform operators under IMO safety mandates demonstrate lowest sensitivity.
Supply Chain Analysis
Direct-to-fabricator digital channels handle standard molded profile demand from US municipal authorities. Manufacturing concentration rests in Germany, China, and the United States, with precision mold tooling concentrated among German and Chinese suppliers. Styrene and vinyl ester monomer costs fluctuate with crude oil derivatives, creating raw material price volatility. Single-source vulnerability in high-performance grating dies extends tooling lead times for custom load-rated profiles. Distribution runs through regional molders for commodity grades and captive pultruders for premium architectural specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FRP grating market functions as a stable compounder anchored by corrosion-driven asset replacement cycles across chemical processing and offshore energy infrastructure. Infrastructure lifecycle cost accounting now favors fiber-reinforced polymer alternatives over conventional steel in salt-exposed environments.
For Market Incumbents: Deploy captive testing laboratory investment to compress ASTM E-84 and UL 94 fire certification timelines. Strongwell Corporation and Exel Composites exemplify this lever through in-house load testing capabilities that consolidate procurement among oil majors. Backward integration into resin compounding secures formulation control against styrene feedstock volatility. Defensive positioning must address long-fiber reinforced thermoplastics penetrating light-duty industrial flooring segments. For New Entrants and Emerging Players: Begin with green hydrogen electrolyzer facility construction in North Rhine-Westphalia and Dutch port zones, where phenolic platform specifications are accelerating under EU industrial decarbonization timelines. US inland waterway lock rehabilitation offers penetrable federal infrastructure procurement previously dominated by steel. A direct-to-fabricator digital configurator platform bypasses traditional distributor markups for standard molded profiles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale pultruders possessing die temperature control expertise and fiber tension calibration capabilities. Workforce skill scarcity constrains capacity expansion, creating acquisition opportunities for technically proficient operators. Long-term viability frames around validated service life data competition rather than commodity pricing. The signal to watch is Army Corps of Engineers specification shifts for corrosion-resistant materials in submerged gate walkways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Formulation control secures margin stability against styrene monomer cost volatility from crude derivatives. |
| Captive Testing Laboratory Investment | In-house ASTM E-84 and UL 94 certification compresses qualification timelines for oil major procurement. |
| Direct-to-Fabricator Digital Channel Launch | Configurator platforms bypass distributor markups for US municipal wastewater authority maintenance grating. |
| Phenolic Resin Formulation Scale-Up | Low smoke toxicity systems absorb premium positioning under IMO and NFPA evacuation visibility mandates. |
| Pultrusion Automation Technology Deployment | Continuous fiber alignment reduces dimensional tolerance variation for architectural span-critical installations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged plant managers at Rhine corridor chemical processors, procurement leads at North Sea offshore operators, distribution channel partners serving municipal wastewater authorities, and technical R&D directors at pultrusion specialists. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed composites manufacturers, and ECHA REACH registration databases. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level outputs.
Comparable-period anchoring linked projection assumptions to historical replacement cycle data across chemical processing, offshore energy, and wastewater infrastructure. The analytical framework segmented by resin chemistry, manufacturing process, end-use vertical, and regional regulatory cluster across the analysis window. CAGRs were derived from asset lifecycle cost transition curves and corrosion-driven specification shifts. Forecast inputs included electrolyzer facility construction pipelines, Army Corps lock rehabilitation schedules, and ECHA enforcement timeline acceleration.
Several conditions sit outside the modeled scope, including abrupt resin feedstock price shocks, unilateral tariff impositions on Chinese molded grating, and breakthrough thermoplastic composite technologies displacing thermoset applications. Forecasts reflect assumptions about steady EU Green Deal implementation and continued OSHA walkway safety regulatory enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Medical Composite Material Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Hybrid Composites Market
Composite Materials
Reinforced Plastics Market
Composite Materials
Transportation Composites Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Graphene Composites Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market