
 Reinforced Nonwoven Plastics Market | 2026-2036
Reinforced Nonwoven Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforced Nonwoven Plastics Market Intelligence
Consolidation among Tier-1 automotive suppliers and large-scale construction firms is repositioning the supplier-buyer dynamic. Freudenberg Group leverages its extensive R&D in polymer science to serve specialized industrial applications. Johns Manville competes on the basis of its strong distribution network in North America, particularly for construction materials. Meanwhile, Ahlstrom-Munksjö specializes in filtration and packaging media, targeting high-margin segments.
Reinforced nonwoven plastics are engineered fabrics created by bonding or interlocking fibers, strengthened with additional materials like glass or carbon fibers. Their primary purpose is to provide high tensile strength, durability, and dimensional stability in applications where traditional textiles or plastics are insufficient. Polypropylene-based products command a significant share due to their cost-effectiveness and chemical resistance, especially in consumer goods. The automotive and construction end-use sectors drive development, with geotextiles and insulation applications representing key areas of technical innovation.
Material composition and end-of-life management are governed by frameworks such as the EU's REACH regulation and directives from the US Environmental Protection Agency (EPA). Additionally, ISO standards for material testing and performance verification dictate market access and product specifications for geotextiles and automotive components. Future competitiveness depends on developing circular economy-compliant materials without compromising structural performance.
Market Dynamics
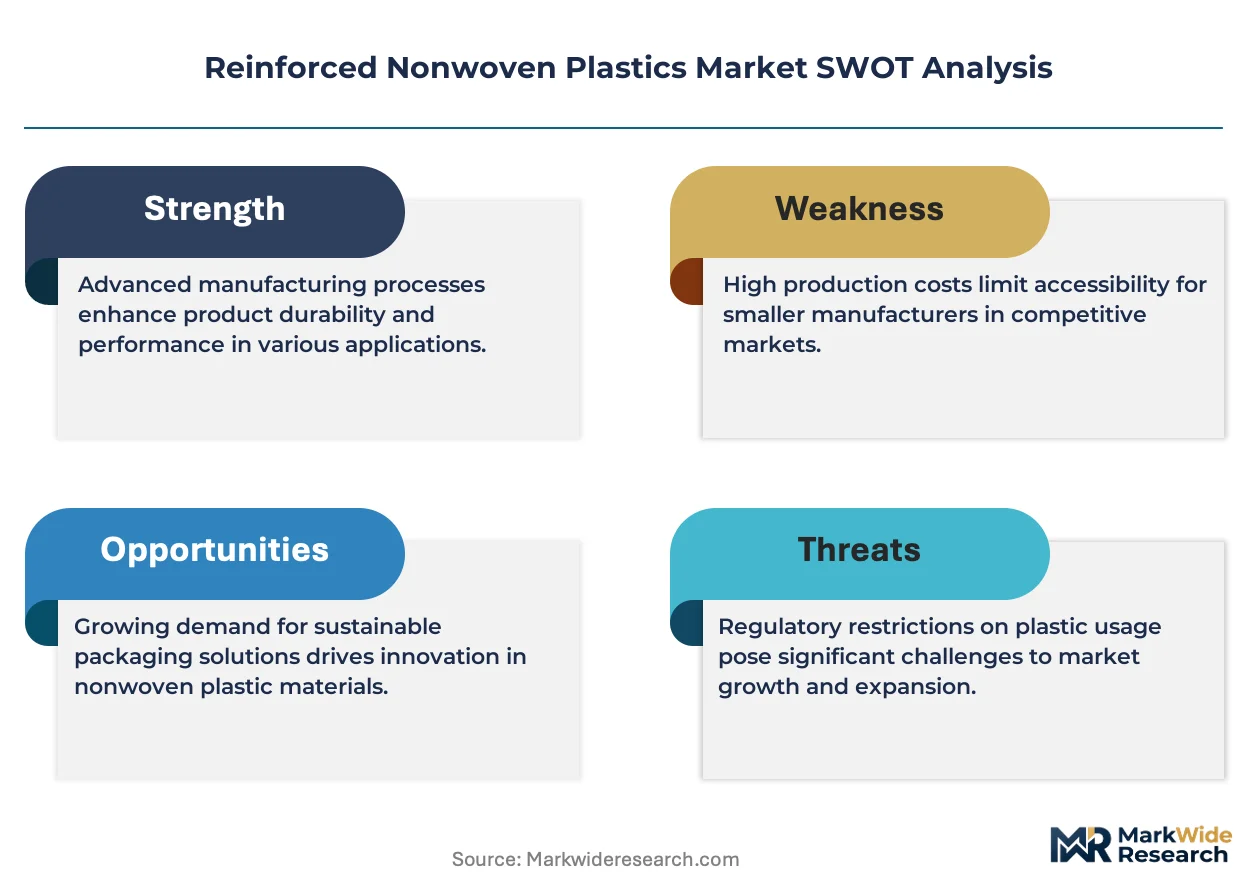
The central force shaping the market is the dual pressure to enhance material performance for demanding applications while complying with circular economy mandates. This requires innovation in both polymer science and end-of-life processing technologies.
Growth Catalysts
- EU Green Deal:Mandates for recycled content and reduced carbon footprints in construction and automotive sectors accelerate adoption of sustainable nonwoven solutions.
- Web Formation Technology:Advances in hydroentanglement and thermal bonding create materials with superior strength-to-weight ratios, expanding use in aerospace and performance apparel.
- Infrastructure Investment:Civil engineering projects in economies like India and Brazil stimulate demand for high-performance geotextiles for soil stabilization and drainage.
Market Restraints
- Input Cost Volatility:Price fluctuations in raw materials like polypropylene and reinforcements like carbon fiber create margin pressure for manufacturers.
- Recycling Complexity:The composite nature of reinforced nonwovens makes material separation for recycling technically difficult and often economically unviable.
- Threat of Substitution:High-strength metal alloys and advanced thermoplastics present a performance alternative in certain structural automotive and industrial components.
Strategic Opportunities
- Electric Vehicle Components:The shift to EVs creates applications in battery separators, thermal insulation, and lightweight structural parts.
- Smart Textiles:Integrating micro-sensors into nonwoven fabrics opens opportunities for structural health monitoring in infrastructure and composite aircraft.
- Bio-Based Polymers:Developing nonwovens from polylactic acid (PLA) and natural fibers meets demand for materials compliant with EPA sustainability goals.
Industry Challenges
- Standardization Gaps:A lack of harmonized ISO standards for testing the recyclability of composite nonwovens creates barriers to international trade and material specification.
- High Capital Investment:Acquiring and maintaining advanced manufacturing lines for web formation requires significant capital, limiting market entry.
- Specialized Talent Scarcity:A shortage of material scientists with expertise in polymer composites constrains R&D and operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforced Nonwoven Plastics Market |
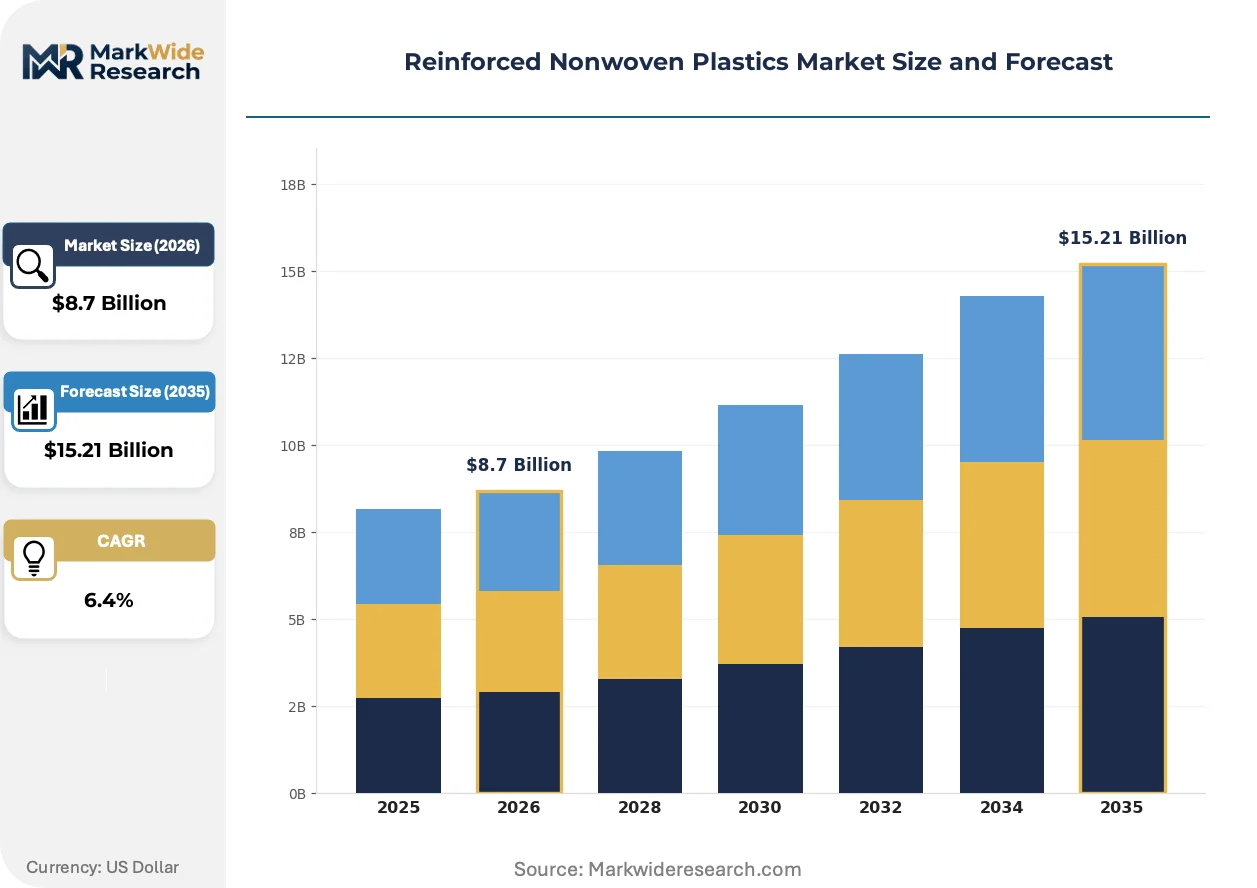
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Nylon, Others End Use Industry: Automotive, Construction, Healthcare, Consumer Goods Manufacturing Stage: Material Preparation, Web Formation, Consolidation, Finishing Application: Geotextiles, Filters, Insulation, Packaging |
| Companies Covered | Kimberly-Clark Corporation, Johns Manville, Berry Global, Suominen Corporation, Toray Industries, Freudenberg Group, Ahlstrom-Munksjö, Fibertex Nonwovens, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforced Nonwoven Plastics Market Strategic Shifts & Innovations
Material science advancements are converging with digital manufacturing to meet sustainability requirements. The evolution of reinforced nonwovens is now linked to data-driven production and lifecycle management, moving beyond simple substitution.
AI-driven process control is a critical innovation in web formation. This technology uses machine learning to optimize fiber orientation and density in real time. Automotive and medical device manufacturers adopt it to meet stringent quality standards. This granular control is rewriting the benchmarks for material performance in safety-critical applications.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory force. It compels companies to provide audited disclosures on the environmental impact of their products, including sourcing and end-of-life pathways. This affects construction and automotive suppliers, who now integrate lifecycle assessment data into product development.
Buyers in large-scale infrastructure are moving from transactional purchases to integrated solutions. They now seek performance guarantees for geotextiles and erosion control systems. This model disrupts traditional distribution, favoring suppliers that provide engineering support and monitoring. The shift is most pronounced in North American and European public works.
Reinforced Nonwoven Plastics Market Segmentation
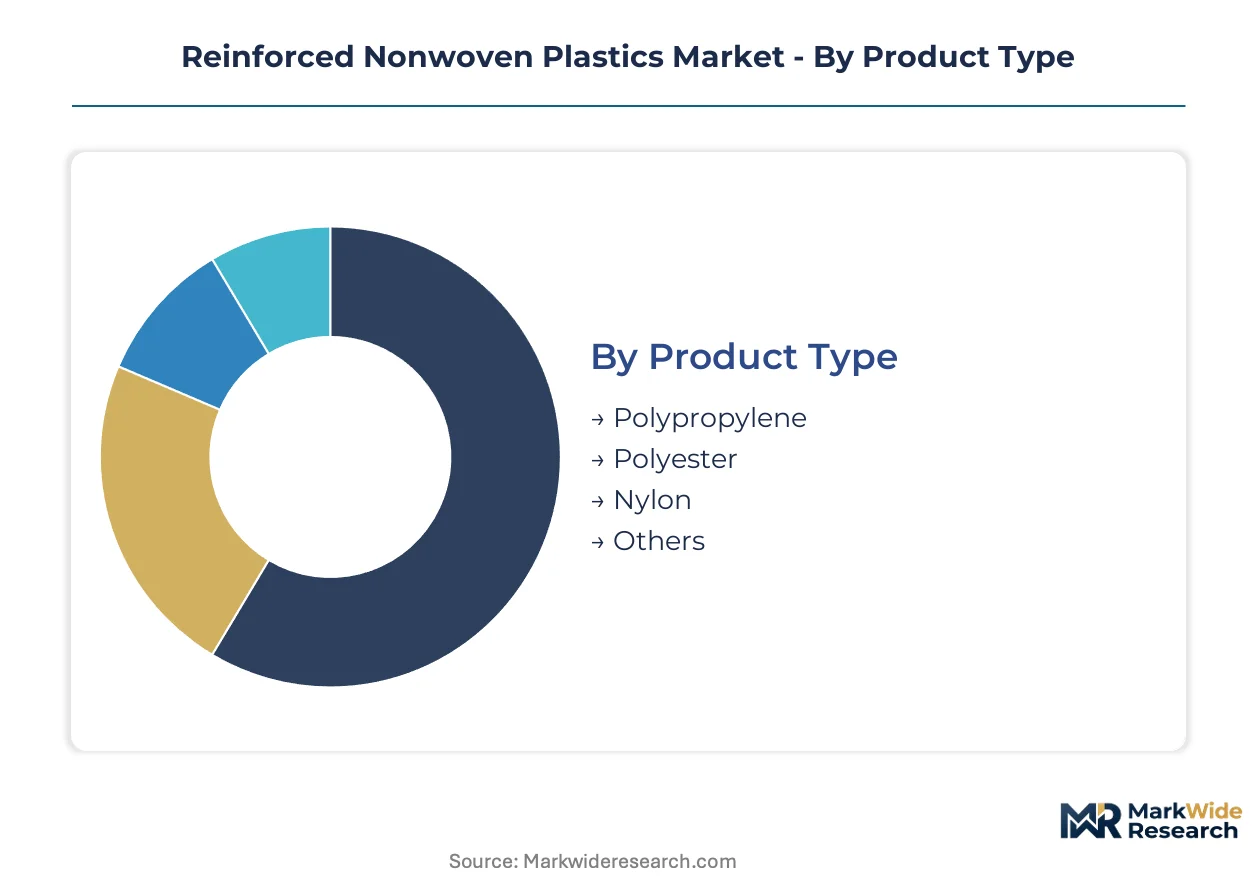
Market segmentation for reinforced nonwoven plastics illuminates the diverse material requirements and application-specific performance drivers across key industrial sectors. Understanding these distinctions is critical for manufacturers to align product development with evolving end-use demands.
Product Type:
The material science underpinning reinforced nonwovens differentiates products by their polymer base, each offering distinct mechanical and chemical properties for diverse industrial requirements.
- Polypropylene:Polypropylene-based reinforced nonwovens leverage a thermoplastic polymer known for its low density and chemical inertness. Demand concentrates in consumer goods and automotive interior components, driven by cost-effectiveness and processability.
- Polyester:Polyester reinforced nonwovens offer excellent tensile strength, dimensional stability, and resistance to UV radiation and hydrolysis. Civil engineering projects in India and Brazil drive demand for polyester geotextiles, valued for long-term durability in soil stabilization.
- Nylon:Nylon nonwovens provide superior abrasion resistance and high strength, finding niche applications in performance apparel and industrial filtration.
- Others:This category includes specialized polymers like aramid or glass fibers, utilized for extreme temperature resistance or specific structural reinforcement.
Mature deployment sits with Polypropylene. Newer deployment is concentrated in the development of specialized Others, particularly bio-based polymers for sustainability mandates.
End Use Industry:
The varied performance requirements across sectors dictate the specific formulations and structural designs of reinforced nonwoven plastics.
- Automotive:The automotive sector uses reinforced nonwovens for lightweighting, NVH (Noise, Vibration, Harshness) insulation, and interior trim components. Demand is expanding for EV battery separators and thermal management solutions, driven by the shift towards electric vehicle production.
- Construction:Construction relies on reinforced nonwovens for geotextiles, roofing membranes, and insulation, providing structural integrity and moisture barriers. Infrastructure investments in Asia-Pacific economies stimulate demand for high-performance geotextiles in road building and erosion control.
- Healthcare:Healthcare applications include surgical drapes, wound dressings, and sterilization wraps, requiring high barrier properties and absorbency.
- Consumer Goods:Consumer goods utilize reinforced nonwovens in durable bags, protective covers, and furniture components, valuing their cost-effectiveness and versatility.
Automotive and Construction sectors collectively represent the largest volume consumers. Healthcare applications exhibit significant expansion potential due to stringent regulatory demands and single-use product trends.
Manufacturing Stage:
Each phase of manufacturing introduces distinct technological challenges and opportunities to enhance the material's final mechanical properties and cost efficiency.
- Web Formation:Web formation involves arranging fibers into a coherent web, utilizing processes like spunbond, meltblown, or hydroentanglement. Advances in hydroentanglement technology are expanding applications in aerospace and performance apparel due to superior strength-to-weight ratios.
- Consolidation:Consolidation binds the fibers together, often through thermal bonding, chemical binders, or needlepunching, to impart structural integrity. The drive for enhanced durability in geotextiles and automotive insulation fuels innovation in advanced thermal bonding techniques.
- Material Preparation:Material preparation involves polymer compounding and fiber extrusion, ensuring consistent raw material quality for subsequent stages.
- Finishing:Finishing processes include coating, calendering, and slitting, customizing the nonwoven for specific functional requirements like water repellency or printability.
Innovation in Web Formation is critical for developing new product functionalities. Consolidation techniques are evolving to meet demands for higher performance and recyclability.
Application:
The specific functional demands of an application determine the required performance characteristics, such as tensile strength, filtration efficiency, or thermal resistance.
- Geotextiles:Geotextiles are permeable nonwoven fabrics used in civil engineering for soil stabilization, drainage, and erosion control. Infrastructure development in emerging economies like Brazil and India drives substantial demand for high-performance geotextiles in road and railway construction.
- Insulation:Reinforced nonwovens provide thermal and acoustic insulation in buildings and vehicles, contributing to energy efficiency and comfort. The electric vehicle market creates new opportunities for lightweight thermal insulation solutions in battery packs and cabin interiors.
- Filters:Filters utilize reinforced nonwovens for air, liquid, and gas purification, valued for their precise pore size distribution and chemical resistance.
- Packaging:Packaging applications leverage nonwovens for durable bags, protective wraps, and industrial coverings, offering strength and tear resistance.
Geotextiles and Insulation applications collectively command the largest market share. Filters are expanding quickly, driven by increasing air quality regulations and industrial process demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's robust chemical industry and advanced manufacturing capabilities anchor significant production of reinforced nonwoven plastics in Europe. This concentration supports specialized industrial applications and automotive component development. German policies like the EU Green Deal further influence material innovation and adoption.
Germany
Germany's automotive sector drives demand for lightweight interior components and advanced insulation materials. The EU Green Deal mandates recycled content, influencing material development for construction and vehicle manufacturing. Companies in Baden-Württemberg's automotive hub collaborate on new polymer science innovations.
United States
Construction and electric vehicle production propel demand for reinforced nonwovens in the United States. EPA directives on material composition and end-of-life management shape product development for sustainability. Johns Manville leverages its North American distribution network from Denver to serve construction projects.
China
Infrastructure investments and consumer goods manufacturing stimulate significant demand for reinforced nonwovens in China. China's dual carbon goals accelerate the adoption of sustainable materials across industrial sectors. The Yangtze River Delta's extensive manufacturing base serves both domestic and export markets for polypropylene-based products.
India
Civil engineering projects in India stimulate demand for high-performance geotextiles for soil stabilization and drainage. The PLI scheme encourages domestic manufacturing of advanced materials for various applications. Gujarat's industrial corridors are witnessing increased production capacity for polyester-based nonwovens.
South Korea
South Korea's advanced manufacturing capabilities and automotive industry drive demand for high-strength nonwoven components. National environmental regulations promote circular economy-compliant materials for various end-use sectors. Manufacturers in Gyeonggi Province focus on innovations in web formation for specialized applications.
Reinforced Nonwoven Plastics Market Key Industry Players
Established producers occupy the standard tier, providing cost-effective polypropylene-based solutions for consumer goods and automotive interiors. Emerging entrants pursue high-margin segments like smart textiles and bio-based polymers, aligning with sustainability mandates. The market structure features Tier-1 automotive suppliers, large-scale construction material providers, and specialized industrial application firms. Companies engage in strategic partnerships and extensive R&D to enhance material performance and meet regulatory compliance.
Specialists in advanced material science, such as Freudenberg Group, leverage extensive R&D in polymer science to serve specialized industrial applications. Johns Manville occupies a strong position in North America, particularly anchoring the construction materials sector through its robust distribution network. Meanwhile, Ahlstrom-Munksjö exemplifies a focus on high-margin segments, specializing in filtration and packaging media. These firms collectively represent the diverse strategic approaches within the reinforced nonwoven plastics market, from broad-based supply to niche technical solutions.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Johns Manville |
| Berry Global |
| Suominen Corporation |
| Toray Industries |
| Freudenberg Group |
| Ahlstrom-Munksjö |
| Fibertex Nonwovens |
| DuPont |
| Others |
Cost & Logistics Intelligence
Captive supply arrangements within large automotive and construction firms anchor their supply positions, influencing pricing power for specialized nonwoven plastics. This integration insulates major buyers from raw material volatility, dictating terms for smaller suppliers.
Pricing Analysis
Warranty and service bundling differentiate offerings in the reinforced nonwoven plastics market, moving buyers towards integrated solutions. Contract-based long-term offtake agreements dominate, especially for large construction and automotive projects. Price differentiation stems from material performance specifications and adherence to ISO standards for critical applications. Input cost volatility, particularly for polypropylene and carbon fiber, exerts downward pressure on manufacturer margins. Consumer goods manufacturers exhibit the highest price sensitivity, while aerospace and medical device producers prioritize performance over cost.
Supply Chain Analysis
Certification and qualification processes gate market access for reinforced nonwoven plastics, particularly for automotive and aerospace applications. Supply concentration centers in Germany, South Korea, and China, leveraging advanced manufacturing capabilities. The industry relies on raw material inputs like polypropylene, glass fibers, and carbon fibers. Recycling complexity, driven by the composite nature of these materials, poses a structural supply chain risk. Distribution runs through direct sales channels to Tier-1 automotive suppliers and large-scale construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, as firms pursue upstream control over specialized polymer compounding and fiber extrusion. Such integration secures consistent material quality and cost advantages for demanding end-use sectors.
For Market Incumbents:Deepen R&D investments in circular economy-compliant materials, particularly bio-based polymers, to counter regulatory threats from the EU Green Deal and CSRD. Incumbents should pursue strategic partnerships with Electric Vehicle battery manufacturers to secure new thermal management and insulation applications. Expanding advanced manufacturing lines in Gyeonggi Province, South Korea, also reinforces a strong supply position against emerging thermoplastic alternatives.
For New Entrants and Emerging Players:Launch via integrated solution models, offering engineering support and monitoring services for geotextiles in civil engineering projects. New entrants can target white-space opportunities in smart textiles for infrastructure health monitoring or advanced filtration media. The geotextiles segment in India and Brazil presents a penetrable market due to ongoing infrastructure investments. Focus on bio-based polymer nonwovens to align with EPA sustainability goals.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized material science firms with proprietary intellectual property in polymer composites and advanced web formation. The market exhibits strong long-term viability over the next 5-10 years, driven by sustained demand from automotive and construction sectors and global sustainability mandates. Investors should target companies demonstrating expertise in circular economy-compliant materials. The signal to watch is the increasing adoption rates of AI-driven process control in web formation, indicating technological leadership.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands advanced manufacturing capabilities in high-growth regions like Gyeonggi Province, South Korea. |
| Green Manufacturing Transition | Integrates bio-based polymers and sustainable processing to meet EU Green Deal mandates. |
| Long-term Supply Agreement | Secures raw material inputs like polypropylene and carbon fiber against price volatility. |
| Product Launch | Introduces new reinforced nonwovens for electric vehicle battery separators and thermal insulation. |
| Strategic Partnership | Collaborates with Tier-1 automotive suppliers on lightweight interior components and NVH solutions. |
Research Approach
EU REACH documentation, EPA directives, and ISO standards formed the secondary backbone for this analysis, complemented by industry association reports. Primary interviews with R&D directors, procurement leads, material scientists, and civil engineers provided crucial qualitative insights. This approach ensured robust bottom-up and top-down triangulation of market data.
A bottom-up sizing approach, validated through top-down market estimates, defined the forecast framework across the analysis window. Segmentation dimensions included product type, end-use industry, manufacturing stage, application, and regional regulatory clusters. Compound Annual Growth Rates were derived using regression analysis and market growth models. Key industry-specific inputs included electric vehicle production forecasts and global infrastructure spending projections.
Raw material price volatility, evolving regulatory landscapes, and unforeseen technological breakthroughs are the dominant revision risks for this market analysis. Forecasts reflect prevailing assumptions regarding economic conditions and industry development. A model refresh is warranted upon material change in global trade policies or significant material science advancements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Europe Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Asia-Pacific Natural Fiber Composites Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Carbon Composites Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Hybrid Composites Market