
 Battery Additives Market | 2026-2036
Battery Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Additives Market Analysis
Modular additive bundling is restructuring procurement patterns across the battery supply chain. BASF SE leverages its integrated chemical platform to offer combined electrolyte and performance additive packages. Cabot Corporation anchors North American conductive additive capacity through captive carbon black production. Orion Engineered Carbons competes on furnace-grade specialization for high-surface-area conductive blacks.
Battery additives comprise functional chemical compounds and carbonaceous materials introduced during cell manufacturing to enhance conductivity, thermal stability, cycling efficiency, and safety margins in electrochemical energy storage systems. Conductive additives such as carbon black and carbon nanotubes establish electron percolation networks at loadings of one to three percent by electrode weight. Electrolyte additives dominate margin pools due to formulation complexity and patent-protected molecular architectures, while solid-state technology segments attract the fastest R&D allocation as sulfide and oxide electrolyte systems require novel interface stabilizers.
REACH registration requirements in Europe, EPA chemical reporting in the United States, and China's GB standards under SAMR oversight collectively govern additive purity thresholds, hazardous substance labeling, and cross-border material flows. Battery manufacturers must demonstrate compliance with evolving F-Gas Regulation constraints on fluorinated electrolyte components and EU Battery Directive recycling content mandates. Stakeholders should monitor regulatory divergence between jurisdictions to anticipate reformulation costs and supply chain qualification timelines.
Market Dynamics
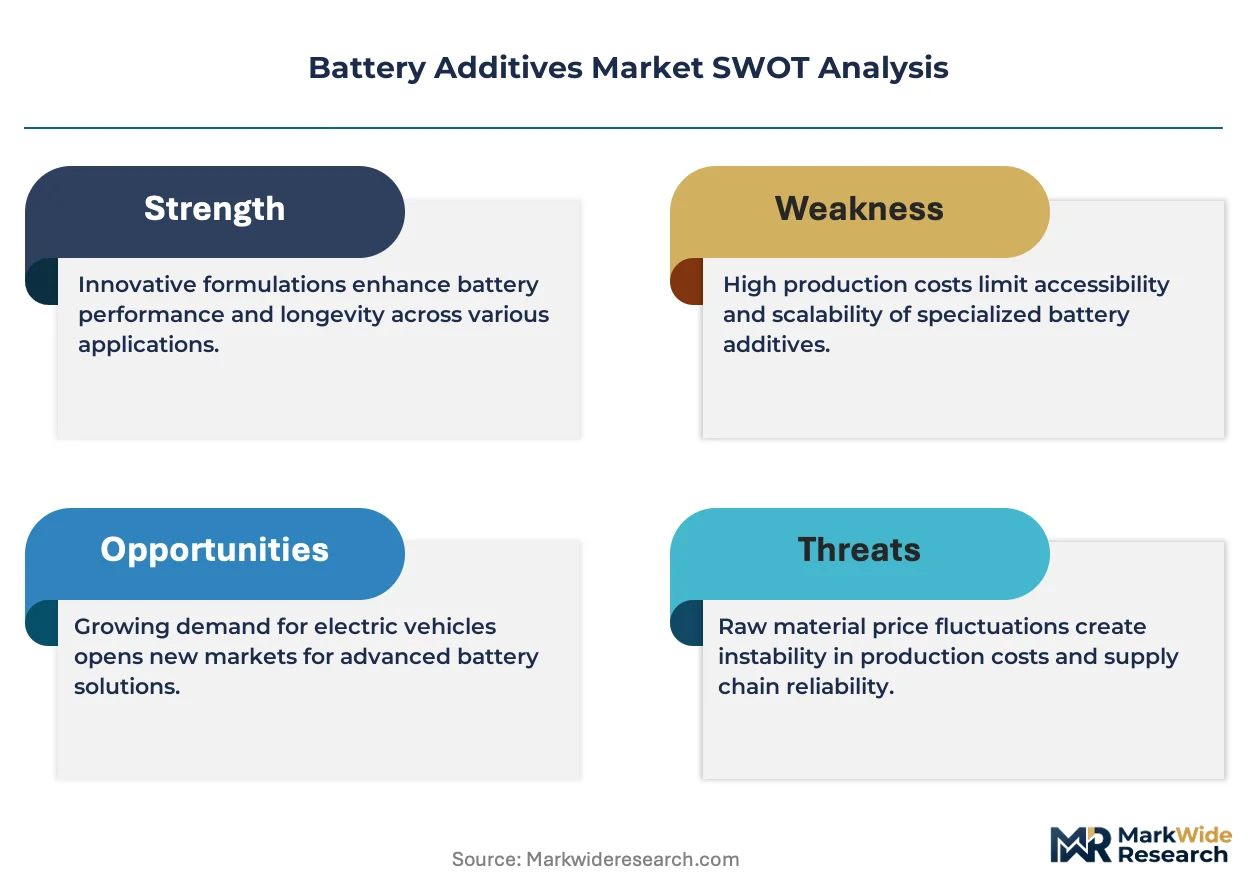
Electrolyte additive bundling is compressing supplier margins while elevating technical barriers to entry, as cell manufacturers consolidate procurement around integrated performance packages rather than discrete chemical inputs.
Growth Catalysts
- Solid-state electrolyte interfaces:Sulfide and oxide solid-state systems require novel stabilizer chemistries that command premium formulation value. Korean and Japanese cell producers are accelerating qualification timelines for these additives.
- REACH F-Gas constraints:The EU F-Gas Regulation is phasing down fluorinated greenhouse gases, forcing reformulation of electrolyte salts toward lower-GWP alternatives and creating demand for compatible additive architectures.
- Stuttgart-Wolfsburg cluster concentration:Germany's automotive battery hub is pulling conductive carbon black and electrolyte additive volumes through localized cathode active material plants serving BMW, Mercedes-Benz, and Volkswagen cell programs.
Market Restraints
- Furnace-grade carbon black feedstock volatility:High-surface-area conductive blacks depend on residual aromatic oils whose pricing tracks naphtha and coal tar markets, creating margin squeeze for additive compounders.
- China GB standard purity barriers:SAMR-enforced GB standards for conductive carbon black imports are tightening heavy metal and ash content thresholds, disqualifying legacy furnace-grade supply from Southeast Asian producers.
- Silicon anode volume expansion:Silicon's 300% lithiation swelling degrades conventional binder and electrolyte additive systems, limiting loadings to sub-10% graphite blends until next-generation polymer binders mature.
Strategic Opportunities
- India PLI scheme localization:India's production-linked incentive scheme for advanced chemistry cell manufacturing is creating first-mover additive qualification windows for electrolyte and conductive material suppliers establishing domestic compounding capacity.
- Dual carbon goal compliance services:China's MEE enforcement of dual carbon targets is opening advisory and certification revenue streams for additive suppliers who can document embodied carbon and recycled content for battery passports.
- Pre-lithiation additive convergence:Integration of pre-lithiation compounds with electrolyte additive packages is enabling silicon-anode commercialization by compensating for first-cycle capacity loss in high-energy cells.
Industry Challenges
- Electrochemical simulation talent scarcity:Cell manufacturers require additive suppliers to co-develop molecular architectures using density functional theory and finite element modeling, but PhD-level computational electrochemists concentrate at national laboratories and top-tier cell producers.
- Cross-jurisdiction qualification timelines:SAMR GB testing, ECHA REACH registration, and EPA TSCA pre-manufacture notification each demand 18-36 month validation cycles, delaying revenue recognition for novel additive launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Additives Market |
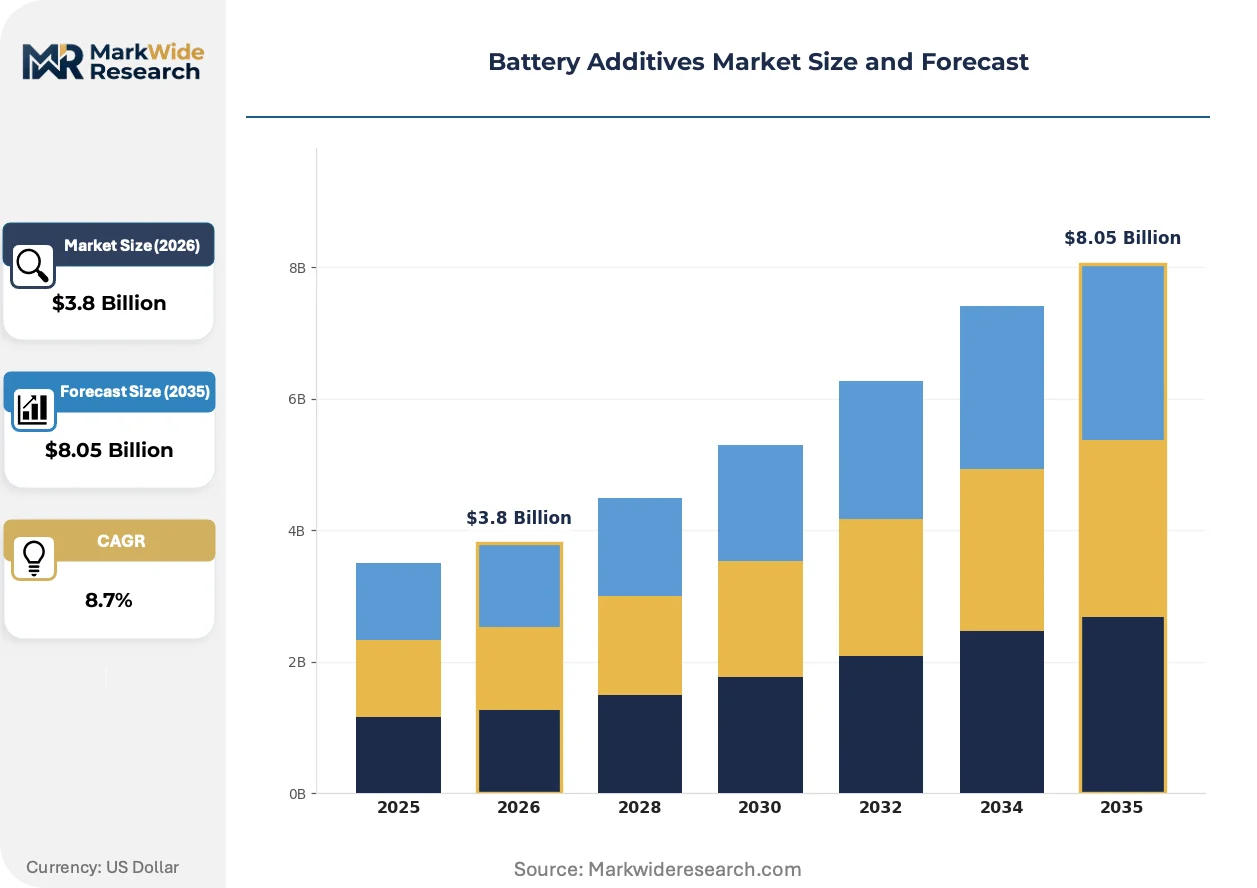
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Additives, Electrolyte Additives, Performance Additives, Thermal Stabilizers Application: Automotive Batteries, Industrial Batteries, Consumer Electronics, Renewable Energy Storage End User: Electric Vehicle Manufacturers, Electronics Manufacturers, Energy Storage Providers, Battery Manufacturers Technology: Lithium-ion Technology, Lead-acid Technology, Nickel-metal Hydride, Solid-state Technology |
| Companies Covered | Cabot Corporation, 3M, Imerys, BASF SE, Hammond Group, Inc., Orion Engineered Carbons, SGL Carbon, ALTANA, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Additives Market Emerging Trajectories
Additive molecular architecture is diverging along performance-specialist versus cost-optimized trajectories, with solid-state interfaces and silicon-anode compatibility commanding disproportionate R&D allocation.
Fluorinated electrolyte additives are rewriting stability thresholds for high-voltage cathode operation. Cell producers targeting 4.5V+ nickel-rich cathodes are adopting these compounds at pilot scale. The technology is compressing the viable window for conventional carbonate-based electrolyte systems.
ECHA REACH authorization requirements for persistent organic pollutants are tightening disclosure obligations for fluorinated electrolyte components. Battery manufacturers must now demonstrate substitution feasibility or secure time-limited derogations. The regulation is forcing additive suppliers to accelerate bio-based and non-fluorinated molecular development programs.
Cell manufacturers are consolidating additive procurement around single-source technical partnerships. Discrete spot purchasing of carbon black and electrolyte salts is yielding to multi-year co-development agreements with locked pricing. Korean cell producers are pioneering this model through dedicated technical service contracts with Japanese and German specialty chemical suppliers.
Battery Additives Market Segmentation
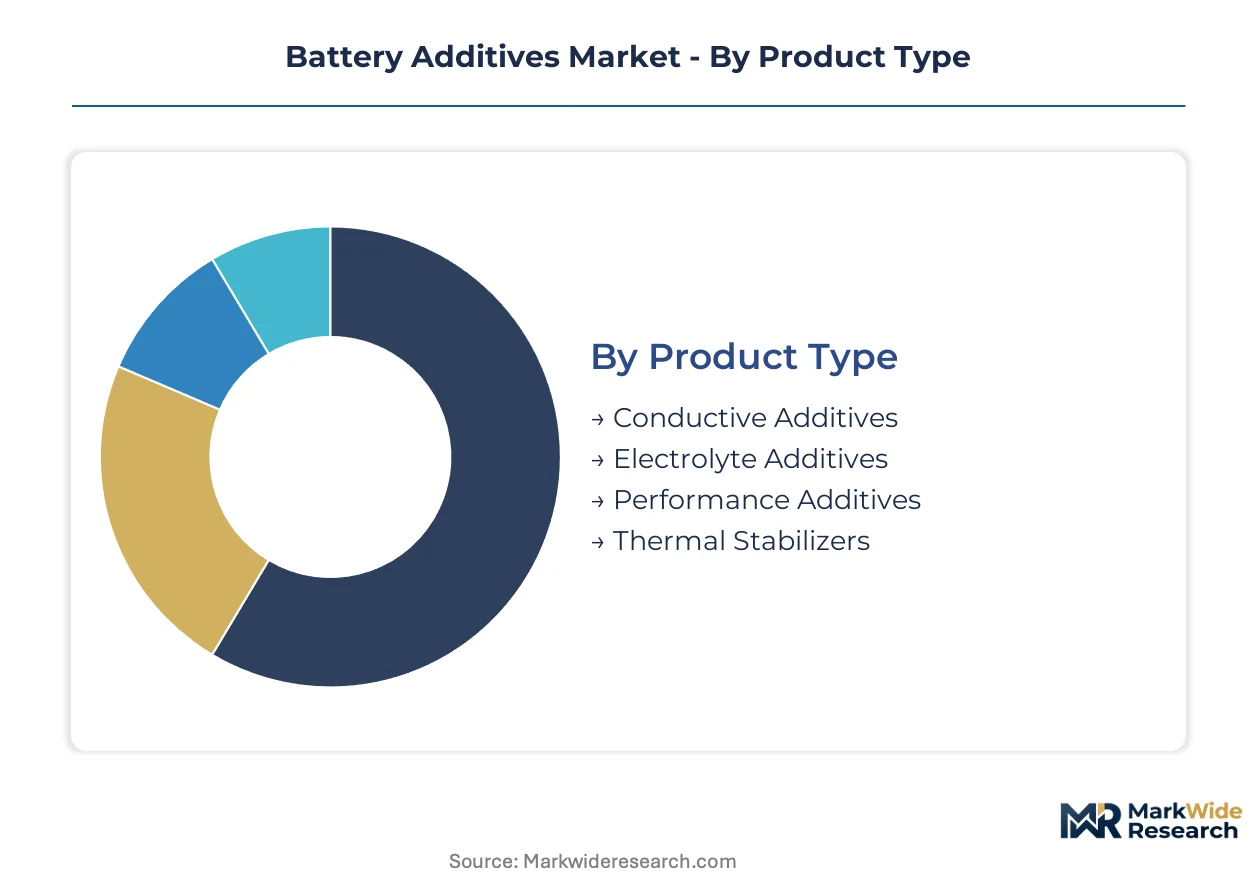
Battery additive procurement splits along technical performance tiers and cell chemistry requirements. Buyers prioritize conductivity thresholds, thermal runaway suppression, and cycle life extension when selecting across product categories.
Product Type:
Cost tier determines supplier qualification depth, with premium electrolyte formulations commanding multi-year co-development contracts while commodity conductive materials trade on spot pricing.
- Conductive Additives:Carbon black and carbon nanotubes establish electron percolation networks at one to three percent electrode loading. Demand concentrates in Germany's Stuttgart-Wolfsburg automotive cluster where BMW, Mercedes-Benz, and Volkswagen cathode plants pull furnace-grade and high-surface-area conductive blacks through localized supply agreements.
- Electrolyte Additives:Patent-protected molecular architectures including fluorinated compounds and solid-electrolyte interphase formulators dominate margin pools due to formulation complexity. Korean and Japanese cell producers are accelerating qualification timelines for sulfide and oxide solid-state stabilizers.
- Performance Additives:Binder systems and dispersants optimize electrode slurry rheology and mechanical adhesion during calendering operations.
- Thermal Stabilizers:Flame retardant and overcharge protection compounds prevent thermal runaway propagation in high-energy density cells.
Electrolyte Additives leads on scale; Thermal Stabilizers leads on momentum.
Application:
Volume concentration tracks electrification intensity across mobility and grid storage end-uses.
- Automotive Batteries:High-voltage traction battery packs for electric vehicles require conductive additives for fast-charge capability and electrolyte stabilizers for 4.5V+ nickel-rich cathode operation. China's dual carbon goals under MEE enforcement and EU F-Gas Regulation constraints are tightening purity and fluorinated compound disclosure requirements.
- Renewable Energy Storage:Grid-scale lithium-ion installations demand long-cycle-life electrolyte formulations and thermal management additives for daily cycling over 15-20 year operational lifespans. India's PLI scheme for advanced chemistry cell manufacturing is creating first-mover qualification windows for domestic additive compounding capacity.
- Industrial Batteries:Forklift, telecom backup, and motive power applications utilize lead-acid and nickel-metal hydride chemistries with specialized additive packages for deep-cycle durability.
- Consumer Electronics:Smartphone and laptop cells prioritize volumetric energy density with ultra-thin electrode additives and low-viscosity electrolyte formulations.
Automotive Batteries commands the largest volume footprint; Renewable Energy Storage is expanding most quickly.
End User:
Customer type shapes technical service intensity and contract structure.
- Electric Vehicle Manufacturers:Cell producers and automotive OEMs consolidate procurement around integrated additive packages rather than discrete chemical inputs, compressing supplier margins while elevating technical barriers.
- Battery Manufacturers:Dedicated cell producers including Korean and Japanese specialists pioneer multi-year co-development agreements with locked pricing and embedded technical service contracts.
- Electronics Manufacturers:Consumer device OEMs prioritize supply security and rapid formulation iteration for annual product refresh cycles.
- Energy Storage Providers:Utility and commercial integrators specify additive performance warranties tied to cycle life guarantees and degradation curves.
Battery Manufacturers leads on scale; Electric Vehicle Manufacturers leads on momentum.
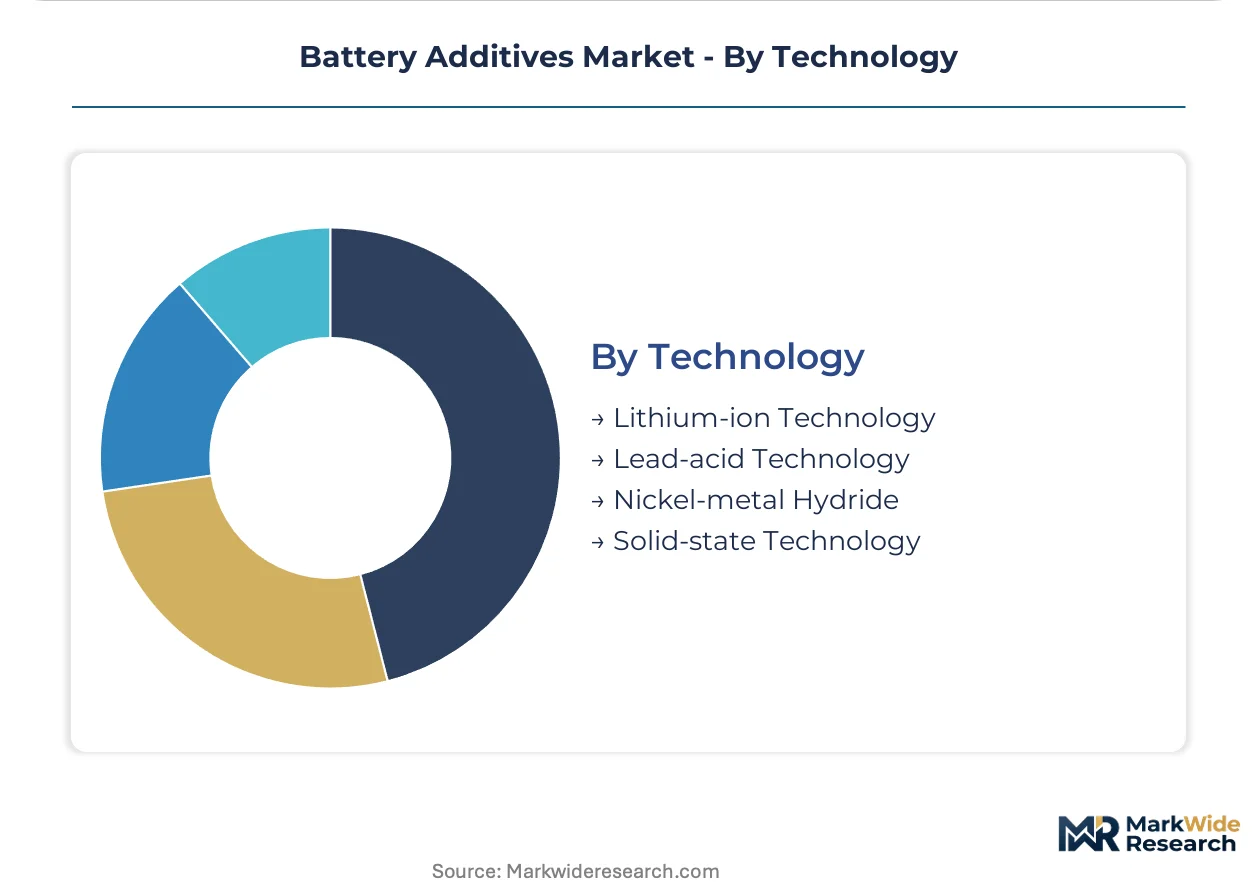
Technology:
Maturity curve determines additive specification stability versus reformulation frequency.
- Lithium-ion Technology:Dominant chemistry for automotive and grid applications with established additive protocols for graphite anodes and layered oxide cathodes. ECHA REACH registration and EPA TSCA pre-manufacture notification govern cross-border material flows with 18-36 month qualification timelines.
- Solid-state Technology:Sulfide and oxide electrolyte systems require novel interface stabilizers and pre-lithiation compounds to compensate for first-cycle capacity loss. Korean and Japanese producers are accelerating pilot-scale adoption.
- Lead-acid Technology:Mature chemistry for starter batteries and industrial applications with carbon additive enhancements for start-stop vehicle systems.
- Nickel-metal Hydride:Declining share in hybrid vehicles and consumer electronics with established electrolyte additive packages for memory effect mitigation.
Lithium-ion Technology leads on scale; Solid-state Technology leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The battery additives industry traces its industrial lineage to Germany's chemical manufacturing heritage and Japan's post-war electronics materials sector, with contemporary production gravitating toward automotive battery clusters and integrated chemical platforms.
China
Domestic cathode active material plants in Jiangsu and Fujian provinces are scaling electrolyte additive procurement to serve CATL and BYD cell manufacturing programs. SAMR-enforced GB standards are tightening purity thresholds for conductive carbon black imports, disqualifying legacy Southeast Asian furnace-grade supply. The Yangtze River Delta concentration around Shanghai anchors formulation R&D for solid-state interface stabilizers.
Germany
BMW, Mercedes-Benz, and Volkswagen cell programs are pulling conductive carbon black and electrolyte additive volumes through cathode plants clustered around Stuttgart and Wolfsburg. ECHA REACH F-Gas Regulation constraints are forcing reformulation of fluorinated electrolyte salts toward lower-GWP alternatives. BASF SE leverages its Ludwigshafen integrated chemical platform to offer bundled electrolyte and performance additive packages.
United States
EPA TSCA pre-manufacture notification requirements govern cross-border material flows with 18-36 month qualification timelines for novel additive architectures. Cabot Corporation anchors North American conductive additive capacity through captive carbon black production in the Gulf Coast petrochemical corridor. Midwest automotive battery investments are creating localized demand for thermal stabilizer compounds.
South Korea
LG Energy Solution and Samsung SDI are accelerating qualification timelines for sulfide and oxide solid-state stabilizers through dedicated technical service contracts. MFDS-aligned chemical safety assessments govern electrolyte additive import protocols for high-voltage cathode formulations. The Gyeonggi-Seoul corridor concentrates formulation co-development partnerships with Japanese and German specialty chemical suppliers.
India
The PLI scheme for advanced chemistry cell manufacturing is creating first-mover qualification windows for electrolyte and conductive material suppliers establishing domestic compounding capacity. BIS certification requirements are being harmonized with automotive battery safety standards for grid-scale storage deployments. Tamil Nadu and Gujarat are emerging as preferred locations for cathode active material and additive formulation plants.
Battery Additives Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and patent protection dimensions, with electrolyte additive specialists commanding multi-year co-development contracts while conductive carbon black producers compete on furnace-grade specialization and feedstock integration. The market structure reflects a tiered hierarchy: integrated chemical conglomerates with captive raw material positions, specialized carbon black manufacturers with high-surface-area furnace expertise, and electrolyte formulation houses with molecular architecture capabilities. Consolidation pressure is elevating technical barriers to entry as cell manufacturers reduce supplier counts. Dominant competitive moves include backward integration into carbon black feedstocks and strategic partnerships for solid-state electrolyte interface development.
Within the integrated chemical conglomerate tier, BASF SE and 3M exemplify platform players capable of bundling electrolyte and performance additive packages. Among specialized carbon black manufacturers, Cabot Corporation occupies a position anchored in North American captive production capacity. Orion Engineered Carbons sits within the furnace-grade specialization archetype competing on high-surface-area conductive blacks. These three represent distinct strategic postures: full-platform integration, regional feedstock dominance, and technical grade specialization respectively.
| Leading Market Players |
|---|
| Cabot Corporation |
| 3M |
| Imerys |
| BASF SE |
| Hammond Group, Inc. |
| Orion Engineered Carbons |
| SGL Carbon |
| ALTANA |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China's Jiangsu and Fujian provinces anchor electrolyte additive capacity expansion, compressing spot pricing for conductive carbon black while elevating long-term contract premiums for patent-protected electrolyte formulations. BASF SE's Ludwigshafen integrated platform and Cabot Corporation's Gulf Coast captive production demonstrate how ownership structure dictates supply discipline and pricing power across tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates multi-year co-development contracts with locked pricing from spot-market conductive carbon black transactions. Price differentiation hinges on formulation complexity and REACH F-Gas compliance certification, with fluorinated electrolyte additives commanding substantial premiums over commodity furnace-grade blacks. Cost compression in conductive additives is intensifying because naphtha and coal tar feedstock volatility squeezes compounder margins. Battery manufacturers exhibit the highest price sensitivity for conductive materials, while automotive OEMs prioritize technical service intensity over unit cost for electrolyte packages.
Supply Chain Analysis
Dual-sourcing requirements from Korean and Japanese cell producers mandate multi-supplier qualification for sulfide and oxide solid-state stabilizers, fragmenting procurement across domestic and import channels. Geographic supply concentration centers on China, Germany, and South Korea, with Jiangsu cathode plants, Stuttgart-Wolfsburg automotive clusters, and Gyeonggi-Seoul corridors pulling additive volumes through localized agreements. Raw material dependencies draw from residual aromatic oils, fluorinated salt precursors, and high-purity carbon black feedstocks. Single-source vulnerability threatens electrolyte additive supply given ECHA REACH and EPA TSCA qualification timelines spanning 18-36 months. Distribution runs through cathode active material plants serving cell manufacturing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in battery additives rests on electrolyte formulation premiumization and conductive carbon black feedstock integration, with solid-state interface stabilizers redirecting R&D allocation toward higher-value molecular architectures.
For Market Incumbents: Deploy backward integration into carbon black feedstocks to defend against naphtha and coal tar price volatility eroding conductive additive margins. BASF SE's bundled electrolyte and performance additive packages demonstrate how platform breadth neutralizes discrete spot-purchasing pressure from cell manufacturers. Incumbents should accelerate solid-state electrolyte interface co-development partnerships before Korean and Japanese producers lock in technical service contracts with locked pricing. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cell manufacturing represents the most penetrable entry corridor, with Tamil Nadu and Gujarat formulation plants offering first-mover qualification windows before domestic compounding capacity saturates. New entrants should pursue advisory and certification revenue streams around China's dual carbon goal compliance, documenting embodied carbon and recycled content for battery passports as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Specialty chemical conglomerates with integrated electrolyte platforms are the most active acquirer in this space, seeking molecular architecture capabilities to complement captive raw material positions. Acquisition targets should display patent-protected fluorinated compound portfolios or high-surface-area furnace-grade specialization. The signal to watch is qualification timeline compression for sulfide and oxide solid-state stabilizers, which would indicate inflection toward premium formulation value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | Cabot Corporation's Gulf Coast captive production anchors North American conductive additive capacity against import volatility. |
| Solid-State Interface Co-Development | Korean cell producers accelerate qualification timelines for sulfide and oxide stabilizers through dedicated technical service contracts. |
| Dual Carbon Compliance Services | China's MEE enforcement opens advisory revenue streams for additive suppliers documenting embodied carbon for battery passports. |
| India PLI Localization | Tamil Nadu and Gujarat cathode plants create first-mover windows for electrolyte and conductive material domestic compounding. |
| REACH F-Gas Reformulation | ECHA constraints force electrolyte salt reformulation toward lower-GWP alternatives, creating demand for compatible additive architectures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolyte formulation directors, carbon black procurement leads at cathode plants, cell manufacturer platform engineers, and specialty chemical R&D heads with secondary validation. Sources included customs and trade flow data, SAMR GB standard filings, ECHA REACH registration databases, SEC chemical segment disclosures, and automotive battery production databases. Bottom-up electrolyte additive volume estimates and top-down conductive material demand projections were cross-referenced for triangulation.
Segment-weighting across the projection horizon applied product type, application intensity, end-user procurement structure, and technology maturity curve dimensions. CAGRs were derived from electrolyte additive bundling trends, solid-state pilot-scale adoption rates, and conductive carbon black import qualification patterns. Forecast inputs incorporated F-Gas Regulation phase-down schedules, PLI scheme capacity buildout assumptions, and silicon anode commercialization timelines.
Underlying measurement precision varies by segment; electrolyte additive molecular architectures carry tighter precision than commodity conductive carbon black given patent landscape transparency. Forecasts reflect assumptions around SAMR GB enforcement consistency, ECHA REACH authorization timelines, and Korean-Japanese solid-state qualification acceleration. Deviation in fluorinated compound substitution feasibility or silicon anode binder system maturation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Chemical Silage Additives Market
Additives
Tragacanth Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Dispersing Agents Market
Additives
Lubricant Additives Market
Additives
Anti-Wear Additives Market
Additives
Paint Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Plastics Modifiers Market
Additives
Conditioning Agent Market
Additives
Tackifier Market
Additives
Phthalate Plasticizer Market
Additives
Spain Anti Caking Market
Additives
Global Sizing Agents Market
Additives
Citric Acid Anhydrous Market