
 CFRP Propeller Shaft Market | 2026-2036
CFRP Propeller Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
CFRP Propeller Shaft Market Outlook
Buyer concentration in the CFRP propeller shaft market is shifting as tier-one automotive suppliers consolidate procurement while marine OEMs fragment across specialized yacht builders and commercial shipyards. AVANCO GmbH leverages its German engineering base to dominate precision filament-winding contracts for high-torque automotive shafts. NAKASHIMA PROPELLER Co., Ltd. anchors Asian marine demand through integrated propeller-and-shaft packages. CENTA Corporation specializes in modular coupling systems that extend CFRP shaft applicability across hybrid propulsion architectures.
A CFRP propeller shaft consists of continuous carbon fiber filaments embedded in thermoset epoxy or thermoplastic matrices, manufactured via filament winding, pultrusion, or resin transfer molding to achieve specific stiffness-to-weight ratios exceeding steel by 60-70% while delivering critical torque transmission in rotating drivetrain assemblies. Marine propulsion applications occupy the most mature margin pool due to decades of corrosion-driven substitution, whereas automotive transmission shafts represent the fastest-expanding segment as OEMs pursue mass-reduction targets. Hybrid product-type configurations are gaining share where metal-CFRP interfaces solve bearing-seat durability challenges.
The EPA enforces fuel-economy standards that penalize fleet-weight excess, while the EU Green Deal and REACH restrict heavy-metal coatings on conventional steel shafts, together elevating CFRP as a compliance pathway. Japan's METI promotes carbon-fiber recycling infrastructure that lowers lifecycle environmental assessments for domestic manufacturers. Stakeholders must monitor thermoplastic resin cycle-time improvements and automated fiber-placement cost curves to determine timing for capacity commitments.
Market Dynamics
Automotive OEM procurement consolidation around electric drivetrain architectures is compressing supplier qualification timelines and favoring filament-winding specialists with proven torque-transmission track records.
Growth Catalysts
- EPA Fuel-Economy Mandates:Fleet-weight penalties under US regulations accelerate CFRP substitution for steel propeller shafts in light trucks and performance vehicles.
- Japan's METI Recycling Infrastructure:Government-funded carbon-fiber recovery programs lower lifecycle environmental assessments for domestic automotive and marine manufacturers.
- EU Green Deal Heavy-Metal Restrictions:REACH limitations on cadmium and chromium coatings for conventional steel shafts elevate corrosion-resistant CFRP as a compliance pathway.
Market Restraints
- Carbon Fiber Precursor Cost Volatility:Polyacrylonitrile feedstock prices fluctuate with acrylonitrile monomer supply, compressing filament-winding margins during petrochemical cycles.
- German Engineering Concentration:Precision winding equipment and specialized tooling suppliers cluster in Baden-Württemberg, creating single-source vulnerability for tier-one automotive contracts.
- Thermoset Cure Cycle Limitations:Epoxy matrix systems require 4-6 hour autoclave cycles that throttle throughput versus pultruded aluminum driveshafts.
Strategic Opportunities
- India's PLI Scheme for Automotive:Production-linked incentives for advanced materials manufacturing attract filament-winding capacity to Tamil Nadu and Maharashtra automotive corridors.
- Hybrid Metal-CFRP Interfaces:Bearing-seat durability solutions unlock commercial vehicle applications where full-composite designs previously failed fatigue specifications.
- Marine Retrofit Channel Expansion:Specialized yacht service yards in Florida and the Mediterranean adopt modular CFRP shaft replacement programs for corrosion-damaged superyacht drivetrains.
Industry Challenges
- Filament-Winding Technician Scarcity:Precision tension control and mandrel programming skills concentrate among aging workforces in Stuttgart and Nagoya manufacturing clusters.
- ISO 19070 Marine Certification Timelines:Type-approval testing for CFRP shaft torsional fatigue consumes 18-24 months, delaying new entrant market entry.
- Legacy Steel Shaft Inventory Integration:Automotive OEMs struggle to phase out multi-year steel shaft supply agreements while accelerating CFRP qualification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CFRP Propeller Shaft Market |
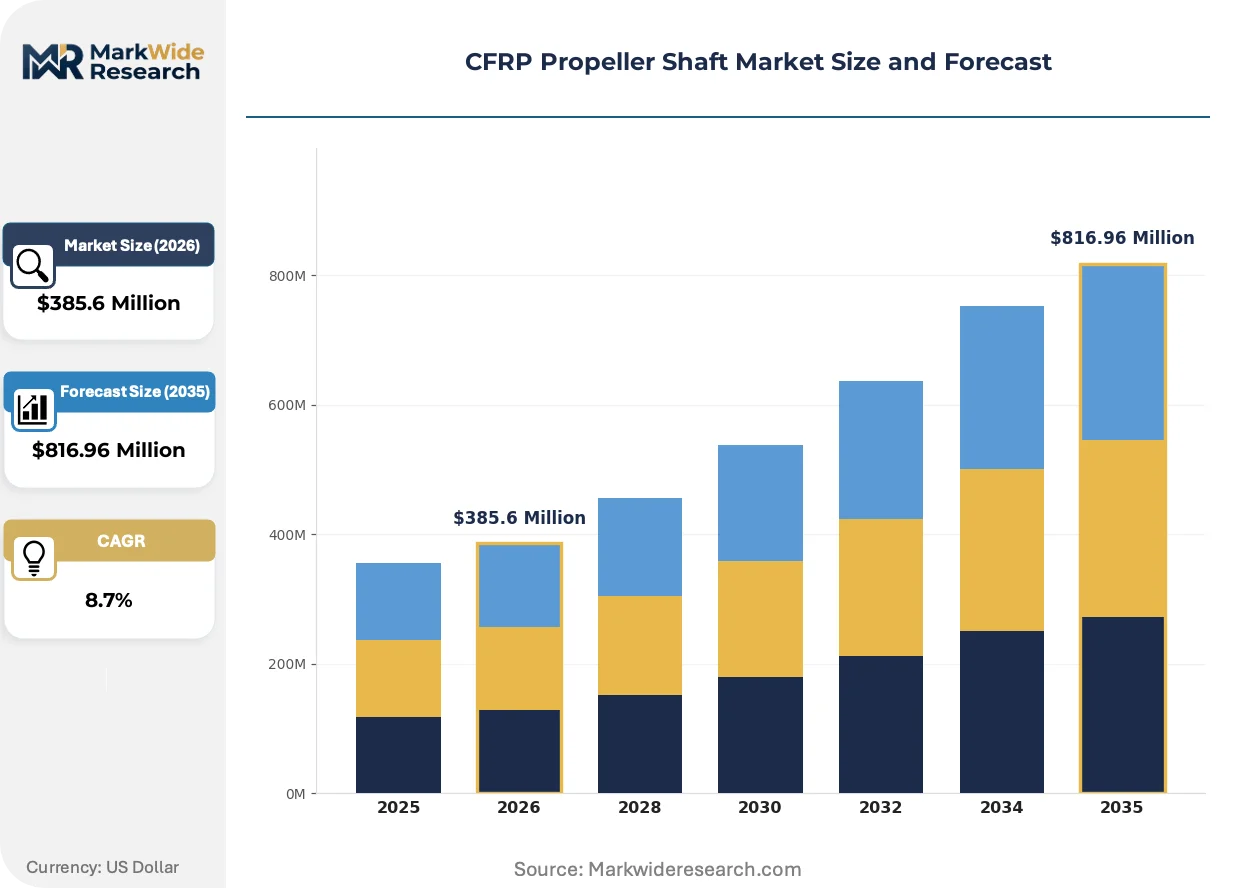
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic, Composite, Hybrid, Reinforced Deployment Mode: Onshore, Offshore, Modular, Fixed End User: Marine, Aerospace, Automotive, Industrial Application: Propulsion, Transmission, Leisure, Commercial |
| Companies Covered | Lentus Composites Ltd, AVANCO GmbH, NAKASHIMA PROPELLER Co., Ltd., Alfred Heyd GmbH u. Co. KG, Amarillo Gear Company, CENTA Corporation, Rexnord, Lentus Corporation, Johnson Power Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CFRP Propeller Shaft Market Strategic Shifts
Thermoplastic resin matrices and automated fiber placement are compressing manufacturing cycle times while regulatory pressure on fleet emissions intensifies material substitution mandates across automotive and marine propulsion systems.
Continuous carbon fiber-reinforced thermoplastic (CFRTP) propeller shafts utilizing polyamide or PEEK matrices are decentralizing production geography by enabling out-of-autoclave consolidation at temperatures below 400°C. Tier-one suppliers in Michigan and Bavaria are piloting in-situ consolidation lines that cut cycle times from hours to minutes. This thermal processing flexibility is decentralizing capacity decisions away from traditional epoxy autoclave clusters toward regional automotive assembly proximity.
REACH restrictions on hexavalent chromium surface treatments for steel shafts entered full enforcement across EU member states in 2024, eliminating corrosion-protection options for conventional marine drivetrain components. Shipyards in the Netherlands and Italy now specify CFRP shafts as default specifications for vessels under 50 meters. The regulatory compression is accelerating R&D investment in hybrid metal-composite interface designs that satisfy classification society bearing-load requirements.
Automotive OEMs are unbundling propeller shaft procurement from integrated axle-driveline contracts, creating direct purchasing relationships with composite specialists. This disintermediation fragments historical tier-one supplier monopolies in Germany and Japan. Fleet operators in California and fleet-compliance managers at Detroit headquarters now specify CFRP content percentages in supplier scorecards, shifting technical evaluation authority from mechanical engineering to sustainability procurement functions.
CFRP Propeller Shaft Market Segmentation
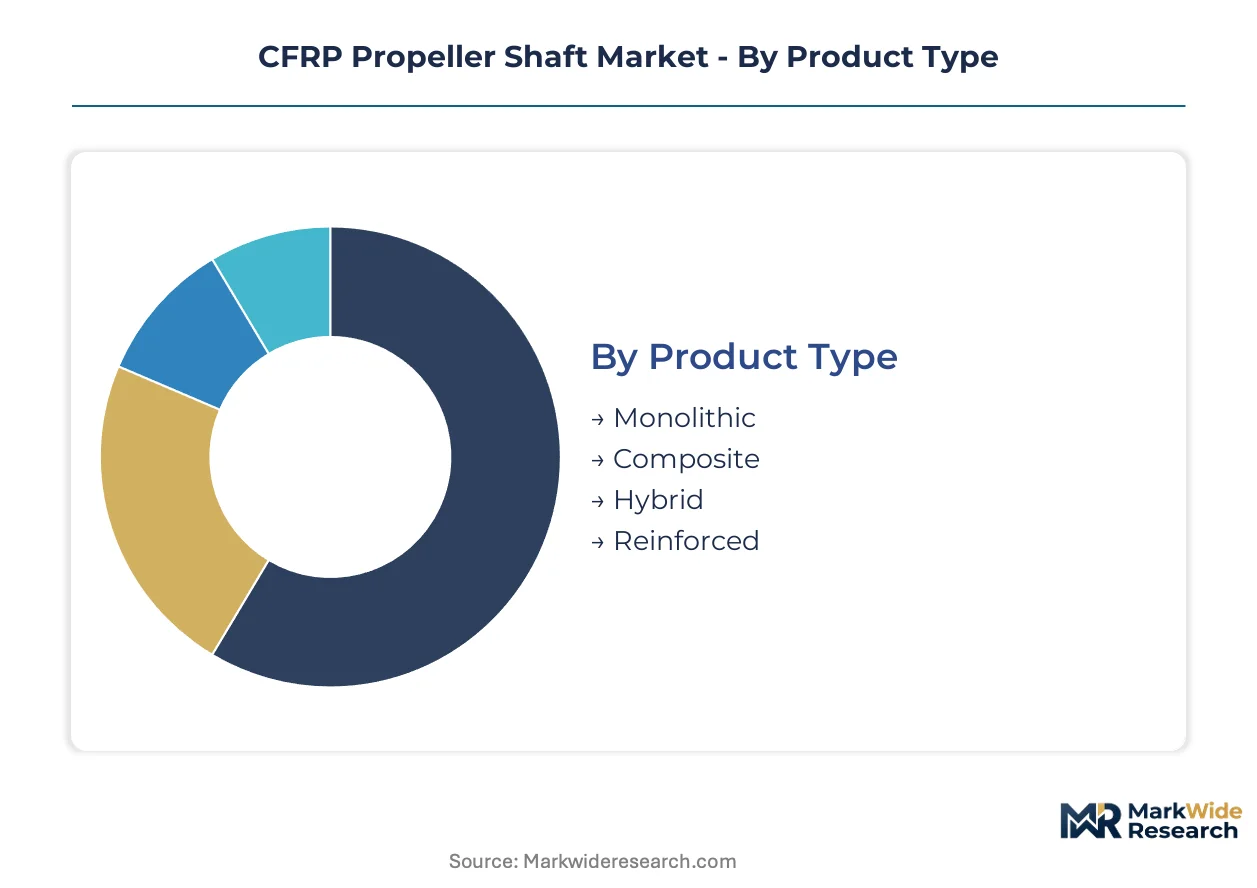
Segmentation in the CFRP propeller shaft market reveals divergent engineering requirements across propulsion architectures. Each dimension—product construction, installation environment, customer vertical, and functional use—carries distinct certification protocols and margin structures that shape supplier specialization.
Product Type:
Upgrade cycles in marine and automotive drivetrains are accelerating displacement of legacy steel shafts, with composite architectures capturing procurement specifications that previously specified monolithic metal designs.
- Monolithic:Continuous carbon fiber filaments wound in single-matrix epoxy systems deliver uniform torsional stiffness for high-speed marine propulsion. Yacht builders in the Netherlands specify these for superyacht shafts above 6 meters where corrosion resistance eliminates steel maintenance cycles. EPA fuel-economy penalties on fleet weight are compressing automotive qualification timelines for monolithic designs.
- Hybrid:Metal-composite interfaces at bearing seats and coupling flanges solve fatigue failures that plagued early full-composite automotive shafts. Tier-one suppliers in Baden-Württemberg are securing multi-year contracts for hybrid architectures in electric light trucks where torque transmission exceeds 15,000 Nm. METI-funded recycling infrastructure in Japan lowers lifecycle assessments for hybrid shafts with aluminum or titanium end fittings.
- Composite:Multi-layer fiber orientations optimize stiffness-to-weight ratios for aerospace auxiliary drives and industrial power transmission.
- Reinforced:Localized fiber density increases at stress concentration points extend service intervals in commercial marine operations.
Volume placements concentrate in Monolithic configurations for mature marine applications; the faster expansion belongs to Hybrid architectures solving automotive durability thresholds.
Deployment Mode:
Cost tiers separate installation approaches, with capital-intensive fixed systems commanding premium engineering margins while modular formats enable aftermarket retrofit economics.
- Modular:Segmented shaft designs with standardized coupling interfaces reduce replacement downtime from weeks to days. Florida and Mediterranean yacht service yards are building inventory positions for 8-12 meter modular CFRP shafts targeting corrosion-damaged superyacht drivetrains. The format is gaining share in commercial fishing fleets where seasonal maintenance windows are narrow.
- Fixed:Permanently installed single-piece shafts dominate new-build naval architecture where classification society rules permit integrated hull-mounting designs. Italian shipyards specify fixed CFRP shafts for vessels under 50 meters following REACH hexavalent chromium restrictions on steel alternatives. Long lead times for ISO 19070 certification protect incumbent suppliers with established type-approval records.
- Onshore:Land-based industrial power transmission applications include wind turbine drivetrains and heavy equipment linkages.
- Offshore:Submerged installations for oil platform auxiliary systems and deep-sea research vessels require specialized pressure-resistant matrix formulations.
Margin concentration sits with Fixed installations in premium new-build marine; Modular formats are climbing fastest as retrofit channels formalize.
End User:
Customer-type segmentation maps directly to certification burden and procurement authority concentration, with automotive OEMs consolidating specifications while marine buyers fragment across specialized yards.
- Marine:Decades of corrosion-driven substitution have built the most mature margin pool, with yacht builders and commercial shipyards specifying CFRP as default for shafts above 4 meters. Dutch and Italian classification societies accelerated CFRP adoption following REACH enforcement against cadmium and chromium coatings on steel. The segment commands premium pricing for custom-engineered shafts in superyacht and naval applications.
- Automotive:Electric drivetrain architectures are unbundling propeller shaft procurement from integrated axle contracts, creating direct purchasing relationships with composite specialists. Detroit OEMs and California fleet operators now specify CFRP content percentages in supplier scorecards. NHTSA safety validation timelines remain the primary constraint on mass-market penetration.
- Aerospace:Auxiliary power unit drives and helicopter tail rotor shafts utilize CFRP for weight-critical applications with lower torque requirements than main propulsion.
- Industrial:Mining equipment and heavy machinery drivetrains represent an emerging specification channel where fatigue resistance outweighs upfront cost premiums.
Procurement volume concentrates in Marine established specifications; Automotive direct-buying relationships are expanding most quickly.
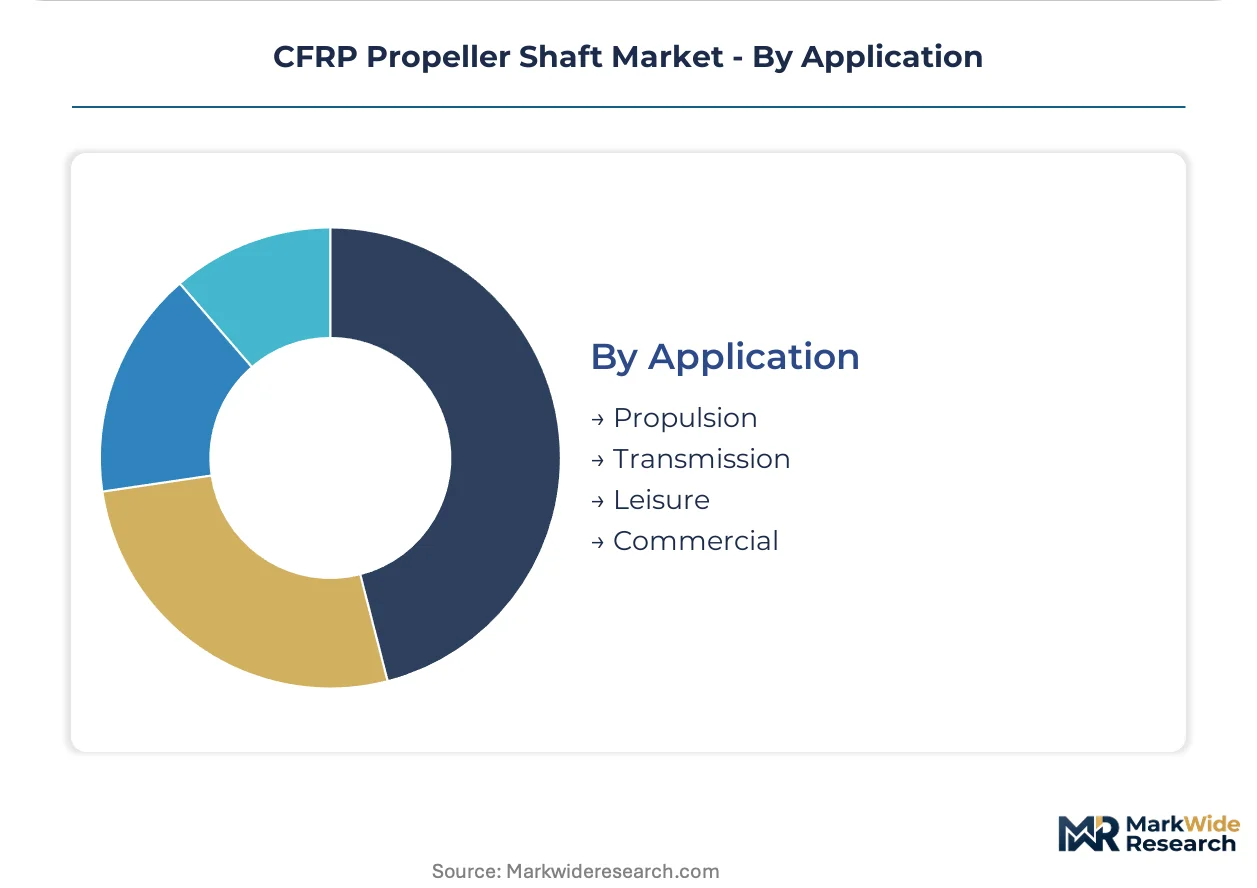
Application:
Functional use cases separate propulsion-primary shafts from secondary transmission linkages, with commercial duty cycles demanding durability validation that leisure applications often bypass.
- Propulsion:Primary drivetrain shafts transmitting main engine torque to propellers or wheels carry the highest certification burden and unit value. Marine classification societies require 18-24 month torsional fatigue testing for CFRP propulsion shafts under ISO 19070. Automotive OEMs are compressing these timelines for electric vehicle programs through simulation-validated physical testing protocols.
- Transmission:Secondary driveline linkages between gearbox and differential operate at reduced torque loads, enabling thinner-wall CFRP designs. Tier-one suppliers in Michigan and Bavaria are piloting thermoplastic matrix transmission shafts with sub-400°C consolidation cycles that cut manufacturing time from hours to minutes.
- Leisure:Recreational marine and motorsport applications prioritize weight reduction over extended service life, accepting shorter replacement intervals.
- Commercial:Heavy-duty trucking and cargo vessel specifications emphasize total cost of ownership calculations spanning 15-20 year service lives.
Revenue concentration remains in Propulsion applications with full certification; Transmission shafts are gaining share fastest through thermoplastic cycle-time improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for CFRP propeller shafts concentrates in automotive manufacturing clusters and marine shipbuilding corridors across Germany, Japan, and the United States. EPA fleet-weight penalties and EU corrosion-regulation enforcement are accelerating specification shifts in these three markets.
Germany
Baden-Württemberg hosts precision filament-winding equipment suppliers serving tier-one automotive contracts for electric light trucks. REACH hexavalent chromium restrictions eliminate steel shaft options for Dutch and Italian shipyards sourcing from German engineering firms. Stuttgart manufacturing clusters face technician scarcity for mandrel programming and tension control operations.
Japan
METI-funded carbon-fiber recycling infrastructure lowers lifecycle environmental assessments for domestic automotive and marine manufacturers. Nagoya manufacturing clusters concentrate precision winding skills among aging workforces. Classification society type-approval timelines for ISO 19070 certification protect incumbent suppliers with established track records.
United States
EPA fuel-economy mandates penalize fleet-weight excess in light trucks and performance vehicles. Michigan and California automotive corridors pilot thermoplastic matrix transmission shafts with sub-400°C consolidation cycles. Florida yacht service yards build inventory positions for modular CFRP shaft replacement programs.
Italy
Shipyards in the Netherlands and Italy specify CFRP shafts as default for vessels under 50 meters following REACH enforcement. Italian classification societies accelerated CFRP adoption through corrosion-driven substitution mandates. Custom-engineered shafts for superyacht applications command premium pricing in Mediterranean new-build channels.
India
PLI scheme production-linked incentives attract filament-winding capacity to Tamil Nadu and Maharashtra automotive corridors. Domestic manufacturers leverage government-funded advanced materials programs to qualify for electric vehicle supply chains. Regional assembly proximity is decentralizing capacity decisions away from traditional epoxy autoclave clusters.
CFRP Propeller Shaft Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue thermoplastic matrix technologies and modular retrofit formats. The vendor base stratifies across filament-winding specialists with proven torque-transmission records, marine-integrated propulsion packagers, and modular coupling system providers. Strategic archetypes include precision engineering houses, corrosion-solution marine specialists, and hybrid-interface innovators. Competitive moves center on capacity expansion toward regional automotive assembly proximity and technology licensing for out-of-autoclave consolidation processes.
Among German engineering-based fabricators, AVANCO GmbH exemplifies precision filament-winding specialization for high-torque automotive applications. NAKASHIMA PROPELLER Co., Ltd. anchors Asian marine demand through integrated propulsion packaging. CENTA Corporation occupies a position within modular coupling architectures that extend CFRP shaft applicability across hybrid propulsion systems.
| Leading Market Players |
|---|
| Lentus Composites Ltd |
| AVANCO GmbH |
| NAKASHIMA PROPELLER Co., Ltd. |
| Alfred Heyd GmbH u. Co. KG |
| Amarillo Gear Company |
| CENTA Corporation |
| Rexnord |
| Lentus Corporation |
| Johnson Power Ltd |
| Others |
Value Chain & Pricing Dynamics
Polyacrylonitrile precursor costs transmit directly from petrochemical feedstock markets through filament-winding margins to tier-one automotive contracts, with Baden-Württemberg engineering houses capturing premium pricing for ISO 19070-certified shafts while modular retrofit channels compete on replacement economics in Florida yacht service yards.
Pricing Analysis
Volume placements concentrate in standard-grade monolithic marine shafts where corrosion-driven substitution has commoditized base specifications, while margin pools sit with hybrid metal-composite architectures solving automotive fatigue thresholds above 15,000 Nm. Price differentiation hinges on certification tier—ISO 19070 type-approval commands 40-60% premiums over uncertified alternatives—and geographic delivery cost from Stuttgart or Nagoya clusters to assembly plants. Cost compression in thermoset epoxy segments is intensifying because CFRTP cycle-time improvements are repositioning pultruded aluminum as a viable substitute. Fleet procurement managers at Detroit OEMs exhibit highest price sensitivity, whereas Dutch superyacht builders prioritize performance specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with precision winding equipment manufacturers clustered in Baden-Württemberg, where specialized mandrel programming and tension control tooling anchors tier-one automotive qualification timelines. Geographic supply concentration centers on Germany, Japan, and the United States for filament-winding capacity, with emerging nodes in Tamil Nadu and Maharashtra drawing from PLI scheme incentives. Raw material dependencies rest on polyacrylonitrile precursor from petrochemical complexes, epoxy resin formulations, and carbon fiber tow from Toray and Hexcel supply bases. Tariff exposure on acrylonitrile monomer imports threatens margin stability during petrochemical cycles. Distribution runs through direct OEM procurement relationships that disintermediate historical tier-one axle-driveline integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CFRP propeller shaft procurement operates as a cost-of-compliance market where REACH hexavalent chromium restrictions and EPA fleet-weight penalties erect regulatory moats that favor incumbent suppliers with established type-approval records.
For Market Incumbents: Deepen backward integration into carbon fiber recycling infrastructure to capture METI-funded lifecycle assessment advantages and lock in Japanese automotive contracts. Prioritize capacity addition in Michigan and Bavaria to secure thermoplastic matrix transmission shaft programs before cycle-time improvements commoditize epoxy autoclave advantages. Defend against emerging filament-winding specialists by accelerating hybrid interface R&D for electric light truck torque thresholds. For New Entrants and Emerging Players: Yacht service yards in Florida and the Mediterranean represent the most penetrable channel partner type for modular retrofit programs targeting corrosion-damaged superyacht drivetrains. Target India's PLI scheme corridors in Tamil Nadu and Maharashtra to establish regional assembly proximity before epoxy autoclave clusters consolidate. Pursue thermoplastic out-of-autoclave certification to bypass 18-24 month ISO 19070 timelines that protect European incumbents. For Investors and Strategic Acquirers: Thermoplastic resin cycle-time compression reaching sub-400°C consolidation is the leading indicator that manufacturing economics are shifting toward regional automotive proximity plays. Position for 5-10 year horizon consolidation around hybrid metal-composite interface specialists with proven bearing-seat durability validation. Acquisition target archetype: mid-cap filament-winding houses with pending ISO 19070 type-approval and established relationships with tier-one automotive procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Matrix Transition | Sub-400°C consolidation cycles cut manufacturing time from hours to minutes in Michigan pilot lines. |
| Hybrid Interface Development | Metal-composite bearing-seat solutions unlock commercial vehicle applications above 15,000 Nm torque. |
| Modular Retrofit Channel Buildout | Florida and Mediterranean yacht service yards formalize inventory positions for 8-12 meter shaft replacements. |
| Carbon Fiber Recycling Integration | METI-funded infrastructure lowers lifecycle environmental assessments for Japanese automotive qualification. |
| Regional Capacity Decentralization | Tamil Nadu and Maharashtra corridors capture PLI scheme incentives for electric vehicle supply chain proximity. |
Study Parameters
Trade association filings from the European Boating Industry, Japan Carbon Fiber Manufacturers Association, and American Composites Manufacturers Association formed the secondary backbone, supplemented by EPA enforcement records, ECHA REACH restriction updates, and METI program documentation. Primary interviews with filament-winding plant managers, tier-one automotive procurement directors, marine classification society surveyors, and yacht service yard operations heads validated production cost structures and qualification timelines. Bottom-up shaft production estimates triangulated against top-down automotive and marine drivetrain demand projections.
Bottom-up modeling aggregated individual facility capacities across Baden-Württemberg, Nagoya, and Michigan manufacturing clusters, while top-down analysis tracked EPA fleet-weight penalty exposure and EU corrosion-regulation enforcement across the analysis window. Segmentation dimensions included product construction type, deployment mode, end-user vertical, and functional application with torque load thresholds. CAGRs derived from regression against historical substitution rates for steel shafts in marine propulsion and electric drivetrain mass-reduction targets. Industry-specific inputs incorporated polyacrylonitrile price volatility indices and ISO 19070 certification pipeline data.
Caveats apply where thermoplastic resin cycle-time improvements or carbon fiber precursor supply disruptions could materially shift the outlook. Deviation in EPA enforcement intensity or REACH heavy-metal restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
FRP Reactor Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Hybrid Composites Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Laminar Composites Market
Composite Materials
Transportation Composites Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Scrim Reinforced Films Market