
 Glass Fiber Reinforced Plastics (GFRP) Composites Market | 2026-2036
Glass Fiber Reinforced Plastics (GFRP) Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Fiber Reinforced Plastics (GFRP) Composites Market Analysis
Market Context with Strategic Players
Chinese state-backed fiber producers is repositioning global supply weights toward Asia-Pacific capacity zones. Jushi Group Co., Ltd. leverages vertical integration from glass melt to roving to capture margin across the value chain. Owens Corning sustains technology leadership in high-performance thermoplastic formulations for automotive structural parts. Saint-Gobain Corporation anchors European demand through specialized aerospace prepregs and construction-grade laminates.
Technical Definition and Structural Segments
Glass Fiber Reinforced Plastics (GFRP) composites consist of continuous or chopped E-glass, S-glass, or ECR-glass fibers embedded within thermosetting polyester, vinyl ester, or epoxy matrices, yielding specific tensile strengths exceeding 300 MPa at densities below 2.0 g/cm³ for primary load-bearing industrial applications. Thermosetting resins dominate volume throughput across marine hull fabrication and wind blade manufacturing, while thermoplastics register the fastest expansion as automotive OEMs pursue recyclability-aligned circular material strategies and sub-60-second cycle times. Compression molding and RTM technologies concentrate margin pools in aerospace and premium automotive segments where net-shape precision reduces secondary finishing costs.
Regulatory Frame and Forward Outlook
REACH restrictions on styrene emissions in open-mold processes and the EU Green Deal's embodied carbon thresholds for construction materials are tightening formulation standards and reshaping resin selection across European supply chains. The FAA's material qualification protocols for GFRP primary structures and China's GB standards for building fire safety collectively elevate testing burdens for cross-border suppliers. Stakeholders must monitor evolving automotive OEM recyclability mandates and wind energy blade end-of-life regulations to anticipate fiber recovery infrastructure investments.
Market Dynamics
Wind turbine blade manufacturers are extending rotor diameters beyond 120 meters, forcing GFRP suppliers to scale fiber architecture from woven mats to unidirectional prepregs capable of handling 80-meter single-piece spar caps.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Construction procurement in Germany and France now prioritizes lower-carbon fiber reinforcements over conventional steel and aluminum for facade cladding and structural profiles.
- Automotive thermoplastic conversion:OEMs in Stuttgart's supplier corridor demand sub-60-second cycle times for structural components, accelerating press-flow molding adoption.
- Offshore wind installation scale-up:Blade lengths exceeding 100 meters require specialized E-glass rovings with enhanced fatigue resistance for North Sea turbine arrays.
Market Restraints
- Borosilicate glass raw material volatility:Energy-intensive melting operations tie fiber pricing to natural gas benchmarks, compressing margins when European utility rates spike.
- Chinese state-backed capacity concentration:Jushi Group and CPIC command over 60 percent of global E-glass output, creating single-source dependency risk for European laminators.
- Styrene emission compliance costs:REACH restrictions on open-mold polyester processes force German and Italian fabricators toward closed-mold RTM investments exceeding 2 million euros per line.
Strategic Opportunities
- India's building code modernization:BIS adoption of fire-rated GFRP standards for high-rise construction opens specification pathways in Mumbai and Bangalore commercial developments.
- Hydrogen pressure vessel filament winding:Type IV composite tanks for fuel cell mobility converge automated fiber placement with epoxy-anhydride cure chemistries.
- Direct digital manufacturing channels:Specialized distributors now offer cut-to-length roving kits with embedded RFID traceability for small-batch wind repair operations.
Industry Challenges
- End-of-life blade decommissioning expertise:Pyrolysis and mechanical recycling infrastructure for 50-meter wind blades remains underdeveloped, stranding fiber recovery value.
- FAA primary structure qualification timelines:Material certification for GFRP flight-critical components demands 18-24 month test protocols, delaying new supplier entry into aerospace tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Fiber Reinforced Plastics (GFRP) Composites Market |
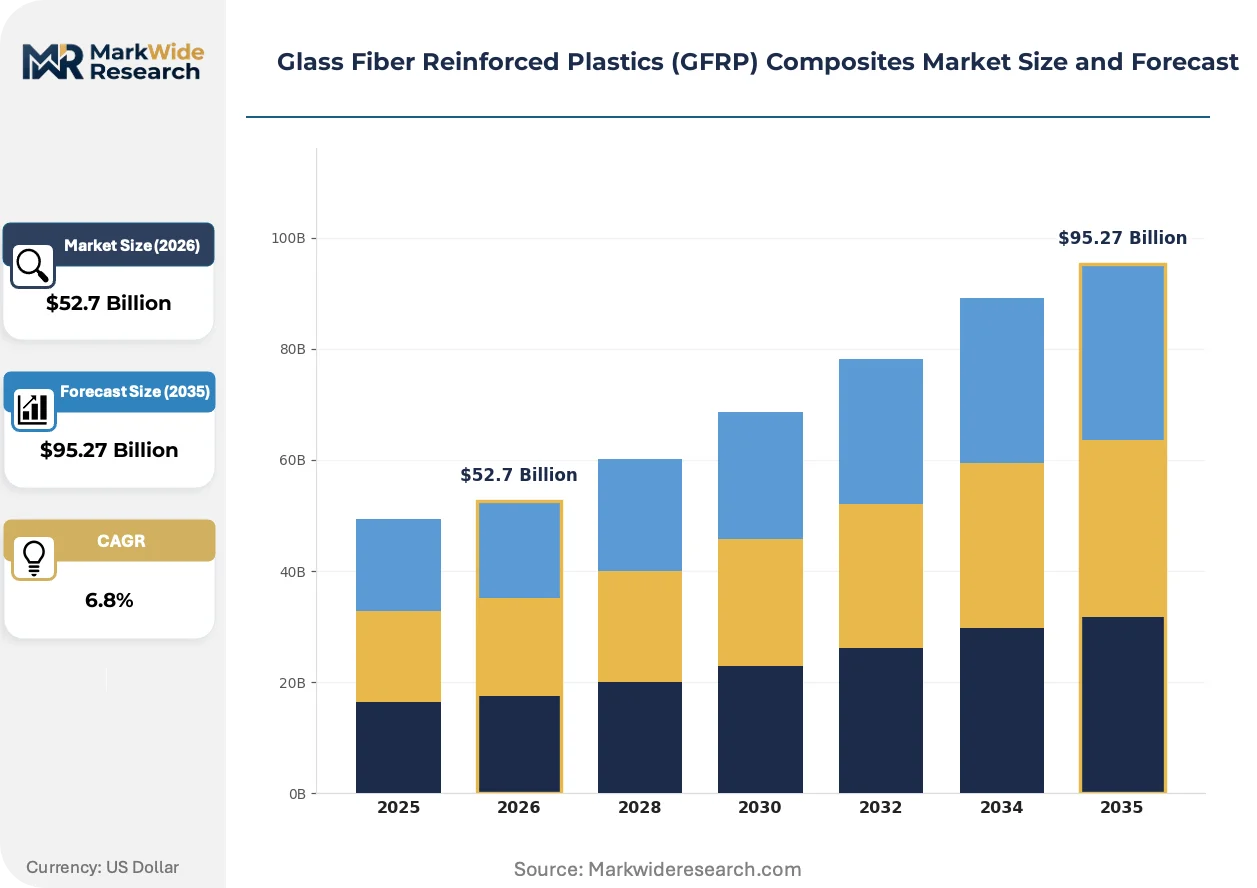
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting, Thermoplastics, Hybrid Composites, Gel Coat Application: Aerospace, Automotive, Marine, Construction End User: OEMs, Tier-1 Suppliers, Manufacturers, Contractors Technology: Filament Winding, Lay-Up, Compression Molding, RTM |
| Companies Covered | Chongqing Polycomp International Corporation, Saint-Gobain Corporation, Owens Corning, Taishan Fiberglass Inc., Nippon Electric Glass Co., Ltd., Jushi Group Co., Ltd., Johns Manville Corporation, AGY Holding Corp., PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Fiber Reinforced Plastics (GFRP) Composites Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are compressing product development cycles while fragmenting specification authority across end-use verticals.
Thermoplastic composites with continuous glass fiber reinforcement are overtaking thermoset dominance in automotive structural parts. BMW and Volkswagen Group suppliers in Lower Saxony now specify polyamide and polypropylene matrices for bumper beams and underbody shields. This shift enables closed-loop recycling aligned with EU end-of-life vehicle directives while eliminating paint-line VOC emissions.
REACH Annex XVII restrictions on styrene monomer exposure limits are forcing open-mold boat builders in Italy and Spain toward vacuum-infused epoxy systems. The regulation mandates workplace exposure thresholds below 20 ppm, rendering conventional spray-up polyester operations economically unviable for small craft manufacturers. Marine fabricators are consolidating production into fewer, larger facilities with automated closed-mold capability.
Specification authority is migrating from OEM engineering departments to specialized composite design houses. Wind turbine developers in Denmark and blade engineering consultancies in the Netherlands now dictate fiber architecture and resin selection, bypassing traditional tier-one supplier relationships. This disintermediation concentrates margin with firms holding proprietary failure analysis databases and full-scale structural test capabilities.
Glass Fiber Reinforced Plastics (GFRP) Composites Market Segmentation
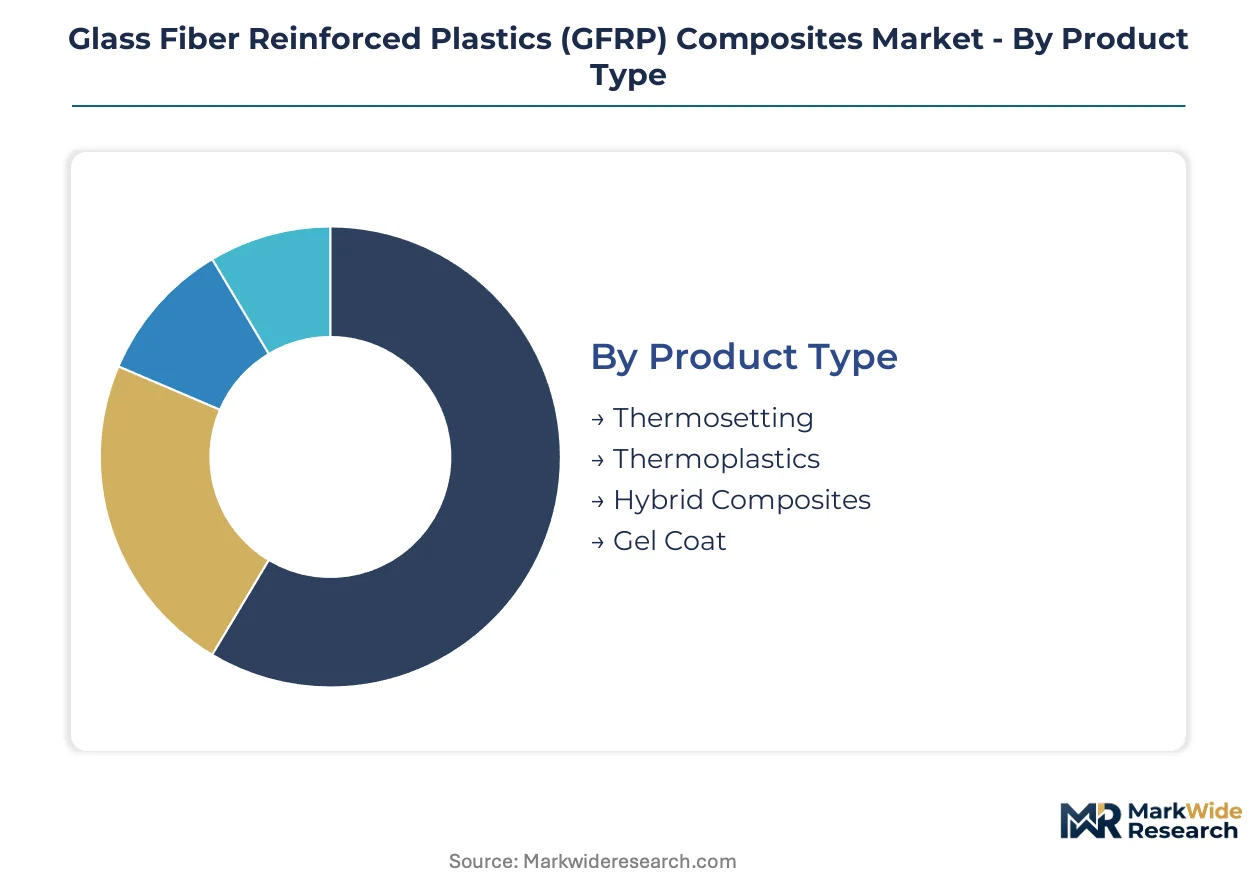
Segmentation in GFRP composites reveals how material specifications diverge across load-bearing requirements, regulatory exposure, and manufacturing throughput. Procurement patterns differ sharply between wind blade fabricators seeking fatigue-resistant unidirectional architectures and automotive stampers prioritizing sub-60-second thermoplastic cycle times.
Product Type:
Customization intensity varies from commodity thermoset bulk to engineered thermoplastic formulations requiring precise melt-flow calibration.
- Thermosetting:Polyester, vinyl ester, and epoxy matrices dominate marine hull fabrication and wind turbine blade manufacturing through room-temperature or elevated cure cycles. German blade producers in Lower Saxony specify epoxy-anhydride systems for 80-meter spar caps requiring enhanced fatigue resistance in North Sea installations.
- Thermoplastics:Polyamide and polypropylene matrices with continuous glass reinforcement enable closed-loop recycling aligned with EU end-of-life vehicle directives. Stuttgart automotive suppliers specify these for bumper beams and underbody shields to eliminate paint-line VOC emissions while hitting sub-60-second molding cycles.
- Hybrid Composites:Combines thermoset and thermoplastic layers for localized performance optimization in aerospace secondary structures.
- Gel Coat:Surface finishing layer providing UV resistance and aesthetic finish for marine and construction applications.
Leading the category by volume: Thermosetting. Expanding most quickly: Thermoplastics.
Application:
Margin pools concentrate where certification burdens and performance premiums intersect.
- Aerospace:Primary and secondary structural components demand FAA qualification protocols extending 18-24 months for material certification. European prepreg specialists supply flame-retardant epoxy systems for interior paneling and cargo liners where specific strength thresholds exceed 300 MPa.
- Automotive:Structural components including bumper beams, underbody shields, and battery enclosures drive thermoplastic conversion. Wolfsburg and Stuttgart supplier corridors specify press-flow molded polyamide composites for weight reduction targets.
- Marine:Hull fabrication and deck structures utilize spray-up and infusion processes now migrating toward closed-mold systems under REACH styrene restrictions.
- Construction:Facade cladding, structural profiles, and reinforcement bars benefit from EU Green Deal embodied carbon thresholds redirecting specification budgets from steel and aluminum.
Highest margin capture: Aerospace. Steepest volume climb: Automotive.
End User:
Specification authority migrates downstream as engineering complexity concentrates in specialized design houses.
- OEMs:Original equipment manufacturers in wind energy and automotive retain direct material qualification responsibility for primary structures. Vestas and Siemens Gamesa dictate fiber architecture and resin selection for blade platforms exceeding 100 meters.
- Tier-1 Suppliers:Automotive component specialists manage compound selection and molding process integration for platform-shared modules across multiple OEM programs.
- Manufacturers:Independent composite fabricators serve marine, construction, and industrial equipment markets with standardized laminating processes.
- Contractors:Installation-focused entities specify GFRP for infrastructure rehabilitation and architectural applications requiring field-adaptable joining methods.
Specification control concentrates with: OEMs. Fastest procurement growth: Tier-1 Suppliers.
Technology:
Capital intensity and cycle time requirements fragment process selection across end-use scale and precision demands.
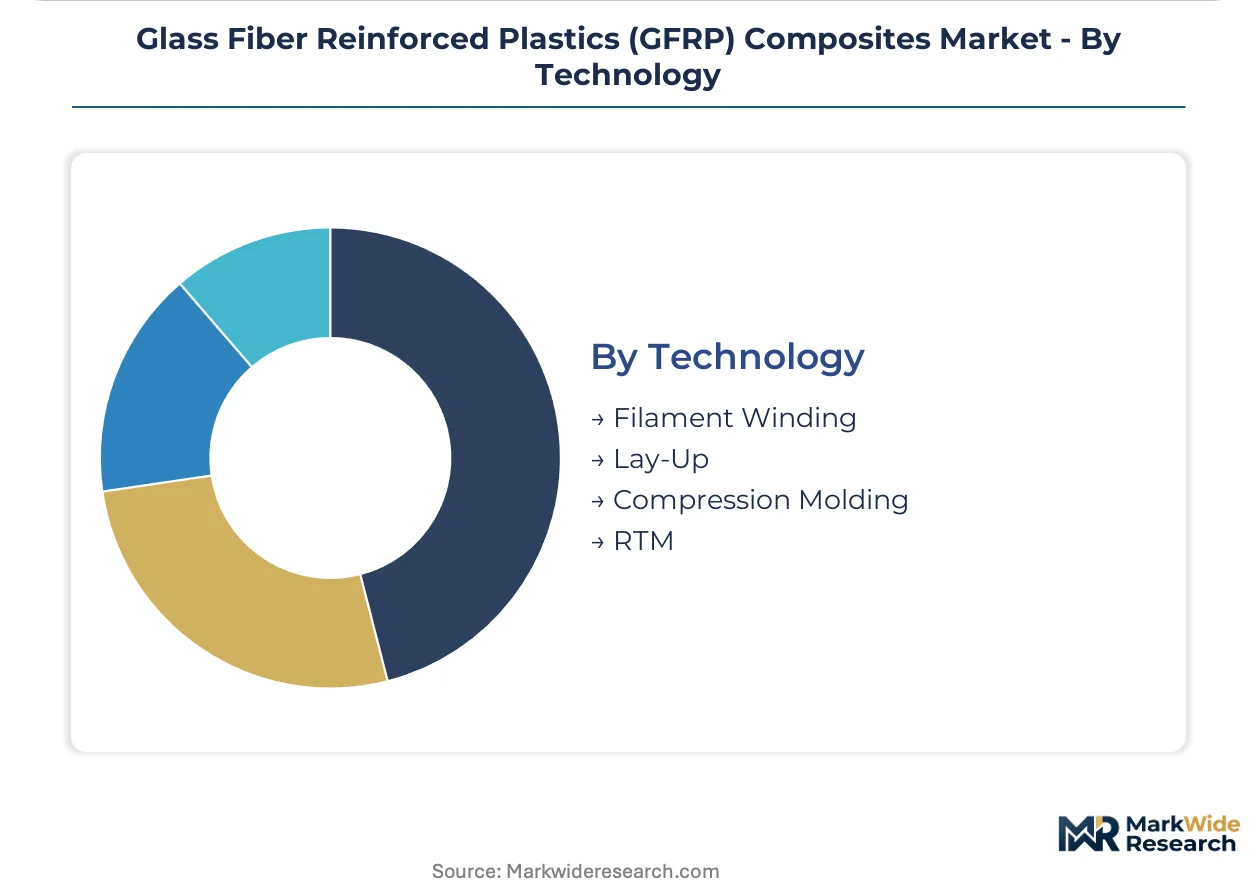
- Filament Winding:Automated fiber placement around mandrels produces pressure vessels, pipes, and cylindrical structures with optimized hoop strength. Hydrogen mobility applications drive adoption for Type IV composite tanks requiring precise fiber tension control.
- Lay-Up:Manual or automated fiber placement with subsequent resin infusion remains dominant for marine hulls and wind blade shells. Italian and Spanish boat builders migrate from open-mold spray-up to vacuum-infused epoxy under REACH Annex XVII styrene limits.
- Compression Molding:Matched-die forming of sheet molding compound enables high-volume automotive component production with sub-60-second cycle times.
- RTM:Resin transfer molding delivers net-shape precision for aerospace and premium automotive segments, reducing secondary finishing costs through closed-mold control.
Dominant by throughput: Lay-Up. Gaining share fastest: RTM.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass melting operations in Germany's industrial corridor anchor European supply chains for high-performance fiber reinforcements. Natural gas pricing volatility at these energy-intensive sites directly compresses margin structures for downstream laminators. Procurement patterns diverge sharply between automotive stampers in Stuttgart and wind blade fabricators in Lower Saxony.
Germany
Automotive OEMs in Stuttgart and Wolfsburg corridors specify thermoplastic composites for sub-60-second cycle times on structural components. REACH Annex XVII styrene exposure limits below 20 ppm force marine fabricators toward closed-mold RTM investments exceeding 2 million euros per production line. Lower Saxony wind blade producers now source epoxy-anhydride systems for 80-meter spar caps bound for North Sea installations.
China
State-backed capacity concentration at Jushi Group and CPIC commands over 60 percent of global E-glass output, creating single-source dependency risk for European buyers. GB standards for building fire safety elevate testing burdens for cross-border construction material suppliers. Yangtze River Delta manufacturing clusters supply unidirectional prepregs for domestic wind turbine blade platforms exceeding 100 meters.
United States
FAA material qualification protocols for GFRP primary structures demand 18-24 month certification timelines, delaying new supplier entry into aerospace tiers. EPA and OSHA workplace exposure regulations shape resin selection for open-mold fabricators in Gulf Coast marine manufacturing zones. Texas and Louisiana chemical corridors supply vinyl ester formulations for corrosion-resistant industrial equipment.
India
BIS adoption of fire-rated GFRP standards for high-rise construction opens specification pathways in Mumbai and Bangalore commercial developments. Central Electricity Authority grid codes for renewable integration accelerate wind blade manufacturing demand. Gujarat industrial zones host emerging composite fabricators serving domestic infrastructure rehabilitation projects.
France
EU Green Deal embodied carbon thresholds redirect construction procurement budgets from steel and aluminum toward lower-carbon fiber reinforcements for facade cladding. ANSM workplace safety regulations align with REACH styrene restrictions affecting open-mold boat builders in Mediterranean coastal regions. Auvergne-Rhône-Alpes aerospace clusters demand flame-retardant epoxy prepregs for interior paneling applications.
Glass Fiber Reinforced Plastics (GFRP) Composites Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue thermoplastic conversion and circular material strategies. The vendor base stratifies across three maturity levels: integrated fiber-to-composite conglomerates, specialized prepreg formulators, and regional laminators serving marine and construction verticals. Two strategic archetypes dominate: backward-integrated glass melt operators capturing margin across the value chain, and technology-focused compounders commanding premium positioning in automotive and aerospace grades. Capacity expansion and formulation licensing represent the dominant competitive moves as players defend position against Chinese state-backed output growth.
Among Asia-Pacific-based integrated producers, Chongqing Polycomp International Corporation and Taishan Fiberglass Inc. exemplify the scale-driven archetype with captive glass melting through roving production. Saint-Gobain Corporation occupies a position within the European specialty tier, anchoring demand through aerospace prepregs and construction-grade laminates. Owens Corning represents the technology leadership vector in high-performance thermoplastic formulations for automotive structural applications.
| Leading Market Players |
|---|
| Chongqing Polycomp International Corporation |
| Saint-Gobain Corporation |
| Owens Corning |
| Taishan Fiberglass Inc. |
| Nippon Electric Glass Co., Ltd. |
| Jushi Group Co., Ltd. |
| Johns Manville Corporation |
| AGY Holding Corp. |
| PPG Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Specialized wind blade laminator labor pools in Lower Saxony create cost-of-labor differentials that widen pricing spreads between premium certified prepregs and commodity thermoset bulk. German fabricators absorbing REACH compliance investments pass these costs downstream, while Chinese state-backed producers compete on unbundled base-material pricing.
Pricing Analysis
Warranty-backed fatigue-performance guarantees separate premium epoxy-anhydride prepreg tiers from unbundled commodity roving supply. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-standard grades reflects FAA qualification timelines and OEM audit burdens. Cost compression in commodity E-glass rovings is intensifying because Jushi Group and CPIC flood spot markets with state-subsidized output. Tier-1 automotive suppliers in Stuttgart exhibit lowest price sensitivity given platform-lock contracts, while independent marine fabricators in Italy and Spain face acute margin pressure from styrene-compliance retrofit costs.
Supply Chain Analysis
Borosilicate glass melt capacity rests on concentrated German and Chinese industrial zones where natural gas pricing volatility directly feeds fiber cost structures. European downstream laminators draw specialized epoxy formulations from Texas and Louisiana chemical corridors, while unidirectional prepreg architectures source from Yangtze River Delta manufacturing clusters. Single-source vulnerability concentrates around Jushi Group and CPIC commanding over sixty percent of global E-glass output. Distribution runs through specialized composite distributors offering cut-to-length kits with embedded RFID traceability for small-batch wind repair operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Annex XVII styrene exposure thresholds below twenty ppm erect barrier-to-entry moats favoring closed-mold RTM investors over open-mold incumbents.
For Market Incumbents: Lock in aerospace certification pipelines against eighteen-to-twenty-four-month FAA material qualification timelines that delay substitute supplier entry. Owens Corning and Saint-Gobain should deepen backward integration into captive glass melt capacity to defend margin compression from Chinese state-backed spot pricing. Threat vectors include thermoplastic conversion acceleration by automotive OEMs pursuing sub-sixty-second cycle times. For New Entrants and Emerging Players: Specialized composite design houses in Denmark and the Netherlands offer partnership pathways to specification authority migration bypassing traditional tier-one relationships. White-space targets concentrate in India's BIS fire-rated GFRP standards adoption for Mumbai and Bangalore high-rise construction, plus hydrogen pressure vessel filament winding for Type IV composite tank applications. Go-to-market positioning should emphasize automated fiber placement expertise with epoxy-anhydride cure chemistry specialization. For Investors and Strategic Acquirers: Re-rating potential sits with thermoplastic compounders given EU end-of-life vehicle directive alignment and circular material strategy mandates from Wolfsburg and Stuttgart OEMs. Acquisition targets should screen for proprietary failure analysis databases and full-scale structural test capabilities. Signal to watch: wind energy blade end-of-life regulation finalization triggering fiber recovery infrastructure investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Melt Capacity | Jushi Group captures margin across roving-to-prepreg value chain against European utility volatility. |
| Thermoplastic Formulation Licensing | Polyamide matrix technology transfers enable Stuttgart suppliers to hit EU recyclability mandates. |
| Closed-Mold RTM Line Investment | German marine fabricators exceed two-million-euro per line thresholds to satisfy REACH Annex XVII. |
| Specialized Design House Acquisition | Netherlands blade engineering consultancies concentrate specification authority away from tier-one laminators. |
| Hydrogen Pressure Vessel Certification | Type IV composite tank qualification opens mobility fuel cell filament winding revenue streams. |
Methodological Framework
Multi-period observation of wind blade length extensions, automotive thermoplastic conversion rates, and REACH enforcement patterns anchored the trend analysis, supplemented by interviews with blade engineering directors, automotive platform engineers, marine fabricator plant managers, and specialized composite distributors. Secondary validation drew from ECHA regulatory filings, EU Green Deal construction procurement databases, FAA material qualification protocols, and customs trade data for E-glass roving flows. Bottom-up volume builds across resin matrix types and fiber architectures triangulated against top-down end-use industry consumption estimates.
The input-output matrix framed demand as function of wind turbine rotor diameter scaling, automotive lightweighting targets, and embodied carbon threshold compliance across EU member states. Segmentation dimensions modeled include thermoset versus thermoplastic matrix chemistry, aerospace-automotive-marine-construction application verticals, and lay-up versus RTM versus compression molding process technologies. CAGRs derived from elasticity-adjusted demand curves incorporating natural gas price sensitivity for borosilicate glass melting operations and OEM platform lifecycle timing.
Caveats apply where FAA certification timeline compression, Chinese state subsidy policy shifts, or EU Green Deal embodied carbon threshold revisions could materially shift the outlook. Forecasts embed assumptions around wind blade decommissioning infrastructure development pace and automotive OEM recyclability mandate enforcement timing. A small set of triggers—REACH Annex XVII expansion, GB standards adoption acceleration in India, and North Sea offshore wind installation scale—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Pultrusion Market
Composite Materials
Global FRP Vessels Market
Composite Materials
China Marine Composites Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Reinforced Plastics Market
Composite Materials
Lightweight Materials Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Biocomposites Market