
 Asia-Pacific Natural Fiber Composites Market | 2026-2036
Asia-Pacific Natural Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Natural Fiber Composites Market Insights
Biodegradable resin matrices paired with bast fiber reinforcement is rewriting material selection protocols across automotive and construction supply chains in Asia-Pacific. Toray Industries leverages its carbon fiber expertise to anchor high-performance hybrid natural fiber offerings for Japanese OEMs. Jilin Chemical Fiber Group dominates domestic bast fiber supply, while UPM-Kymmene extends European biocomposite know-how into Southeast Asian packaging and panel applications.
Natural fiber composites combine lignocellulosic fibers such as jute, hemp, or kenaf with thermoplastic or thermoset matrices to yield lightweight, moldable materials with specific flexural strengths comparable to glass-reinforced grades at lower density. These materials primarily serve industries seeking weight reduction coupled with end-of-life biodegradability or incineration compatibility. Polypropylene composites currently occupy the largest volume share given established automotive interior molding infrastructure, while biodegradable composites represent the fastest-expanding category as Japanese and South Korean electronics brands mandate compostable packaging. Among applications, automotive interiors leads in value terms due to OEM sustainability scorecards, though construction materials is gaining share as India's affordable housing programs specify fiber-cement board alternatives.
Japan's METI enforces stringent automotive recycling directives that mandate recoverable content percentages, directly elevating natural fiber composite specifications in vehicle interiors. India's BIS certification requirements for fiber-reinforced building panels and China's GB standards for indoor air emissions from composite products collectively shape product development priorities and factory certification costs. Stakeholders must monitor how evolving extended producer responsibility frameworks across the region alter material qualification timelines and supplier audit protocols.
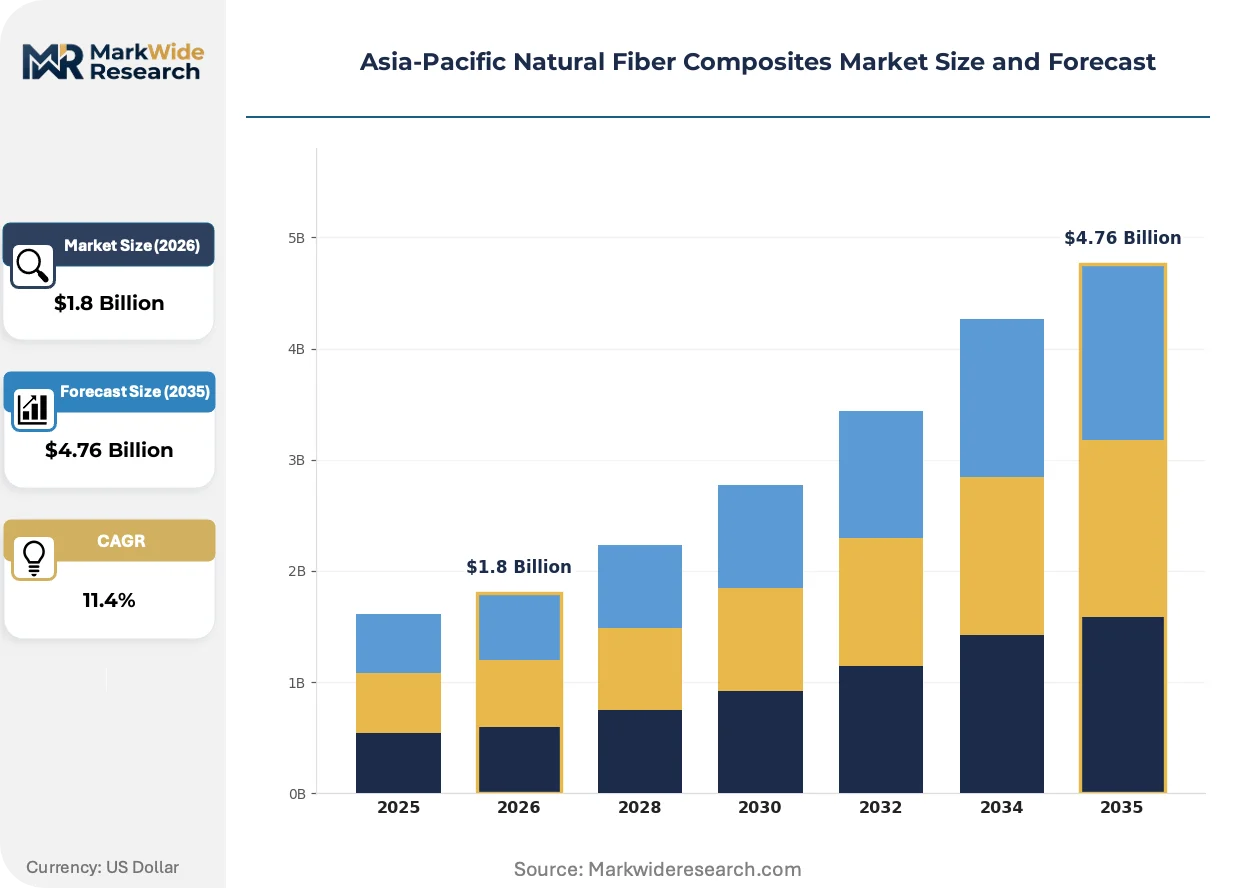
Market Dynamics
Automotive OEM sustainability mandates are compressing material qualification timelines across Asia-Pacific, forcing suppliers to accelerate biocomposite validation cycles while maintaining performance parity with glass-reinforced alternatives.
Growth Catalysts
- India's PLI scheme for advanced materials:Production-linked incentives are expanding domestic bast fiber processing capacity and attracting polymer matrix compounders to establish regional compounding facilities.
- Japan's METI automotive recycling directives:Mandatory recoverable content percentages in vehicle interiors are elevating natural fiber composite specifications across Japanese OEM supply chains.
- Biodegradable resin advancement:Compostable thermoplastic matrices paired with kenaf and hemp reinforcement are penetrating electronics packaging for South Korean and Japanese consumer brands.
Market Restraints
- Jute fiber price volatility:Weather-dependent harvests in Bangladesh and eastern India create input cost instability that undermines long-term supply contracts with automotive tier suppliers.
- China's bast fiber supply concentration:Jilin Chemical Fiber Group controls domestic hemp and flax supply, creating single-source risk for compounders seeking geographic diversification.
- Moisture absorption limitations:Unmodified lignocellulosic fibers exhibit dimensional instability above 8% moisture content, restricting exterior automotive and marine applications.
Strategic Opportunities
- Vietnam's underdeveloped biocomposite base:Absence of domestic bast fiber processing creates first-mover advantage for integrated producers establishing Southeast Asian compounding operations.
- India's affordable housing programs:Government-mandated fiber-cement board alternatives in low-cost construction are opening specification pathways for jute-reinforced building panels.
- Hybrid carbon-natural fiber convergence:Toray Industries' high-performance hybrid offerings demonstrate viable load-bearing applications beyond non-structural automotive trim.
Industry Challenges
- BIS certification timeline compression:India's Bureau of Indian Standards approval for fiber-reinforced building panels requires 14-18 month validation cycles that mismatch construction project schedules.
- Biocomposite molding technician scarcity:Shortage of process engineers experienced in lignocellulosic fiber moisture management and mold flow optimization constrains production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Natural Fiber Composites Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Composites, Polypropylene Composites, Thermoplastic Composites, Biodegradable Composites Application: Automotive Interiors, Construction Materials, Consumer Goods, Sporting Equipment End User: OEMs, Contractors, Manufacturers, Retailers Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Polyvlies Franz Beyer GmbH, Toray Industries Inc, Amorim Cork Composites SA, Flexform Technologies, TECNARO GmbH, Cobra Advanced Composites Co Ltd, UPM-Kymmene Corp, Jilin Chemical Fiber Group Co Ltd, Lanxess AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Natural Fiber Composites Market Trends and Innovations
Digital twin platforms are virtualizing material development workflows across Asia-Pacific biocomposite supply chains, compressing formulation iteration cycles while regulatory mandates accelerate specification turnover.
Hybrid natural-synthetic fiber architectures are virtualizing traditional material selection hierarchies in Japanese automotive engineering. Toray Industries combines carbon fiber with bast fiber reinforcement to achieve specific flexural strength targets at 15-20% lower density than glass-reinforced alternatives. Toyota and Honda interior engineering teams are adopting these hybrids for door panels and seat backs where load-bearing requirements previously excluded pure biocomposites.
China's GB standards for indoor air emissions from composite products are tightening formaldehyde and VOC thresholds for construction applications. The 2024 revisions to GB 18580 and related standards are forcing domestic panel manufacturers to migrate from urea-formaldehyde binders toward bio-based thermoset matrices. Guangdong and Jiangsu province building material suppliers are investing in PLA and PHA matrix compatibility layers to maintain market access.
Japanese electronics brands are compressing packaging supplier qualification cycles from 24 months to 8 months through pre-certified biocomposite material libraries. Sony and Panasonic procurement teams now specify compostable cushioning from approved compounder lists rather than conducting bespoke material validation. This shift is concentrating supply relationships around UPM-Kymmene and domestic Japanese compounders with established biodegradability certification portfolios.
Asia-Pacific Natural Fiber Composites Market Segmentation
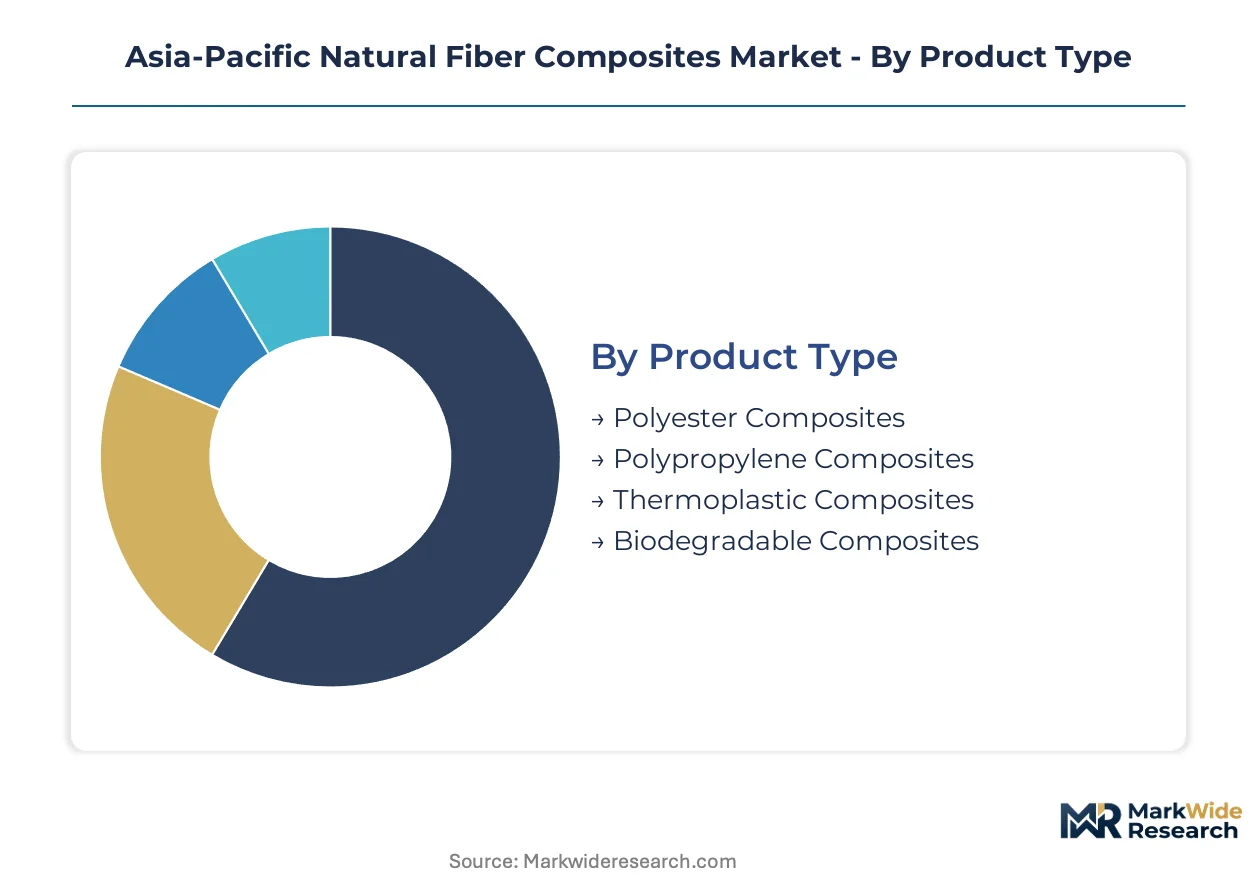
Segmentation in the Asia-Pacific natural fiber composites market reveals how material specifications, end-use requirements, and channel economics fragment supply strategies across automotive, construction, and consumer applications. Understanding these divisions exposes where margin pools concentrate and where specification power sits.
Product Type:
Polypropylene composites anchor volume flows through established automotive interior molding infrastructure, while biodegradable matrices rewrite qualification protocols for Japanese and South Korean electronics brands.
- Polypropylene Composites:Lignocellulosic reinforcement dispersed in PP matrix delivers moldable, lightweight panels with established recycling streams. Toyota and Honda interior programs in Japan specify these for door panels and seat backs where OEM sustainability scorecards mandate recoverable content percentages under METI directives.
- Biodegradable Composites:PLA and PHA matrices paired with kenaf or hemp reinforcement achieve compostability certification for electronics packaging. Sony and Panasonic procurement teams in Japan compress supplier qualification cycles through pre-certified material libraries, concentrating supply relationships around compounders with established biodegradability portfolios.
- Polyester Composites:Thermoset matrices with jute or flax reinforcement serve construction panel applications where fiber-cement board alternatives are gaining specification in India's affordable housing programs.
- Thermoplastic Composites:Engineering-grade matrices enable reprocessing and end-of-life recovery, aligning with China's GB standards for indoor air emissions and circular material flows.
The dominant share belongs to polypropylene composites, while biodegradable composites are gaining share fastest.
Application:
Automotive interiors command premium pricing through OEM sustainability mandates, while construction materials scale through government procurement programs.
- Automotive Interiors:Door panels, seat backs, and trim components where load-bearing requirements previously excluded pure biocomposites now accept hybrid carbon-natural fiber architectures from Toray Industries. Japanese OEM engineering teams adopt these for 15-20% density reduction versus glass-reinforced alternatives.
- Construction Materials:Fiber-cement board alternatives and building panels where India's BIS certification requirements and China's GB 18580 formaldehyde thresholds force migration from urea-formaldehyde binders toward bio-based thermoset matrices.
- Consumer Goods:Electronics packaging and household items where South Korean and Japanese brands mandate compostable cushioning specifications.
- Sporting Equipment:Lightweight structural components where specific flexural strength targets at reduced density justify material cost premiums.
Automotive interiors retains the largest value position, though construction materials is climbing the fastest as India's housing programs scale.
End User:
OEMs wield specification power through sustainability scorecards, while contractors face compressed timelines from certification bottlenecks.
- OEMs:Automotive and electronics manufacturers with direct material qualification teams and 8-24 month validation cycles. Japanese OEMs leverage METI recycling directives to mandate recoverable content percentages, elevating natural fiber composite specifications in vehicle interiors.
- Contractors:Construction firms executing India's affordable housing programs where BIS certification timelines of 14-18 months mismatch project schedules, creating specification friction for fiber-reinforced building panels.
- Manufacturers:Tier suppliers and compounders establishing regional compounding facilities under India's PLI scheme for advanced materials.
- Retailers:Consumer goods channels where electronics packaging specifications flow down from brand owner procurement teams.
OEMs control the dominant specification share, while contractors are expanding procurement fastest as construction applications scale.
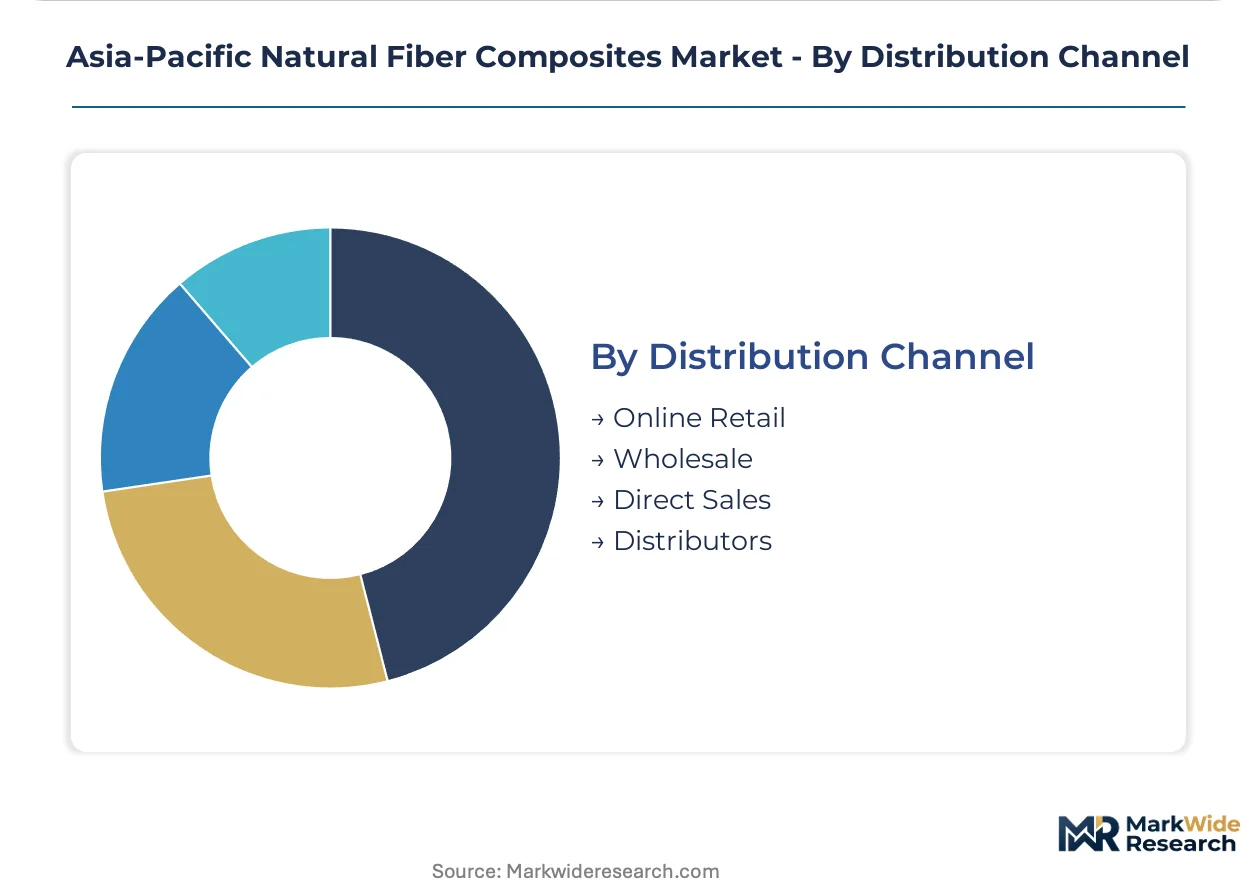
Distribution Channel:
Direct sales capture high-value automotive specifications, while wholesale channels aggregate fragmented construction demand.
- Direct Sales:OEM-facing technical service teams managing material qualification, mold flow optimization, and moisture management protocols for lignocellulosic fiber processing. Toray Industries and Jilin Chemical Fiber Group deploy direct technical resources for automotive and industrial accounts.
- Wholesale:Aggregators serving India's construction sector where fiber-cement board alternatives distribute through regional building material suppliers in Gujarat and Maharashtra.
- Distributors:Regional inventory and technical support for mid-tier manufacturers lacking direct compounder relationships.
- Online Retail:Emerging channel for standardized grades and sample quantities, particularly for biodegradable composite formulations targeting smaller electronics packaging suppliers.
Direct sales holds the dominant share for high-specification applications, while wholesale is expanding most quickly as construction volumes scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bast fiber shipments from Bangladesh and eastern India feed compounders across China and Southeast Asia, creating a procurement corridor that concentrates raw material sourcing in the subcontinent while manufacturing scales in East Asian industrial clusters.
China
Construction panel manufacturers in Guangdong and Jiangsu provinces drive biocomposite demand as GB 18580 standards tighten formaldehyde emissions. MIIT industrial policy directs capital toward bio-based thermoset matrices. The Yangtze River Delta anchors domestic hemp and flax processing through state-backed fiber conglomerates.
Japan
Automotive OEMs specify recoverable content percentages for vehicle interiors under METI recycling directives. Toyota and Honda engineering teams validate hybrid carbon-bast fiber architectures for door panels. The Kanto region surrounding Tokyo concentrates technical compounders serving tier-one supplier networks.
India
Affordable housing programs in Gujarat and Maharashtra specify fiber-cement board alternatives for low-cost construction. BIS certification requirements for building panels create 14-18 month validation cycles. The PLI scheme for advanced materials attracts polymer matrix compounders to establish regional compounding facilities.
South Korea
Electronics brands mandate compostable packaging specifications for consumer goods distribution. Samsung and LG procurement teams compress supplier qualification timelines through pre-certified biocomposite libraries. The Seoul Capital Area hosts compounders specializing in PLA and PHA matrix formulations.
Vietnam
Absence of domestic bast fiber processing creates first-mover opportunity for integrated producers establishing Southeast Asian operations. Foreign direct investment in manufacturing parks near Ho Chi Minh City targets export-oriented automotive component supply. The government offers tax incentives for advanced materials fabrication facilities.
Asia-Pacific Natural Fiber Composites Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Japanese and European multinationals anchor high-specification automotive and electronics segments through direct OEM relationships, while regional compounders serve construction and packaging applications through wholesale distribution. Three archetypes dominate: integrated fiber-to-compound producers, polymer specialists with biocomposite divisions, and pure-play natural fiber compounders. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines compress.
Among integrated fiber producers, Jilin Chemical Fiber Group Co Ltd anchors Chinese domestic bast fiber supply, while Toray Industries Inc exemplifies the hybrid composite specialist archetype serving Japanese automotive OEMs. UPM-Kymmene Corp represents European biocomposite know-how extended into Asia-Pacific packaging applications. These three occupy positions spanning raw material control, high-performance hybrid development, and certified biodegradable formulations.
| Leading Market Players |
|---|
| Polyvlies Franz Beyer GmbH |
| Toray Industries Inc |
| Amorim Cork Composites SA |
| Flexform Technologies |
| TECNARO GmbH |
| Cobra Advanced Composites Co Ltd |
| UPM-Kymmene Corp |
| Jilin Chemical Fiber Group Co Ltd |
| Lanxess AG |
| Others |
Pricing and Supply Chain Analysis
Jilin Chemical Fiber Group's control over Chinese domestic hemp and flax supply concentrates upstream margin capture in bast fiber processing, while compounders downstream compete on formulation value-add and certification speed. Automotive OEMs in Japan and electronics brands in South Korea extract pricing leverage through pre-qualified supplier lists, compressing tier-two margins.
Pricing Analysis
Polypropylene composite formulations anchor current-generation pricing at established automotive interior molding rates, while biodegradable PLA and PHA matrices command next-generation premiums tied to compostability certification. Three-tier pricing structure across certified biodegradable, hybrid carbon-natural fiber, and commodity polypropylene grades separates specification tiers. Cost compression in commodity PP compounds is intensifying because India's PLI scheme attracts new domestic compounders. Automotive OEMs exhibit lowest price sensitivity given sustainability mandate compliance costs, while Indian construction contractors face acute budget constraints under affordable housing program ceilings.
Supply Chain Analysis
Tariff exposure between Bangladesh and India dominates raw material cost planning as weather-dependent jute harvests trigger input volatility. Bast fiber supply concentrates in Bangladesh, eastern India, and China's Jilin province, while compounders cluster in Japan's Kanto region and India's Gujarat. Manufacturing rests on lignocellulosic fiber supply, thermoplastic resin feedstock, and bio-based thermoset chemistry. Single-source vulnerability persists where Jilin Chemical Fiber Group controls domestic Chinese hemp supply. Distribution runs through direct technical sales for automotive specifications and wholesale aggregators for Indian construction panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific natural fiber composites constitute a high-growth materials disruption as Japan's METI automotive recycling directives and India's PLI scheme simultaneously accelerate specification turnover and domestic capacity buildout.
For Market Incumbents: Insulate specification relationships with Japanese OEMs through accelerated biodegradability certification and backward integration into bast fiber preprocessing. Toray Industries' hybrid carbon-natural fiber architecture demonstrates how technical differentiation defends against commodity PP compounders. Priority lever: captive supply of moisture-stabilized fiber grades to lock in automotive interior programs. For New Entrants and Emerging Players: Vietnam's absence of domestic bast fiber processing offers first-mover positioning for integrated compounders targeting export-oriented automotive component supply. Electronics packaging for South Korean brands presents the most penetrable segment given compressed 8-month qualification cycles. Go-to-market angle: pre-certified biodegradable material libraries matching Sony and Panasonic procurement specifications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European biocomposite specialists seeking Asia-Pacific geographic expansion. Long-term viability hinges on 5-10 year regulatory trajectories embedding extended producer responsibility into automotive and construction supply chains. Signal to watch: BIS certification timeline compression in India as validation cycles shorten from 18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bast Fiber Processing | Jilin Chemical Fiber Group's supply control demonstrates margin capture upstream of compounding operations. |
| Biodegradability Certification Investment | PLA and PHA matrix approvals unlock Sony and Panasonic electronics packaging procurement lists. |
| Hybrid Composite R&D Partnership | Toray Industries' carbon-bast fiber architectures expand load-bearing applications beyond non-structural trim. |
| Regional Compounding Facility Expansion | India's PLI scheme attracts polymer matrix compounders to Gujarat and Maharashtra industrial corridors. |
| Pre-Certified Material Library Development | Japanese electronics brands compress supplier qualification cycles through approved compounder lists. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automotive tier supplier procurement managers, biocomposite compounder technical directors, and BIS certification consultants; and secondary validation through MIIT industrial policy documents, METI recycling directive filings, and India PLI scheme implementation records. Bottom-up triangulation across fiber processing capacity, compounding facility utilization, and end-use specification pipelines anchored volume estimates. Top-down cross-checks applied customs trade data for lignocellulosic fiber shipments and automotive interior component import flows.
Forecast inputs considered product type segmentation across polypropylene, biodegradable, polyester, and thermoplastic composite matrices; application segmentation spanning automotive interiors, construction materials, consumer goods, and sporting equipment; and end-user segmentation distinguishing OEM direct procurement from contractor wholesale channels. CAGRs derived from regression analysis of historical specification adoption curves and regulatory mandate implementation timelines. Industry-specific inputs included BIS certification queue lengths and METI recoverable content percentage phase-in schedules.
Practitioners should monitor jute harvest variability in Bangladesh, GB standard revision cycles in China, and PLI scheme beneficiary announcements in India for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Polyurethane Composites Market
Composite Materials
United States Marine Composites Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Lightweight Materials Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Europe Marine Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Global Sports Composites Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market