
 Medical Composite Material Market | 2026-2036
Medical Composite Material Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Composite Material Market Analysis
ISO 10993 biocompatibility certification is bifurcating the competitive landscape into qualified suppliers and aspirants. SGL Carbon SE leverages its carbon fiber expertise to anchor supply relationships with orthopedic implant OEMs. Owens Corning sustains scale advantages in glass fiber substrates that feed dental and cardiovascular device production.
Medical composite materials are engineered combinations of two or more constituent materials with distinct physical or chemical properties, typically pairing a polymer matrix such as PEEK or PEKK with reinforcing fibers like carbon, glass, or bioactive ceramics to achieve specific strength-to-weight ratios, radiolucency, or osteoconductivity for implantable and procedural devices. Thermoplastic composites dominate current volume due to their melt-processability and recyclability in injection molding workflows, while biocomposites represent the fastest-expanding margin pool as regulators and hospitals prioritize resorbable and bioactive formulations that eliminate secondary removal surgeries. 3D printing technology is displacing conventional subtractive methods in patient-specific orthopedic and dental applications, though filament winding retains cost advantages for high-volume tubular cardiovascular grafts.
The FDA enforces biocompatibility and mechanical performance standards through ISO 10993 and ASTM F2077 testing protocols, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence requirements for implantable composites. Japan's PMDA applies JIS T 0301 standards that create additional localization burdens for foreign suppliers. Stakeholders must monitor evolving regulatory divergence between major jurisdictions to avoid redundant qualification cycles that erode product development timelines.
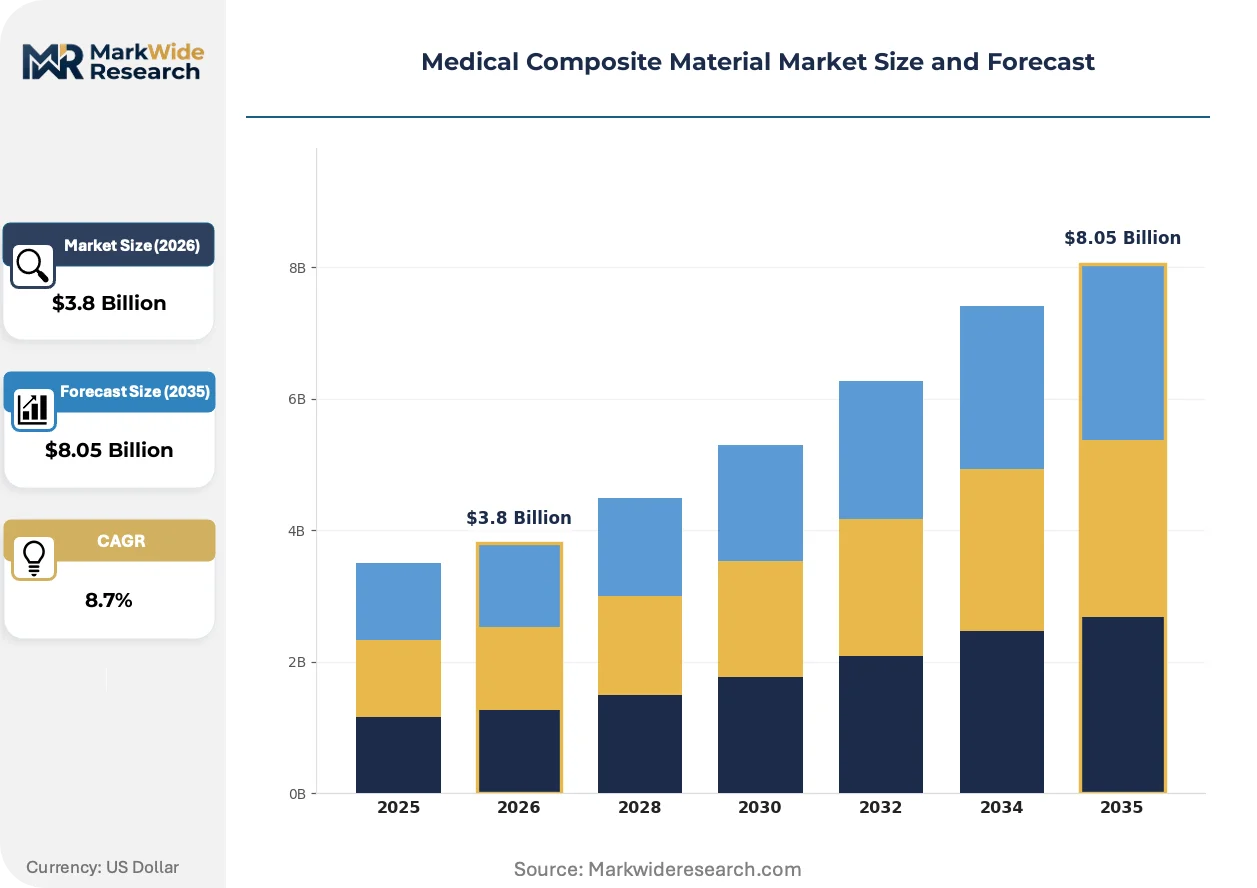
Market Dynamics
Fiber-reinforced biocomposites are displacing metal alloys in permanent dental restorations, while the FDA's tightened ISO 10993 qualification pathways are filtering supplier bases and extending product development timelines for implantable devices.
Growth Catalysts
- Biocompatibility Mandates:The FDA's updated guidance on long-term implantable devices elevates certified composite suppliers. OEMs in Baden-Württemberg's orthopedic clusters prioritize pre-qualified material sources to accelerate regulatory submissions.
- Carbon Fiber Expertise Migration:Aerospace-grade carbon fiber producers are transferring technical capabilities to medical implant applications. SGL Carbon SE anchors supply relationships with orthopedic device manufacturers seeking radiolucent structural components.
- 3D Printing Filament Demand:Patient-specific orthopedic and dental workflows require specialized PEEK and PEKK composite filaments. Precision dental labs in Germany drive concentrated consumption of melt-processable thermoplastic formulations.
Market Restraints
- PEEK Resin Price Volatility:Medical-grade polyetheretherketone supply concentrates among a limited producer base. Input cost fluctuations compress margin pools for composite processors serving price-sensitive cardiovascular graft segments.
- Qualification Timeline Burden:ISO 10993 and ASTM F2077 testing protocols extend material approval cycles. Smaller composite suppliers face capital barriers to sustaining multi-year biocompatibility certification programs.
- Titanium Alloy Substitution:Established orthopedic implant manufacturers retain legacy machining infrastructure for metal components. Switching costs and surgeon familiarity slow composite penetration in load-bearing structural applications.
Strategic Opportunities
- Resorbable Biocomposite Formulations:Elimination of secondary removal surgeries aligns with hospital cost-containment priorities. Bioactive ceramic-polymer combinations represent underdeveloped margin pools in pediatric and trauma fixation segments.
- Japan Localization Pathways:PMDA's JIS T 0301 standards create qualification barriers that favor early-entrant composite suppliers. Foreign material producers establishing domestic testing partnerships capture preferential access to Nippon medical device OEMs.
- Continuous Fiber 3D Printing:Convergence of automated fiber placement with additive manufacturing enables anisotropic strength tailoring. Patient-specific orthopedic implants with optimized fiber orientation challenge subtractive machining economics.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:ISO 10993-qualified toxicologists and materials scientists command premium compensation. Composite suppliers compete with pharmaceutical and broader medical device sectors for limited regulatory expertise.
- Multi-Jurisdiction Certification Redundancy:Divergent FDA, EMA MDR, and PMDA evidence requirements force parallel qualification tracks. Product development timelines extend as stakeholders navigate non-harmonized biocompatibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Composite Material Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocomposites, Thermoplastic Composites, Reinforced Composites, Bio-based Composites Application: Orthopedics, Dental, Cardiovascular, Tissue Engineering End User: Hospitals, Research Institutions, Clinics, Medical Device Manufacturers Technology: 3D Printing, Injection Molding, Vacuum Infusion, Filament Winding |
| Companies Covered | SGL Carbon SE, Owens Corning, 3M Company, Composiflex Inc., Zeus Industrial Products Inc., Toray Industries Inc., Dentsply Sirona, Kulzer GmbH, Royal DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Composite Material Market Emerging Trajectories
Manufacturing automation and regulatory digitization are compressing development cycles, while material science advances enable functional gradients that match native tissue mechanical properties.
Continuous fiber 3D printing is displacing conventional subtractive machining in patient-specific orthopedic implant production. German precision dental labs and orthopedic device manufacturers in Baden-Württemberg are adopting melt-extrusion systems for PEEK and PEKK composites at accelerating rates. This technology is displacing five-axis CNC workflows by enabling topology-optimized structures with anisotropic strength distribution and reduced material waste.
The EU Medical Device Regulation mandates enhanced clinical evidence requirements for implantable composites through CE marking pathways. Strontium-substituted bioactive glass fiber suppliers face expanded post-market surveillance obligations and notified body audit intensification. Cardiovascular graft manufacturers with legacy product portfolios are most affected, responding with systematic clinical data generation programs and quality management system upgrades.
Hospital procurement departments are consolidating composite material suppliers around certified tier-one sources with integrated testing capabilities. German university hospital networks and orthopedic specialty clinics are displacing fragmented multi-vendor arrangements with preferred supplier frameworks. This concentration is most visible in Baden-Württemberg's integrated care regions, where standardized composite specifications reduce incoming inspection burdens and streamline inventory management.
Medical Composite Material Market Segmentation
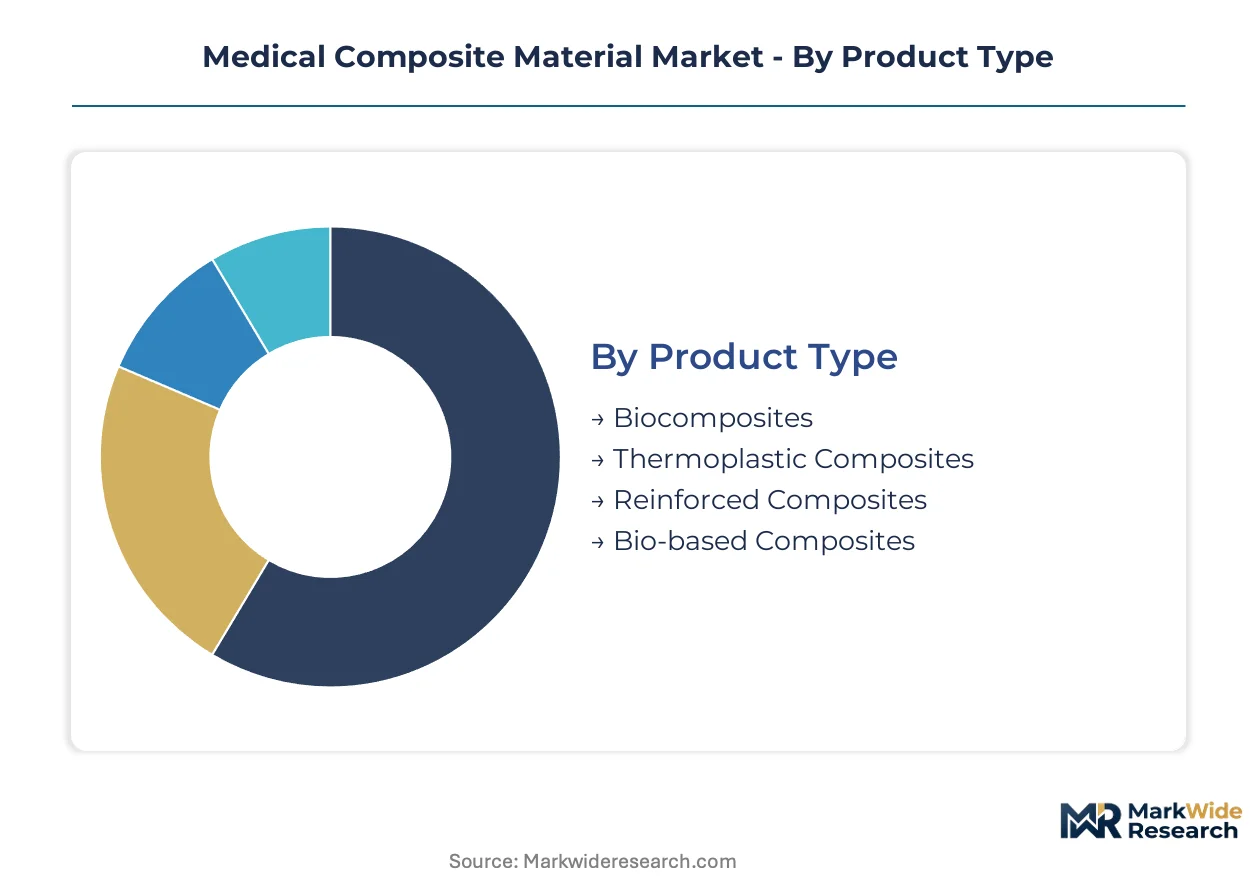
Segmentation in medical composites reveals how material specifications, processing technologies, and end-use requirements fragment supply relationships. Manufacturers configure product portfolios around regulatory qualification pathways rather than commodity scale, concentrating margin capture in certified formulations for permanent implantables.
Product Type:
Margin pools concentrate in formulations that eliminate secondary surgeries and satisfy tightened biocompatibility mandates.
- Biocomposites:Bioactive ceramic-polymer matrices enable resorbable fixation devices that dissolve as tissue regenerates. German pediatric trauma centers and Baden-Württemberg orthopedic clusters drive specialized procurement of strontium-substituted formulations that accelerate bone ingrowth.
- Thermoplastic Composites:PEEK and PEKK matrices with carbon or glass reinforcement dominate load-bearing permanent implants due to melt-processability and radiolucency. Precision dental labs in Germany favor these materials for permanent restorations requiring repeated sterilization cycles.
- Reinforced Composites:Continuous fiber architectures deliver anisotropic strength for structural orthopedic components.
- Bio-based Composites:Polylactic acid and cellulose-derived matrices serve temporary fixation and suture anchor applications with lower regulatory burden.
The dominant share belongs to Thermoplastic Composites, while Biocomposites are gaining share fastest as hospitals prioritize elimination of removal surgeries.
Application:
Volume scales with procedure frequency, but value concentrates in applications demanding permanent implantation and radiolucent imaging compatibility.
- Orthopedics:Spinal fusion cages, trauma plates, and joint replacement components require fatigue-resistant carbon fiber-PEEK constructs. German orthopedic device manufacturers in Baden-Württemberg specify these materials for load-bearing applications where metal artifact reduction improves post-operative imaging.
- Dental:Fiber-reinforced posts, bridges, and implant abutments demand aesthetic color-matching and biocompatibility certification. German precision dental labs accelerate adoption of biocomposite permanent restorations as metal-free alternatives gain patient preference.
- Cardiovascular:Vascular grafts and structural heart components utilize filament-wound or braided fiber architectures.
- Tissue Engineering:Scaffolds for bone and cartilage regeneration employ resorbable bioactive glass and collagen-polymer hybrids.
Orthopedics commands the dominant revenue position, though Dental applications are expanding most quickly as fiber-reinforced biocomposites displace metal alloys in restorative procedures.
End User:
Procurement sophistication varies sharply across customer types, with integrated hospital networks consolidating supplier relationships around certified tier-one sources.
- Hospitals:German university hospital networks and orthopedic specialty clinics in Baden-Württemberg implement preferred supplier frameworks that standardize composite specifications and reduce incoming inspection burdens.
- Medical Device Manufacturers:OEMs anchor supply relationships with pre-qualified material sources to accelerate FDA and CE marking submissions for long-term implantable devices.
- Research Institutions:Academic medical centers and biodesign laboratories prototype patient-specific implants using 3D printing filaments.
- Clinics:Ambulatory surgical centers and private dental practices source standardized restorations through dental lab intermediaries.
Medical Device Manufacturers retain the largest procurement volume, while Hospital networks are consolidating purchasing fastest through integrated care region standardization.
Technology:
Processing method selection determines fiber architecture control, surface finish quality, and economic viability across production scales.
- 3D Printing:Fused filament fabrication with PEEK and PEKK composites enables topology-optimized patient-specific implants with anisotropic strength distribution. German orthopedic device manufacturers adopt melt-extrusion systems to displace five-axis CNC workflows and reduce material waste.
- Filament Winding:Automated fiber placement produces cost-efficient tubular cardiovascular grafts with circumferential reinforcement. High-volume production of vascular prostheses retains this method despite additive manufacturing advances.
- Injection Molding:Short-fiber thermoplastic composites serve high-volume disposable and semi-durable device housings.
- Vacuum Infusion:Resin transfer molding accommodates large-format fiber preforms for external fixation and bracing applications.
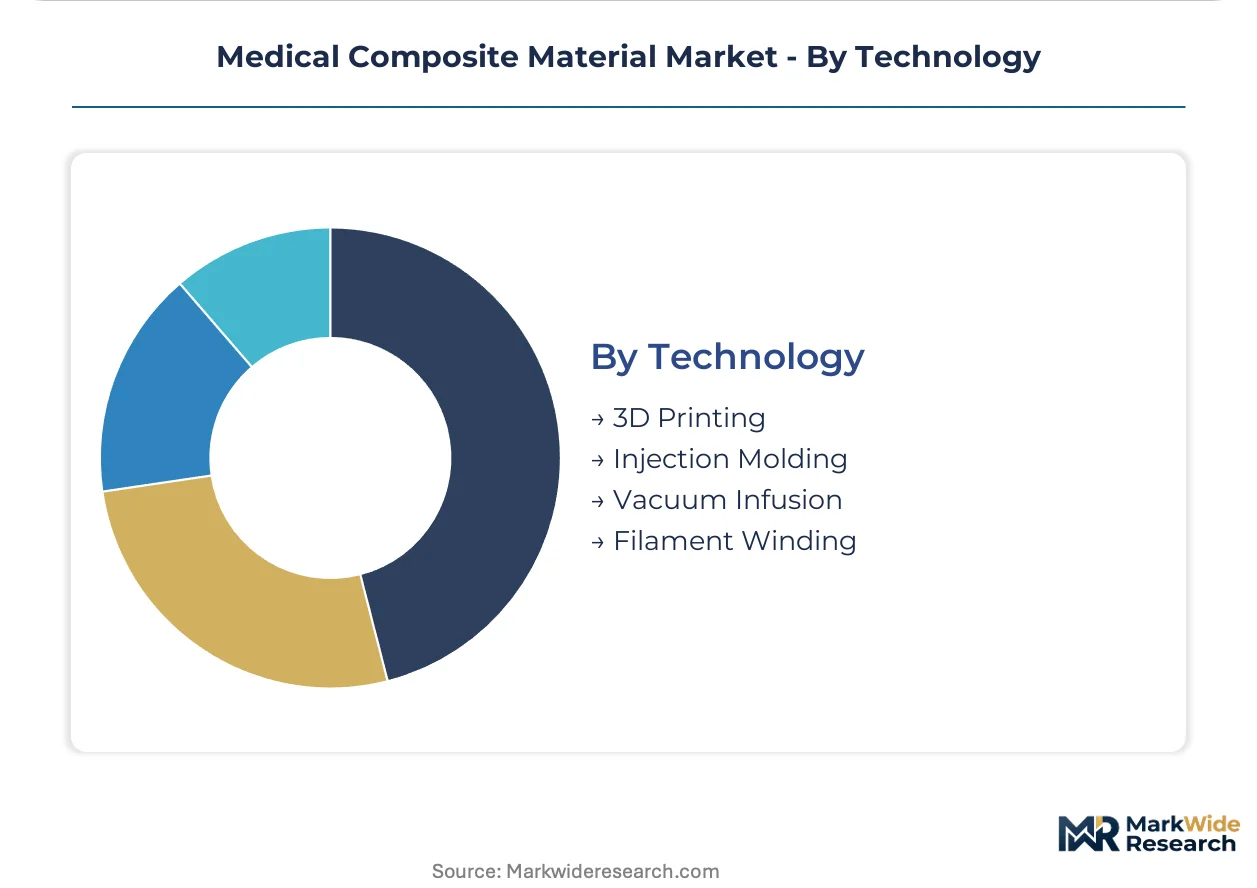
Injection Molding maintains the broadest installed base, yet 3D Printing is climbing the fastest as patient-specific orthopedic and dental workflows expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for domestic medical device manufacturing are redirecting composite procurement flows across major economies. National regulators are tightening biocompatibility frameworks that favor pre-qualified local suppliers. Industrial clusters in precision dentistry and orthopedic devices concentrate specialized composite consumption in specific metropolitan regions.
United States
FDA's updated ISO 10993 guidance for long-term implantables is elevating certified composite suppliers. The agency's biocompatibility testing protocols extend material qualification timelines. Medical device manufacturers in the Minneapolis-St. Paul corridor and Boston-Cambridge cluster anchor supply relationships with pre-qualified carbon fiber-PEEK sources to accelerate regulatory submissions.
Germany
Baden-Württemberg's orthopedic device manufacturers drive concentrated demand for radiolucent structural components. The EU Medical Device Regulation mandates enhanced clinical evidence requirements through CE marking pathways. Precision dental labs in Stuttgart and Freiburg accelerate adoption of fiber-reinforced biocomposites as metal-free alternatives gain patient preference.
Japan
PMDA's JIS T 0301 standards create qualification barriers that favor early-entrant composite suppliers. The regulator's localization requirements for foreign medical materials force parallel testing partnerships. Orthopedic device OEMs in the Osaka-Kobe manufacturing belt prioritize domestic-certified PEEK composite sources to streamline approval timelines.
China
NMPA's updated biocompatibility standards for implantable devices are filtering supplier bases. The regulator's emphasis on domestic clinical evidence generation extends product registration cycles. Medical device clusters in Suzhou and Shenzhen are consolidating composite procurement around tier-one suppliers with integrated ISO 10993 testing capabilities.
Switzerland
Swissmedic's stringent post-market surveillance requirements for implantable composites concentrate procurement among certified suppliers. The regulator's quality management system audits favor integrated material-device manufacturers. Precision dental and orthopedic device specialists in the Lake Geneva region and Basel area standardize specifications to reduce incoming inspection burdens.
Medical Composite Material Market Vendor Landscape
Player mix skews toward specialized fiber-reinforced composite manufacturers with aerospace-grade carbon fiber expertise. The competitive structure bifurcates between large-scale glass fiber substrate producers and niche medical-grade thermoplastic compounders. Strategic archetypes include certified biocompatibility specialists, integrated polymer-fiber compounders, and patient-specific additive manufacturing enablers. Dominant competitive moves center on regulatory qualification partnerships and capacity expansion for medical-grade PEEK resin processing.
Among German-based carbon fiber specialists, SGL Carbon SE exemplifies the aerospace-to-medical capability migration archetype. Owens Corning represents the scale-driven glass fiber substrate tier that feeds dental and cardiovascular device production. Toray Industries Inc. occupies a position within the integrated polymer-fiber compounder segment, anchoring supply relationships through materials science breadth rather than medical specialization alone.
| Leading Market Players |
|---|
| SGL Carbon SE |
| Owens Corning |
| 3M Company |
| Composiflex Inc. |
| Zeus Industrial Products Inc. |
| Toray Industries Inc. |
| Dentsply Sirona |
| Kulzer GmbH |
| Royal DSM N.V. |
| Others |
Supply Flow & Price Mechanics
Fiber-reinforced biocomposites displacing titanium alloys in orthopedic load-bearing applications simultaneously shift procurement geography toward Baden-Württemberg's certified supplier clusters and compress pricing power for legacy metal processors. This substitution dynamic concentrates margin capture among ISO 10993-qualified compounders while forcing price realignment across implantable device supply chains.
Pricing Analysis
Certification level (ISO 10993/FDA-grade/CE-marked) creates the primary spread between premium and standard tiers, with medical-grade PEEK resin commanding substantial premiums over industrial grades. Pricing stratifies across pre-qualified, certified-in-process, and uncertified material tiers, with German university hospital networks and orthopedic OEMs showing lowest price sensitivity for permanent implantables. Cost compression in cardiovascular graft segments intensifies as PEEK resin supply concentrates among limited producers, while dental restoration buyers retain moderate sensitivity due to lab intermediary pricing power.
Supply Chain Analysis
Strategic stockpiling of medical-grade PEEK resin dominates inventory strategy among German orthopedic device manufacturers facing qualification timeline risks. Raw material supply draws from Germany, Japan, and the United States for carbon fiber substrates and specialized thermoplastic resins. Single-source vulnerability concentrates in aerospace-grade carbon fiber feedstocks originally developed for defense applications. Distribution runs through direct mill relationships for high-volume OEMs and specialized medical distributors for precision dental labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
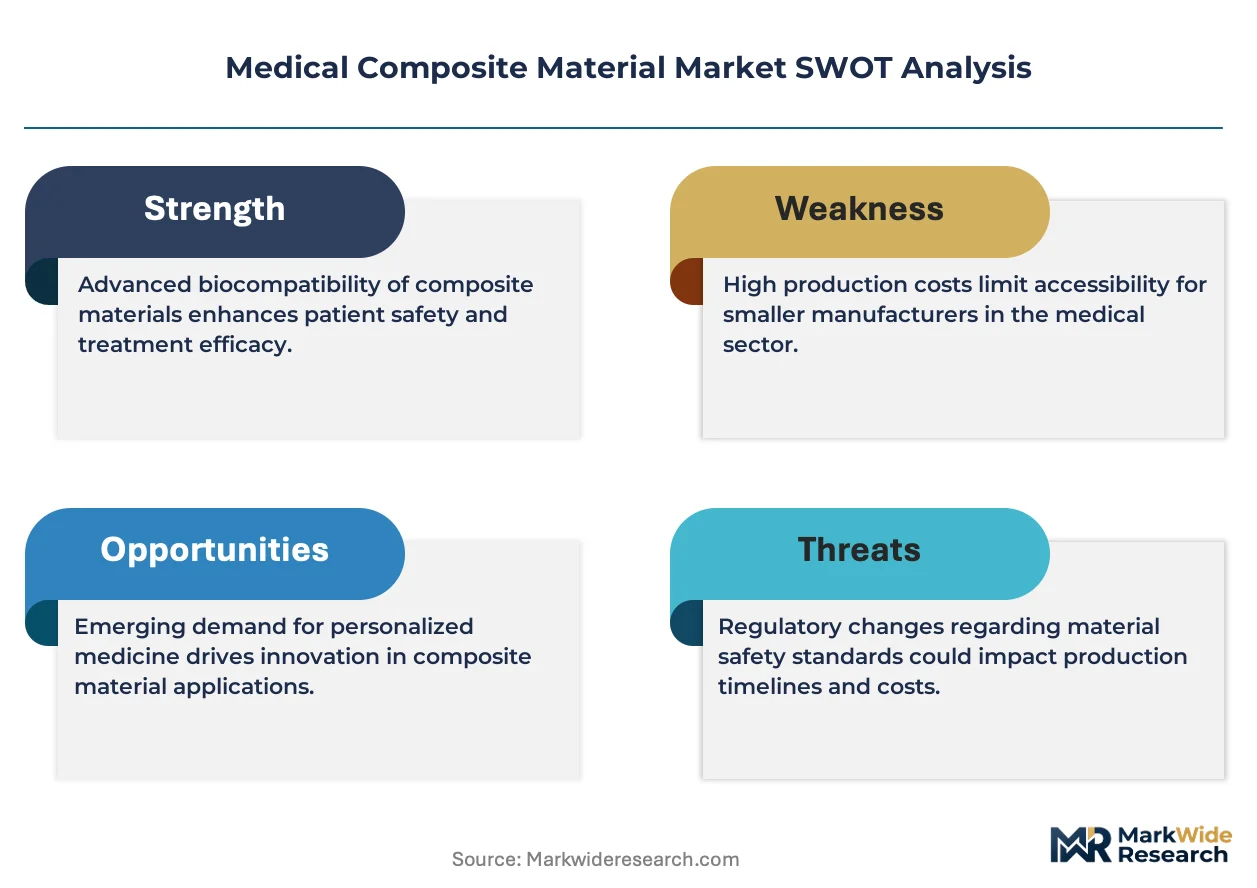
Titanium alloy substitution threatens incumbent composite suppliers in structural orthopedic applications, requiring active defense of radiolucency and fatigue-resistance value propositions. Incumbents must navigate surgeon familiarity barriers and legacy machining infrastructure lock-in.
For Market Incumbents: Consolidate certification asset depth by acquiring ISO 10993-qualified testing capabilities or partnerships, eliminating qualification timeline disadvantages against aerospace-grade carbon fiber migrants. Anchor supply relationships through backward integration into medical-grade PEEK resin processing, capturing margin pools currently concentrated among limited polymer producers. Defend against titanium substitution by co-developing patient-specific implant workflows with Baden-Württemberg orthopedic clusters.
For New Entrants and Emerging Players: FDA Breakthrough Device Designation fast-tracks offer accelerated regulatory pathways for resorbable biocomposite formulations in pediatric trauma fixation. Target Germany's precision dental labs with metal-free permanent restoration solutions, leveraging patient preference shifts and lower regulatory burden versus orthopedic implants. Pursue white-label filament supply partnerships with 3D printing system OEMs serving patient-specific orthopedic workflows.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aerospace carbon fiber specialists seeking medical diversification. Five-to-ten year viability hinges on regulatory qualification moat sustainability and resorbable formulation pipeline depth. Watch FDA guidance harmonization with EU MDR as inflection indicator for multi-jurisdiction certification cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Investment | Biocompatibility testing capabilities differentiate qualified suppliers from capital-constrained aspirants in implantable segments. |
| Backward Integration into PEEK Resin | Captive polymer supply insulates margin pools from medical-grade resin price volatility and limited producer concentration. |
| 3D Printing Filament Partnership | Specialized PEEK and PEKK composite filament supply relationships anchor patient-specific orthopedic workflow adoption. |
| Japan Localization Partnership | PMDA JIS T 0301 testing collaborations streamline approval timelines for Nippon medical device OEM access. |
| Resorbable Biocomposite R&D | Bioactive ceramic-polymer formulations eliminate secondary removal surgeries, aligning with hospital cost-containment priorities. |
Methodological Framework
The analysis maps thermoplastic composites, biocomposites, reinforced composites, and bio-based composites, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at orthopedic and dental device OEMs. Primary interview findings triangulate against FDA 510(k) filings, EMA CE marking databases, hospital procurement contract disclosures, and trade flow data for carbon fiber and PEEK resin imports. Bottom-up segment sizing reconciles with top-down market aggregation across material type, application, end user, and processing technology dimensions.
Consistency checks validate volume and value outputs against external benchmarks including medical device production indices, composite materials trade associations, and regulatory submission trend data. The analytical framework models demand across product type, application, end user archetype, and processing technology segments throughout the forecast period. CAGRs derive from procedure volume projections, material substitution elasticity estimates, and pricing trajectory assumptions for medical-grade resin inputs. Patient-specific 3D printing adoption curves and resorbable formulation regulatory approval timelines inform segment-specific growth differentials.
Underlying assumptions cover ISO 10993 harmonization stability, PEEK resin supply concentration persistence, and surgeon training adoption rates for composite implants, with deviation risk concentrated in regulatory divergence between FDA and EU MDR frameworks. Revision becomes warranted when titanium alloy price compression or breakthrough resorbable material approvals cross threshold adoption rates in load-bearing applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Hybrid Composites Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Global Composite Resin Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Tow Prepreg Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Composite Coatings Market