
 Asia-Pacific Molded FRP Grating Market | 2026-2036
Asia-Pacific Molded FRP Grating Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Molded FRP Grating Market Outlook
Water treatment facilities and food processing units are reorganizing procurement priorities toward corrosion-resistant infrastructure, displacing traditional steel grating in coastal and chemically aggressive environments. AGC Matex leverages its regional manufacturing footprint to serve Japanese industrial standards. Jiangyin Runlin anchors supply to Chinese chemical park expansions along the Yangtze River Delta. Zhongsheng FRP competes on custom fabrication capabilities for platform assemblies in offshore applications.
Asia-Pacific molded FRP grating consists of fiberglass-reinforced plastic panels formed through open-mold or closed-mold processes with typical resin content of 35-65% by weight, delivering strength-to-weight ratios exceeding steel at one-quarter the density for load-bearing industrial surfaces. Anti-slip grating commands premium positioning due to embedded quartz or aluminum oxide surfaces required in offshore oil and food processing safety protocols. Vinylester resin formulations capture expanding share in chemical plant applications where sulfuric acid and chlorine exposure degrades polyester alternatives. Custom grating generates concentrated margin pools where project-specific cutouts, fire-retardant additives, and color-coded safety zones justify engineering surcharges.
China's SAMR enforces GB standards for flame spread and smoke density in industrial composites, while Japan's METI promotes low-carbon material substitution through procurement guidelines for public infrastructure. India's BIS certification requirements for load-bearing plastics are tightening market access for uncatalogued suppliers. Buyers must track regulatory divergence between national standards regimes when specifying resin systems and fire performance ratings across multi-country project portfolios.
Market Dynamics
Corrosion-driven infrastructure replacement across Southeast Asian chemical processing clusters is compressing procurement cycles and elevating specification stringency for resin-grade compliance.
Growth Catalysts
- GB Standards Enforcement:China's SAMR mandates flame-spread and smoke-density testing for industrial composites, forcing asset owners to upgrade legacy steel platforms in Yangtze River Delta chemical parks.
- Offshore Oil Expansion:Anti-slip grating with embedded quartz surfaces captures procurement priority from drill platform operators facing OSHA-equivalent safety protocols across Australian and Malaysian waters.
- Vinylester Formulation Advances:Sulfuric acid and chlorine exposure tolerance in chemical plant environments is displacing polyester resin specifications in India's Gujarat petrochemical corridor.
Market Restraints
- Raw Material Concentration:Glass fiber roving supply concentrates in Chinese state-owned enterprises, exposing fabricators to input volatility when export quotas tighten.
- Technical Performance Ceiling:Load-bearing deflection limits at elevated temperatures restrict molded FRP grating deployment in steel mill walkway retrofits above 120°C continuous service.
- Regulatory Divergence:India's BIS certification timelines for load-bearing plastics extend 14-18 months, freezing market access for uncatalogued resin system suppliers.
Strategic Opportunities
- Water Treatment Infrastructure:Secondary clarifier platforms and odor-control covers in Thailand and Vietnam represent underpenetrated demand as municipal budgets expand corrosion-resistant asset replacement.
- Food Processing Modernization:HACCP-aligned facility upgrades across Indonesian seafood processing clusters create specification openings for color-coded safety zone grating with embedded antimicrobial additives.
- Dual Carbon Policy Tailwind:China's MEE low-carbon material substitution guidelines incentivize FRP grating procurement in state-owned enterprise infrastructure tenders versus energy-intensive steel alternatives.
Industry Challenges
- Resin Chemistry Expertise Gap:Formulation engineers capable of matching vinylester cure profiles to tropical humidity conditions remain scarce across Southeast Asian fabrication facilities.
- Fire Certification Complexity:Project-specific ASTM E-84 and GB 8624 testing requirements force batch-level documentation that extends order-to-delivery timelines by 6-10 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Molded FRP Grating Market |
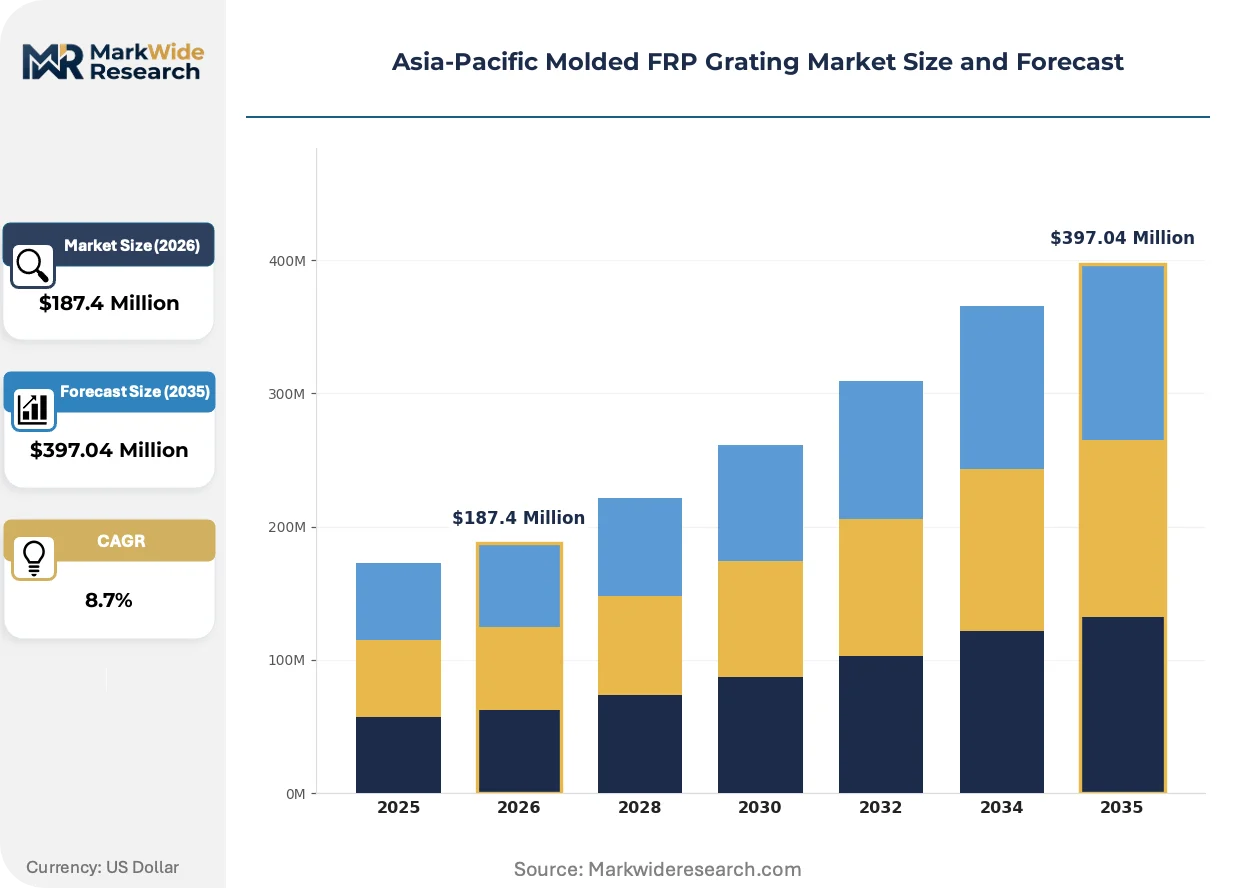
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Grating, Square Grating, Custom Grating, Anti-slip Grating Application: Industrial Flooring, Walkways, Drain Covers, Platforms Material: Polyester, Vinylester, Epoxy, Phenolic End User: Chemical Plants, Water Treatment Facilities, Oil & Gas Industry, Food Processing Units |
| Companies Covered | Strongwell Corporation, Fibergrate Composite Structures, Bedford Reinforced Plastics, AGC Matex, Meiser Grating, Liberty Pultrusions, Jiangyin Runlin, Shanghai Sunoff, Zhongsheng FRP, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Molded FRP Grating Market Strategic Shifts
Material science advances and specification convergence between offshore safety protocols and chemical plant corrosion standards are compressing product development cycles across regional supply chains.
Pultruded FRP grating is supplanting molded alternatives in offshore platform mezzanine applications where span capabilities exceed 1.5 meters without intermediate support. North Sea and Timor Sea operators specify pultruded I-bar profiles for drilling module walkways, enabling modular platform designs that reduce installation man-hours by eliminating steel welding requirements. This structural shift is supplanting traditional steel procurement in brownfield platform expansions where weight reduction translates directly to topside capacity gains.
Japan's METI energy efficiency procurement guidelines now mandate lifecycle carbon assessment for public infrastructure materials, including industrial flooring systems in port and wastewater treatment facilities. The framework requires disclosure of embodied carbon per square meter of installed grating, favoring suppliers with verified resin sourcing and regional manufacturing footprints. Municipal buyers in Osaka Bay industrial zones are responding by specifying domestic-fabricated FRP products with JIS-compliant fire performance ratings over imported alternatives.
Engineering-procurement-construction firms are consolidating vendor panels to single-source FRP grating suppliers capable of delivering cut-to-size platform assemblies with integrated fire-retardant additives and color-coded safety demarcation. This consolidation displaces fragmented local fabrication networks in Indian chemical park developments, where project owners now demand turnkey module delivery including structural calculations and installation supervision. The pattern is most visible in Dahej and Mundra port complexes, where EPC contractors face liquidated damages clauses for schedule overruns.
Asia-Pacific Molded FRP Grating Market Segmentation
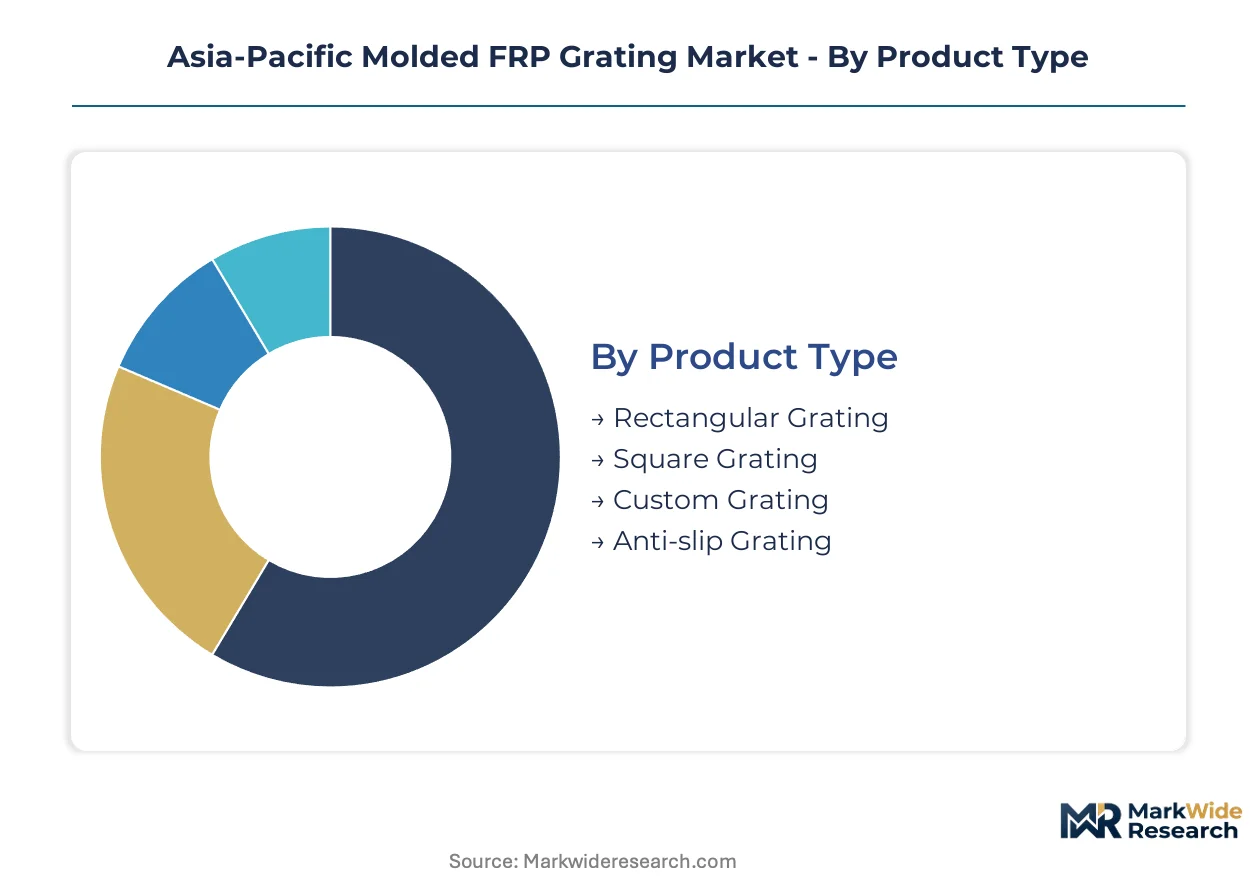
Segmentation in the Asia-Pacific molded FRP grating market reveals how resin chemistry, load-bearing geometry, and end-use corrosion exposure dictate procurement patterns across chemical corridors and offshore installations. Buyers specify product categories against project-specific compliance regimes rather than interchangeable commodity sourcing.
Product Type:
Domestic fabrication capacity in China and Japan concentrates on standardized rectangular and square profiles for chemical park volume contracts, while export-led demand from Australian offshore operators and Indian EPC contractors pulls custom and anti-slip configurations.
- Rectangular Grating:Open-molded panels with 38mm or 50mm bearing bar spacing dominate procurement for chemical plant trench covers and secondary containment walkways. Dahej and Mundra port complexes in Gujarat specify rectangular profiles for modular platform assemblies where span requirements stay below 1.2 meters.
- Anti-slip Grating:Embedded quartz or aluminum oxide surfaces deliver coefficient of friction ratings exceeding 0.6 for drill platform operators across Malaysian and Australian waters. METI procurement guidelines for port infrastructure in Osaka Bay now mandate documented slip resistance testing for public facility tenders.
- Square Grating:Uniform mesh geometry suits food processing washdown environments where drainage efficiency and hose-directed cleaning compatibility matter.
- Custom Grating:Project-specific cutouts, fire-retardant additives, and color-coded safety zones command engineering surcharges from EPC contractors consolidating vendor panels in Indian chemical park developments.
Rectangular grating commands the established base. The steepest expansion runs through anti-slip configurations.
Application:
Cost tiering separates specification-intensive platform assemblies from commodity drain cover replacements, with premium engineering concentrated in offshore mezzanine structures.
- Platforms:Load-bearing surfaces supporting equipment maintenance access in chemical plants and offshore modules require deflection calculations and resin-grade documentation. Pultruded alternatives increasingly displace molded grating where spans exceed 1.5 meters in Timor Sea drilling expansions.
- Industrial Flooring:Continuous surface coverage in corrosive process areas drives volume demand across Yangtze River Delta chemical parks upgrading to GB 8624 flame-spread compliance.
- Walkways:Elevated personnel access routes in water treatment clarifiers and odor-control structures represent underpenetrated replacement demand as Thai and Vietnamese municipal budgets expand.
- Drain Covers:Standardized trench and sump covers in food processing HACCP-aligned facilities specify antimicrobial resin additives for Indonesian seafood processing clusters.
Platform applications absorb the highest engineering margins. Drain covers represent the most price-sensitive volume tier.
Material:
Vinylester formulations are climbing the fastest as sulfuric acid and chlorine exposure tolerance displaces polyester specifications, while phenolic chemistry remains confined to specialized fire-performance applications.
- Vinylester:Superior chemical resistance against strong acids and oxidizing agents positions this resin for Gujarat petrochemical corridor procurement where process streams degrade polyester alternatives. Formulation engineers capable of matching cure profiles to tropical humidity conditions remain scarce across Southeast Asian fabrication facilities.
- Polyester:General-purpose isophthalic and orthophthalic formulations serve cost-sensitive water treatment and food processing applications with moderate chemical exposure.
- Epoxy:High-strength formulations with elevated temperature tolerance target specialized industrial flooring above 80°C continuous service where polyester deflection limits apply.
- Phenolic:Inherent fire-retardant properties without additive loading satisfy ASTM E-84 Class A and GB 8624 requirements for offshore platform living quarters and evacuation routes.
Polyester retains the volume base. Vinylester captures the steepest share gains.
End User:
Customer type segmentation tracks regulatory divergence, with chemical plants and oil and gas operators facing the most stringent resin-grade and fire-performance certification requirements.
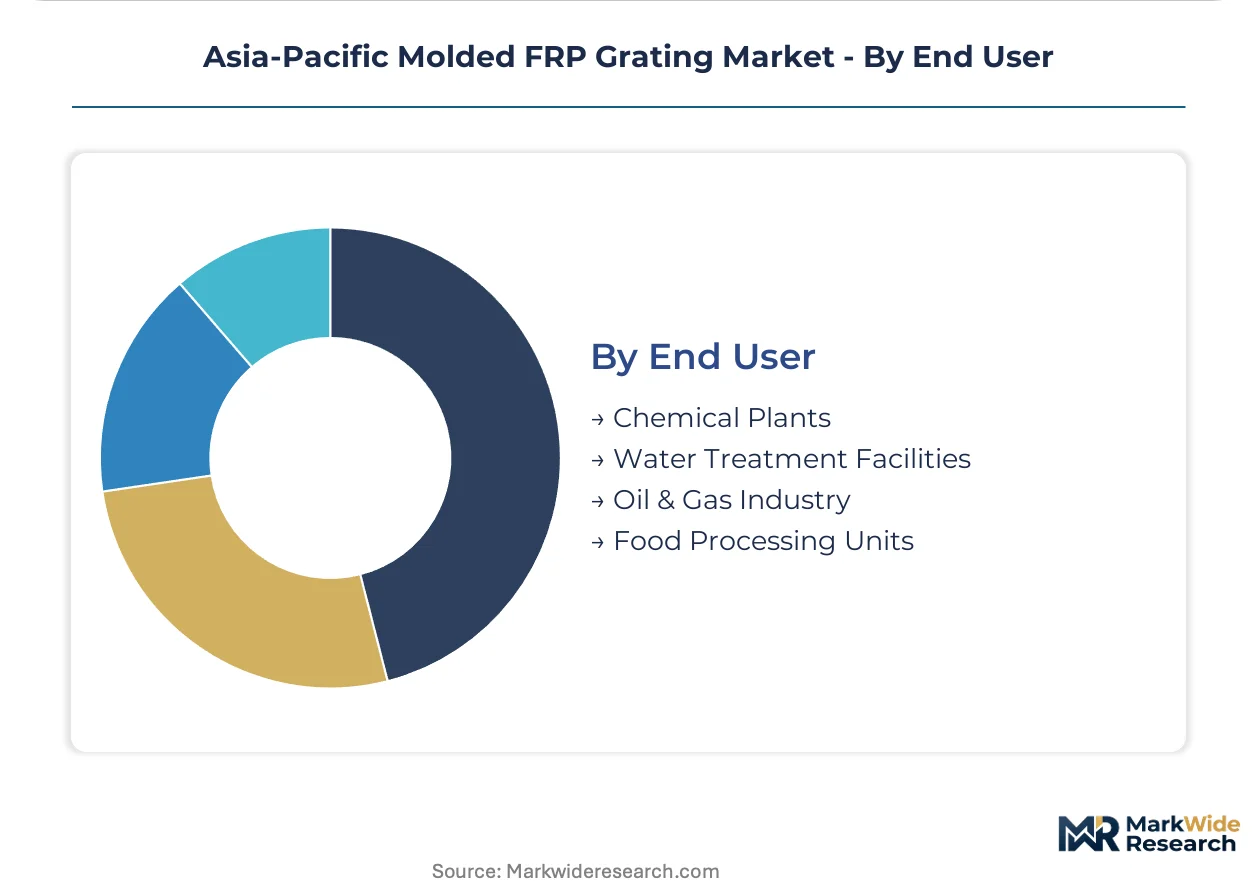
- Chemical Plants:Corrosion-driven infrastructure replacement across Southeast Asian processing clusters compresses procurement cycles and elevates specification stringency for vinylester compliance. China's SAMR enforcement of GB standards for flame spread and smoke density forces asset owners to upgrade legacy steel platforms.
- Oil & Gas Industry:Offshore operators specify anti-slip grating with embedded quartz surfaces under OSHA-equivalent safety protocols across Australian and Malaysian waters, with weight reduction translating directly to topside capacity gains in brownfield platform expansions.
- Water Treatment Facilities:Secondary clarifier platforms and odor-control covers in Thailand and Vietnam represent underpenetrated demand as municipal budgets expand corrosion-resistant asset replacement.
- Food Processing Units:HACCP-aligned facility upgrades across Indonesian seafood processing clusters create specification openings for color-coded safety zone grating with embedded antimicrobial additives.
Chemical plants anchor established procurement volumes. Water treatment facilities present the most rapid demand expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fabricators supply corrosion-resistant platform assemblies to Southeast Asian chemical park expansions, while Japanese producers anchor premium-grade procurement for domestic offshore and port infrastructure upgrades.
China
Yangtze River Delta chemical parks drive volume demand for flame-retardant grating as SAMR enforces GB 8624 standards for smoke density and flame spread in industrial composites. Ningbo and Shanghai fabrication clusters serve domestic retrofit cycles while exporting standardized panels to Vietnamese processing facilities.
Japan
Osaka Bay port authorities specify JIS-compliant FRP flooring with documented embodied carbon disclosures under METI procurement guidelines. Domestic fabricators capture premium positioning for offshore platform living quarters where phenolic resin fire performance satisfies evacuation route requirements.
India
Gujarat's Dahej and Mundra port complexes compress procurement cycles for vinylester-grade platform assemblies as BIS certification timelines extend market access barriers for uncatalogued suppliers. Maharashtra's petrochemical corridor elevates resin-grade stringency for sulfuric acid exposure tolerance.
Australia
Timor Sea drilling expansions specify pultruded I-bar profiles for modular platform designs where weight reduction translates to topside capacity gains. Western Australian offshore operators mandate anti-slip surfaces with embedded quartz under OSHA-equivalent safety protocols.
Vietnam
Thai Binh and Long An province water treatment facilities represent underpenetrated demand for secondary clarifier platforms as municipal budgets expand corrosion-resistant asset replacement. Chinese supply chains dominate procurement through cross-border fabrication networks.
Asia-Pacific Molded FRP Grating Market Competitive Environment
Player mix skews toward regional fabrication specialists with captive resin formulation capabilities and standardized-mesh volume producers serving chemical park procurement. The structure fragments across three strategic tiers: domestic-standard champions serving national compliance regimes, export-oriented custom fabricators capturing offshore platform specifications, and multinational pultrusion specialists displacing molded alternatives in long-span applications. Competitive moves concentrate on backward integration into glass fiber roving supply and geographic expansion into Southeast Asian chemical corridors.
Among Japanese fabricators, AGC Matex exemplifies the premium-tier archetype serving METI-aligned procurement with JIS-compliant fire performance documentation. Chinese producers Jiangyin Runlin and Zhongsheng FRP occupy distinct positioning vectors—Runlin anchors supply to Yangtze River Delta chemical park expansions while Zhongsheng represents the custom fabrication specialist capturing project-specific platform assembly demand. These three entities collectively illustrate how national regulatory divergence shapes viable competitive positioning across the regional market.
| Leading Market Players |
|---|
| Strongwell Corporation |
| Fibergrate Composite Structures |
| Bedford Reinforced Plastics |
| AGC Matex |
| Meiser Grating |
| Liberty Pultrusions |
| Jiangyin Runlin |
| Shanghai Sunoff |
| Zhongsheng FRP |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Yangtze River Delta chemical park operators and domestic fabricators lock in both glass fiber roving supply access and price visibility across multi-year platform retrofit cycles. These contracts insulate buyers from spot volatility in vinylester resin feedstocks while committing suppliers to GB 8624 fire-performance batch documentation.
Pricing Analysis
Current-generation vinylester formulations command 15-25% premiums over prior-generation polyester specifications in Gujarat petrochemical corridor procurement. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified phenolic grating for Japanese offshore platforms from standardized rectangular profiles for Vietnamese water treatment facilities. Cost compression in economy-tier polyester drain covers is intensifying because Chinese state-owned enterprises dominate glass fiber supply. Municipal buyers in Thailand exhibit highest price sensitivity, while Australian offshore operators prioritize anti-slip performance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior among Indian EPC contractors facing 14-18 month BIS certification timelines for uncatalogued resin systems. Manufacturing gravity centers on China, Japan, and India, with glass fiber roving supply drawing from Chinese state-owned enterprises and vinylester resin formulations resting on specialty chemical producers in Japan. Single-source vulnerability concentrates in glass fiber feedstocks when export quotas tighten. Distribution runs through engineering-procurement-construction firms consolidating vendor panels for turnkey platform assembly delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation supervision and structural calculation services expand faster than hardware margins as EPC contractors demand turnkey module delivery with liquidated damages protection. This service-attach layer captures recurring revenue from platform lifecycle maintenance contracts.
For Market Incumbents: Fortify backward integration into glass fiber roving supply to offset Chinese state-owned enterprise quota volatility. Expand captive vinylester formulation capacity in tropical humidity zones where qualified engineers remain scarce. Pultruded I-bar specialists threaten molded grating share in long-span offshore applications above 1.5 meters. For New Entrants and Emerging Players: BIS certification fast-track through pre-submission consultation with Indian testing laboratories unlocks Dahej and Mundra port complex procurement. Target Thai and Vietnamese water treatment municipalities with standardized rectangular grating for secondary clarifier platforms. Lead with antimicrobial-additive formulations for Indonesian seafood processing HACCP upgrades. For Investors and Strategic Acquirers: Regional fabrication specialists with JIS-compliant fire performance documentation and documented embodied carbon disclosures represent priority acquisition targets. Long-term viability hinges on compliance infrastructure depth rather than commodity volume scale. Watch for METI procurement guideline expansion beyond Osaka Bay port authorities into wastewater treatment facility tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Supply | Captive roving access insulates margins from Chinese state-owned enterprise export quota volatility. |
| Vinylester Formulation Capacity Expansion | Tropical-humidity cure profile expertise addresses scarcity of qualified engineers across Southeast Asia. |
| Turnkey Platform Assembly Service Layer | EPC contractor consolidation demands integrated structural calculations and installation supervision. |
| BIS Certification Infrastructure Investment | Pre-approved testing protocols accelerate 14-18 month timelines for Indian chemical park access. |
| Embodied Carbon Disclosure Verification | METI procurement guidelines in Osaka Bay favor suppliers with documented lifecycle assessments. |
Study Parameters
A spread of perspectives from plant engineers at Yangtze River Delta chemical parks, procurement leads at Indian EPC contractors, resin formulation specialists at Japanese fabricators, and port authority infrastructure managers converged on the working assumptions for demand trajectories. Secondary validation drew from GB standards documentation, BIS certification timelines, METI procurement guideline releases, and customs trade data for glass fiber roving imports. Bottom-up project pipeline assessments triangulated against top-down chemical park capacity expansion announcements.
Segmentation dimensions modeled include resin chemistry tier, load-bearing geometry type, end-use corrosion exposure level, and national regulatory compliance cluster across the analysis window. CAGRs derived from weighted average of historical procurement cycle compression rates and projected infrastructure replacement schedules. Forecast inputs incorporated SAMR enforcement intensity for GB 8624 standards and METI low-carbon material substitution incentive expansion.
The analysis sits within stated boundaries; outcomes outside sustained Chinese chemical park investment levels or accelerated BIS certification streamlining would require recalibration. Forecasts reflect assumptions on resin price stability and glass fiber supply continuity. Revision becomes warranted when Indian petrochemical corridor project approvals cross threshold volumes or Japanese offshore platform decommissioning schedules accelerate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Global Sports Composites Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
United States Marine Composites Market
Composite Materials
Composite Drums Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
FRP Tanks Market
Composite Materials
Carbon Aerogel Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Decorative High-Pressure Laminates Market