
 Fiber-Reinforced Plastic (FRP) Grating Market | 2026-2036
Fiber-Reinforced Plastic (FRP) Grating Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber-Reinforced Plastic (FRP) Grating Market Foresight
The capability gap between capital-heavy pultrusion specialists and smaller molded-grating producers is collapsing as automation costs fall. STRONGWELL CORPORATION leverages its integrated resin-to-fabrication pipeline to sustain price competitiveness across North American industrial accounts. Bedford Reinforced Plastics anchors its position through deep specialization in custom-molded architectures for wastewater infrastructure. Eurograte competes on geographic proximity, operating established distribution nodes that serve European chemical clusters with reduced lead times.
Fiber-reinforced plastic grating consists of thermoset resin matrices reinforced with continuous glass fibers, formed through pultrusion, molding, or filament winding to achieve load-bearing bar structures with high strength-to-weight ratios and complete corrosion immunity. The primary industrial purpose is to replace steel gratings in chemically aggressive environments where oxidation, galvanic corrosion, or conductive hazards compromise structural integrity and worker safety. Pultruded grating dominates margin pools in heavy-load petrochemical applications where continuous fiber alignment delivers superior span capabilities, while molded grating leads volume in water treatment and marine platforms where complex geometries and bi-directional strength prove decisive. Hand layup and filament wound variants occupy narrower niches in custom architectural and high-pressure vessel contexts respectively.
OSHA mandates slip-resistant walking surfaces in industrial facilities, directly specifying grating performance criteria that FRP manufacturers must certify through third-party testing. EPA effluent limitations and Clean Water Act provisions are accelerating FRP replacement of corroded metal infrastructure in municipal and industrial wastewater systems. ISO structural standards and ASTM load-rating protocols govern international product acceptance, creating compliance barriers for uncertified entrants. Stakeholders must monitor evolving resin chemistry regulations, particularly around styrene emissions and fire-retardant additives, as these will reshape formulation costs and factory location decisions.
Market Dynamics
The collapse of automation costs is eroding the traditional capability gap between capital-intensive pultrusion specialists and smaller molded-grating producers, redistributing competitive leverage across the supply base.
Growth Catalysts
- OSHA walkway safety mandates:Slip-resistant surface requirements in industrial facilities are compelling facility managers to specify FRP grating over corroded metal alternatives, particularly in chemical processing environments.
- United States Gulf Coast petrochemical expansion:Concentrated investment in ethylene crackers and derivative plants is generating concentrated demand for corrosion-resistant flooring systems.
- Vinyl ester resin formulations:Advanced thermoset chemistry is extending service life in extreme pH environments, opening specification opportunities previously reserved for exotic alloys.
Market Restraints
- Styrene emission regulations:EPA air quality standards and state-level OSHA variants are constraining resin handling operations, elevating compliance capital requirements for open-mold producers.
- Glass fiber supply concentration:Three manufacturers control the majority of continuous roving supply in North America, creating input cost volatility during energy price spikes.
- Fire-retardant additive costs:Halogen-free flame suppression chemistry is priced at multiples of legacy brominated compounds, compressing margins on spec-grade architectural installations.
Strategic Opportunities
- Offshore wind platform decking:European North Sea installations are specifying FRP for reduced topside weight and eliminated galvanic corrosion with turbine foundations.
- Modular wastewater system kits:Packaged treatment plant OEMs are sourcing pre-cut grating assemblies, bypassing traditional distribution channels.
- EU Green Deal embodied carbon accounting:Life-cycle assessment requirements are favoring FRP over steel in public infrastructure tenders across Germany, France, and the Netherlands.
Industry Challenges
- Pultrusion die engineering talent:The specialized skill set for continuous profile tooling design is retiring faster than apprenticeship programs replenish capacity.
- Multi-standard certification timelines:ASTM D635 fire testing, ISO 14122 safety of machinery, and project-specific oil company specifications create parallel approval tracks that delay order conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber-Reinforced Plastic (FRP) Grating Market |
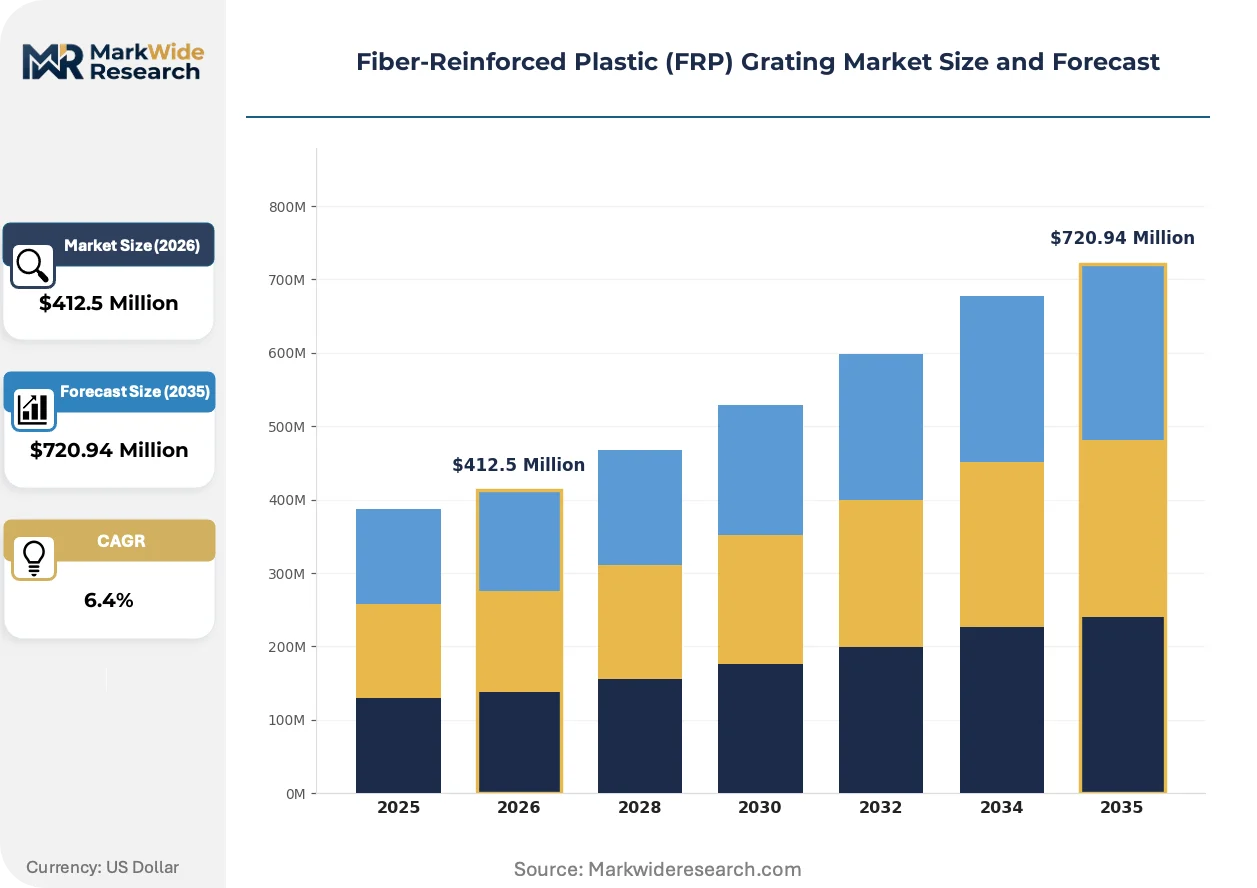
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molded Grating, Pultruded Grating, Hand Layup Grating, Filament Wound Grating Application: Water Treatment, Chemical Processing, Transportation Infrastructure, Marine Platforms End User Industry: Oil & Gas Facilities, Power Generation Plants, Food Processing, Commercial Construction Installation Method: Bolted, Welded, Clamped, Adhesive Bonded |
| Companies Covered | Bedford Reinforced Plastics, STRONGWELL CORPORATION, Fibergrate Composite Structures, Gebrüder MEISER GmbH, Creative Pultrusions, Delta Composites, Eurograte, Techno-Composites Domine GmbH, Lionweld Kennedy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber-Reinforced Plastic (FRP) Grating Market Shifts & Advancements
Resin chemistry automation and digital manufacturing controls are compressing batch-to-batch variation, enabling mid-scale producers to challenge legacy specialists on specification-grade contracts.
Continuous fiber-reinforced thermoplastic (CFRTP) grating is bifurcating the traditional thermoset market by offering weldable repairability and end-of-life recyclability. Offshore oil operators in the Norwegian Continental Shelf are piloting CFRTP walkways for reduced installation weight and simplified logistics. This technology is bifurcating procurement committees into thermoset loyalists and thermoplastic experimenters, with the latter capturing platform maintenance contracts previously dominated by pultruded suppliers.
REACH restrictions on styrene monomer exposure limits are forcing resin formulators to accelerate low-V vinyl ester development. German chemical cluster manufacturers are retrofitting closed-mold systems to maintain access to automotive and electronics sector buyers. The regulatory pressure is most acute in Belgium and the Netherlands, where port authority infrastructure tenders now require third-party emissions certification for grating installation contracts.
Specification authority is migrating from distributor sales engineers to owner-operator engineering departments armed with in-house structural analysis software. Major water utilities in Texas and Louisiana are bypassing traditional channel partners to issue direct RFQs with embedded load calculations. This disintermediation is most visible in municipal wastewater infrastructure, where engineering-procurement-construction firms are consolidating supplier panels and demanding digital twin compatibility for grating asset management.
Fiber-Reinforced Plastic (FRP) Grating Market Segmentation
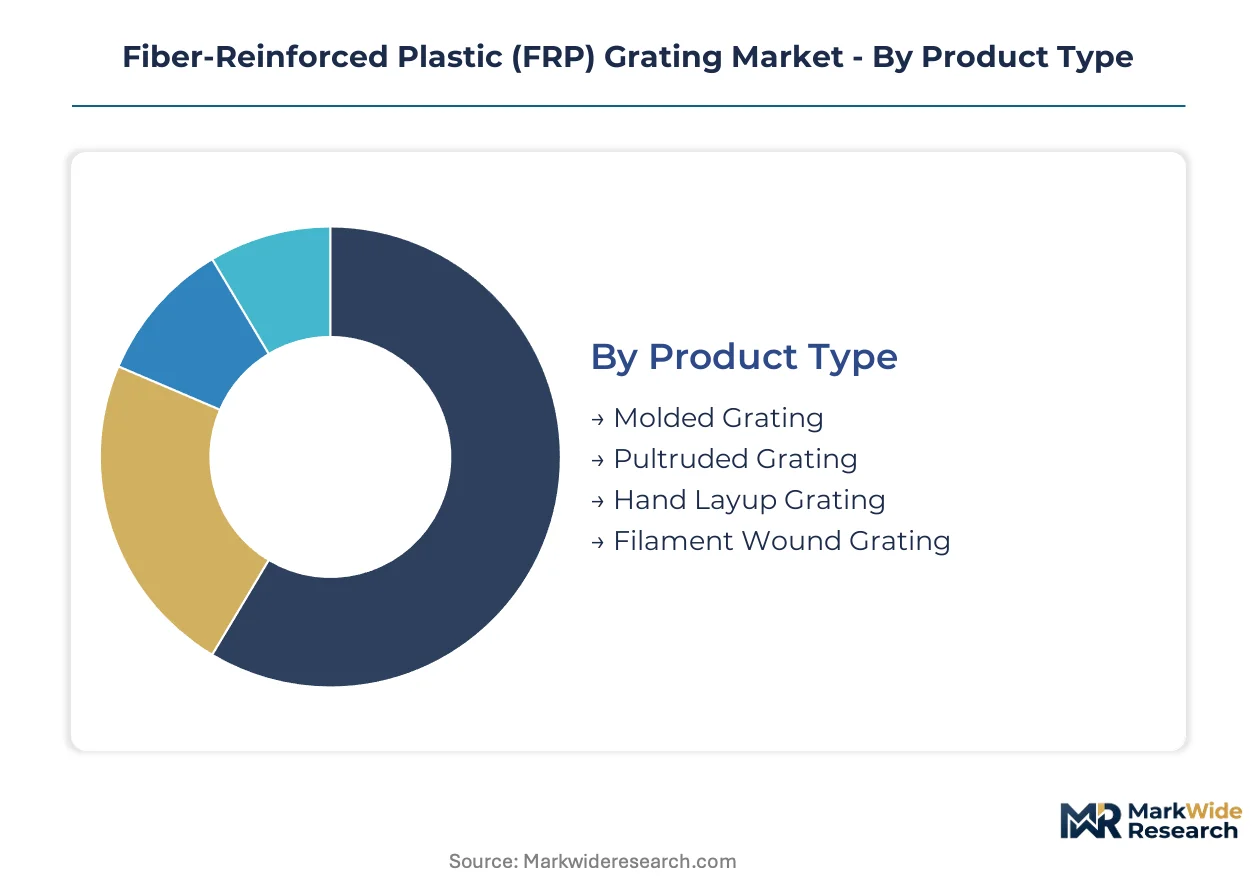
FRP grating procurement patterns diverge sharply across manufacturing methods and end-use environments. Specification authority migrates toward engineering departments that demand load-certified solutions matched to corrosive exposure severity.
Product Type:
Pultruded grating dominates North American domestic consumption for heavy-load petrochemical corridors, while molded variants sustain export volume leadership through standardized water treatment specifications.
- Molded Grating:Bi-directional strength derives from interwoven glass roving in thermoset resin matrices, producing uniform load distribution without secondary fabrication. Municipal wastewater authorities in Louisiana and Texas specify molded architectures for elevated tank walkways and clarifier access platforms, driven by complex geometry requirements and rapid installation timelines.
- Pultruded Grating:Continuous unidirectional fiber alignment delivers superior span capabilities and deflection resistance under concentrated wheel loads. United States Gulf Coast ethylene crackers and derivative plants specify pultruded I-bar and T-bar profiles for process unit mezzanines, compelled by OSHA-mandated live load ratings and corrosive vapor exposure.
- Hand Layup Grating:Custom-fabricated open-mold construction serves architectural installations requiring non-standard panel dimensions or embedded color specifications.
- Filament Wound Grating:Cylindrical fiber deposition creates high-pressure vessel access platforms and specialized structural shapes for offshore containment systems.
Pultruded grating commands the established base. The steepest expansion runs through molded grating as packaged wastewater system OEMs consolidate procurement.
Application:
Specification intensity escalates with regulatory exposure severity, concentrating margin capture in environments where metal corrosion generates safety liabilities or maintenance burden.
- Chemical Processing:Extreme pH exposure and solvent vapor atmospheres eliminate metallic alternatives across acid regeneration units, chlor-alkali cell rooms, and sulfuric acid storage diked areas. EPA emissions compliance and OSHA process safety management protocols mandate corrosion-resistant flooring with certified slip resistance and fire-retardant performance.
- Water Treatment:Continuous moisture, chlorine disinfection byproducts, and biological film accumulation accelerate infrastructure degradation in municipal and industrial facilities. Texas and Louisiana water utilities bypass distribution channels to issue direct RFQs with embedded structural calculations, consolidating supplier panels around digital twin-compatible asset management.
- Marine Platforms:Salt spray immersion and galvanic isolation requirements from steel superstructures drive offshore oil and emerging wind installation specifications.
- Transportation Infrastructure:Bridge decks, boardwalks, and rail platforms exploit FRP's electromagnetic transparency and reduced dead load for seismic and fatigue performance.
Chemical processing commands the established base. The steepest expansion runs through marine platforms as European North Sea wind installations specify reduced topside weight.
End User Industry:
Capital expenditure cycles and regulatory enforcement intensity create divergent procurement patterns across industrial verticals, with energy infrastructure leading specification-grade volume.
- Oil & Gas Facilities:Upstream production platforms, midstream terminals, and downstream refineries generate concentrated demand for fire-retardant, corrosion-immune access systems. OSHA walkway mandates and EPA spill containment requirements compel replacement of corroded steel grating in process areas, tank farms, and loading racks across the United States Gulf Coast petrochemical corridor.
- Power Generation Plants:Cooling tower drift exposure, flue gas desulfurization scrubber environments, and coal handling facilities demand FRP for structural longevity in aggressive chemical and thermal cycling conditions.
- Food Processing:USDA sanitary design requirements and caustic washdown protocols specify slip-resistant, non-porous flooring for processing and packaging line access.
- Commercial Construction:Architectural facades, rooftop equipment platforms, and pedestrian bridges exploit aesthetic color stability and reduced structural dead load.
Oil & gas facilities command the established base. The steepest expansion runs through power generation as cooling tower infrastructure ages.
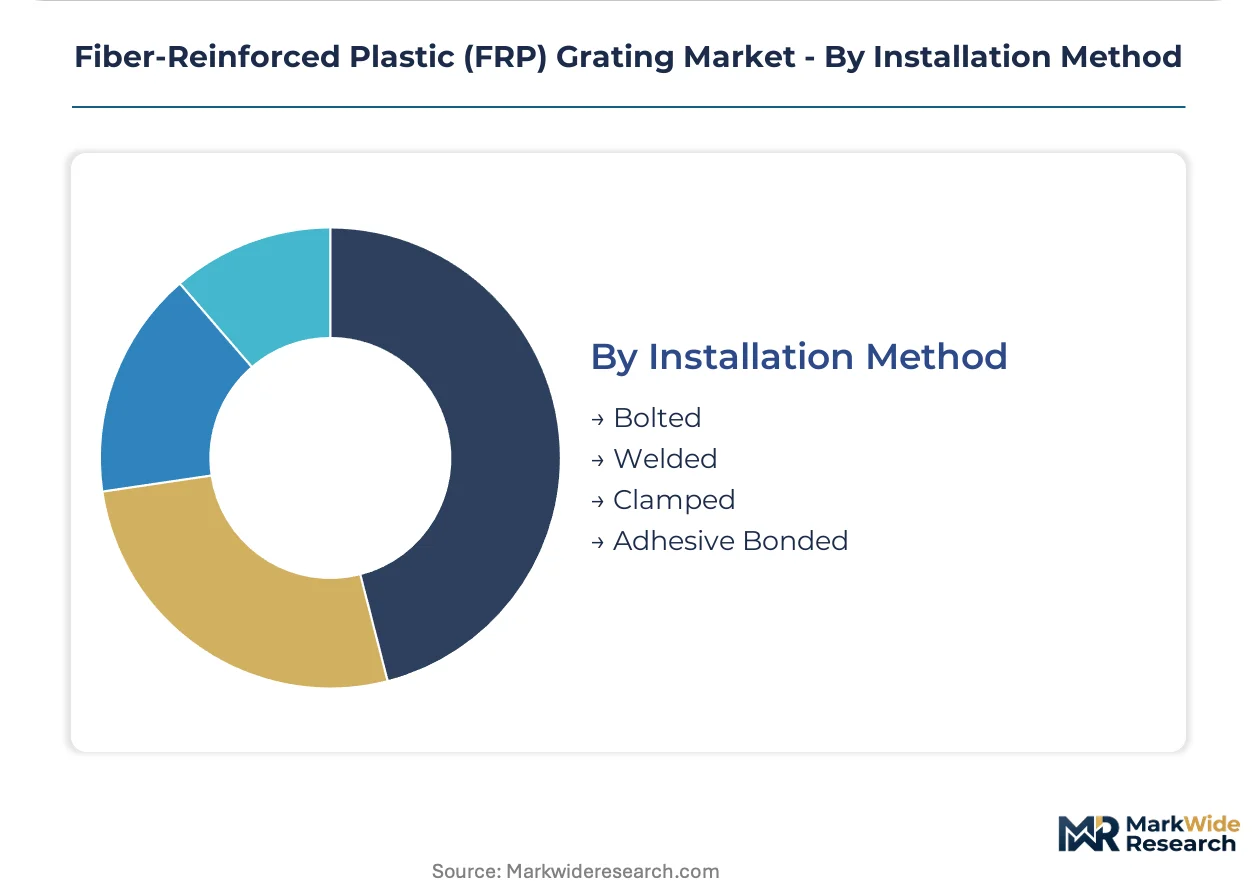
Installation Method:
Fabrication labor intensity and field modification flexibility shape contractor preferences, with mechanical fastening dominating industrial specifications and adhesive systems penetrating architectural applications.
- Bolted:Through-bolted connections with GRP hardware eliminate galvanic corrosion at support interfaces while permitting future panel replacement or reconfiguration. Chemical processing and oil & gas maintenance contractors specify bolted assemblies for process unit turnarounds, driven by speed of installation and compatibility with existing steel support structures.
- Clamped:Proprietary clamping systems enable rapid deployment without hot work permits or structural welding, reducing installation cost and schedule risk in active process facilities.
- Welded:Thermoplastic welding of CFRTP variants offers repairability and end-of-life recyclability, piloted in Norwegian Continental Shelf platform maintenance contracts.
- Adhesive Bonded:Structural epoxy systems serve architectural installations requiring flush surfaces and concealed mechanical connections.
Bolted installation commands the established base. The steepest expansion runs through clamped systems as maintenance contractors prioritize schedule compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States Gulf Coast petrochemical corridor demonstrate the lowest price elasticity, accepting specification-grade premiums for corrosion-resistant flooring, while municipal water utilities in developing markets remain highly sensitive to upfront capital costs despite lower lifecycle expenses.
United States
OSHA walkway safety mandates and EPA emissions rules are tightening material specifications for industrial flooring across chemical processing plants. The Gulf Coast petrochemical corridor from Houston to New Orleans generates concentrated demand for pultruded grating in ethylene crackers and derivative facilities. Texas and Louisiana water utilities are bypassing traditional distribution channels to issue direct RFQs with embedded structural calculations.
Germany
REACH restrictions on styrene monomer exposure limits are forcing resin formulators to accelerate low-V vinyl ester development. The country's national chemical regulator is retrofitting closed-mold system requirements to maintain automotive and electronics sector market access. Port authority infrastructure tenders in Hamburg and Rotterdam now require third-party emissions certification for grating installation contracts.
China
Dual carbon goals and infrastructure modernization programs are expanding specification opportunities for corrosion-immune access systems in power generation and chemical processing. The national standards administration is aligning GB structural standards with ISO load-rating protocols to facilitate export competitiveness. Yangtze River Delta chemical clusters are consolidating procurement around digital twin-compatible asset management systems.
Netherlands
EU Green Deal embodied carbon accounting requirements are favoring FRP over steel in public infrastructure tenders across Rotterdam and Amsterdam port authorities. The national environmental regulator is enforcing stringent air quality standards that constrain open-mold resin handling operations. North Sea offshore wind installations are specifying reduced topside weight decking for turbine foundation platforms.
Norway
Offshore oil operators on the Norwegian Continental Shelf are piloting continuous fiber-reinforced thermoplastic walkways for reduced installation weight and simplified logistics. The national petroleum regulator is mandating corrosion-immune materials for platform maintenance contracts previously dominated by pultruded suppliers. Stavanger and Bergen engineering clusters are driving specification authority migration toward owner-operator engineering departments.
Fiber-Reinforced Plastic (FRP) Grating Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin-to-fabrication pipelines sustaining margin capture against automated mid-scale challengers. The supply base exhibits moderate concentration around pultrusion specialists and molded-grating producers, with automation cost collapse redistributing competitive leverage. Three strategic archetypes dominate: capital-heavy integrated manufacturers, geography-proximate distributors, and custom-molded specialists. Dominant competitive moves include backward integration into resin formulation and geographic expansion through established distribution nodes.
Among North American fabricators, STRONGWELL CORPORATION and Bedford Reinforced Plastics occupy positions representing distinct strategic archetypes, while Eurograte exemplifies the geography-proximate distribution model serving European chemical clusters. These three companies anchor the competitive structure through their representation of integrated manufacturing, custom-molded specialization, and regional distribution proximity respectively.
| Leading Market Players |
|---|
| Bedford Reinforced Plastics |
| STRONGWELL CORPORATION |
| Fibergrate Composite Structures |
| Gebrüder MEISER GmbH |
| Creative Pultrusions |
| Delta Composites |
| Eurograte |
| Techno-Composites Domine GmbH |
| Lionweld Kennedy |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between United States Gulf Coast petrochemical operators and integrated resin-to-fabrication suppliers lock in both vinyl ester supply access and price visibility across multi-year project horizons, insulating procurement teams from spot market volatility in glass fiber roving.
Pricing Analysis
After-sales service revenue from installation support and maintenance contracts drives lifetime value capture for FRP grating manufacturers. Three-tier pricing structure across specification-grade, industrial-standard, and economy levels segments buyers by certification burden and load-rating requirements. Cost compression in economy-tier molded grating is intensifying because automation cost collapse enables mid-scale producers to challenge legacy specialists. Municipal water utilities exhibit the highest price sensitivity due to capital budget constraints, while Gulf Coast petrochemical operators accept specification-grade premiums for corrosion-resistant flooring systems.
Supply Chain Analysis
Strategic stockpiling of continuous glass fiber roving dominates procurement behavior among North American pultrusion specialists facing supply concentration risk. Manufacturing capacity concentrates in the United States, China, and Germany, with each hub serving distinct regional chemical processing and infrastructure markets. Production draws from vinyl ester resins, continuous glass roving, and halogen-free fire-retardant additives as primary inputs. Single-source vulnerability in continuous roving supply creates exposure during energy price spikes. Distribution runs through engineering-procurement-construction firms and direct OEM relationships, with municipal utilities increasingly bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as specification authority migrates from distributor sales engineers to owner-operator engineering departments, creating niche openings for digitally native challengers with load-calculation software and digital twin compatibility.
For Market Incumbents: Shield margin position by accelerating backward integration into low-V vinyl ester resin formulation ahead of REACH styrene exposure restrictions. Secure pultrusion die engineering talent through apprenticeship partnerships before retirement-driven scarcity intensifies. Certification investment in ISO 14122 and ASTM D635 parallel approval tracks defends against automated mid-scale competitors.
For New Entrants and Emerging Players: Anchor in modular wastewater system kits for packaged treatment plant OEMs, bypassing consolidated distributor channels where incumbents hold relationship lock-in. European North Sea offshore wind platform decking represents the most penetrable application, driven by EU Green Deal embodied carbon accounting favoring FRP over steel. Lead with digital twin-compatible asset management software as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin-to-fabrication manufacturers with captive vinyl ester supply and established Gulf Coast petrochemical relationships. Long-term viability hinges on regulatory compliance architecture rather than commodity cost position alone. Watch for CFRTP thermoplastic adoption rates in Norwegian Continental Shelf maintenance contracts as the inflection signal indicating technology bifurcation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive vinyl ester supply insulates margin from styrene emission compliance cost spikes. |
| Digital Twin Platform Development | Asset management software locks in Texas and Louisiana water utility direct procurement relationships. |
| CFRTP Thermoplastic Capacity Addition | Weldable repairability captures Norwegian offshore platform maintenance contract migration. |
| Closed-Mold System Retrofit | Emissions certification maintains access to EU automotive and electronics sector buyers. |
| Pultrusion Die Engineering Apprenticeship | Specialized tooling design capacity replacement defends against talent-driven production bottlenecks. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors at chemical processing facilities, procurement leads at water utilities, and EPC contractor project managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including OSHA regulatory filings, EPA effluent limitation databases, customs trade records for FRP imports, and SEC 10-K disclosures from integrated manufacturers. Bottom-up segment sizing across product type, application, and end-use industry converged with top-down macro validation.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios and regulatory enforcement intensity variations throughout the projection horizon. Segmentation dimensions modeled include manufacturing method, corrosive exposure severity tier, installation method, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new capacity addition pipelines in petrochemical and offshore wind sectors. Vinyl ester resin formulation cost curves and glass fiber supply concentration indices served as industry-specific forecast inputs.
Material uncertainties — abrupt REACH styrene restriction tightening, Gulf Coast hurricane disruption to petrochemical construction schedules, CFRTP thermoplastic specification capture rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and EU Green Deal procurement rule implementation. Revision becomes warranted when CFRTP adoption in offshore maintenance contracts crosses threshold penetration levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Epoxy Composite Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Transportation Composites Market
Composite Materials
Green Composites Market
Composite Materials
Global Geocomposites Market
Composite Materials
Composite Market
Composite Materials
Composite Cans Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Carbon Aerogel Market
Composite Materials
Marine Composites Market
Composite Materials
Laminar Composites Market
Composite Materials
CFRP Propeller Shaft Market