
 Wireless Smart Home Market | 2026-2036
Wireless Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Smart Home Market Insights
Multifamily residential development is pivoting toward integrated wireless ecosystems as landlords seek operational efficiency and tenant retention. Amazon.com, Inc. leverages its Alexa voice platform to anchor whole-home command layers across third-party hardware. Schneider Electric specializes in energy management interfaces that extend building automation into residential retrofit environments. Samsung Electronics Co., Ltd. competes through its SmartThings hub, which controls Zigbee and Z-Wave device meshes from a single interface.
Wireless smart home systems comprise distributed sensor networks, actuator nodes, and gateway controllers that communicate through radio-frequency protocols without dedicated wired infrastructure. These systems typically operate on mesh topologies using sub-gigahertz or 2.4 GHz spectra, with latency thresholds below 100 milliseconds for real-time climate and security responsiveness. Smart Security and Smart Thermostats command the largest installed bases, though Smart Lighting registers the fastest retrofit attachment rates as LED depreciation cycles force fixture replacements. Voice Activation dominates control mechanism preferences, while Professional Installation retains margin pools in luxury single-family segments where custom programming justifies service premiums.
The EU Green Deal and F-Gas Regulation shape product roadmaps by mandating refrigerant transitions and building energy performance disclosures that drive thermostat and HVAC controller upgrades. FCC Part 15 rules in the United States govern unlicensed spectrum use for Wi-Fi and Zigbee transmissions, creating compliance barriers for non-certified imports. ETSI standards in Europe enforce interoperability testing that fragments certification costs across regional variants. Stakeholders must monitor spectrum reallocation proceedings and cybersecurity labeling programs that threaten to fragment addressable markets by compliance tier.
Market Dynamics
Mesh network protocol convergence is compressing hardware margins while elevating software and service revenue pools across the wireless smart home ecosystem. The shift from proprietary radio stacks toward standardized Matter-over-Thread implementations is forcing gateway manufacturers to recalibrate value capture models around cloud subscriptions rather than device markups.
Growth Catalysts
- EU Green Deal building codes:Mandatory energy performance disclosures in Germany and France are accelerating thermostat and HVAC controller replacements in multifamily housing stock.
- LED depreciation cycles:Fixture replacement waves in the United Kingdom are attaching wireless control modules to new luminaire installations at retrofit sites.
- Voice-first interfaces:Natural language command layers are reducing technical barriers for elderly demographics in Japan and South Korea, expanding addressable household bases.
Market Restraints
- Silicon supply concentration:Sub-gigahertz radio chip fabrication depends on a limited foundry base in Taiwan, creating input cost volatility and allocation risk.
- Interoperability certification fragmentation:ETSI standards in Europe, FCC Part 15 in the United States, and MIC radio law in Japan impose redundant testing costs on single-SKU global products.
- Legacy wired infrastructure persistence:New construction in the United Arab Emirates and Saudi Arabia continues specifying KNX bus systems, limiting wireless penetration in greenfield residential.
Strategic Opportunities
- India smart city mandates:The country's urban transformation programs are embedding wireless sensor networks into public housing and municipal building retrofits.
- Matter-Thread-Zigbee convergence:Unified application layers are collapsing gateway hardware requirements and enabling phone-native device commissioning without dedicated hubs.
- Utility demand response programs:Time-of-use rate structures in California and Texas are creating attach opportunities for cloud-connected thermostat ecosystems.
Industry Challenges
- Embedded systems security engineering:Shortage of firmware developers with cryptographic implementation expertise is delaying product launches and patch cycles.
- Multi-protocol radio integration:Simultaneous Wi-Fi, Thread, and Zigbee 3.0 support in single-SKU designs is expanding bill-of-materials complexity and thermal management requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Smart Home Market |
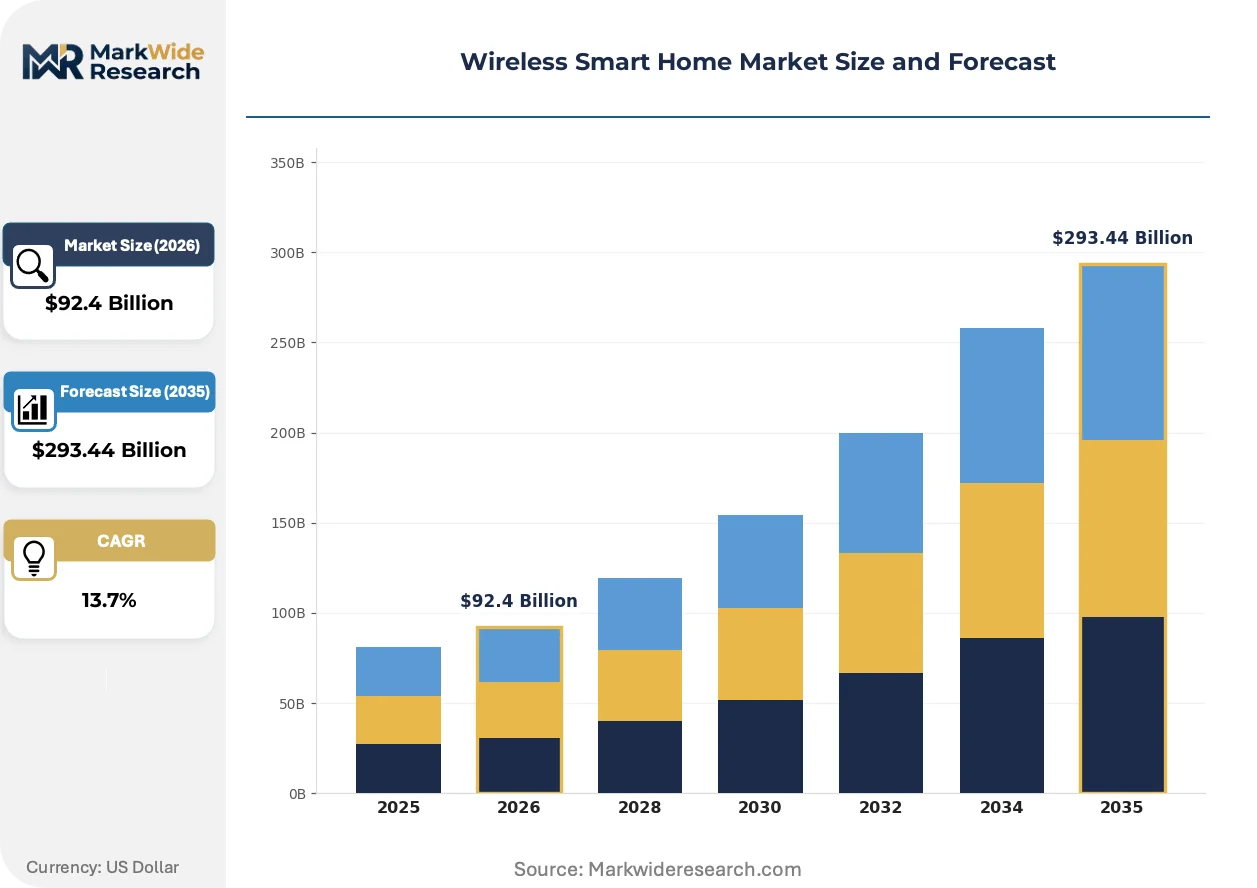
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $293.44 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security, Smart Thermostats, Smart Appliances Control Mechanism: Voice Activation, Mobile App Control, Remote Control, Automation Systems Installation Type: DIY Installation, Professional Installation, Retrofit Solutions, New Construction Connectivity Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth |
| Companies Covered | Amazon.com, Inc., Apple Inc., Alphabet Inc., Samsung Electronics Co., Ltd., Honeywell International Inc., Schneider Electric, Johnson Controls Inc., Robert Bosch GmbH, ADT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Smart Home Market Trends and Innovations
Edge inference and on-device machine learning are redistributing computational load away from cloud servers and into sensor endpoints, reshaping power budgets and silicon selection criteria across product categories.
Matter-over-Thread radio stacks are automating cross-brand device discovery and commissioning workflows. Residential installers in the United States and Netherlands are adopting phone-based configuration tools that eliminate manual pairing sequences. This compression of setup friction is reducing professional installation margins while accelerating consumer self-service attachment rates for lighting and climate categories.
The EU AI Act risk classification framework is imposing documentation and conformity assessment burdens on smart home devices with biometric or behavioral inference capabilities. Camera and voice-enabled products face heightened transparency requirements and human oversight mandates. Manufacturers serving European markets are segregating product lines between high-risk and limited-risk feature tiers to manage compliance scope.
Subscription unbundling from hardware purchases is restructuring channel economics. Retailers in the United Kingdom and Australia are pivoting toward recurring revenue shares from cloud storage and advanced automation services. This shift compresses upfront price points on gateway devices while elongating customer lifetime value capture through monthly fees for remote access and AI-powered energy optimization features.
Wireless Smart Home Market Segmentation
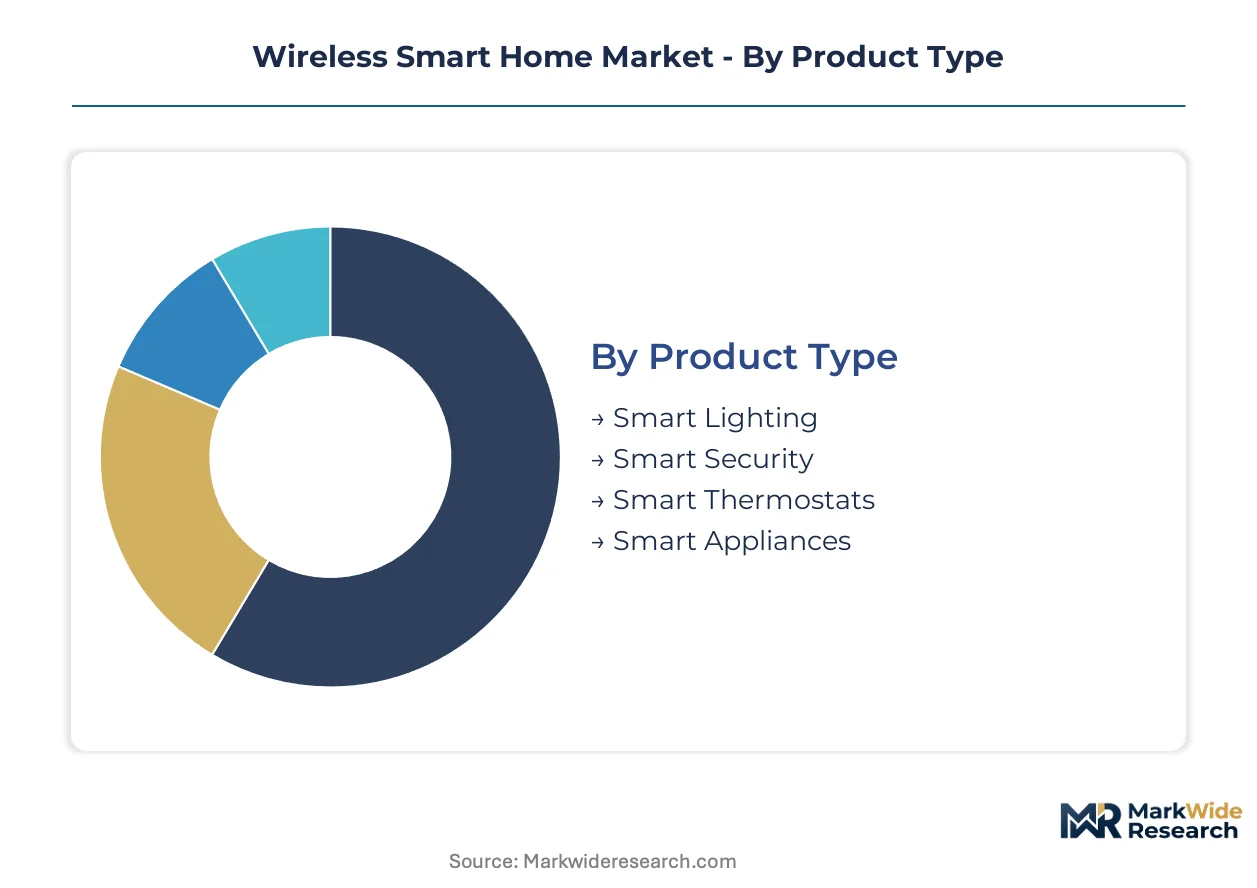
Wireless smart home purchasing decisions cascade through four distinct lenses: hardware category, user interface preference, deployment complexity, and radio protocol compatibility. Each segmentation axis carries different margin structures, certification burdens, and channel economics that reshape vendor positioning.
Product Type:
Replacement cycles and energy regulations drive category selection more than novelty appeal.
- Smart Lighting:LED depreciation cycles in the United Kingdom and Germany are attaching wireless control modules to fixture replacements. EU Green Deal building codes accelerate luminaire upgrades in multifamily retrofits where wiring access is constrained.
- Smart Security:Camera and sensor systems command premium pricing through recurring cloud storage subscriptions. Professional monitoring attach rates remain highest in single-family suburban deployments across the United States and Japan.
- Smart Thermostats:Utility demand response programs in California and Texas subsidize device costs. F-Gas Regulation refrigerant transitions in Europe force HVAC controller replacements alongside compressor upgrades.
- Smart Appliances:Connectivity modules add marginal cost to white goods where replacement cycles stretch 10-15 years. South Korean manufacturers lead on native Wi-Fi integration in washing machines and refrigerators.
Smart Security leads on scale; Smart Lighting leads on momentum.
Control Mechanism:
Interface preference stratifies sharply by age demographic and technical confidence.
- Voice Activation:Natural language layers reduce technical barriers for elderly households in Japan and South Korea. Alexa and Google Assistant command dominance through third-party hardware integration deals.
- Mobile App Control:Phone-native commissioning through Matter-over-Thread is collapsing gateway hardware requirements. Dutch and United States installers are adopting smartphone-based configuration tools.
- Remote Control:Physical handhelds persist in hospitality and senior living segments where tactile feedback outweighs convenience. Dedicated remotes retain share in German and Austrian markets.
- Automation Systems:Rule-based scheduling and geofencing attract power users seeking energy optimization. Subscription unbundling in the United Kingdom and Australia is shifting revenue toward cloud automation services.
Voice Activation dominates volume; Mobile App Control gains share fastest.
Installation Type:
Labor cost differentials and housing stock age determine deployment mode economics.
- DIY Installation:Self-service attachment rates climb as phone-based commissioning eliminates manual pairing. Lighting and plug-in categories show highest consumer completion rates without professional support.
- Professional Installation:Custom programming and integrated security retain margin pools in luxury single-family segments. United Arab Emirates and Saudi Arabia greenfield construction specifies KNX bus systems that limit wireless penetration.
- Retrofit Solutions:Aging housing stock in the United Kingdom drives wireless attachment where rewiring is cost-prohibitive. Battery-powered sensors and wireless switches dominate 1960s-era multifamily upgrades.
- New Construction:Pre-wiring for power-over-ethernet and centralized hubs occurs in premium developments. German multifamily developers are expanding smart apartment deployments ahead of tightened energy codes.
Retrofit Solutions address the largest installed base; DIY Installation expands most quickly.
Connectivity Technology:
Radio protocol choice trades off range, power consumption, and interoperability certification costs.
- Wi-Fi:Ubiquitous infrastructure eliminates gateway requirements but imposes higher power budgets on battery devices. FCC Part 15 compliance in the United States creates barriers for non-certified imports.
- Zigbee:Mesh topologies using 2.4 GHz spectra deliver sub-100 millisecond latency for climate and security responsiveness. ETSI interoperability testing in Europe fragments certification costs across regional variants.
- Z-Wave:Sub-gigahertz operation penetrates walls more effectively in multi-story European masonry construction. Silicon supply concentration in Taiwan creates input cost volatility for radio chip fabrication.
- Bluetooth:Low-energy variants enable direct phone-to-device commissioning without hub intermediation. Matter-over-Thread convergence is absorbing Bluetooth commissioning workflows into unified application layers.
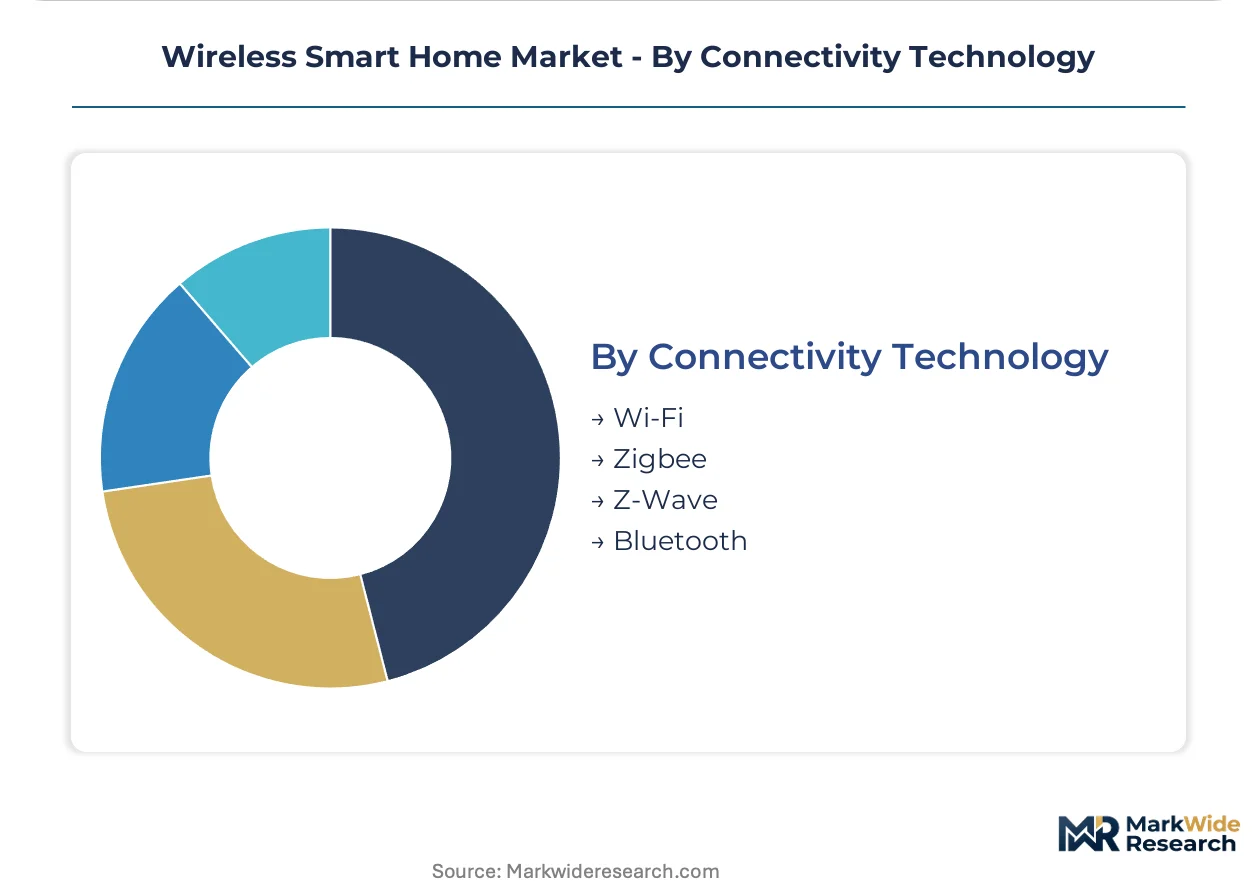
Wi-Fi leads on device count; Zigbee leads on mesh deployment momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate assembly toward jurisdictions with streamlined certification regimes. Cost-of-compliance gaps between ETSI testing in Europe and FCC Part 15 procedures in the United States now exceed 18 months in product launch timelines.
United States
Utility demand response programs in California and Texas subsidize thermostat deployments at scale. FCC Part 15 rules govern unlicensed spectrum use for Wi-Fi and Zigbee transmissions, creating compliance barriers for non-certified imports. The Pacific Northwest corridor hosts cloud infrastructure clusters where voice-activated platform providers anchor data center capacity.
Germany
Multifamily residential developers are expanding smart apartment deployments as the EU Green Deal tightens building energy codes. F-Gas Regulation mandates refrigerant transitions that force HVAC controller replacements alongside compressor upgrades. The Rhine-Ruhr metropolitan region concentrates building automation engineering talent for retrofit wireless installations.
United Kingdom
LED depreciation cycles are attaching wireless control modules to fixture replacements across aging housing stock. Battery-powered sensors and wireless switches dominate 1960s-era multifamily upgrades where rewiring is cost-prohibitive. Greater London hosts the highest density of Matter-over-Thread commissioning tool adoption among residential installers.
Japan
Natural language command layers reduce technical barriers for elderly households, expanding addressable household bases. MIC radio law imposes testing requirements that fragment certification costs on single-SKU global products. The Kanto region around Tokyo anchors voice-first interface development partnerships between platform providers and consumer electronics manufacturers.
India
Urban transformation programs are embedding wireless sensor networks into public housing and municipal building retrofits. The national smart city mandate creates procurement pipelines for distributed sensor networks and gateway controllers. Maharashtra and Karnataka host emerging hardware assembly clusters serving domestic retrofit demand.
Wireless Smart Home Market Competitive Landscape
Strategic partnerships dominate the current landscape as platform providers secure hardware integration commitments from lighting and climate manufacturers. The vendor base stratifies across three tiers: voice-first ecosystem orchestrators, energy management specialists, and security-focused service providers. Platform-scale players and component-integrated industrials represent the primary strategic archetypes. Technology licensing agreements and cloud subscription unbundling constitute the dominant competitive moves reshaping value capture models.
Within the platform-orchestrator tier, Amazon.com, Inc. and Alphabet Inc. exemplify ecosystem anchoring through third-party hardware integration deals. Schneider Electric occupies a position among energy management specialists extending building automation into residential retrofit environments. Samsung Electronics Co., Ltd. sits within the component-integrated archetype, leveraging hub hardware to control multi-protocol device meshes.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Alphabet Inc. |
| Samsung Electronics Co., Ltd. |
| Honeywell International Inc. |
| Schneider Electric |
| Johnson Controls Inc. |
| Robert Bosch GmbH |
| ADT Inc. |
| Others |
Pricing and Supply Chain Analysis
Utility procurement programs in California and Texas concentrate thermostat purchasing power through demand-response subsidies, anchoring contract-based long-term offtake as the dominant pricing model across climate-control hardware tiers.
Pricing Analysis
Retailer markup compression in the United Kingdom and Australia is accelerating subscription unbundling from hardware purchases. Three-tier pricing structure across premium, standard, and economy levels separates professional installation bundles from DIY self-service kits and bare-device SKUs. Cost compression in gateway hardware is intensifying because Matter-over-Thread convergence collapses hub requirements. DIY consumers exhibit highest price sensitivity, while luxury single-family segments in the United States and United Arab Emirates tolerate service premiums for custom programming.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Rotterdam, and Dallas anchor hub-and-spoke patterns for finished-device fulfillment to retail and installer channels. Sub-gigahertz radio chip fabrication draws from Taiwan, with secondary assembly clusters in Malaysia and Mexico. Silicon supply concentration creates single-source vulnerability for Z-Wave and proprietary mesh protocols. Distribution runs through omnichannel retail networks, direct-to-consumer platforms, and professional installer cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eighteen-month cost-of-compliance gap between ETSI testing in Europe and FCC Part 15 procedures in the United States positions regulatory arbitrage as the decisive geographic play for manufacturers seeking launch velocity.
For Market Incumbents: Deploy cloud subscription layering to recapture value as gateway hardware margins compress under Matter-over-Thread standardization. Deepen backward integration into sub-gigahertz radio silicon to mitigate Taiwan foundry allocation risk. Fortify certification investment across ETSI, FCC Part 15, and MIC radio law variants to defend against import compliance barriers. For New Entrants and Emerging Players: EU Green Deal building codes in Germany and France open a window for thermostat and HVAC controller specialization in multifamily retrofit channels. White-space targets include battery-powered sensor networks for 1960s-era United Kingdom housing stock and voice-first interfaces for elderly demographics in Japan. A phone-native commissioning go-to-market angle bypasses incumbent hub dependencies. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking edge-AoT talent and device-commissioning IP. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Watch utility demand-response program expansion in Texas and California as the inflection signal for thermostat ecosystem consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Matter-Thread Protocol Integration | Unifies commissioning workflows across Samsung, Amazon, and Google hardware ecosystems. |
| Cloud Subscription Unbundling | Shifts United Kingdom and Australian retailer economics toward recurring revenue shares. |
| Edge AI Inference Deployment | Redistributes computational load from AWS and Google servers into sensor endpoints. |
| Sub-Gigahertz Silicon Backward Integration | Mitigates Taiwan foundry concentration risk for Z-Wave mesh radio fabrication. |
| Utility Demand Response Partnership | Attaches thermostat ecosystems to California and Texas time-of-use rate structures. |
Research Methodology
Direct dialogue with smart home platform engineers, residential installer network heads, utility demand-response program managers, and semiconductor procurement leads grounded the qualitative foundation. Secondary validation drew from FCC equipment authorization databases, ETSI interoperability test reports, utility regulatory filings, and hyperscaler IoT capex disclosures. Bottom-up device shipment modeling and top-down ecosystem revenue analysis were triangulated to cross-verify segment sizing.
Bottom-up volume builds by product category, control mechanism, installation type, and connectivity protocol were reconciled against top-down ecosystem spend estimates across the projection horizon. CAGRs were derived from regression analysis of replacement cycle timing, regulatory mandate enforcement schedules, and technology substitution curves. Forecast inputs incorporated LED depreciation wave timing in the United Kingdom, EU Green Deal implementation phasing in Germany, and Matter certification adoption rates among gateway manufacturers.
Revisions become necessary when spectrum reallocation proceedings, cybersecurity labeling program expansions, or foundry capacity disruptions materialize beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
Wi-Fi Booster Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market