
 Femtocell Market | 2026-2036
Femtocell Market Size, Share, and Industry Trends Forecast 2026-2036
Femtocell Market Intelligence
The capital investment gap between large-scale network equipment manufacturers and specialized femtocell component suppliers is collapsing under the pressure of open RAN architectures. Ericsson leverages its extensive carrier relationships to deploy integrated solutions for mobile network operators. In contrast, Qualcomm dominates the underlying chipset technology, influencing device-level performance and features across multiple vendors. Cisco Systems positions its enterprise-grade femtocells for seamless integration with existing corporate IT infrastructure, targeting large business clients.
A femtocell is a small, low-power cellular base station designed to extend mobile network coverage within a confined area, such as a residence or office. It operates in licensed spectrum and connects to the mobile operator's network through a standard broadband internet connection to improve voice quality and data throughput. LTE technology-based femtocells currently lead the market, but the transition to 5G standards is creating significant opportunities. While residential applications provide a foundational demand, growth is increasingly driven by deployments in corporate facilities and public venues.
Regulatory compliance is critical, with devices requiring approval from bodies like the FCC in the United States for spectrum use and interference management. In Europe, femtocells must adhere to CE marking directives for safety and the F-Gas Regulation for any cooling components. China's MIIT sets specific standards for all network access equipment. Stakeholders must therefore navigate evolving spectrum allocation policies and heightened security mandates for network-connected devices to ensure market access.
Market Dynamics
The femtocell market's core dynamic is the architectural tension between proprietary, vertically integrated network solutions and the disaggregation driven by Open RAN standards. This force shapes competition, supply chain dependencies, and operator deployment strategies for 5G network densification.
Growth Catalysts
- 5G Network Densification:The rollout of 5G requires a higher density of cells to deliver promised speeds and low latency, making femtocells essential for indoor and localized coverage where macro signals are weak.
- Enterprise Demand:Corporate facilities, hospitals, and public venues require consistent, high-quality mobile connectivity for mission-critical applications and guest services, driving private network and indoor system deployments.
- Open RAN Architectures:The promotion of open, interoperable network standards lowers barriers to entry for specialized component suppliers, fostering innovation and competitive pricing in the chipset and software segments.
Market Restraints
- Backhaul Dependency:Femtocell performance is contingent on the quality and bandwidth of the user's broadband internet connection, a factor outside the mobile operator's direct control which can create service bottlenecks.
- Interference Management:Poorly configured devices can cause interference with the macro cellular network and other nearby small cells, requiring sophisticated self-organizing network (SON) capabilities to manage.
- Spectrum Licensing:Access to licensed spectrum remains a complex and costly barrier, particularly for neutral host models or private networks operating in shared or locally licensed frequency bands.
Strategic Opportunities
- Private 5G Networks:Deploying femtocells for private cellular networks in manufacturing, logistics, and port environments offers a significant growth vector by enabling secure, low-latency Industrial IoT applications.
- Edge Computing Integration:Combining femtocell hardware with multi-access edge computing (MEC) capabilities creates a platform for low-latency applications, from enterprise data processing to localized content delivery.
- Neutral Host Models:Developing multi-operator femtocells for public venues and multi-tenant buildings allows property owners to offer enhanced connectivity as an amenity, creating a new service-based revenue stream.
Industry Challenges
- Security Management:Securing a massively distributed attack surface of millions of femtocell endpoints against cyber threats presents a substantial and ongoing operational challenge for network operators.
- Multi-Vendor Integration:Ensuring seamless interoperability and unified management between femtocells, core network elements, and OSS/BSS systems from different vendors remains a significant technical hurdle.
- Regulatory Compliance Timelines:Navigating disparate certification processes, such as FCC approval in the US and CE marking in Europe, for hardware and software updates can delay product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Femtocell Market |
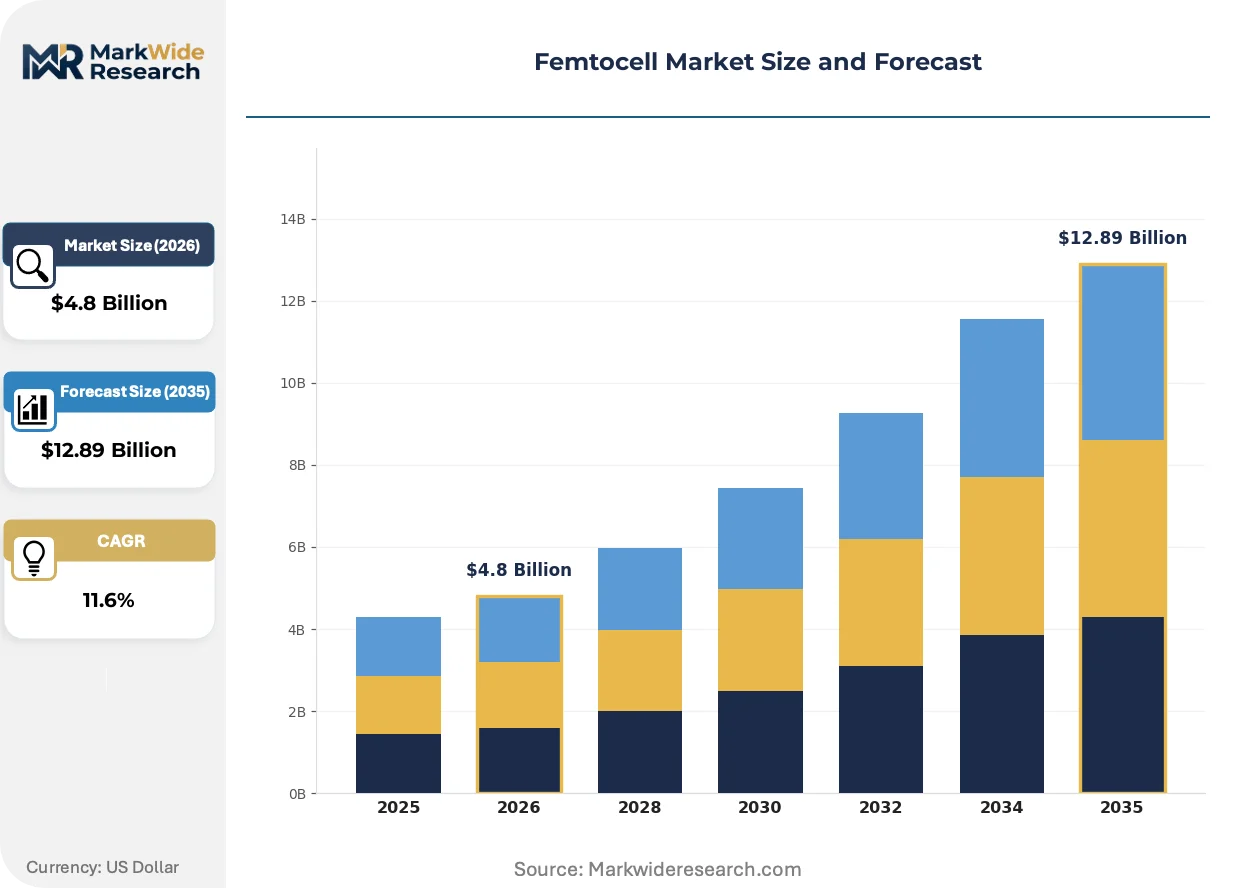
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Femtocell, Integrated Femtocell, Hybrid Femtocell, Enterprise Femtocell Technology: UMTS, LTE, GSM, CDMA, WiMAX Application: Residential, Small Office/Home Office, Public Venues, Educational Institutions, Corporate Facilities End User: Mobile Network Operators, Telecommunication Service Providers, Managed Service Providers, Infrastructure Vendors |
| Companies Covered | Huawei Technologies, Qualcomm, Nokia Corporation, Fujitsu Ltd., Ericsson, Samsung Electronics, ZTE Corporation, CommScope Inc., Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Femtocell Market Strategic Shifts & Innovations
The evolution of femtocells from simple coverage extenders to intelligent edge nodes is the defining theme. This transition is driven by embedded processing power, new service models, and regulatory frameworks that favor network disaggregation and interoperability.
Onboard artificial intelligence is transforming device functionality. Modern femtocell chipsets integrate machine learning algorithms to perform real-time radio frequency optimization and predictive traffic management. Enterprise and mobile network operators are adopting these advanced systems to reduce operational costs. This development is bifurcating the market into basic, low-cost coverage extenders and premium, self-optimizing network nodes capable of supporting complex service level agreements.
Regulatory support for Open RAN standards is altering the competitive landscape. Initiatives from government bodies, including the US National Telecommunications and Information Administration, are designed to foster a more diverse and resilient telecom supply chain. The primary consequence is increased modularity, allowing operators to mix and match components from different suppliers. This shift most directly benefits specialized software and hardware vendors who can now compete with incumbent network equipment providers.
Enterprise consumption models for indoor connectivity are shifting toward managed services. Instead of a one-time capital expenditure for hardware, businesses increasingly prefer subscription-based "network-as-a-service" offerings. This disrupts the traditional direct-sales channel, elevating the role of system integrators and mobile operators as managed service providers. This trend is most visible within the healthcare and hospitality sectors in North America, where reliable connectivity is a critical operational requirement.
Femtocell Market Segmentation
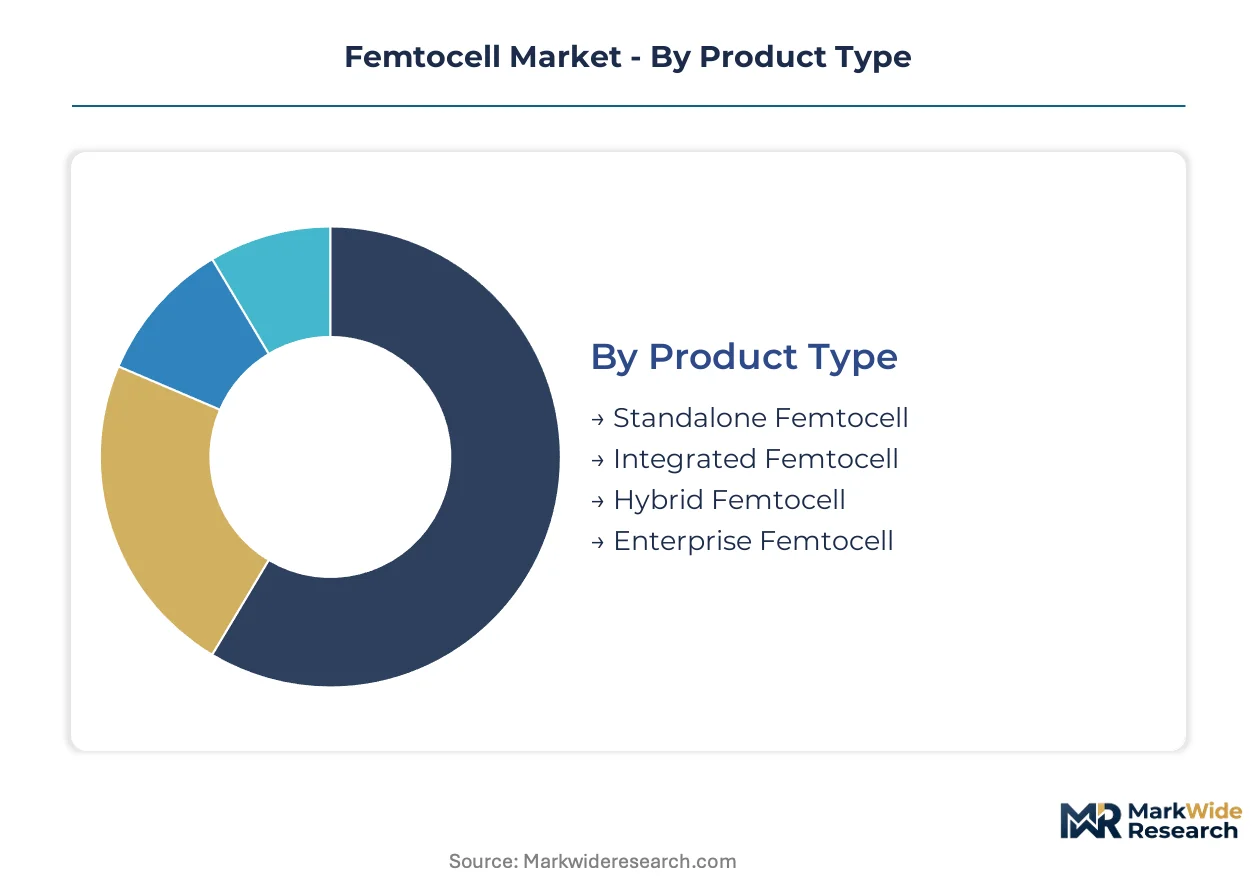
The femtocell market segments reflect diverse technological capabilities and deployment scenarios, crucial for understanding its evolving competitive landscape. Analyzing these segments reveals how different product types and technologies address specific end-user demands and application requirements across various geographies.
Product Type:
Regulatory frameworks often distinguish femtocell product types based on their deployment model and interoperability requirements, influencing market access and certification processes.
- Enterprise Femtocell:Designed for large-scale deployments within corporate campuses, these units prioritize robust security and centralized management for business-critical operations. Demand concentrates in the United States and Germany, driven by the need for secure private 5G networks in industrial settings.
- Integrated Femtocell:These solutions combine femtocell functionality with existing network equipment, simplifying deployment and reducing hardware footprint for operators. The push for 5G network densification in China and Japan drives demand, accelerating adoption in urban centers.
- Standalone Femtocell:These independent devices provide localized coverage, connecting directly to a mobile operator's core network via a standard broadband connection.
- Hybrid Femtocell:Hybrid femtocells operate as both cellular extenders and Wi-Fi access points, offering flexible connectivity options for small office environments.
Enterprise Femtocell handles the majority of throughput; Integrated Femtocell is the fastest mover on share.
Technology:
The underlying technology choice for femtocells dictates the spectrum efficiency and data speeds available for end-user applications, impacting overall network performance.
- LTE:This technology currently dominates the femtocell market, offering high-speed data and voice over IP capabilities for 4G networks. Demand is strong in developed markets like the United States and South Korea, where operators prioritize 4G network optimization.
- UMTS:As a 3G technology, UMTS femtocells still provide foundational mobile coverage, particularly in regions with ongoing 3G infrastructure and specific legacy applications. European markets, specifically France and Italy, still utilize UMTS for rural coverage and voice services.
- GSM:These femtocells extend 2G network coverage, primarily supporting voice and basic data services in niche or developing applications.
- CDMA:CDMA femtocells serve specific legacy networks, offering voice and data services where this technology remains prevalent in certain regions.
- WiMAX:While less common for cellular extension, WiMAX femtocells historically provided broadband wireless access in certain fixed wireless deployments.
LTE technology currently holds the largest installed base, while UMTS continues to see deployments for specific coverage needs.
Application:
Femtocell applications vary significantly in their deployment scale and the critical nature of the connectivity they provide, from individual homes to large public spaces.
- Corporate Facilities:These deployments provide dedicated, high-capacity mobile coverage within business premises, supporting mission-critical enterprise applications and private networks. The United States and China show high demand for these solutions, driven by digital transformation initiatives.
- Public Venues:Femtocells enhance connectivity in stadiums, airports, and shopping malls, improving guest experience and operational efficiency for high-density user environments. European cities like London and Paris are prioritizing these deployments to accommodate large crowds.
- Residential:These femtocells extend mobile coverage within homes, improving voice quality and data speeds for individual users in areas with poor macro signal.
- Small Office/Home Office:SOHO deployments offer reliable cellular connectivity for small businesses, supporting essential communication needs with dedicated bandwidth.
- Educational Institutions:Universities and schools deploy femtocells to ensure ubiquitous mobile coverage for students and staff across large campus environments.
Corporate Facilities represent a significant segment for revenue generation, with Public Venues demonstrating accelerating growth in new deployments.
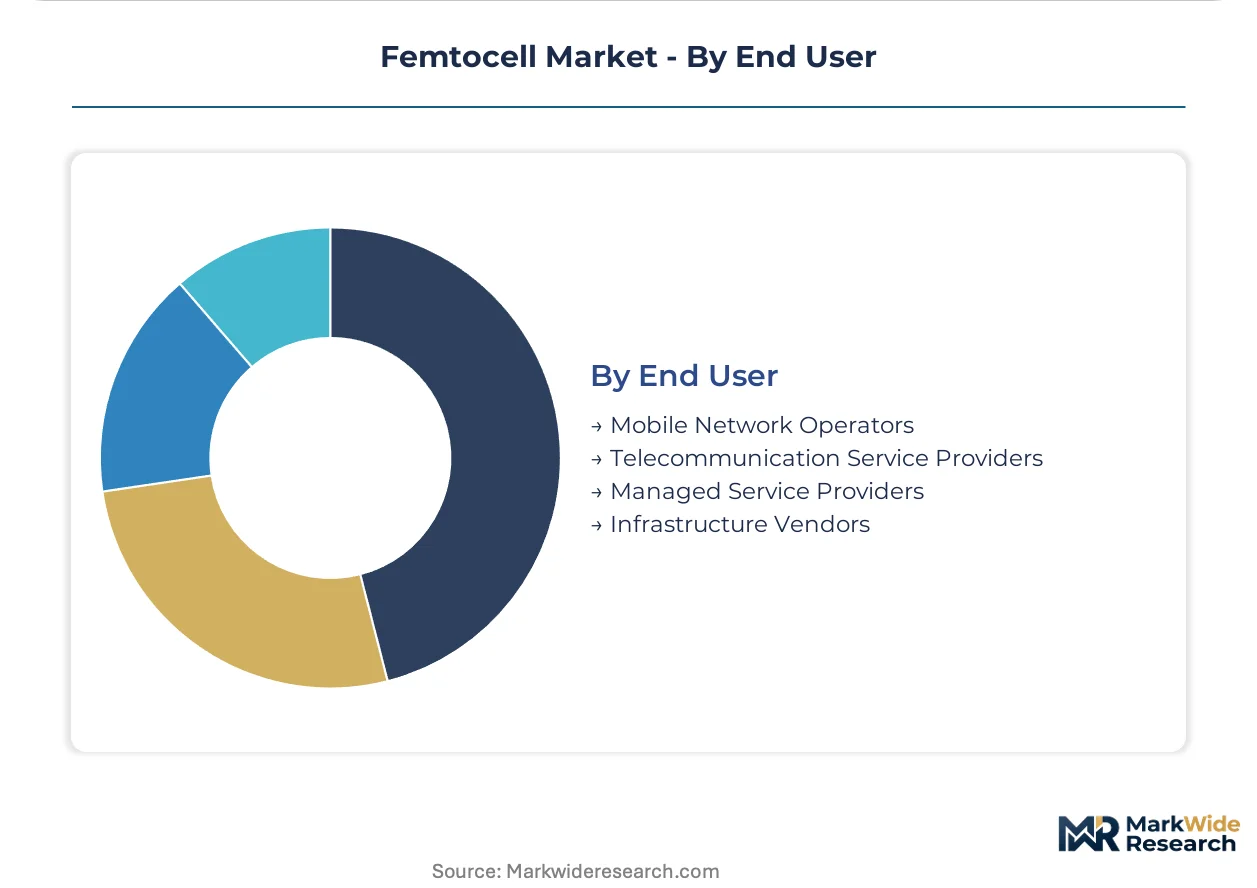
End User:
The end-user landscape for femtocells reflects the diverse stakeholders involved in delivering and managing cellular connectivity, from network operators to service providers.
- Mobile Network Operators:These entities deploy femtocells directly to enhance their network coverage and capacity, particularly in indoor environments and urban densification zones. Operators in India and Brazil are investing heavily to improve service quality and reach new subscribers.
- Managed Service Providers:MSPs offer femtocell solutions as part of a broader network-as-a-service package, handling deployment and ongoing management for enterprises. This model gains traction in North America and Western Europe, where businesses seek outsourced IT solutions.
- Telecommunication Service Providers:These providers offer a range of communication services, integrating femtocells to bolster their mobile offerings and improve customer satisfaction.
- Infrastructure Vendors:These companies supply the hardware and software components for femtocell deployments, often partnering with operators and service providers globally.
Mobile Network Operators remain the primary purchasers, while Managed Service Providers are rapidly expanding their market footprint through flexible service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption patterns for femtocells vary significantly across global regions, reflecting diverse infrastructure priorities and regulatory environments. While some nations prioritize enterprise-grade solutions for industrial applications, others focus on broad consumer coverage. This differential approach shapes investment flows and technological adoption rates worldwide.
United States
Demand for enterprise femtocells is high, driven by the need for secure private 5G networks in corporate facilities. The FCC actively manages spectrum allocation and interference, ensuring network stability. Silicon Valley and other tech hubs are seeing significant deployments for advanced enterprise connectivity.
China
The push for 5G network densification accelerates demand for integrated femtocell solutions, particularly in urban centers. China's MIIT sets stringent standards for network access equipment, influencing product development. Major cities like Shanghai and Shenzhen are focal points for extensive 5G small cell rollouts.
Germany
Enterprise-grade femtocells are critical for industrial settings, supporting mission-critical applications in manufacturing. CE marking directives apply to femtocell components, ensuring product safety and compliance across the European Union. Industrial clusters in Bavaria and North Rhine-Westphalia are implementing private 5G networks.
Japan
The rapid adoption of 5G technology drives significant demand for integrated femtocells to enhance urban coverage. METI initiatives support the development of advanced telecommunications infrastructure, including small cell deployments. Tokyo and Osaka are experiencing intensive densification efforts for high-speed mobile connectivity.
India
Mobile Network Operators heavily invest in femtocells to improve service quality and extend reach to new subscribers. TRAI regulations guide spectrum usage and network expansion, promoting broader connectivity. Major metropolitan areas like Mumbai and Delhi are targets for extensive network coverage enhancements.
Femtocell Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the femtocell market. This tiered structure reflects the capital intensity of telecommunications infrastructure and the necessity for specialized component expertise. Strategic archetypes include large network equipment vendors offering comprehensive solutions, specialized chipset developers influencing device performance, and enterprise solution providers integrating femtocells into corporate IT. Companies pursue strategic partnerships and portfolio diversification to enhance their market presence and address evolving 5G requirements.
Within the ecosystem, Ericsson exemplifies the integrated network equipment vendor archetype, leveraging its extensive carrier relationships to deploy comprehensive solutions for mobile network operators. Qualcomm, a US-based corporation, dominates the underlying chipset technology, influencing device-level performance and features across multiple vendors. Cisco Systems, another US-based company, positions its enterprise-grade femtocells for seamless integration with existing corporate IT infrastructure, specifically targeting large business clients. These entities collectively shape the technological direction and deployment strategies for femtocell solutions, reflecting distinct approaches to market penetration.
| Leading Market Players |
|---|
| Huawei Technologies |
| Qualcomm |
| Nokia Corporation |
| Fujitsu Ltd. |
| Ericsson |
| Samsung Electronics |
| ZTE Corporation |
| CommScope Inc. |
| Cisco Systems |
| Others |
Cost & Logistics Intelligence
Six-month lead times for advanced 5G femtocell chipsets directly impact the cost structure and downstream pricing power for network equipment manufacturers. This dependency shapes the availability and cost of integrated solutions for mobile network operators.
Pricing Analysis
Project-based contracts define large-scale enterprise femtocell deployments, while subscription models gain traction for managed services offerings. Pricing stratifies across premium, standard, and economy tiers based on integrated features like onboard AI optimization and security capabilities. Pricing softness stems from intense competition among specialized component suppliers, particularly in the chipset and software segments. Mobile Network Operators and enterprise clients requiring private 5G networks exhibit lower price sensitivity compared to residential users.
Supply Chain Analysis
Concentrated chipset manufacturing in a few global hubs underpins the femtocell supply chain, creating potential single-source vulnerabilities for critical components. Geographic supply heavily draws from the United States, China, and South Korea for advanced processors and radio frequency modules. Raw material dependencies include specialized semiconductors and high-frequency antenna arrays. A structural risk is the reliance on a limited number of foundries for cutting-edge 5G components. Distribution runs through established channels like Mobile Network Operators and a growing ecosystem of Managed Service Providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The femtocell market represents an early-cycle expansion story, driven by the accelerating global rollout of 5G network densification initiatives. This foundational demand creates significant opportunities across the value chain.
For Market Incumbents:Consolidate core carrier relationships by offering comprehensive, integrated femtocell solutions that span hardware, software, and managed services. Defend market share against specialized Open RAN component suppliers by deepening proprietary software capabilities and advanced AI optimization. Leverage extensive carrier ties to secure long-term contracts for 5G network densification projects, particularly in urban centers and corporate facilities. Invest in R&D for next-generation 5G-Advanced and 6G technologies to maintain a competitive edge.
For New Entrants and Emerging Players:Differentiate on specialized Open RAN-compliant hardware and software solutions, targeting modularity and interoperability. White-space opportunities exist in developing AI-driven radio frequency optimization algorithms and security management platforms for distributed femtocell networks. The chipset and software segments for Open RAN architectures represent the most penetrable market. Partner with system integrators and managed service providers to accelerate market penetration with flexible "network-as-a-service" offerings.
For Investors and Strategic Acquirers:Carve-out targets emerge from large network equipment vendors shedding non-core femtocell software or specialized hardware divisions. The market offers long-term viability, driven by persistent demand for indoor 5G coverage and private networks over the next decade. Acquisition archetypes include specialized chipset developers, AI-driven network optimization software firms, and managed service providers with strong enterprise client bases. A key signal to watch is the increasing adoption rate of Open RAN standards by Tier 1 mobile network operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification | Expands revenue streams by offering integrated femtocell solutions for diverse applications. |
| Open RAN Partnership | Fosters interoperability and accelerates market access for specialized component suppliers. |
| Managed Services Expansion | Captures recurring revenue from enterprises seeking "network-as-a-service" connectivity. |
| AI Integration | Enhances device functionality through real-time optimization and predictive traffic management. |
| Geographic Market Entry | Taps into new demand from countries with accelerating 5G infrastructure rollouts. |
Research Approach
Operator-level perspectives from mobile network planning directors, enterprise IT procurement leads, and specialized component vendors anchored the qualitative base for this study. Primary interviews with telecommunication service providers and managed service executives were triangulated with extensive secondary research. Secondary data sources included regulatory filings from the FCC and MIIT, CE marking directives, and financial reports of major infrastructure vendors. This approach ensured robust bottom-up data collection and top-down market validation.
Sensitivity analyses informed the quantitative forecast framework, assessing market evolution across the analysis window. The model segmented femtocell demand by product type, underlying technology, primary application, and end-user category, alongside regional 5G infrastructure maturity. Compound annual growth rates were derived from historical deployment trends and projected densification requirements. Key forecast inputs included global 5G rollout acceleration and Open RAN adoption rates.
Material uncertainties — including evolving spectrum allocation policies and unforeseen regulatory compliance timelines — sit outside the modeled envelope. Forecasts reflect a comprehensive set of assumptions regarding technological advancements and market dynamics. Practitioners should keep alternative scenarios live as 5G infrastructure investment patterns and enterprise adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Optical Wireless Communication and Li-Fi Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Wimax Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Underwater Wireless Communication Market