
 5G Wireless Ecosystem Market | 2026-2036
5G Wireless Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
5G Wireless Ecosystem Market Analysis
Silicon-germanium is broadening its displacement of gallium arsenide in 5G radio-frequency front-end modules, cutting material costs while preserving millimeter-wave performance. Qualcomm leverages integrated modem-antenna designs to sustain technology leadership in sub-6 GHz and mmWave chipsets. Nokia anchors European infrastructure supply through its Open RAN portfolio, while Crown Castle controls the largest US shared wireless infrastructure footprint.
The 5G Wireless Ecosystem comprises the integrated hardware, software, and services enabling fifth-generation cellular networks operating across sub-1 GHz, sub-6 GHz, and 24–100 GHz frequency bands with sub-millisecond latency targets. Its primary purpose is to deliver enhanced mobile broadband, ultra-reliable low-latency communication, and massive machine-type connectivity for industrial digitization. Massive MIMO dominates capital expenditure in macro cell deployments due to spectral efficiency gains, while network slicing concentrates margin pools by enabling operator revenue differentiation across enterprise verticals. Private network deployments within the Deployment Model dimension represent the fastest-growing structural category as manufacturers and ports pursue captive connectivity.
The Federal Communications Commission governs spectrum allocation and auction mechanics that directly determine carrier deployment timelines and infrastructure vendor addressable markets in the United States. The European Telecommunications Standards Institute coordinates 5G technical specifications with national regulators such as Germany's Federal Network Agency to harmonize cross-border equipment certification. Stakeholders must monitor Open RAN interoperability mandates and mid-band spectrum reallocation proceedings to anticipate vendor repositioning and capital cycle timing.
Market Dynamics
Massive MIMO deployment economics are compressing per-bit transmission costs while fragmenting vendor margins across hardware commoditization and software value-add differentiation.
Growth Catalysts
- EU AI Act connectivity mandates:Industrial automation in Germany requires deterministic low-latency links, forcing manufacturers to deploy captive 5G infrastructure rather than rely on public network service-level agreements.
- Millimeter-wave spectrum densification:Urban corridors in South Korea demonstrate that 28 GHz small-cell grids can sustain factory-floor robotics without fiber backhaul to every access point.
- Silicon-germanium process migration:RF front-end foundries are converting gallium arsenide capacity to SiGe CMOS, cutting bill-of-materials overhead for sub-6 GHz and mmWave modules simultaneously.
Market Restraints
- Gallium nitride substrate scarcity:Power amplifier foundries face allocation constraints for high-electron-mobility transistors used in macro cell base stations, extending lead times for 64T64R antenna shipments.
- Mid-band spectrum auction mechanics:The Federal Communications Commission's staggered release of C-band blocks creates deployment timing uncertainty that freezes carrier capex commitments until contiguous bandwidth clarity emerges.
- Open RAN interoperability friction:Disaggregated baseband-to-radio interfaces delay multi-vendor integration testing, compressing deployment windows for operators with aggressive coverage targets.
Strategic Opportunities
- Indian manufacturing corridor captive networks:The country's Production-Linked Incentive scheme for electronics assembly creates demand for licensed 5G spectrum in Tamil Nadu and Karnataka industrial zones.
- Network slicing monetization:Automotive OEMs in Stuttgart and Wolfsburg are contracting guaranteed latency tiers for over-the-air firmware delivery, opening recurring revenue streams beyond connectivity resale.
- Terahertz research convergence:Laboratory trials combining photonic integrated circuits with electronic beamforming are positioning 140 GHz as the successor frequency band for indoor factory automation.
Industry Challenges
- RF systems integration talent scarcity:Base station OEMs compete for engineers with compound semiconductor packaging experience, particularly for thermal management of GaN-on-SiC power stages.
- Legacy 4G core interworking complexity:Non-standalone architectures require dual-mode operation that doubles software maintenance overhead during the transition window.
- CE marking timeline compression:European Telecommunications Standards Institute certification queues for new radio equipment categories extend validation cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Wireless Ecosystem Market |
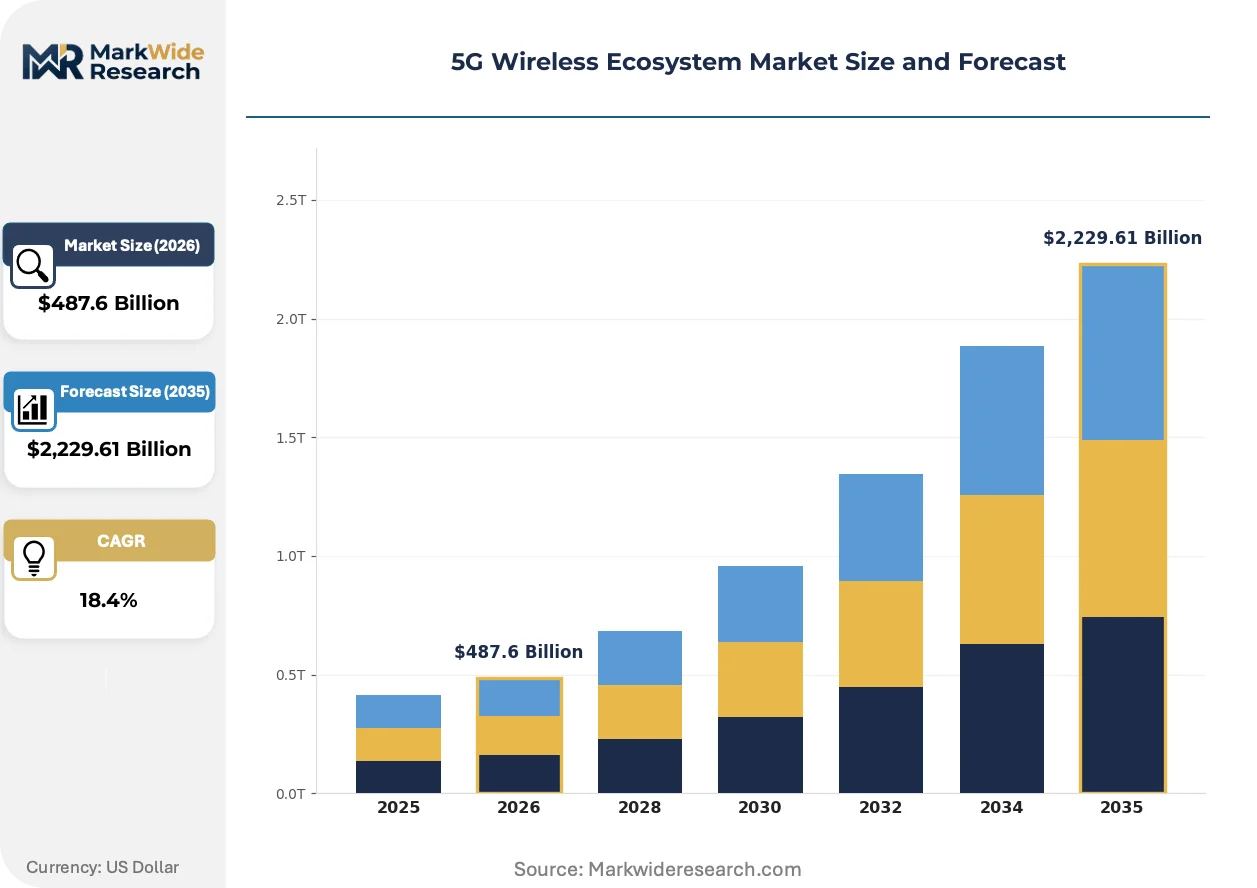
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $2,229.61 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NR, Massive MIMO, Beamforming, Network Slicing End User: Telecom Operators, Enterprises, Government, Consumers Deployment Model: Private Network, Public Network, Hybrid Network, On-Premises Application: IoT, Smart Cities, Autonomous Vehicles, AR/VR |
| Companies Covered | Verizon, T-Mobile US, Qualcomm, Crown Castle, American Tower, Ericsson, AT&T, Skyworks Solutions, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Wireless Ecosystem Market Emerging Trajectories
Open RAN disaggregation is fragmenting traditional integrated vendor positions while creating entry points for specialized software and hardware suppliers across the protocol stack.
Silicon-germanium BiCMOS is overtaking gallium arsenide pHEMTs in millimeter-wave beamformer chips. Automotive radar suppliers in Bavaria and Texas are converting their SiGe process flows to 5G infrastructure applications, exploiting existing 130 nm and 90 nm fab lines. This material transition is collapsing RF front-end cost curves for 28 GHz and 39 GHz deployment bands.
The European Telecommunications Standards Institute's tightened electromagnetic exposure guidelines are forcing base station OEMs to redesign active antenna systems with lower effective isotropic radiated power density. Urban planners in Milan and Barcelona are rejecting macro cell permits that exceed revised Specific Absorption Rate thresholds. Equipment vendors are responding with narrower beamwidth arrays and tilt-optimized radiation patterns.
Enterprise procurement of private 5G networks is consolidating through systems integrators rather than direct carrier relationships. Port operators in Rotterdam and Hamburg are contracting turnkey connectivity from industrial automation specialists who bundle spectrum licenses, core software, and radio access network hardware. This channel shift is marginalizing traditional wholesale revenue models for mobile network operators in heavy-asset verticals.
5G Wireless Ecosystem Market Segmentation
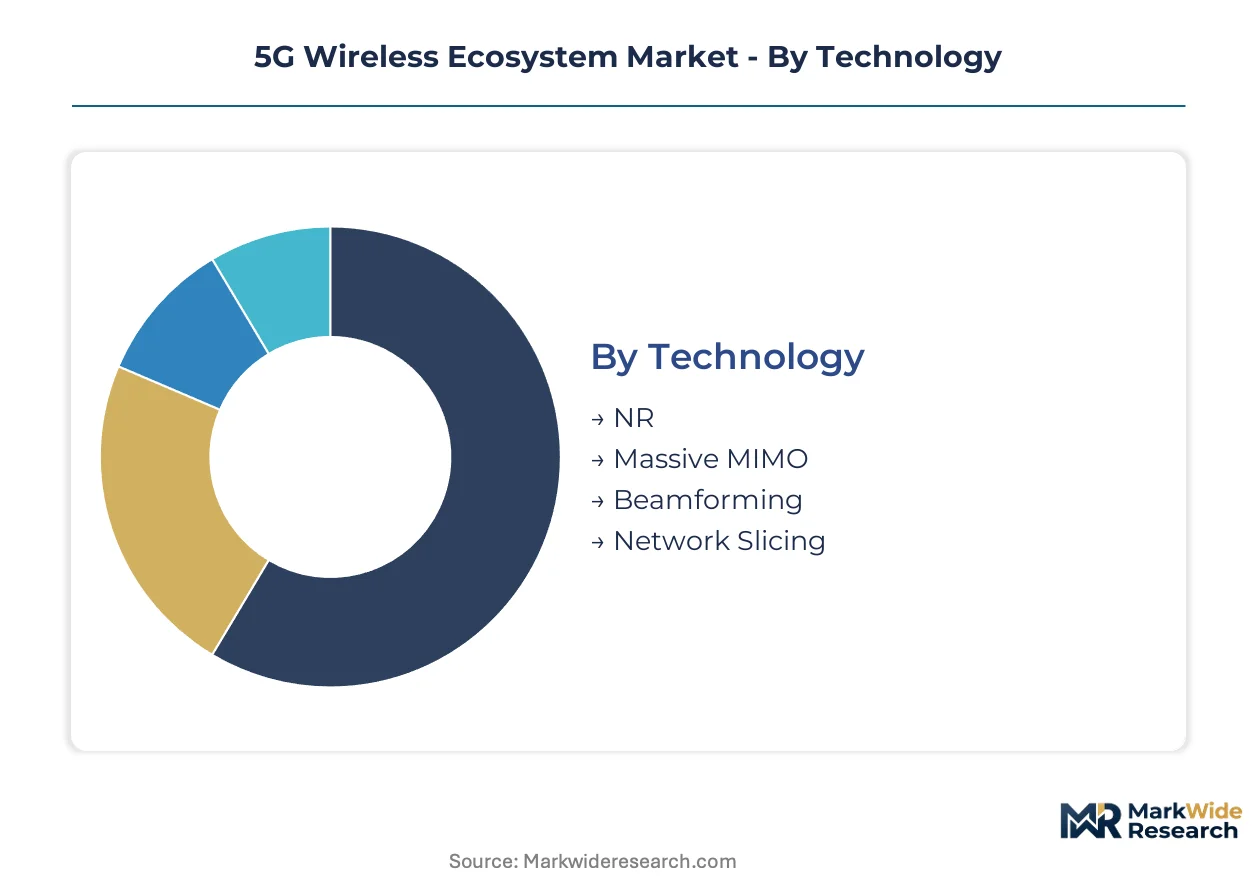
5G ecosystem segmentation reveals how capital allocation fragments across infrastructure layers, with technology choices locking in decade-long vendor relationships and deployment models determining margin capture between carriers and enterprise integrators. Each dimension carries distinct regulatory exposure and competitive intensity profiles that reshape strategic positioning.
Technology:
Supply concentration in RF semiconductor foundries and baseband silicon vendors concentrates margin capture at specific technology layers, with patent thickets around beamforming algorithms creating defensive moats for early movers.
- NR:The 3GPP-defined New Radio interface specifies sub-6 GHz and mmWave physical layer protocols with flexible numerology for diverse latency requirements. German automotive suppliers in Stuttgart and Wolfsburg are mandating NR Release 16 URLLC implementations for factory-floor robotics, driving foundry capacity allocation toward time-sensitive networking chipsets.
- Massive MIMO:Active antenna systems deploy 64T64R configurations with 3D beamforming to multiply spectral efficiency in sub-6 GHz bands. South Korean carriers have operationalized nationwide 64T64R grids, consuming gallium nitride power amplifier output that extends lead times for European macro cell deployments.
- Beamforming:Digital and hybrid analog-digital architectures steer radiation patterns toward user equipment, reducing interference in dense urban corridors.
- Network Slicing:Virtualized core-to-radio resource partitioning enables guaranteed service tiers for industrial automation contracts.
Today's leader: Massive MIMO. Tomorrow's challenger: Network Slicing.
End User:
Customer type determines procurement channel structure, with enterprise buyers consolidating through systems integrators while government tenders impose localization mandates that fragment vendor addressable markets.
- Telecom Operators:Mobile network operators deploy macro and small-cell infrastructure under spectrum license obligations, with capex cycles tied to auction timing and shareholder dividend policy. Verizon and AT&T in the United States are prioritizing C-band mid-band rollout, while Deutsche Telekom balances fiber backhaul investment against Open RAN migration costs.
- Enterprises:Manufacturing, logistics, and energy firms procure captive 5G infrastructure to bypass public network service-level agreement limitations. Port operators in Rotterdam and Hamburg are contracting turnkey private networks from industrial automation specialists, marginalizing traditional carrier wholesale models.
- Government:Defense and public safety agencies require encrypted, sovereign-controlled infrastructure with domestic supply chain certification.
- Consumers:Smartphone and fixed wireless access subscribers generate volume demand that funds infrastructure amortization but captures minimal enterprise margin pools.
Enterprise procurement is climbing the fastest, while consumer revenue per connection flattens.
Deployment Model:
Physical infrastructure ownership structure determines regulatory compliance burden and operational flexibility, with spectrum licensing frameworks varying sharply across jurisdictions.
- Private Network:Captive radio access network and core infrastructure operated by license holders for exclusive facility coverage. Smart manufacturing facilities in Germany are accelerating deployments under EU AI Act connectivity mandates that require deterministic low-latency links for industrial automation.
- Public Network:Carrier-operated infrastructure with roaming agreements and wholesale enterprise access.
- Hybrid Network:Shared radio access network with partitioned core resources blending public coverage with private control.
- On-Premises:Fully localized small-cell and edge computing infrastructure without wide area network dependency.
Private networks currently absorb the steepest expansion trajectory in manufacturing verticals.
Application:
Use case specificity drives performance requirements that cascade through chipset, antenna, and core architecture selections, with latency and reliability tiers determining addressable contract value.
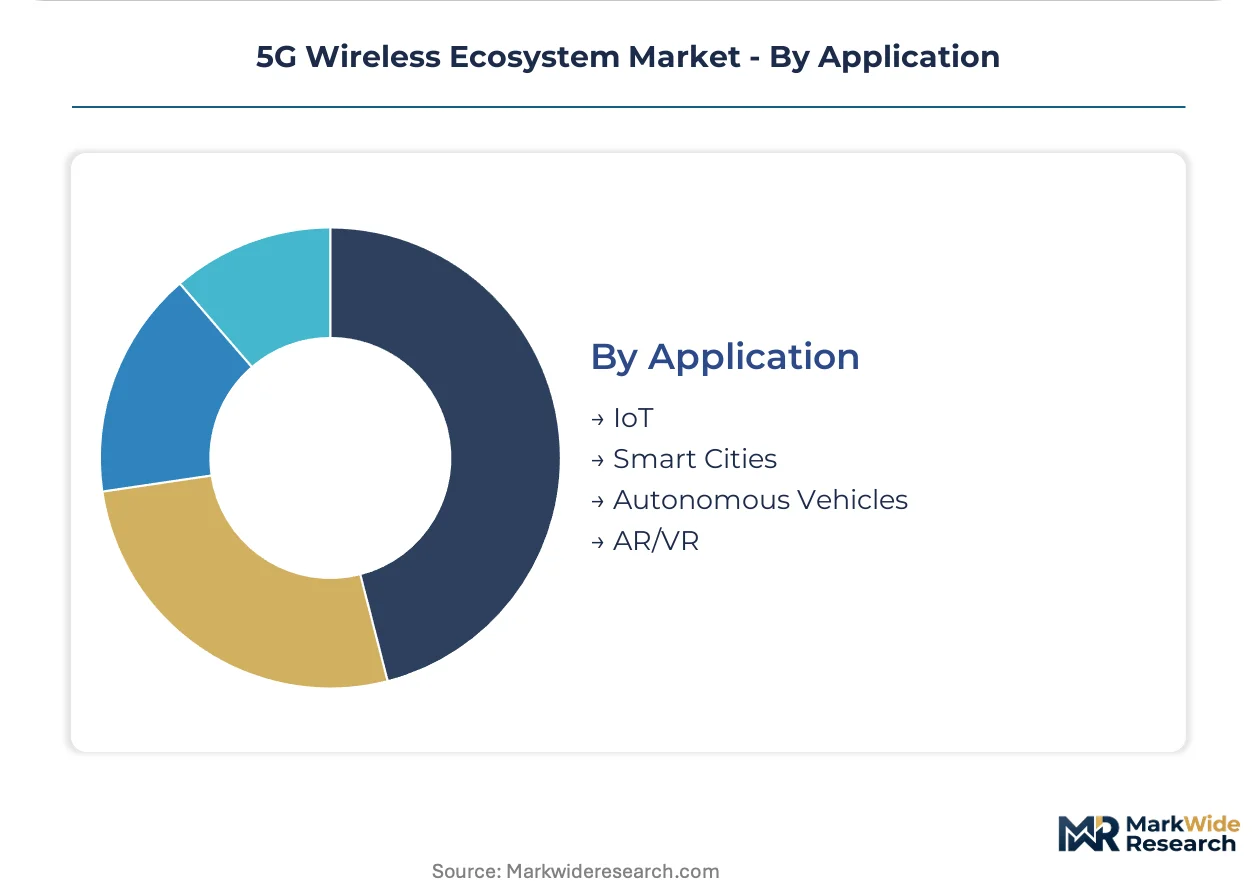
- IoT:Massive machine-type communications connect sensors and actuators with extended battery life and deep indoor penetration. Agricultural monitoring networks in California's Central Valley and industrial predictive maintenance systems in Bavaria are deploying narrowband-IoT and RedCap variants over 5G standalone cores.
- Smart Cities:Integrated traffic management, environmental monitoring, and public safety networks require dense small-cell deployment.
- Autonomous Vehicles:Vehicle-to-everything communications demand sub-10 millisecond latency for collision avoidance and traffic coordination.
- AR/VR:Immersive media and enterprise training applications consume sustained downlink bandwidth with minimal jitter.
IoT volume scales fastest, though autonomous vehicles promise the highest per-connection contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Wolfsburg anchor industrial 5G demand through automotive automation requirements, while regulatory frameworks across four major economies reshape deployment timelines and vendor access.
United States
Verizon and AT&T drive C-band mid-band rollout priorities, with carrier capex cycles tied to FCC auction mechanics. The Federal Communications Commission governs spectrum allocation and staggered C-band block releases that freeze deployment commitments until contiguous bandwidth clarity emerges. Urban corridors in New York and Los Angeles demonstrate millimeter-wave small-cell densification for fixed wireless access.
Germany
Smart manufacturing facilities accelerate private network deployments under EU AI Act connectivity mandates requiring deterministic low-latency links. The Federal Network Agency coordinates with ETSI to harmonize cross-border equipment certification. Stuttgart automotive suppliers mandate NR Release 16 URLLC implementations for factory-floor robotics, driving foundry capacity allocation toward time-sensitive networking chipsets.
South Korea
Samsung and SK Telecom operationalized nationwide millimeter-wave infrastructure for industrial automation. The country's national telecommunications regulator oversees spectrum licensing frameworks that enable 28 GHz small-cell grids sustaining factory-floor robotics without fiber backhaul to every access point. Seoul metropolitan deployment showcases 64T64R Massive MIMO configurations consuming gallium nitride power amplifier output.
India
The Production-Linked Incentive scheme for electronics assembly creates demand for licensed 5G spectrum in Tamil Nadu and Karnataka industrial zones. TRAI governs auction mechanics and private network licensing terms. Port operators in Mumbai and Chennai are contracting turnkey connectivity from industrial automation specialists who bundle spectrum licenses with core software.
Japan
METI coordinates 5G technical specifications with national spectrum allocation for industrial digitization. Automotive OEMs in Toyota City and Yokohama are contracting guaranteed latency tiers for over-the-air firmware delivery. Kanto region deployment concentrates Massive MIMO capital expenditure due to spectral efficiency gains in dense urban corridors.
5G Wireless Ecosystem Market Vendor Landscape
Global majors compete with regional champions across infrastructure supply, with carrier-affiliated tower operators and independent wireless infrastructure specialists fragmenting addressable markets. The vendor base stratifies between integrated base station OEMs, semiconductor foundries, and shared infrastructure asset owners. Three archetypes dominate: spectrum-license holders with captive deployment scale, RF component specialists with process technology differentiation, and neutral-host infrastructure platforms. Consolidation concentrates through tower asset acquisitions and Open RAN software partnerships.
Among US-based carriers, Verizon and T-Mobile US occupy positions as spectrum-license anchors with captive deployment scale. Qualcomm exemplifies the RF semiconductor archetype through integrated modem-antenna designs. Crown Castle represents the neutral-host infrastructure model controlling shared wireless footprint. Nokia anchors European supply through its Open RAN portfolio, while Ericsson sits within the integrated base station OEM tier. These five entities collectively span the value chain from spectrum to silicon to physical infrastructure.
| Leading Market Players |
|---|
| Verizon |
| T-Mobile US |
| Qualcomm |
| Crown Castle |
| American Tower |
| Ericsson |
| AT&T |
| Skyworks Solutions |
| Nokia |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate spot prices cascade through RF power amplifier foundries into tiered equipment procurement contracts, compressing margins for macro cell base station OEMs while concentrating pricing power with compound semiconductor suppliers in Taiwan and the United States.
Pricing Analysis
Input-cost pass-through from silicon-germanium wafer contracts and GaN-on-SiC substrate allocations shapes three-tier pricing structure across premium, standard, and economy levels in radio access network equipment. Certification grade under ETSI and FCC equipment authorization tiers differentiates vendor quotations, with urban carriers in Seoul and New York showing lowest price sensitivity due to spectrum scarcity premiums. Pricing pressure stems from Open RAN disaggregation commoditizing baseband hardware, while rural deployment projects in India exhibit highest buyer price sensitivity due to government tender mechanics.
Supply Chain Analysis
India's Production-Linked Incentive scheme and domestic-content mandates in South Korea's smart factory initiatives are reshaping sourcing patterns for 5G radio units and core network software. Supply concentrates in Taiwan for advanced RF foundry capacity, South Korea for memory and display integration, and Germany for precision mechanical components in active antenna systems. Gallium nitride substrates, silicon-germanium wafers, and high-frequency laminates constitute critical input dependencies. Single-source vulnerability in GaN epitaxy capacity creates structural risk. Distribution runs through systems integrators for enterprise private networks and direct carrier procurement for public infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
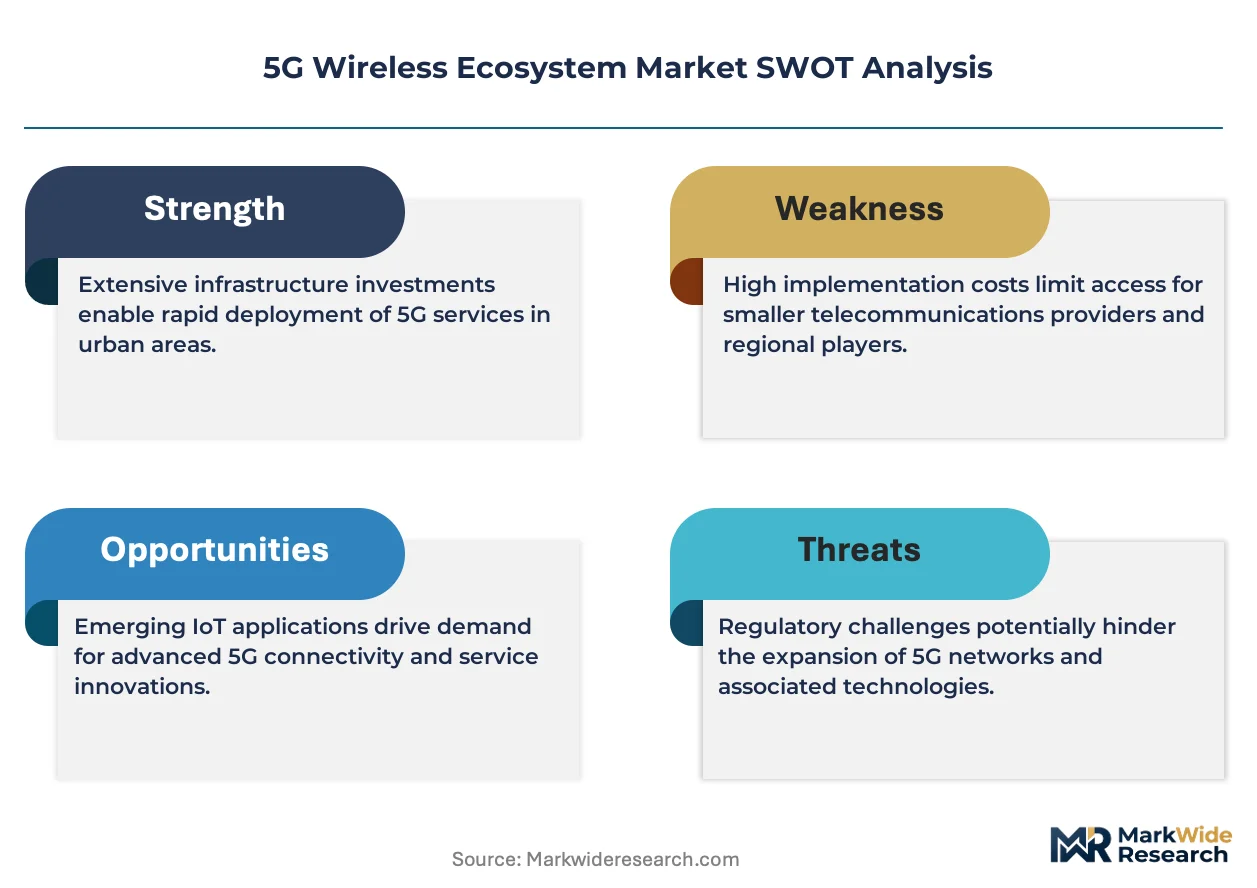
The 5G Wireless Ecosystem operates as a regulatory compounder where EU AI Act connectivity mandates and FCC spectrum auction mechanics compound deployment timing into vendor selection lock-ins.
For Market Incumbents: Hedge against Open RAN interoperability friction by accelerating certification investment for multi-vendor integration testing. Secure backward integration into gallium nitride substrate supply through long-term offtake agreements with Taiwanese foundries, defending against emerging RF semiconductor specialists capturing share in millimeter-wave beamformer segments.
For New Entrants and Emerging Players: Capture white-space in Indian manufacturing corridor captive networks where TRAI private network licensing creates fresh procurement channels outside incumbent carrier relationships. Target port automation integrators in Rotterdam and Hamburg with turnkey spectrum-core-radio bundles, exploiting marginalization of traditional wholesale models.
For Investors and Strategic Acquirers: Asymmetric upside sits with neutral-host infrastructure platforms controlling shared wireless footprint in dense urban corridors. Five-to-ten year viability favors asset owners with tower and small-cell real estate positions over equipment OEMs facing hardware commoditization. Monitor FCC mid-band spectrum reallocation proceedings as inflection signal for carrier capex commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Software Partnership | ETSI interoperability mandates in Germany force multi-vendor integration capabilities. |
| GaN Substrate Supply Agreement | Taiwanese foundry allocation secures power amplifier output for 64T64R antenna shipments. |
| Private Network Turnkey Launch | EU AI Act mandates in Stuttgart automotive plants create deterministic latency contract demand. |
| Millimeter-Wave Small-Cell Deployment | Seoul metropolitan grids demonstrate 28 GHz factory-floor robotics without fiber backhaul. |
| Spectrum License Portfolio Expansion | TRAI auctions in Tamil Nadu industrial zones enable captive electronics manufacturing connectivity. |
Methodological Framework
Bottom-up enterprise procurement modeling reconciled against top-down RF semiconductor foundry capacity tracking forms the analytical core. Primary interviews with base station OEM procurement directors, carrier network planning executives, industrial automation systems integrators, and ETSI certification engineers combined with secondary validation from FCC auction records, 3GPP release documentation, and SEC carrier capex disclosures. Triangulation across deployment data from South Korean national regulator filings and Indian TRAI spectrum allocation announcements anchored volume estimates.
Historical trendline analysis of Massive MIMO deployment cycles and private network licensing velocity informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology layer, deployment model ownership structure, end-user procurement channel, and application latency tier. CAGRs derived from equipment shipment run-rates reconciled against carrier spectrum spend commitments. Foundry capacity utilization rates and Open RAN software release timelines served as industry-specific forecast inputs.
Regulatory timeline slippage, compound semiconductor substrate allocation shocks, and Open RAN interoperability testing delays are the dominant revision risks. Forecasts reflect documented assumptions on spectrum auction completion and equipment certification queue durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Multefire Market
Wireless Technologies
Wigig Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market