
 Global Open Radio Access Network (Oran) Market | 2026-2036
Global Open Radio Access Network (Oran) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Open Radio Access Network (Oran) Market Foresight
Open RAN project finance and vendor-neutral leasing structures are rewriting competitive entry barriers for infrastructure suppliers. Mavenir leverages software-centric business models to compete without captive hardware manufacturing. Samsung Electronics anchors its position through backward integration into semiconductor fabrication for radio units. Nokia sustains R&D intensity across multi-vendor interoperability labs spanning three continents.
Open Radio Access Network denotes a disaggregated cellular architecture separating hardware and software functions via open, standardized interfaces, typically operating below 6 GHz with sub-10 millisecond latency targets for macro and small-cell deployments. The primary purpose is enabling multi-vendor interoperability while reducing carrier capital expenditure through modular procurement. Radio units and centralized units capture the dominant margin pools as physical layer processing demands specialized silicon. Software components represent the fastest-expanding segment as containerized network functions displace proprietary embedded systems. Edge computing applications within the technology dimension are concentrating demand from smart factory deployments requiring localized traffic processing.
The O-RAN Alliance specifications, the EU's Radio Equipment Directive mandating open interfaces, and Japan's MIC spectrum allocation frameworks collectively shape vendor certification requirements and procurement eligibility across three continents. FCC Part 27 rules in the United States condition market access on demonstrated multi-vendor interoperability testing. Stakeholders must monitor whether national security review processes fragment standardization momentum or accelerate regional specification forks.
Market Dynamics
Carrier procurement departments are dismantling single-vendor lock-in through mandatory O-RAN compliance clauses in base station tenders, forcing incumbents to expose previously proprietary interfaces.
Growth Catalysts
- Japan's MIC spectrum frameworks:Tokyo's allocation rules for local 5G bands mandate open interface certification, accelerating disaggregated radio unit deployment by NTT Docomo and KDDI.
- Smart factory edge computing:German automotive manufacturers require sub-10 millisecond processing for robotic coordination, driving private network builds using multi-vendor RAN stacks.
- Containerized network functions:Kubernetes-orchestrated baseband software is displacing embedded proprietary systems, enabling cloud-native scaling across distributed radio sites.
Market Restraints
- Specialized silicon concentration:Radio unit semiconductors depend on a narrow supplier base in Taiwan and South Korea, exposing procurement to foundry capacity constraints.
- Interoperability testing costs:Multi-vendor integration labs require sustained capital outlays that smaller carriers cannot absorb, consolidating deployment capability among Tier-1 operators.
- Legacy hardware stranded assets:Existing macro cell installations use integrated baseband-radio architectures that resist modular retrofit without full site replacement.
Strategic Opportunities
- India's enterprise 5G corridors:Reliance Jio and Bharti Airtel are building private networks for Ahmedabad-Mumbai industrial zones with government production-linked incentives for domestic radio unit assembly.
- AI-driven RAN optimization:Machine learning inference at distributed units for real-time beamforming represents an unclaimed software margin pool beyond basic connectivity.
- Neutral host infrastructure:Stadium and airport operators in Brazil are procuring open RAN as shared service platforms, bypassing traditional carrier ownership models.
Industry Challenges
- Embedded systems engineering scarcity:The talent pool for Layer 1 physical layer optimization is concentrated at incumbent vendors, constraining new entrant hiring.
- Fragmented security certification:Each national regulator applies distinct supply chain audit standards, multiplying compliance timelines for multi-country deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Open Radio Access Network (Oran) Market |
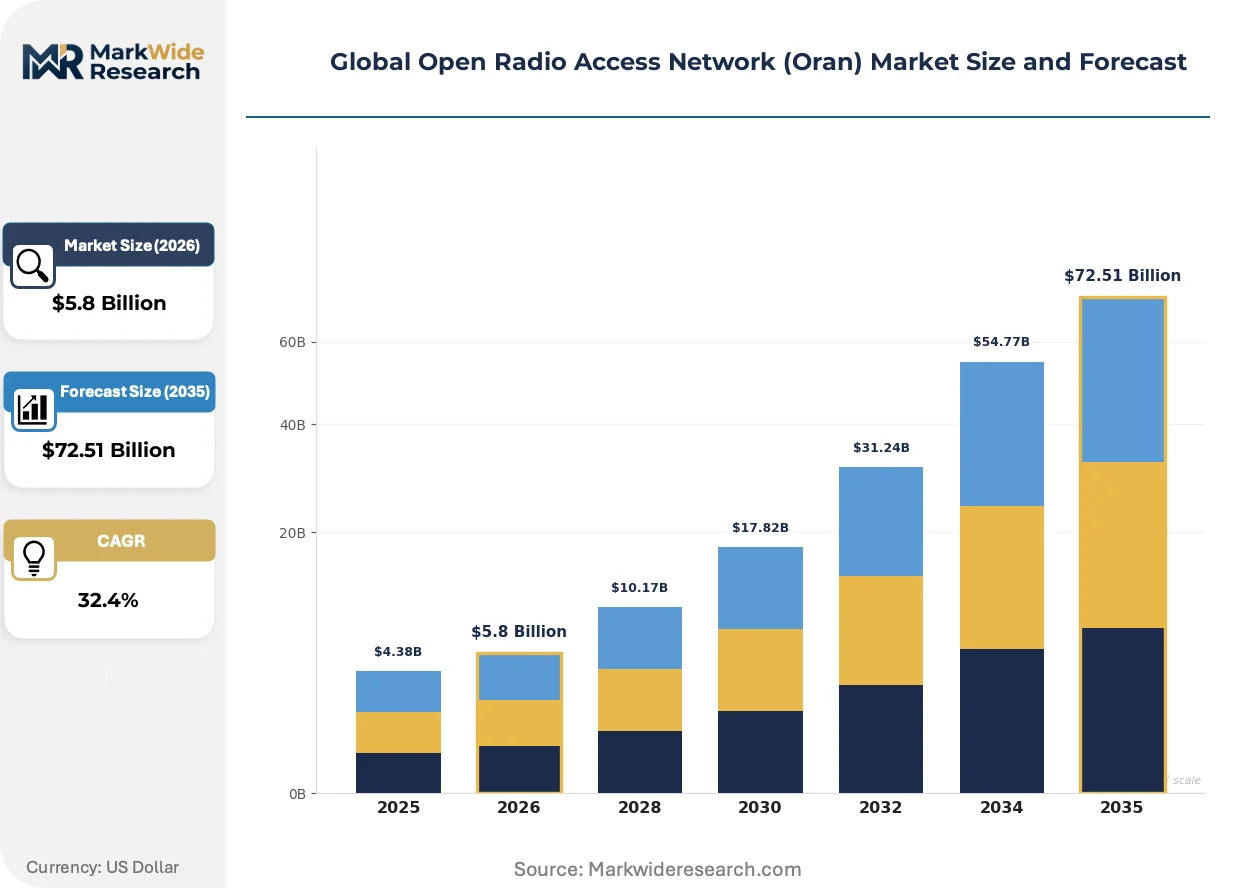
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $72.51 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Radio Units, Distributed Units, Centralized Units, Software, Hardware Technology: Massive MIMO, Beamforming, Network Slicing, Cloud RAN, Edge Computing Application: Smart Cities, Smart Factories, Public Safety, Transportation, Agriculture End User: Tier-1 Carriers, Network Integrators, Infrastructure Vendors, System Operators, Service Providers |
| Companies Covered | Ericsson, Nokia, Samsung Electronics, NEC Corporation, Mavenir, Fujitsu, ZTE Corporation, Parallel Wireless, Casa Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Open Radio Access Network (Oran) Market Shifts & Advancements
Software-defined architectures are compressing hardware refresh cycles while regulatory mandates in major economies force interface disclosure that was previously guarded as competitive advantage.
Massive MIMO antenna arrays with 64+ elements are hybridizing digital beamforming with analog RF chains to reduce power consumption at macro sites. Deutsche Telekom is deploying these in dense urban cells across Berlin and Munich. This hybridizing approach is collapsing the traditional boundary between antenna hardware and baseband processing, enabling vendors without captive semiconductor fabrication to compete on algorithmic differentiation.
The EU's Radio Equipment Directive now mandates open interface disclosure for all radio equipment placed on the European market, with enforcement delegated to notified bodies in Germany and France. This forces incumbent suppliers to document previously proprietary control plane protocols. Small-cell vendors targeting campus networks in Rotterdam and Barcelona are exploiting this transparency to displace integrated solutions with modular procurement.
Carrier technical evaluation committees now require live multi-vendor interoperability demonstrations before contract award, replacing paper specification compliance. This behavior compresses vendor selection timelines while elevating systems integration capability above standalone product performance. The shift is most visible in Japanese carrier procurement, where Rakuten Mobile's open RAN architecture has reset supplier evaluation norms for NTT and KDDI sourcing teams.
Global Open Radio Access Network (Oran) Market Segmentation
Open RAN procurement patterns diverge sharply across component types, with hardware refresh cycles spanning years while software releases iterate monthly. Understanding these temporal mismatches helps vendors align inventory planning against carrier deployment timelines.
Component:
Radio Units turn over slowest due to site access costs and weatherproofing requirements, while Software updates deploy continuously via container orchestration.
- Radio Units:Outdoor-hardened remote radio heads and active antenna units handle RF transmission and reception. Deutsche Telekom's Berlin deployments source these from multi-vendor pools, though foundry constraints in Taiwan and South Korea limit supply elasticity.
- Software:Containerized baseband functions running on commercial-off-the-shelf servers enable cloud-native scaling. Kubernetes-orchestrated releases displace embedded proprietary systems fastest where Rakuten Mobile's architecture has reset procurement norms in Japan.
- Distributed Units:Mid-haul processing nodes aggregate traffic from multiple radio units.
- Centralized Units:Pool baseband resources across distributed sites for statistical multiplexing gains.
- Hardware:Server racks, switches, and power systems supporting disaggregated RAN workloads.
Radio Units dominate installed base. Software is where expansion concentrates fastest.
Technology:
Cost tiers separate proven macro-cell technologies from emerging campus-network capabilities requiring premium integration support.
- Massive MIMO:64-element antenna arrays with hybrid analog-digital beamforming slash power consumption at dense urban macro sites. Deutsche Telekom deploys these across Munich's high-traffic zones, collapsing traditional boundaries between antenna hardware and baseband processing.
- Edge Computing:Localized compute nodes process traffic within 10 milliseconds for robotic coordination in German automotive plants. Smart factory demand in Stuttgart and Wolfsburg drives private network builds using multi-vendor stacks with this capability embedded.
- Beamforming:Dynamic antenna pattern shaping improves spectral efficiency and coverage.
- Network Slicing:Virtual network partitions isolate traffic classes with differentiated quality-of-service guarantees.
- Cloud RAN:Centralized baseband pooling across distributed radio sites.
Massive MIMO captures dominant capital expenditure. Edge Computing claims the steepest expansion trajectory as manufacturing automation accelerates.
Application:
Volume concentration varies by deployment maturity, with industrial sites scaling faster than municipal infrastructure constrained by procurement bureaucracy.
- Smart Factories:Private 5G networks for robotic coordination and predictive maintenance. German automotive manufacturers in Bavaria require sub-10 millisecond latency, driving modular RAN procurement that bypasses traditional carrier ownership models.
- Smart Cities:Integrated sensor networks for traffic management and environmental monitoring. Barcelona and Rotterdam small-cell vendors exploit EU Radio Equipment Directive transparency to displace integrated solutions with modular campus builds.
- Public Safety:Mission-critical voice and data networks for emergency services.
- Transportation:Vehicle-to-infrastructure connectivity for logistics and autonomous systems.
- Agriculture:Precision farming applications with wide-area coverage requirements.
Smart Factories lead current deployment velocity. Smart Cities hold larger addressable footprint once procurement cycles accelerate.
End User:
Customer type determines integration burden, with Tier-1 carriers absorbing complexity that smaller buyers must outsource.
- Tier-1 Carriers:NTT Docomo and KDDI in Japan operate multi-vendor interoperability labs across three continents, sustaining R&D intensity that consolidates deployment capability among capital-rich operators.
- Network Integrators:Systems specialists stitch heterogeneous vendor components into functional networks. These players gain relevance as live interoperability demonstrations replace paper compliance in carrier technical evaluation committees.
- Infrastructure Vendors:Suppliers of radio, compute, and transport equipment.
- System Operators:Neutral host providers managing shared infrastructure for multiple tenants.
- Service Providers:Managed service and outsourcing firms operating RAN on behalf of license holders.
Tier-1 Carriers anchor current procurement volume. Network Integrators are gaining share fastest as multi-vendor complexity fragments vendor selection patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in Open RAN equipment reveal asymmetric trade flows, with specialized radio unit semiconductors flowing from East Asian foundries toward carrier deployment sites in Western Europe and North America. Component assembly concentrates in contract manufacturing hubs serving multiple end markets simultaneously.
United States
FCC Part 27 rules condition market access on demonstrated multi-vendor interoperability testing, accelerating carrier procurement reform. National security review processes through CFIUS shape vendor certification timelines for infrastructure sourced from foreign suppliers. Deployment clusters concentrate in Texas and California where cloud-native network integration expertise pools near hyperscaler data centers.
Germany
Deutsche Telekom's campus networks drive private 5G adoption across automotive manufacturing corridors. The EU's Radio Equipment Directive mandates open interface disclosure for all radio equipment, with enforcement delegated to notified bodies in Berlin and Munich. Stuttgart and Wolfsburg industrial zones require sub-10 millisecond latency for robotic coordination, anchoring modular RAN procurement.
Japan
NTT Docomo and KDDI operate multi-vendor interoperability labs sustaining R&D intensity that consolidates deployment capability. MIC spectrum allocation frameworks for local 5G bands mandate open interface certification, accelerating disaggregated radio unit deployment. Tokyo and Osaka carrier procurement teams now require live interoperability demonstrations before contract award.
India
Reliance Jio and Bharti Airtel are building private networks for Ahmedabad-Mumbai industrial zones with government production-linked incentives for domestic radio unit assembly. TRAI spectrum policy frameworks encourage technology-neutral equipment procurement. Bengaluru and Hyderabad host systems integration specialists stitching heterogeneous vendor components into functional networks.
South Korea
Samsung Electronics anchors regional supply through backward integration into semiconductor fabrication for radio units. MFDS-equivalent telecommunications equipment certification maintains rigorous interoperability standards. Seoul metropolitan carrier procurement absorbs multi-vendor complexity that smaller regional operators must outsource to network integrators.
Global Open Radio Access Network (Oran) Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated conglomerates with captive semiconductor fabrication, software-centric challengers competing without hardware manufacturing, and specialist integrators assembling multi-vendor stacks. Dominant competitive moves include strategic partnerships for interoperability certification and geographic expansion through carrier-direct sales organizations replacing traditional distribution channels.
Among Nordic-heritage infrastructure vendors, Ericsson and Nokia occupy positions within the integrated conglomerate archetype, sustaining R&D intensity across multi-vendor interoperability labs. Samsung Electronics exemplifies the fabrication-backed model through its semiconductor unit supplying radio unit silicon. Mavenir sits within the software-centric tier, leveraging containerized network functions to compete without captive hardware manufacturing.
| Leading Market Players |
|---|
| Ericsson |
| Nokia |
| Samsung Electronics |
| NEC Corporation |
| Mavenir |
| Fujitsu |
| ZTE Corporation |
| Parallel Wireless |
| Casa Systems |
| Others |
Supply & Pricing Matrix
Taiwanese and South Korean foundry concentration for radio unit semiconductors anchors margin capture downstream at distributed unit vendors and software orchestration layers. This upstream bottleneck forces procurement arbitrage between captive silicon supply and modular multi-vendor stacks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in campus network deployments. Price differentiation stems from certification grade under FCC Part 27 interoperability mandates and volume scale in multi-site carrier rollouts. Pricing pressure stems from containerized network functions displacing proprietary embedded systems, compressing software licensing premiums. Tier-1 carriers exhibit lowest price sensitivity due to R&D absorption capacity, while neutral host operators in Brazil and India face acute cost compression.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung Electronics anchors radio unit semiconductor supply, with backend assembly concentrated in Chinese and Vietnamese contract manufacturing hubs. Raw material dependencies span gallium nitride substrates, high-frequency laminates, and precision RF connectors. Single-source vulnerability in Taiwanese 7nm and 5nm foundry nodes exposes procurement to geopolitical disruption. Distribution runs through carrier-direct procurement teams and systems integrators stitching multi-vendor stacks for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN procurement patterns reveal software maintenance and interoperability certification as recurring-revenue layers expanding faster than hardware refresh cycles. Container orchestration services and multi-vendor integration support now claim margin pools beyond initial equipment sale.
For Market Incumbents: Entrench through backward integration into semiconductor fabrication and sustained R&D intensity across multi-vendor interoperability labs spanning three continents. Incumbents must neutralize software-centric challengers by exposing proprietary interfaces under EU Radio Equipment Directive mandates while defending radio unit margin pools through captive silicon supply.
For New Entrants and Emerging Players: India's enterprise 5G corridors present the most penetrable white-space opportunity, with production-linked incentives for domestic radio unit assembly lowering entry barriers. New entrants should target neutral host infrastructure in Brazilian stadiums and airports, deploying Kubernetes-orchestrated baseband software without captive hardware manufacturing. Go-to-market execution requires partnership with systems integrators capable of live interoperability demonstrations.
For Investors and Strategic Acquirers: Capital is best deployed toward software-centric challengers with containerized network function portfolios and systems integrators assembling multi-vendor stacks. Long-term viability over a multi-year horizon favors vendors with demonstrated O-RAN Alliance certification and carrier-direct sales organizations replacing traditional distribution channels. The signal to monitor is Tier-1 carrier procurement committee requirements for live interoperability demonstrations replacing paper specification compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Interoperability Certification | O-RAN Alliance testing resets procurement eligibility for NTT Docomo and KDDI sourcing teams. |
| Containerized Network Function Development | Kubernetes-orchestrated baseband software displaces proprietary embedded systems at Rakuten Mobile. |
| Backward Integration into Semiconductor Fabrication | Samsung Electronics anchors radio unit supply through captive silicon production for 5G massive MIMO arrays. |
| Geographic Expansion via Carrier-Direct Sales | Deutsche Telekom campus network procurement in Stuttgart and Wolfsburg favors direct vendor relationships. |
| Strategic Partnership for Systems Integration | Network integrators gain relevance as live interoperability demonstrations replace paper compliance in Japanese carrier evaluation. |
Research Methodology
A standing panel of carrier procurement executives, O-RAN Alliance technical committee members, semiconductor foundry planning officers, and enterprise network architects provided ongoing calibration against primary field intelligence. Secondary validation drew from FCC Part 27 filings, EU Radio Equipment Directive enforcement notices, MIC spectrum allocation frameworks, TRAI policy consultations, and SEC disclosures from listed infrastructure vendors. Bottom-up component demand modeling triangulated against top-down carrier capex forecasts across the analysis window.
Scenario bracketing anchored volume and value outputs across component, technology, application, and end-user segmentation dimensions. Deployment velocity curves for radio units versus software releases were modeled separately given divergent refresh cycles. CAGRs derived from carrier procurement pipeline visibility, foundry capacity expansion announcements, and regulatory mandate implementation timelines. Industry-specific inputs included O-RAN Alliance specification release schedules and national security review process durations affecting vendor certification.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed challengers or state-sponsored infrastructure vendors would shift outcomes beyond modeled ranges. Quarterly review of carrier interoperability lab investment levels and foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wi-Fi Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Near Field Communication Market