
 Wifi Kiosks Market | 2026-2036
Wifi Kiosks Market Size, Share, and Industry Trends Forecast 2026-2036
Wifi Kiosks Market Analytics
Market Context
Southeast Asia is reshaping regional supply chains for wifi kiosk assembly and component sourcing as manufacturers relocate capacity from higher-cost bases. NCR Corporation leverages its legacy in financial self-service terminals to anchor retail and hospitality kiosk portfolios across North America. Diebold Nixdorf sustains a differentiated position through integrated security modules and ATM-to-kiosk technology transfer. Fujitsu Limited competes on manufacturing scale in Asia-Pacific, where its production facilities supply both domestic operators and export markets.
Technical Definition and Segment Structure
A wifi kiosk is a networked, freestanding or mounted terminal that integrates wireless connectivity, touchscreen interfaces, and peripheral modules—receipt printers, card readers, barcode scanners, cameras—to deliver self-service transactions, information retrieval, or digital signage playback in commercial and public environments. Self-service kiosks dominate current revenue as quick-service restaurants and grocery chains deploy ordering and payment terminals to reduce labor dependency and compress transaction times. Interactive kiosks represent the fastest-expanding product category, driven by museum, healthcare, and municipal deployments where wayfinding and appointment scheduling applications deepen user engagement. Cloud-based technology architectures capture growing preference over on-premises installations, since centralized device management, over-the-air firmware updates, and usage analytics reduce total cost of ownership for operators managing dispersed kiosk fleets.
Regulatory Environment and Outlook
The Federal Communications Commission governs radio frequency emissions and wireless certification for kiosk deployments in the United States, while the Americans with Disabilities Act mandates touchscreen height, audio output, and tactile interface standards that shape product design. In Europe, the Ecodesign for Sustainable Products Regulation and REACH chemical restrictions influence enclosure materials and component recyclability, compelling manufacturers to requalify supply chains. The Payment Card Industry Data Security Standard applies across jurisdictions, dictating encryption, tokenization, and physical tamper-evidence requirements for any kiosk processing card transactions. Stakeholders must monitor evolving accessibility mandates and cybersecurity disclosure rules as procurement specifications harden and liability frameworks expand.
Market Dynamics
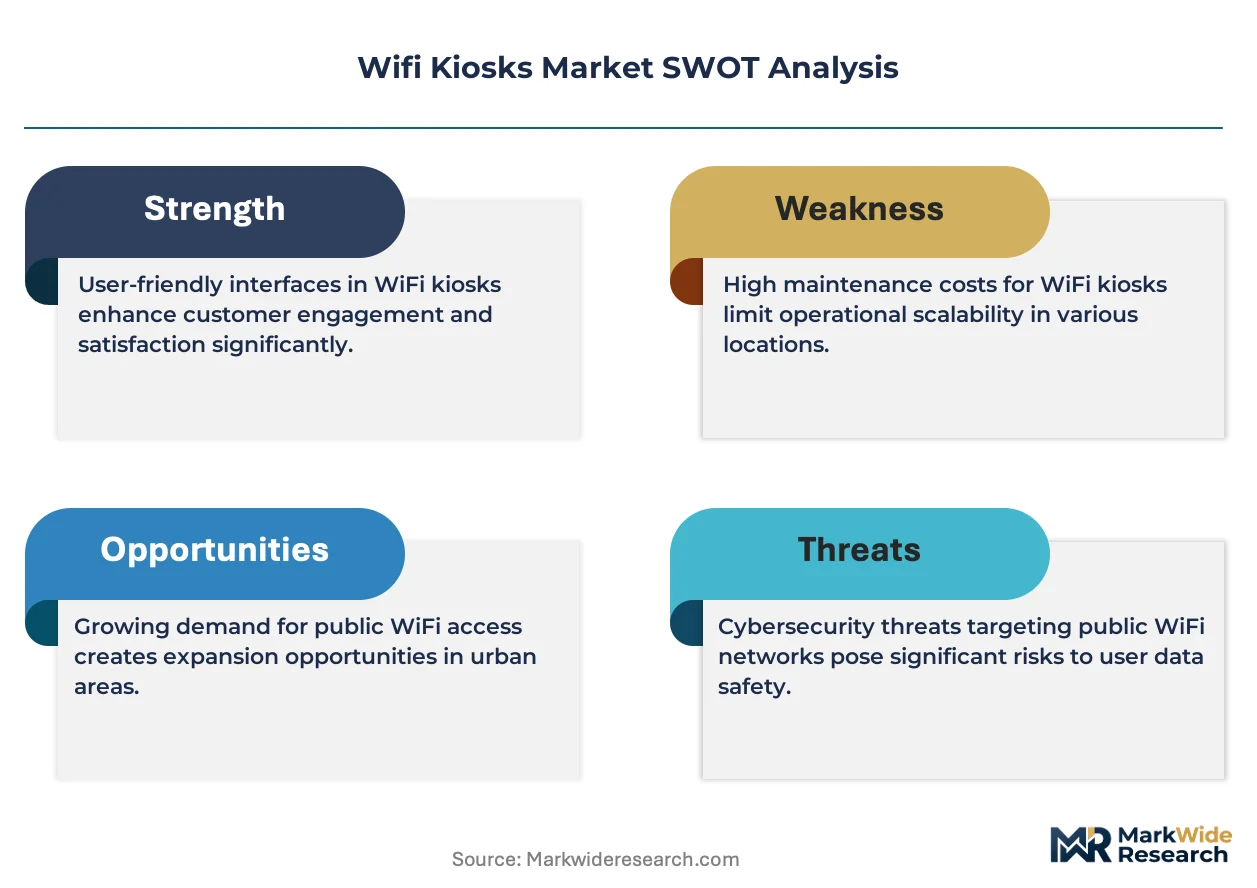
PCI-DSS compliance mandates and ADA accessibility standards are compressing vendor qualification timelines, forcing kiosk manufacturers to re-engineer hardware architectures before procurement windows close.
Growth Catalysts
- Airport modernization mandates:United States transit authorities are expanding self-service baggage tag deployments, tightening specifications around wireless certification and physical accessibility.
- REACH chemical restrictions:European Ecodesign for Sustainable Products Regulation is accelerating enclosure material requalification, creating replacement demand for compliant component supply chains.
- Quick-service automation:Restaurant chains are deploying connected ordering terminals to compress transaction times and reduce front-of-house labor dependency.
Market Restraints
- Semiconductor supply concentration:Touch controller and wireless module fabrication concentrates in Taiwan and South Korea, exposing assembly lines to geographic disruption risk.
- Aluminum enclosure cost volatility:Input price swings for kiosk housing materials compress margin predictability for mid-tier manufacturers.
- FCC certification timelines:Radio frequency approval processes in the United States extend product launch schedules by six to nine months.
Strategic Opportunities
- Rural healthcare wayfinding:Underserved United States medical facilities present untapped deployment potential for interactive appointment-scheduling terminals.
- Cloud-native fleet management:Over-the-air firmware update capabilities are converging with usage analytics platforms to reduce total cost of ownership for dispersed operators.
- IRA energy incentives:United States infrastructure funding is subsidizing municipal digital signage networks that integrate wifi kiosk nodes.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for peripheral integration—receipt printers, card readers, barcode scanners—outpaces available talent pools.
- Multi-jurisdiction certification stacking:Simultaneous FCC, CE marking, and BIS compliance requirements fragment testing budgets and timelines.
- Legacy POS integration complexity:Quick-service restaurant operators face middleware development costs when connecting new kiosk terminals to established payment backbones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wifi Kiosks Market |
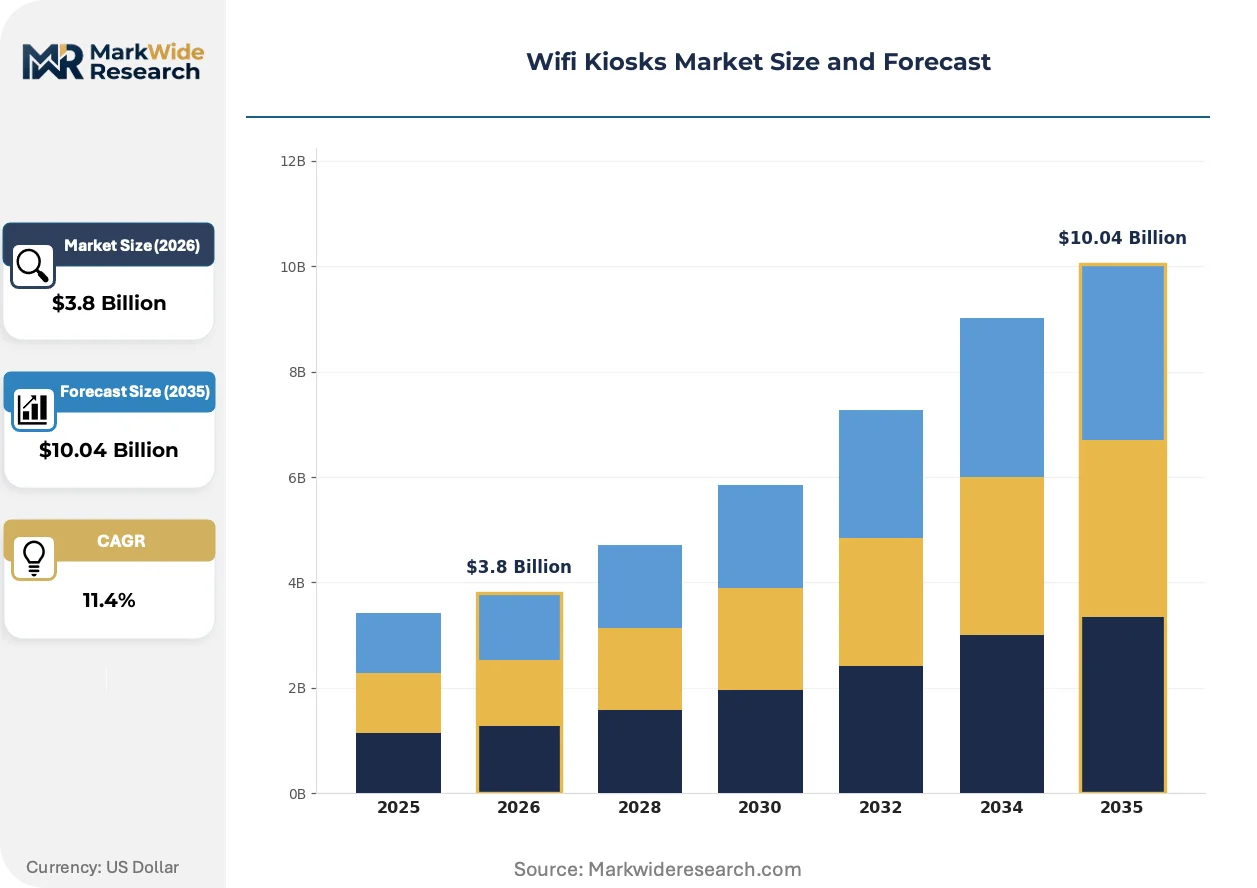
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Interactive Kiosks, Digital Signage Kiosks, Ticketing Kiosks End User: Retail Stores, Airports, Restaurants, Public Utilities Technology: Cloud-Based, On-Premises, Hybrid, Open Source Installation: Indoor, Outdoor, Portable, Wall-Mounted |
| Companies Covered | NCR Corporation, Diebold Nixdorf, Fujitsu Limited, GLORY Ltd., Olea Kiosks Inc., KIOSK Information Systems, Meridian Kiosks, Acrelec, Kontron AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wifi Kiosks Market Evolving Landscape
Touchscreen interface architectures and wireless connectivity modules are undergoing rapid consolidation, compressing hardware footprints while expanding software-defined functionality across deployment environments.
Edge computing capabilities embedded directly into kiosk terminals are collapsing the latency between user input and system response. Quick-service restaurant operators in the United States are adopting these configurations to support real-time menu personalization and inventory-aware ordering. This compression is eliminating the need for dedicated on-premises server rooms at individual store locations.
Europe's Ecodesign for Sustainable Products Regulation is mandating recyclability disclosures and restricted substance documentation for all networked terminal enclosures. Manufacturers serving German and French procurement channels are requalifying aluminum suppliers and redesigning chassis for disassembly. Healthcare and museum segments are responding fastest, as public-sector tenders now embed circularity scoring into award criteria.
Outcome-based service contracts are displacing traditional hardware purchase models among United States airport operators and municipal transit authorities. Under these arrangements, kiosk vendors retain asset ownership and charge per-transaction or per-passenger fees, transferring uptime risk from buyer to supplier. This shift is most visible in California and Texas transit districts, where capital budget constraints favor operational expenditure structures.
Wifi Kiosks Market Segmentation
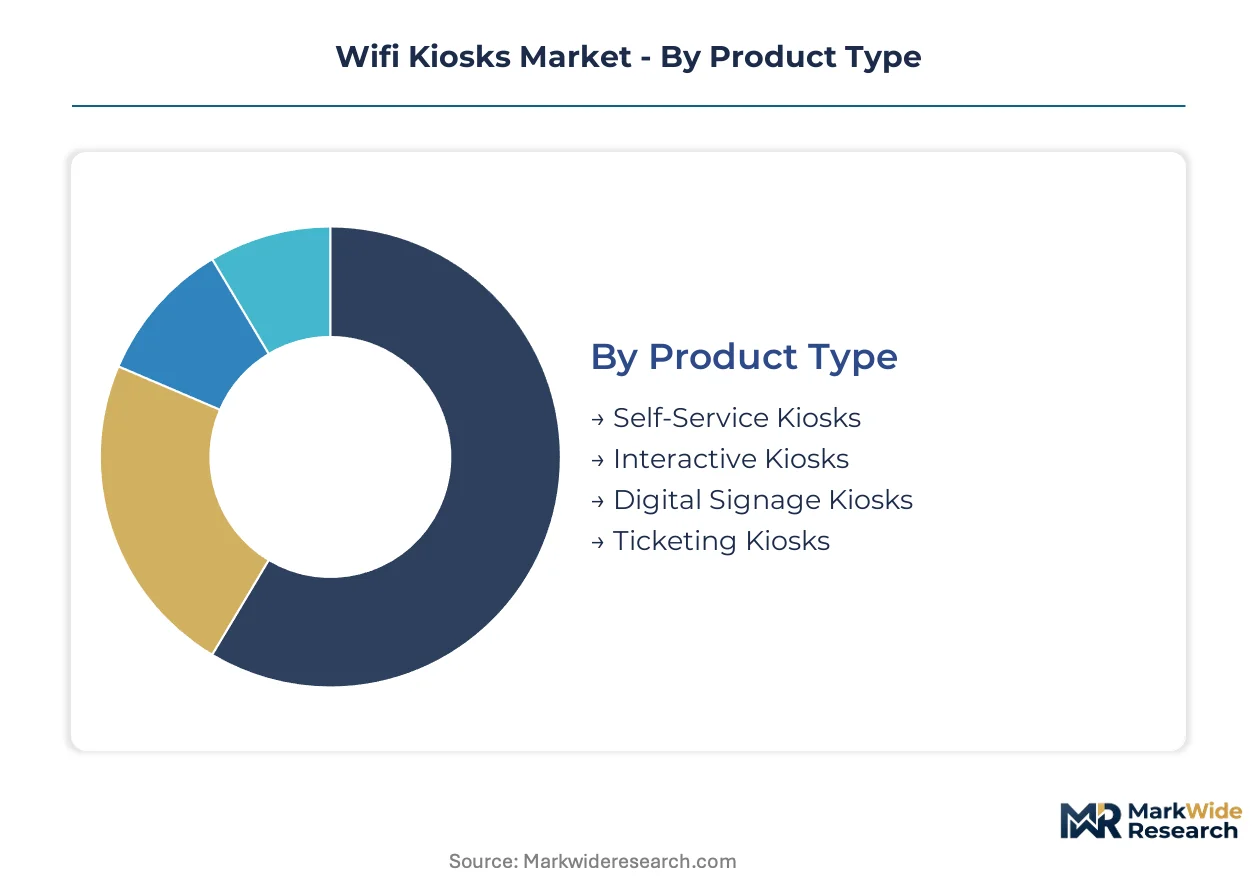
Segmentation in the wifi kiosk market reveals divergent procurement cycles and replacement velocities across product architectures. Operators balance upfront capital outlays against fleet management complexity when selecting configurations for specific deployment environments.
Product Type:
Replacement cycles stretch from three years for high-traffic transactional terminals to seven-plus years for passive digital signage, compressing vendor revenue predictability in shorter-cycle segments.
- Self-Service Kiosks:Integrated ordering and payment terminals with thermal printers, card readers, and barcode scanners. Quick-service restaurants in the United States deploy these most aggressively to reduce front-of-house labor, though PCI-DSS recertification demands accelerate refresh timelines.
- Interactive Kiosks:Wayfinding and appointment-scheduling terminals with capacitive touch overlays and audio output modules. Museums and rural healthcare facilities drive demand as ADA accessibility mandates harden procurement specifications around tactile interface standards.
- Digital Signage Kiosks:Content playback terminals prioritizing display brightness and thermal management over peripheral integration.
- Ticketing Kiosks:Transit and entertainment entry terminals with embedded NFC readers and receipt printers for proof-of-purchase.
Self-service kiosks dominate installed base. Interactive kiosks are where expansion concentrates.
End User:
Customer concentration varies sharply by procurement sophistication and capital availability across deployment sectors.
- Airports:Baggage tag issuance and self-service check-in terminals governed by FAA wireless certification and ADA physical accessibility standards. United States transit authorities modernize these fleets fastest, with California and Texas districts favoring outcome-based service contracts over capital purchases.
- Restaurants:Connected ordering terminals compressing transaction times through menu personalization and inventory-aware recommendations. Cloud-native fleet management reduces total cost of ownership for dispersed quick-service operators.
- Retail Stores:Self-checkout and endless-aisle terminals facing middleware integration complexity with legacy POS backbones.
- Public Utilities:Bill payment and service request terminals in municipal buildings, subsidized by IRA energy incentives for digital infrastructure.
Airports anchor premium pricing tiers. Restaurants are expanding most quickly.
Technology:
Architecture selection determines ongoing operational expenditure structure and vulnerability to supply-side disruption.
- Cloud-Based:Centralized device management with over-the-air firmware updates and usage analytics. Quick-service chains and airport operators prefer this architecture for dispersed fleet visibility, though semiconductor concentration in Taiwan and South Korea creates geographic risk exposure.
- On-Premises:Local server dependency with higher upfront infrastructure investment but reduced connectivity failure modes.
- Hybrid:Edge processing for latency-sensitive transactions with cloud synchronization for analytics and updates.
- Open Source:Customizable software stacks favored by municipal procurement with strict total-cost-of-ownership constraints.
Cloud-based architectures lead new deployments. Hybrid configurations are gaining share fastest.
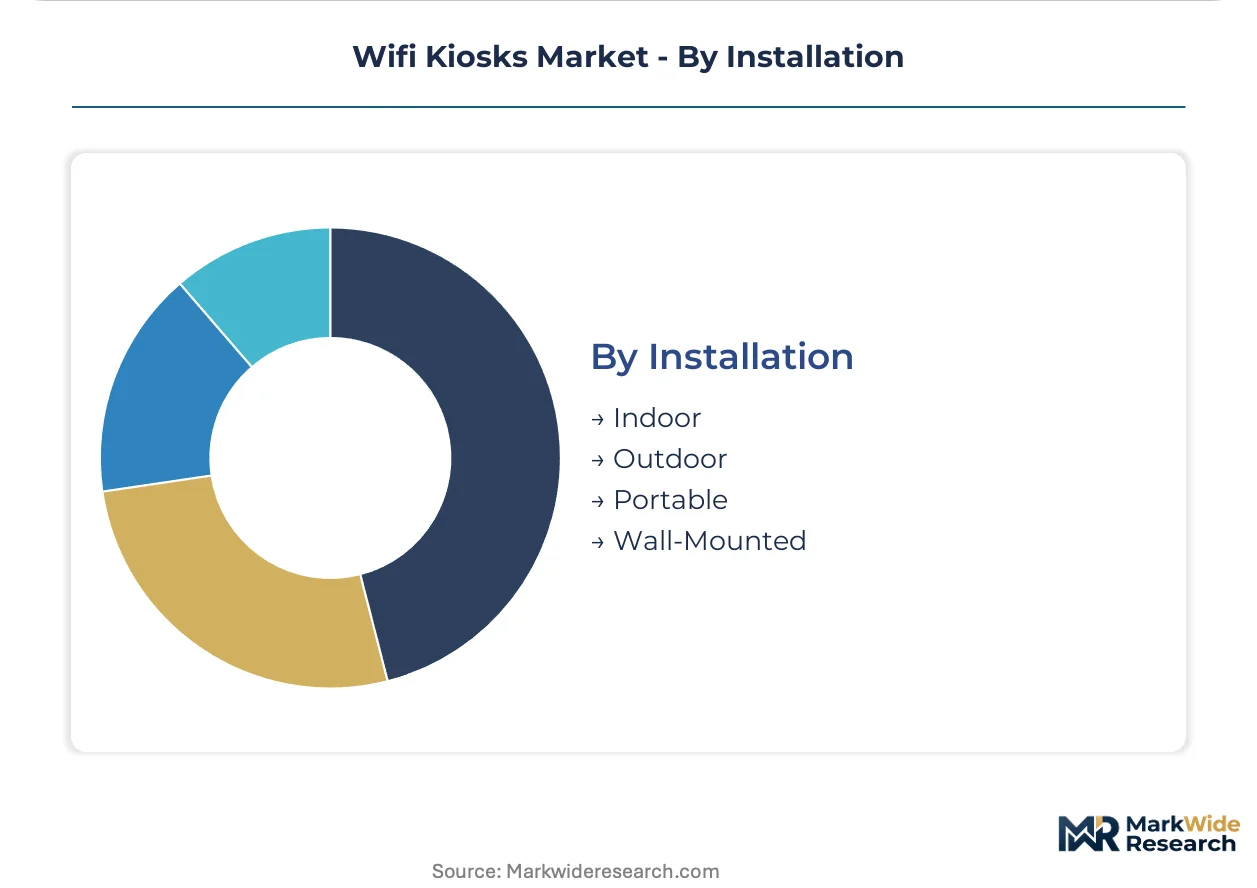
Installation:
Environmental exposure requirements and mobility needs fragment component sourcing and enclosure engineering.
- Indoor:Climate-controlled deployments with standard aluminum enclosures and reduced IP ratings. Museums and retail stores represent the volume base.
- Outdoor:Weather-hardened terminals with anti-glare displays, thermal management, and vandal-resistant housings. Transit authorities in Germany and France embed circularity scoring into tender criteria under Ecodesign regulation.
- Portable:Battery-powered or cart-mounted units for temporary event deployments and seasonal demand spikes.
- Wall-Mounted:Space-constrained installations in healthcare waiting areas and municipal lobbies with reduced footprint requirements.
Indoor installations dominate fleet scale. Outdoor configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: quick-service automation dominates United States deployment volumes, while European procurement prioritizes circularity compliance and Asian markets emphasize manufacturing scale and export logistics.
United States
Airport modernization and restaurant automation drive procurement volumes, with California and Texas transit authorities favoring outcome-based service contracts over capital purchases. The Federal Communications Commission governs wireless certification timelines that extend product launches by six to nine months. Chicago O'Hare and Dallas-Fort Worth anchor self-service baggage tag deployments with hardened ADA accessibility specifications.
China
Domestic transit authorities and export manufacturing capacity shape demand, with municipal digital infrastructure projects absorbing significant production volumes. The Ministry of Industry and Information Technology oversees GB standards compliance for wireless modules and touchscreen interfaces. The Yangtze River Delta manufacturing cluster supplies component assemblies for both domestic operators and international export markets.
Germany
Ecodesign for Sustainable Products Regulation mandates reshape enclosure material sourcing and supplier qualification requirements. The ECHA REACH framework restricts chemical substances in kiosk housings, compelling aluminum supplier requalification. Bavaria and North Rhine-Westphalia host procurement authorities that embed circularity scoring into tender evaluation criteria for museum and healthcare deployments.
Japan
Precision manufacturing standards and aging demographics concentrate demand in healthcare wayfinding and municipal service terminals. METI oversees JIS standards alignment for touchscreen accessibility and audio output modules. The Kanto region around Tokyo anchors deployment volumes for interactive appointment-scheduling systems in rural medical facilities.
India
Quick-service restaurant expansion and municipal digital infrastructure programs accelerate connected terminal adoption. BIS certification requirements for imported wireless modules create compliance bottlenecks for foreign manufacturers. Maharashtra and Karnataka host the fastest-growing deployment clusters for self-service ordering terminals in urban retail corridors.
Wifi Kiosks Market Competitive Landscape
Capability concentration sits with integrated security and financial terminal specialists; scale advantage sits with Asia-Pacific manufacturing conglomerates with captive component supply. The vendor base stratifies across three tiers: legacy financial self-service providers with certification depth, industrial computing specialists with modular hardware platforms, and regional assembly houses serving price-sensitive procurement channels. Dominant competitive moves include backward integration into touch controller and wireless module sourcing, and technology licensing agreements that compress firmware development timelines for peripheral integration.
Among North American financial terminal specialists, NCR Corporation and Diebold Nixdorf occupy positions anchored by legacy ATM-to-kiosk technology transfer and PCI-DSS certification depth. Fujitsu Limited represents the Asia-Pacific manufacturing scale archetype, with production facilities supplying both domestic Japanese operators and export markets. These three entities exemplify the capability-scale bifurcation structuring competitive positioning across premium and volume procurement segments.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| Fujitsu Limited |
| GLORY Ltd. |
| Olea Kiosks Inc. |
| KIOSK Information Systems |
| Meridian Kiosks |
| Acrelec |
| Kontron AG |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress margin buffers for mid-tier assembly houses while amplifying price differentiation between PCI-DSS certified premium tiers and uncertified economy alternatives. Supply concentration in Taiwanese touch controller fabrication and South Korean wireless module production feeds directly into procurement timelines and downstream pricing power for integrated security specialists.
Pricing Analysis
Price spreads between United States and Southeast Asian procurement channels widen as FCC certification timelines extend product launch schedules. Three-tier pricing structure across premium, standard, and economy levels separates ADA-compliant interactive terminals from basic digital signage units. Pricing pressure stems from aluminum enclosure cost volatility and semiconductor supply concentration. Quick-service restaurant chains exhibit highest price sensitivity, while airport authorities with outcome-based service contracts prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from Taiwan-based touch controller suppliers and supply-chain finance facilities anchored in South Korean wireless module distributors shape working capital requirements for assembly houses. Component sourcing concentrates in Taiwan, South Korea, and China, with enclosure fabrication drawing from aluminum suppliers in Germany and Vietnam. Single-source vulnerability in touch controller fabrication creates geographic disruption exposure. Distribution runs through direct OEM relationships for premium tiers and regional distributor networks for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware development capability for peripheral integration—receipt printers, card readers, barcode scanners—outpaces available engineering talent pools, compressing vendor qualification timelines and inflating compensation costs for embedded systems specialists.
For Market Incumbents: Pre-empt emerging cloud-native fleet management specialists by accelerating backward integration into wireless module sourcing and locking exclusive supplier agreements with Taiwanese touch controller foundries. Defend margin position against industrial computing modularists through PCI-DSS certification depth and ADA accessibility specification leadership. For New Entrants and Emerging Players: Rural healthcare wayfinding in underserved United States medical facilities offers lowest competitive density and shortest procurement cycles for interactive appointment-scheduling terminals. Target municipal digital infrastructure programs in India and Texas transit districts where capital budget constraints favor operational expenditure structures and outcome-based contracting models. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive kiosk divisions lacking standalone scale—particularly Japanese precision manufacturers and European enclosure fabricators facing Ecodesign compliance cost escalation. Long-term viability hinges on cloud-native architecture transition completion and edge computing capability integration. Watch for BIS certification bottleneck resolution in India as inflection indicator for export manufacturing capacity reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Touch Controllers | Taiwanese foundry partnerships reduce wireless certification timeline exposure and secure supply priority. |
| Cloud-Native Fleet Management Platform Launch | Over-the-air firmware capabilities compress total cost of ownership for quick-service restaurant operators. |
| ADA Accessibility Certification Investment | FAA-mandated physical accessibility standards harden procurement specifications for airport baggage tag terminals. |
| Enclosure Material Requalification Program | ECHA REACH compliance positions vendors for German and French museum and healthcare tenders. |
| Outcome-Based Service Contract Expansion | Per-transaction revenue models transfer uptime risk from California and Texas transit authorities to vendors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with kiosk manufacturing executives, embedded systems engineering directors, airport procurement officers, and quick-service restaurant IT operations leads; and secondary validation against FCC certification databases, ECHA REACH substance restrictions, PCI-DSS compliance registries, and customs trade records for aluminum enclosure imports. Bottom-up segment sizing triangulated with top-down macroeconomic anchors across the analysis window.
Forecast inputs span product type segmentation by replacement cycle velocity, technology architecture by operational expenditure structure, installation environment by enclosure engineering requirements, and end-use sector by procurement sophistication. CAGRs derive from segment-level growth rate blending and cross-elasticity modeling against semiconductor supply availability and regulatory certification timeline trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants or modular industrial computing specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Global Massive MIMO Market