
 Global Wireless Mesh Network Market | 2026-2036
Global Wireless Mesh Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Mesh Network Market Foresight
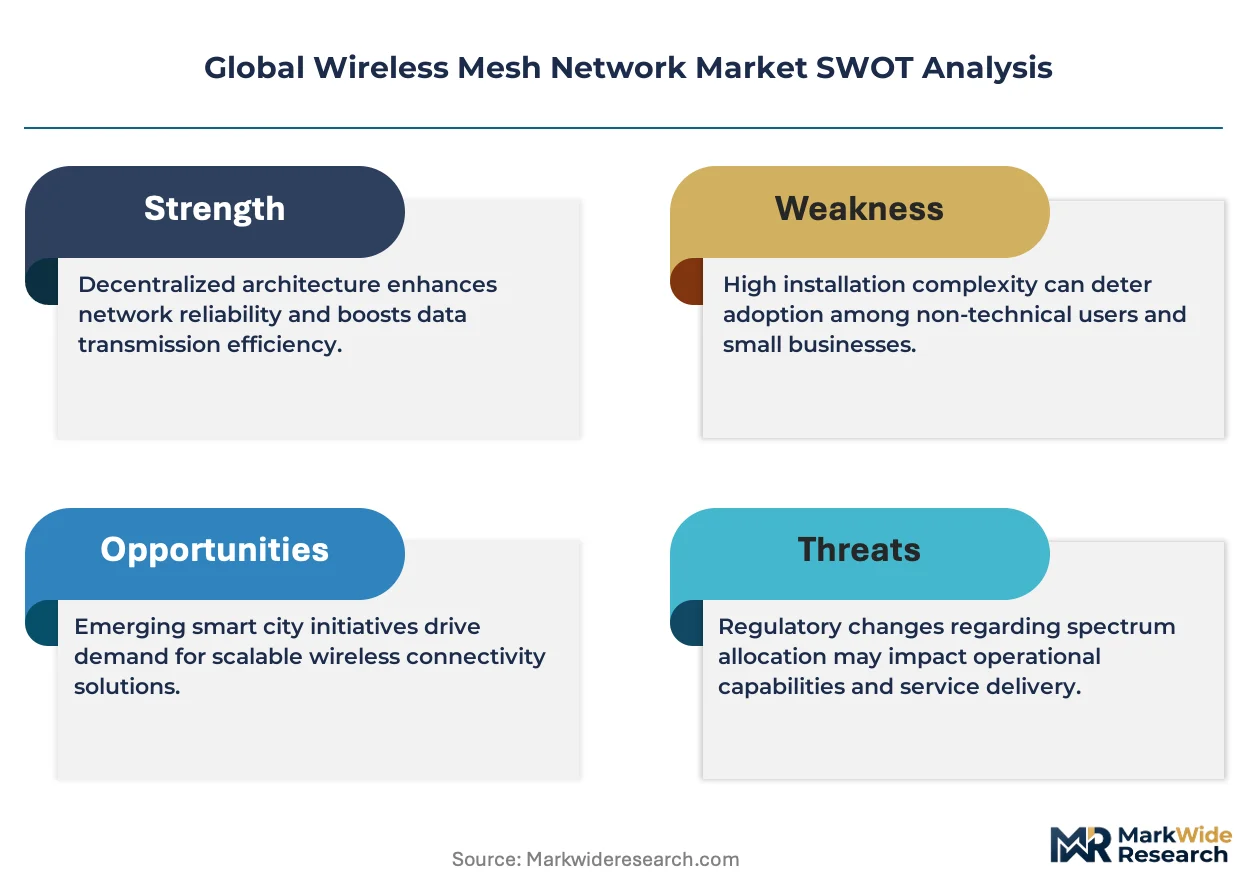
Smart city infrastructure spending is decoupling from traditional carrier-dependent connectivity models as municipalities seek resilient, self-organizing networks. Cisco Systems leverages its enterprise routing heritage to anchor large-scale urban mesh deployments across multiple continents. Aruba Networks competes through cloud-native network management platforms that simplify multi-node orchestration for infrastructure operators. Rajant Corporation specializes in kinetic mesh protocols designed for mobile industrial environments where nodes constantly shift position.
A wireless mesh network consists of radio nodes organized in a mesh topology where each node relays data for the network, typically operating across unlicensed ISM bands at 2.4 GHz or 5 GHz with self-healing capabilities that reroute traffic when individual nodes fail. This architecture eliminates single points of failure and reduces backhaul costs for wide-area coverage in environments where wired infrastructure proves impractical or cost-prohibitive. Wi-Fi Mesh technology dominates consumer and enterprise deployments due to interoperability with existing standards and straightforward integration with current device ecosystems. Industrial Automation applications command premium positioning within the deployment mode matrix, as manufacturing facilities prioritize deterministic latency and protocol reliability over consumer-grade throughput metrics.
The FCC's CBRS rules and the EU's Radio Equipment Directive collectively shape spectrum access and device certification requirements that determine which mesh technologies achieve commercial scale in their respective jurisdictions. ISO/IEC standards for wireless network resilience provide baseline interoperability frameworks that procurement teams at infrastructure operators increasingly embed as mandatory bid criteria. Stakeholders must monitor evolving national spectrum allocation decisions, as priority access licenses versus general authorized access classifications directly determine viable business models for neutral-host mesh providers.
Market Dynamics
Self-healing mesh architectures are displacing point-to-point wireless backhaul as municipalities and industrial operators prioritize resilience over raw bandwidth metrics. The FCC's CBRS framework and Germany's industrial automation corridors exemplify how spectrum access and manufacturing demand are restructuring deployment economics.
Growth Catalysts
- CBRS Shared Spectrum Access:The FCC's Citizens Broadband Radio Service framework in the United States reduces licensing costs for neutral-host operators. Municipal governments now deploy private mesh networks without exclusive spectrum ownership.
- Industrial Automation Corridors:Germany's Rhine-Ruhr manufacturing belt retrofits legacy connectivity with kinetic mesh protocols. Deterministic latency requirements in automotive and chemical plants drive premium infrastructure spend.
- Smart City Infrastructure Mandates:Urban resilience planning embeds self-organizing networks as critical infrastructure. Street lighting, traffic management, and environmental sensors require always-on connectivity without single points of failure.
Market Restraints
- Semiconductor Supply Concentration:Radio frequency chip fabrication concentrates in Taiwan and South Korea. Geopolitical friction threatens node production timelines for mesh hardware vendors.
- Unlicensed Spectrum Congestion:2.4 GHz and 5 GHz ISM bands face interference saturation in dense urban deployments. Performance degradation forces expensive spectrum licensing or proprietary protocol development.
- Copper and Rare Earth Input Volatility:Antenna arrays and power amplifiers depend on copper and neodymium pricing. Mining supply disruptions in Chile and China compress hardware margins unpredictably.
Strategic Opportunities
- India's Smart Cities Mission:The country's urban transformation program targets 100 municipalities with integrated digital infrastructure. Neutral-host mesh providers can bypass traditional carrier relationships.
- EU Radio Equipment Directive Harmonization:Streamlined CE marking across member states reduces certification duplication. Vendors achieve faster cross-border deployment in France, Netherlands, and Nordic markets.
- Agricultural IoT Convergence:Precision farming combines drone telemetry with soil sensor networks. Mesh topologies cover irregular terrain where cellular backhaul remains uneconomical.
Industry Challenges
- RF Engineering Talent Scarcity:Mesh network optimization requires specialized expertise in propagation modeling and interference mitigation. Universities produce fewer graduates with hands-on radio frequency experience than deployment demand requires.
- Multi-Vendor Interoperability Certification:ISO/IEC resilience standards lack enforcement mechanisms. Procurement teams struggle to validate self-healing claims across heterogeneous equipment portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Mesh Network Market |
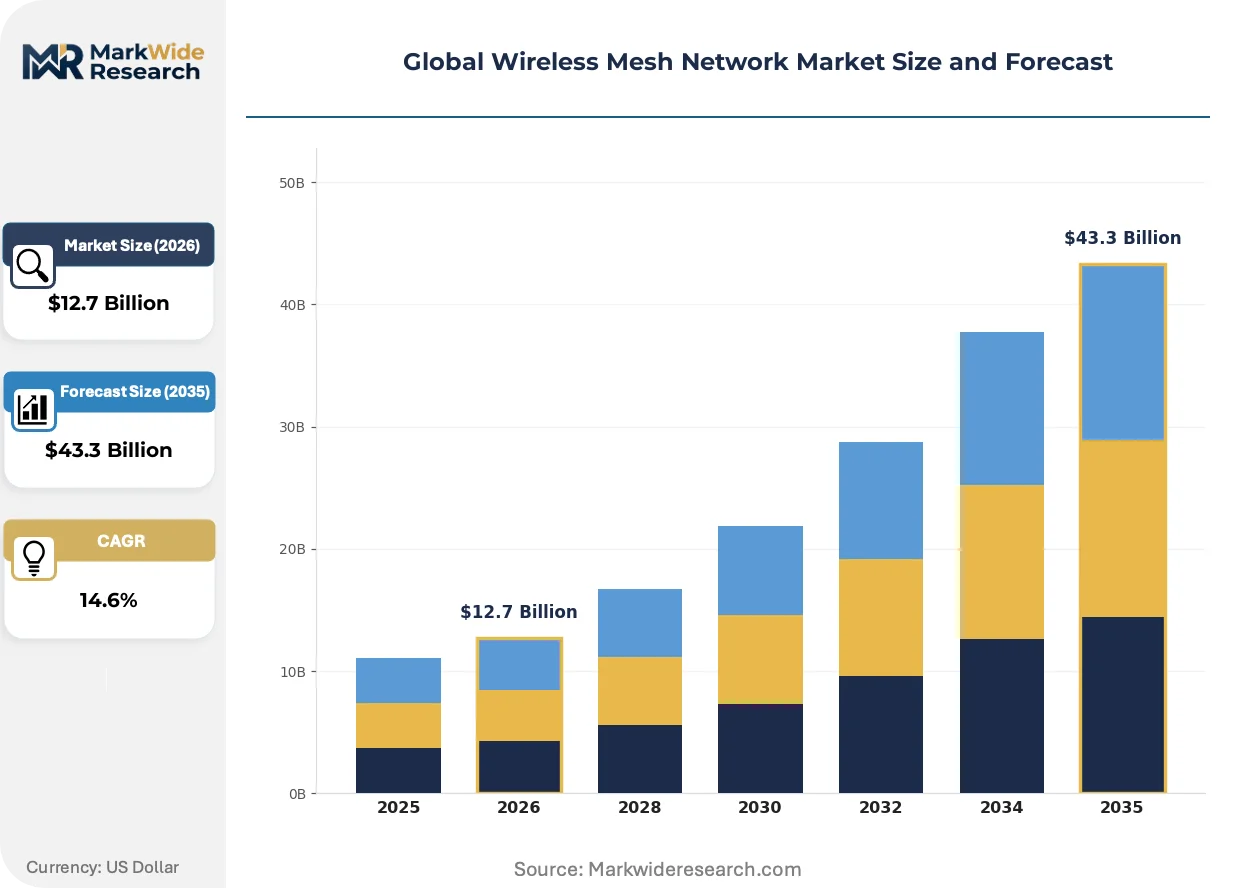
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $43.3 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi Mesh, Zigbee, Thread, Bluetooth Mesh, WirelessHART Application: Smart Cities, Industrial Automation, Agriculture Automation, Military Communications, Smart Homes Deployment Mode: Urban, Remote Locations, Offshore Facilities, Transportation Networks, Underground Networks End User: Telecommunication Providers, Energy Sector, Defense Agencies, Agricultural Enterprises, Infrastructure Operators |
| Companies Covered | Cisco Systems, Aruba Networks, Qualcomm, Cambium Networks, Ruckus Networks, Synapse Wireless, Wirepas, Rajant Corporation, Qorvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Mesh Network Market Shifts & Advancements
Network virtualization and AI-driven traffic orchestration are compressing operational complexity for multi-thousand-node deployments. These shifts alter how infrastructure operators evaluate vendor partnerships and lifecycle costs.
Wi-Fi 7 hardware is unifying previously separate frequency bands under single-radio management. Enterprise campus buyers in the United States and Germany are standardizing on tri-band access points that dynamically steer traffic across 2.4 GHz, 5 GHz, and 6 GHz spectrum. This consolidation reduces equipment sprawl while enabling deterministic latency for video surveillance and building automation systems.
The EU's Cyber Resilience Act imposes mandatory security update obligations on radio equipment manufacturers. Vendors must guarantee patch availability for mesh nodes throughout declared product lifecycles. Industrial automation buyers in the Rhine-Ruhr corridor now embed contractual security-maintenance clauses as standard procurement terms.
Subscription-based network management displaces perpetual licensing for municipal mesh operators. French and Dutch smart city agencies favor operational expenditure models that bundle hardware, software, and field maintenance. This restructures vendor cash flows toward recurring revenue and tightens customer retention through embedded service dependencies.
Global Wireless Mesh Network Market Segmentation
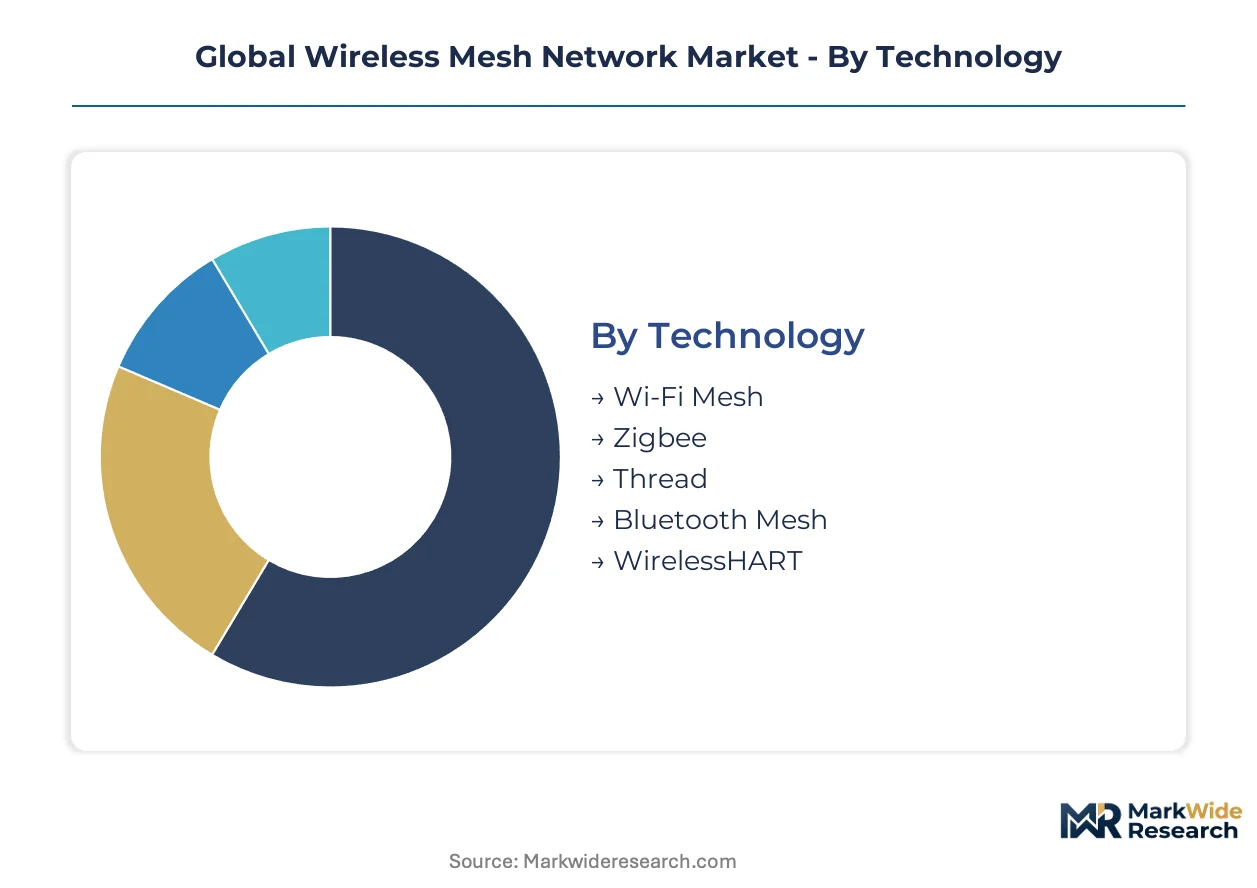
Mesh network procurement decisions hinge on balancing coverage resilience against spectrum licensing economics and end-use latency requirements. Buyers evaluate technology stacks through the lens of deterministic performance versus interoperability breadth.
Technology:
Radio protocol selection determines power consumption, node density limits, and ecosystem interoperability for infrastructure planners.
- Wi-Fi Mesh:Operates across unlicensed 2.4 GHz, 5 GHz, and emerging 6 GHz bands with IEEE 802.11 standards compliance. German industrial campuses and US municipal smart city deployments favor Wi-Fi Mesh for seamless integration with existing enterprise wireless infrastructure and straightforward BYOD compatibility.
- WirelessHART:Purpose-built for process automation with time-synchronized channel hopping and 10-millisecond deterministic latency guarantees. Rhine-Ruhr chemical plants and Saudi Aramco facilities mandate WirelessHART for safety-critical sensor networks where protocol jitter risks operational shutdowns.
- Zigbee:Mesh networking stack optimized for low-power IoT endpoints with sub-gigahertz regional variants.
- Thread:IPv6-native protocol designed for home and building automation with direct cloud connectivity.
- Bluetooth Mesh:Flooding-based message relay for lighting control and asset tracking in retail and healthcare environments.
Wi-Fi Mesh leads on scale; WirelessHART leads on momentum in premium industrial verticals.
Application:
End-use verticals impose distinct throughput, latency, and environmental resilience specifications that reshape hardware requirements.
- Industrial Automation:Demands deterministic sub-50-millisecond latency for closed-loop control systems and kinetic mesh protocols for mobile robotics. German automotive plants along the Rhine-Ruhr corridor and Japanese electronics fabs prioritize self-healing architectures that maintain connectivity during AGV fleet movements.
- Smart Cities:Requires always-on street lighting, traffic signal, and environmental sensor networks spanning square-kilometer coverage zones. India's Smart Cities Mission in Pune and Surat embeds neutral-host mesh infrastructure to bypass traditional carrier dependencies.
- Smart Homes:Consumer-grade whole-home coverage with seamless roaming between satellite nodes.
- Military Communications:Mobile ad-hoc networks with anti-jam waveforms and rapid reconstitution after node compromise.
- Agriculture Automation:Irregular terrain coverage for drone telemetry and soil moisture sensor grids in Australian wheat belts and Brazilian soybean regions.
Industrial Automation commands premium pricing; Smart Cities delivers the steepest expansion trajectory among infrastructure verticals.
Deployment Mode:
Physical installation environment dictates antenna design, power sourcing, and backhaul topology for network architects.
- Urban:Dense node placement with street furniture mounting and fiber backhaul aggregation points. Paris, Barcelona, and Singapore deploy urban mesh layers beneath cellular macro networks to offload municipal IoT traffic.
- Transportation Networks:Trackside, tunnel, and vehicle-to-infrastructure connectivity with handoff protocols for mobility. Deutsche Bahn and Japan Railways retrofit legacy signaling corridors with mesh overlays to reduce copper cable maintenance.
- Remote Locations:Solar-powered nodes with satellite backhaul for mining camps and forestry operations.
- Offshore Facilities:Marine-grade enclosures and explosion-proofing for oil platform process control.
- Underground Networks:Leaky feeder alternatives for mine ventilation monitoring and subway passenger connectivity.
Urban deployments dominate installed base; Transportation Networks are climbing the fastest as rail operators modernize signaling infrastructure.
End User:
Procurement authority and budget cycles vary sharply between regulated utilities, defense classified programs, and competitive telecom operators.
- Infrastructure Operators:Neutral-host entities deploying shared mesh layers for multiple tenant access. Netherlands water management authorities and French highway concessionaires bundle sensor backhaul with third-party commercial access.
- Energy Sector:Grid modernization programs requiring distribution automation and substation connectivity. US rural electric cooperatives leverage CBRS spectrum for private LTE-to-mesh hybrid networks.
- Telecommunication Providers:Fixed wireless access extension and indoor coverage densification.
- Defense Agencies:Tactical mesh radios with frequency-hopping spread spectrum and anti-jam waveforms.
- Agricultural Enterprises:Precision farming cooperatives pooling sensor network investments across land holdings.
Infrastructure Operators lead on scale; Energy Sector shows the strongest momentum as grid modernization accelerates across OECD markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between spectrum licensing regimes is reshaping where mesh infrastructure capital deploys. The FCC's CBRS framework in the United States offers lower barriers than exclusive spectrum auctions, while Germany's industrial automation corridors attract premium kinetic mesh investments. Municipal procurement teams now route budgets toward jurisdictions with streamlined equipment certification.
United States
FCC's Citizens Broadband Radio Service enables neutral-host operators to deploy private mesh layers without spectrum ownership costs. Rural electric cooperatives in the Midwest combine CBRS with hybrid LTE-to-mesh architectures for grid modernization. Smart city agencies in California and Texas embed self-healing networks as critical infrastructure for traffic management and environmental sensing.
Germany
Rhine-Ruhr manufacturing belt retrofits legacy connectivity with deterministic latency protocols for automotive and chemical automation. The country's national spectrum regulator facilitates priority access licenses for industrial private networks. Bavarian automotive plants and North Rhine-Westphalia chemical complexes anchor European demand for kinetic mesh deployments.
India
Smart Cities Mission targets 100 municipalities with integrated digital infrastructure, bypassing traditional carrier dependencies. TRAI's spectrum allocation decisions shape viable business models for neutral-host providers. Pune and Surat embed mesh layers for street lighting and sensor backhaul, while agricultural IoT converges in Maharashtra and Gujarat for precision farming.
France
ANSM and CNIL frameworks govern data governance for municipal sensor networks. French highway concessionaires and water management authorities bundle third-party commercial access with neutral-host mesh layers. Paris deploys urban mesh beneath cellular macro networks to offload municipal IoT traffic from licensed spectrum.
Japan
METI industrial policy prioritizes resilient connectivity for manufacturing competitiveness. Deutsche Bahn-style rail modernization drives mesh overlay deployment across Japan Railways signaling corridors. Tokyo and Osaka smart city programs require always-on networks for disaster resilience and building automation integration.
Global Wireless Mesh Network Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge protocol specialization with scale deployment capability. The vendor base clusters around three archetypes: enterprise networking incumbents with routing heritage, cloud-native specialists in multi-node orchestration, and kinetic mesh pioneers serving mobile industrial environments. Consolidation pressure concentrates among mid-tier protocol vendors lacking carrier relationships. Technology licensing agreements and geographic expansion represent the two dominant competitive moves as vendors navigate divergent national certification requirements.
Within the enterprise networking tier, Cisco Systems and Aruba Networks exemplify scale-driven positioning through cloud-native management platforms and urban deployment anchoring. Rajant Corporation occupies the kinetic specialization vector, representing protocol innovation for mobile industrial nodes. These three entities collectively illustrate how vendor strategy fragments across interoperability breadth versus deterministic performance optimization.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba Networks |
| Qualcomm |
| Cambium Networks |
| Ruckus Networks |
| Synapse Wireless |
| Wirepas |
| Rajant Corporation |
| Qorvo |
| Others |
Supply & Pricing Matrix
The EU's Cyber Resilience Act gates qualified supply for mesh hardware vendors while simultaneously erecting premium-tier pricing access for industrial automation buyers in Germany and France. Municipal procurement teams now embed contractual security-maintenance clauses as mandatory bid criteria, forcing vendors to absorb lifecycle compliance costs or forfeit high-margin infrastructure contracts.
Pricing Analysis
Distributor margins compress equipment economics for neutral-host mesh providers serving India's Smart Cities Mission. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling, with Industrial Automation buyers in the Rhine-Ruhr corridor showing least price sensitivity due to deterministic latency requirements. Cost compression in the standard tier intensifies because semiconductor supply concentration in Taiwan and South Korea limits vendor negotiation leverage. Municipal governments in France and the Netherlands exhibit highest price sensitivity, favoring operational expenditure models that shift capital burden to vendors.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific fabrication hubs to European deployment sites erodes hardware margins for mid-tier protocol vendors. Radio frequency chip production centers on Taiwan, South Korea, and the United States, while antenna arrays draw from copper suppliers in Chile and rare earth processors in China. Single-source vulnerability in Taiwan's advanced node fabrication threatens node production timelines for mesh hardware vendors. Distribution runs through authorized industrial distributors serving automation corridors and direct-to-OEM channels for smart city integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Wireless Mesh Network Market functions as a geographic-arbitrage play where FCC CBRS licensing costs in the United States undercut exclusive spectrum auctions in Germany, redirecting neutral-host capital toward American municipal deployments.
For Market Incumbents: Extend cloud-native management platform capabilities into kinetic mesh orchestration to counter Rajant Corporation's mobile industrial specialization. Cisco Systems and Aruba Networks must backward integrate into RF chip sourcing to mitigate Taiwan concentration risk while embedding ISO/IEC resilience certification as a procurement gatekeeper. For New Entrants and Emerging Players: Begin with India's Smart Cities Mission white space where traditional carrier bypass creates procurement entry points for neutral-host specialists. Agricultural IoT convergence in Maharashtra and Gujarat offers the most penetrable segment, with precision farming cooperatives pooling sensor network investments across irregular terrain where cellular backhaul remains uneconomical. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native network management specialists because subscription-based operational expenditure models restructure vendor cash flows toward recurring revenue and tighten customer retention through embedded service dependencies. Target mid-tier protocol vendors lacking carrier relationships in the 5-10 year viability window. Watch for TRAI spectrum allocation decisions as the inflection indicator for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies Wi-Fi 7 tri-band management with kinetic mesh protocols for German automotive plants. |
| Geographic Expansion | Captures India's Smart Cities Mission procurement bypassing traditional carrier relationships. |
| Acquisition of Specialist Firm | Consolidates kinetic mesh expertise for mobile industrial environments where nodes shift position. |
| Strategic Partnership | Combines Cisco's enterprise routing heritage with cloud-native orchestration for urban deployments. |
| Product Launch | Introduces Wi-Fi 7 hardware consolidating 2.4 GHz, 5 GHz, and 6 GHz under single-radio management. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with infrastructure operators, municipal procurement directors, RF engineering leads, and industrial automation managers with secondary validation from FCC filings, TRAI spectrum decisions, EU Cyber Resilience Act documentation, and customs trade data. Bottom-up node shipment analysis and top-down infrastructure spending estimates provided triangulation across the analysis window.
Segment-weighting approaches modeled technology protocol selection, application vertical latency requirements, deployment mode environmental constraints, and end-user procurement authority across the projection horizon. CAGRs derived from infrastructure investment trajectories in smart city mandates and industrial automation corridor retrofits, with spectrum licensing economics and semiconductor supply timelines as key forecast inputs.
Several conditions sit outside the modeled scope, including unlicensed spectrum congestion saturation thresholds, geopolitical disruption scenarios for Taiwan fabrication capacity, and proprietary protocol adoption rates outside IEEE standards. Forecasts reflect documented assumptions about regulatory stability and supply chain continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
5G WIT120 Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
5G Wireless Ecosystem Market