
 Europe Fixed Wireless Access (FWA) Market | 2026-2036
Europe Fixed Wireless Access (FWA) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fixed Wireless Access (FWA) Market Insights
Germany is fragmenting its fixed-line dependency through aggressive FWA infrastructure rollouts across Bavaria and North Rhine-Westphalia. Nokia Oyj leverages its massive MIMO portfolio to anchor carrier-grade deployments for Deutsche Telekom AG. Ericsson sustains R&D intensity in millimeter-wave CPE designs that differentiate its offering in dense urban corridors. Huawei Technologies Co., Ltd. competes on integrated baseband-to-antenna systems despite procurement restrictions in select member states.
Europe Fixed Wireless Access delivers broadband connectivity through radio links between cellular base stations and subscriber premises equipment, typically operating in sub-6 GHz and millimeter-wave bands with throughput exceeding 100 Mbps to match fiber-equivalent experiences. The technology serves residential, enterprise, and rural connectivity gaps where trenching costs render fiber uneconomical. 5G technology leads deployment momentum as carriers exploit Release 16 URLLC enhancements for residential internet access services. Enterprise and small business end-user segments attract premium pricing due to SLA-backed throughput guarantees and managed security overlays. Private deployment models gain traction among industrial campuses seeking captive network control independent of public infrastructure.
EU regulatory frameworks including the Gigabit Infrastructure Act, CE marking under the Radio Equipment Directive, and national spectrum auctions governed by BEREC shape equipment certification timelines and operator market entry. ETSI harmonized standards for 5G NR interfaces constrain vendor interoperability while accelerating procurement cycles for compliant equipment. Stakeholders must monitor spectrum refarming decisions in France and Italy where 3.5 GHz clearance timelines determine CPE upgrade windows and competitive positioning for the next licensing period.
Market Dynamics
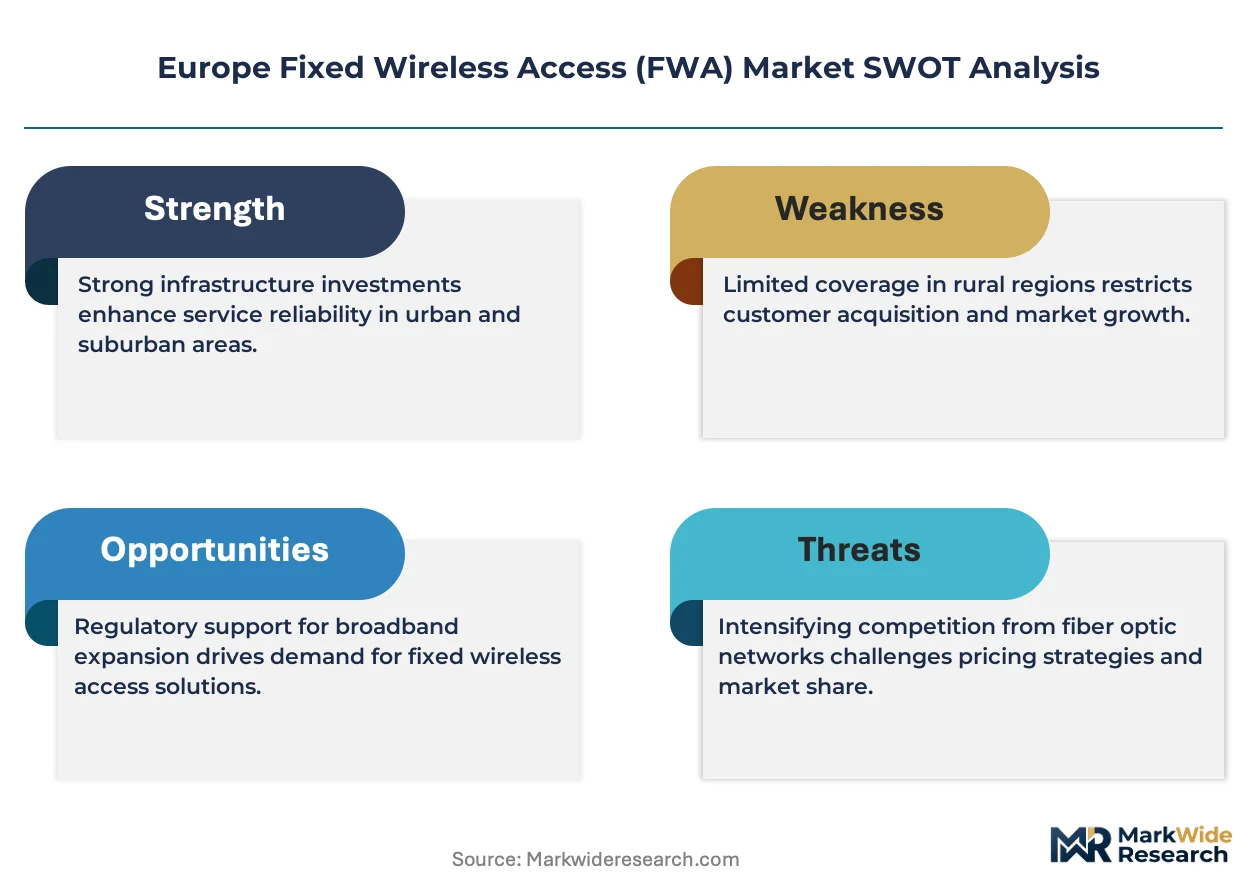
5G Release 16 URLLC capabilities are compressing deployment timelines for carrier-grade FWA, forcing infrastructure decisions before fiber economics stabilize across suburban Europe.
Growth Catalysts
- Gigabit Infrastructure Act:The EU's streamlined spectrum allocation timelines accelerate 5G FWA licensing in member states, reducing regulatory lag between auction and commercial launch.
- Millimeter-wave CPE maturation:Sub-6 GHz congestion in dense German and French urban corridors pushes operators toward higher-frequency equipment with fiber-equivalent throughput.
- Rural connectivity gaps:Trenching cost premiums exceeding 3x wireless deployment in Alpine and Nordic peripheries make FWA the default broadband solution for scattered populations.
Market Restraints
- Semiconductor supply concentration:Baseband processor fabrication concentrates in East Asian foundries, exposing European CPE vendors to lead-time volatility and allocation rationing.
- Spectrum refarming friction:France and Italy face protracted 3.5 GHz clearance timelines, forcing operators to defer CPE upgrade cycles and compressing competitive windows.
- Fiber substitution threat:Municipal open-fiber networks in Spain and Portugal threaten FWA addressable market in mid-density suburbs where trenching costs have fallen.
Strategic Opportunities
- Industrial private networks:German automotive campuses and Dutch port complexes seek captive 5G FWA deployments independent of public infrastructure, creating premium equipment demand.
- CE marking acceleration:ETSI harmonized standards for 5G NR interfaces compress certification timelines, enabling faster vendor entry and procurement cycle compression.
- Eastern European expansion:Poland and Romania exhibit underpenetrated suburban broadband markets where incumbent fixed-line infrastructure remains sparse and wireless last-mile economics dominate.
Industry Challenges
- Millimeter-wave RF engineering talent:CPE design teams face acute shortages of phased-array antenna specialists, compressing R&D throughput at European equipment vendors.
- Legacy DSL integration:Hybrid service migration requires seamless handoff protocols between copper decommissioning and wireless activation, complicating operational workflows for incumbent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fixed Wireless Access (FWA) Market |
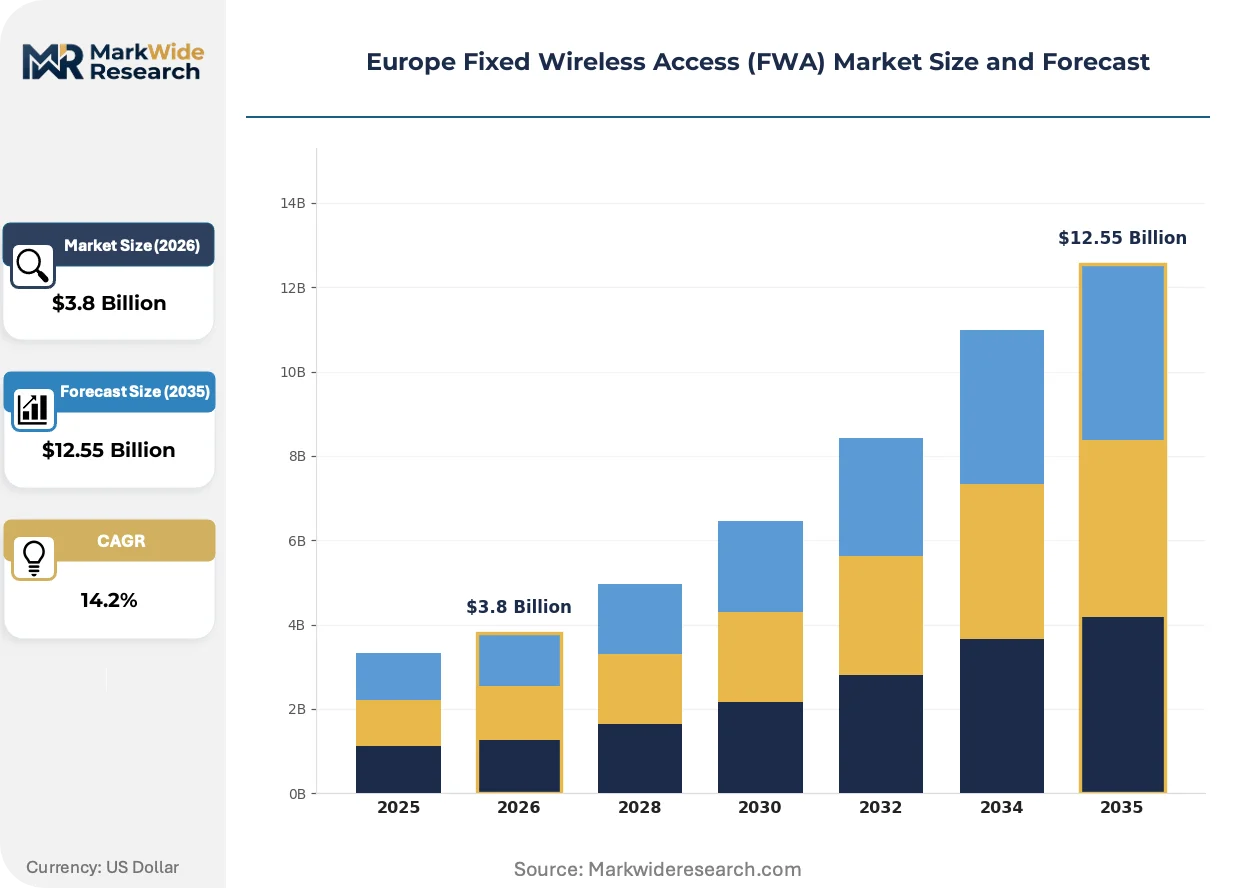
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G, WiMAX, HSPA End User: Residential, Small Businesses, Enterprises, Rural Areas Deployment Model: Private, Hybrid, Fully Managed, Self-Managed Service Type: Internet Access, VoIP, Streaming, Data Transfer |
| Companies Covered | Nokia Oyj, Telefonaktiebolaget LM Ericsson, Huawei Technologies Co., Ltd., ZTE Corporation, Qualcomm Technologies Incorporated, Deutsche Telekom AG, Vodafone Group Plc, Orange S.A., Telefónica S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fixed Wireless Access (FWA) Market Trends and Innovations
Active antenna systems and cloud-native baseband architectures are compressing the traditional RAN cost structure, reshaping how European carriers provision residential broadband.
Massive MIMO beamforming is migrating from macro-cellular infrastructure into subscriber premises equipment, enabling self-install outdoor units that eliminate technician dispatch. Deutsche Telekom and Vodafone Group are piloting 64T64R CPE arrays for suburban deployments. This migration from centralized baseband processing to distributed intelligent antennas is collapsing installation cost structures and accelerating subscriber acquisition velocity.
CE marking under the Radio Equipment Directive now mandates cybersecurity certification for 5G CPE, extending compliance timelines by four to six months for non-EU vendors. BEREC-coordinated national spectrum auctions are synchronizing equipment procurement cycles across member states. German operators face the tightest compliance windows, driving preference toward pre-certified integrated baseband-to-antenna systems.
Self-service installation models are displacing technician-assisted deployment for residential FWA, compressing subscriber acquisition costs and shifting support burden to AI-assisted troubleshooting portals. Retail channel partnerships with consumer electronics distributors are replacing direct operator sales in the United Kingdom and France. This behavioral pivot is most pronounced in suburban British markets where Virgin Media O2 and Three UK compete for switchers through supermarket and online retail placement.
Europe Fixed Wireless Access (FWA) Market Segmentation
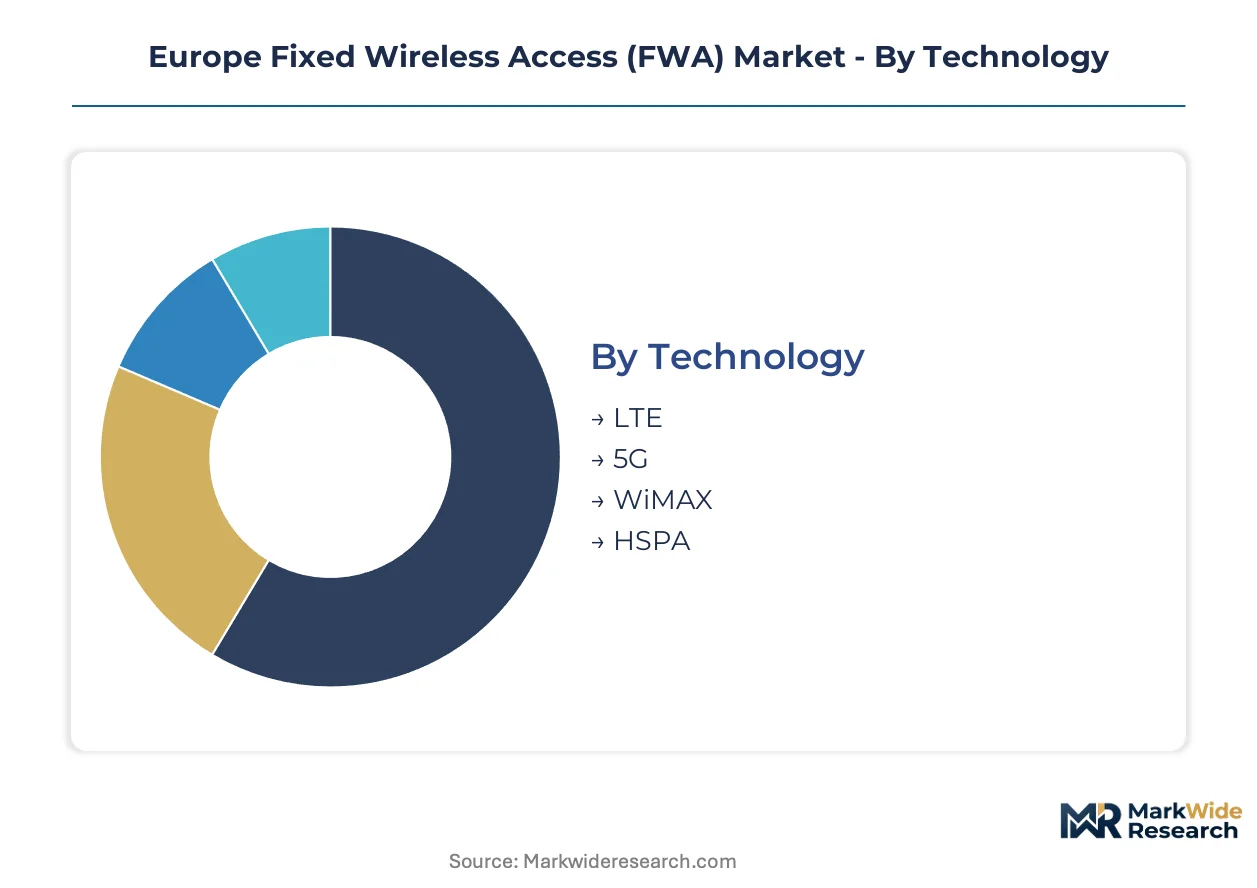
European FWA deployments fragment across multiple technical and commercial dimensions. Operators must align spectrum assets, subscriber density, and service guarantees to capture addressable demand.
Technology:
Mature cellular standards dominate installed base while emerging 5G variants capture expansion capital.
- 5G:Release 16 URLLC implementations deliver sub-10ms latency with gigabit throughput. German and French carriers concentrate procurement in sub-6 GHz massive MIMO configurations for suburban residential density. 5G holds the steepest expansion curve.
- LTE:Cat-18 and Cat-20 modems sustain rural deployments where 5G CPE costs exceed ARPU recovery timelines. Polish operators leverage existing 800 MHz and 2.6 GHz holdings for scattered population coverage. LTE retains volume leadership.
- WiMAX:Legacy 802.16e infrastructure persists in Eastern European industrial zones with captive spectrum licenses. Maintenance-only procurement characterizes this segment.
- HSPA:3G fallback equipment serves Alpine fringe areas with severe backhaul constraints. Romanian operators maintain minimal HSPA CPE stocks for emergency failover.
5G commands premium positioning; LTE sustains rural economics.
End User:
Customer type determines SLA architecture and pricing architecture.
- Residential:Self-install outdoor CPE with AI-assisted troubleshooting dominates acquisition models. United Kingdom supermarket retail channels displace operator direct sales for suburban switchers. Residential commands subscriber volume leadership.
- Enterprises:SLA-backed throughput guarantees with managed security overlays attract premium pricing. German automotive campuses deploy private 5G FWA for production line connectivity independent of public infrastructure. Enterprises climb the fastest.
- Small Businesses:Hybrid copper-wireless migration protocols complicate operational workflows for incumbent operators. French SMBs concentrate in mid-density suburbs where fiber trenching delays persist.
- Rural Areas:Trenching cost premiums exceeding 3x wireless deployment make FWA the default broadband solution for Alpine and Nordic peripheries. Scattered populations justify sub-6 GHz propagation economics.
Residential anchors volume; enterprise segments expand most quickly.
Deployment Model:
Control depth separates capital intensity from operational flexibility.
- Fully Managed:Operator-owned infrastructure with end-to-end service responsibility. Deutsche Telekom and Vodafone Group dominate this segment with carrier-grade SLAs.
- Private:Captive network control for industrial campuses seeking independence from public infrastructure. Dutch port complexes and German manufacturing zones drive premium equipment demand. Private networks gain share fastest.
- Hybrid:Shared backhaul with customer-premises edge processing. French operators pilot hybrid models for mid-density suburban coverage gaps.
- Self-Managed:Enterprise-procured CPE with minimal operator involvement. United Kingdom SMBs favor self-managed options for cost control.
Fully managed retains volume leadership; private networks hold the steepest expansion trajectory.
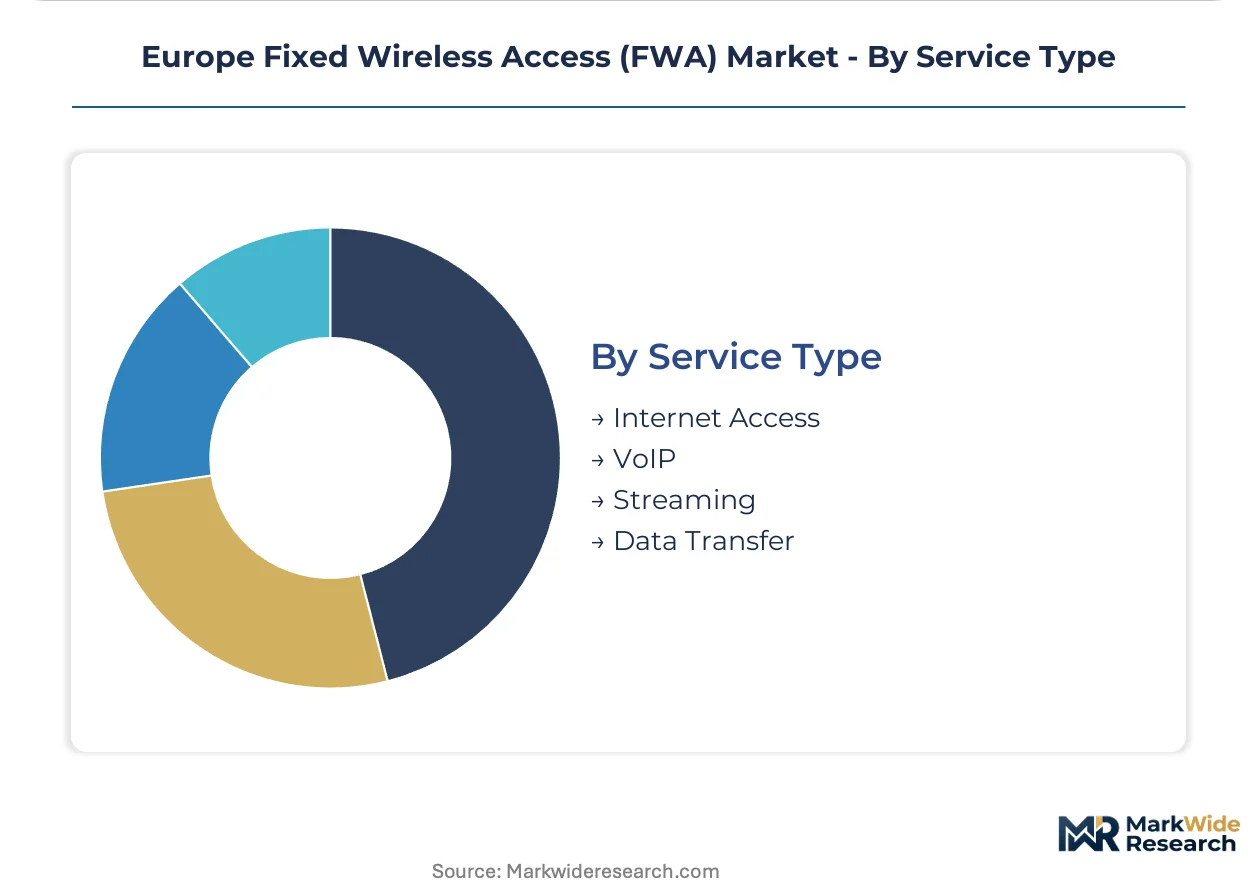
Service Type:
Application layering determines bandwidth provisioning and QoS enforcement.
- Internet Access:Residential broadband replacement with best-effort throughput. Suburban German and British markets concentrate demand as fiber alternatives face deployment delays.
- VoIP:Voice-over-IP services with jitter-sensitive prioritization. Small business end users in France require seamless copper-to-wireless handoff protocols.
- Streaming:Video-optimized traffic shaping for multicast efficiency. Residential subscribers in the United Kingdom drive peak-hour capacity planning.
- Data Transfer:Bulk upload/download services with asymmetric provisioning. Enterprise backup and cloud synchronization workloads in Germany justify dedicated spectrum slices.
Internet access sustains volume dominance; data transfer applications expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's dense fiber backhaul network underwrites Germany's position as Europe's FWA infrastructure anchor. Cross-border spectrum harmonization through BEREC enables seamless equipment procurement cycles across member states. Urban-suburban deployment gradients vary sharply by national regulatory velocity.
Germany
Deutsche Telekom and Vodafone Group drive suburban massive MIMO rollouts in Bavaria and North Rhine-Westphalia. The Gigabit Infrastructure Act compresses 3.5 GHz licensing timelines, reducing auction-to-launch intervals. Stuttgart's automotive manufacturing belt generates captive private network demand for production-line 5G FWA independent of public infrastructure.
France
Orange S.A. and Free Mobile prioritize millimeter-wave CPE for dense Parisian corridors facing sub-6 GHz saturation. ANSM spectrum refarming decisions delay 3.5 GHz clearance in Provence-Alpes-Côte d'Azur, compressing upgrade windows. Lyon-Auvergne-Rhône-Alpes clusters attract hybrid deployment pilots for mid-density suburban coverage gaps.
United Kingdom
Virgin Media O2 and Three UK compete for suburban switchers through supermarket retail channels displacing direct operator sales. CE marking mandates under the Radio Equipment Directive extend cybersecurity certification timelines for CPE imports. Manchester-Liverpool corridor trials self-install outdoor units with AI-assisted troubleshooting portals.
Poland
Play and Polkomtel leverage existing 800 MHz LTE holdings for scattered rural populations where 5G CPE costs exceed ARPU recovery. The national regulator accelerates equipment certification through ETSI harmonized standards alignment. Warsaw-Kraków axis concentrates enterprise procurement for SLA-backed throughput guarantees with managed security overlays.
Netherlands
KPN and VodafoneZiggo target Rotterdam-Amsterdam port complexes seeking captive 5G FWA for logistics automation independent of public networks. Dense fiber backhaul reduces wireless last-mile deployment premiums below 2x trenching costs. Eindhoven's high-tech manufacturing belt drives premium equipment demand for private campus networks.
Europe Fixed Wireless Access (FWA) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying baseband processors and RF front-ends. The vendor base concentrates around three strategic archetypes: Nordic telecom equipment conglomerates with massive MIMO portfolios, Chinese integrated baseband-to-antenna system providers, and European carrier-operators with captive infrastructure deployment capabilities. Competitive maneuvering centers on CE marking pre-certification investments and millimeter-wave CPE R&D partnerships.
Among Nordic equipment vendors, Nokia Oyj and Telefonaktiebolaget LM Ericsson exemplify the platform-integrator archetype with end-to-end 5G NR portfolio depth. Huawei Technologies Co., Ltd. occupies a contested position within the integrated-system tier despite procurement restrictions in select member states. Deutsche Telekom AG represents the carrier-operator vertical, anchoring demand-side concentration through multi-vendor procurement frameworks.
| Leading Market Players |
|---|
| Nokia Oyj |
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies Co., Ltd. |
| ZTE Corporation |
| Qualcomm Technologies Incorporated |
| Deutsche Telekom AG |
| Vodafone Group Plc |
| Orange S.A. |
| Telefónica S.A. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's concentrated baseband processor fabrication capacity feeds directly into European CPE vendor procurement leverage, compressing margin structures for equipment providers dependent on East Asian foundry allocation. The interplay between semiconductor supply rationing and carrier procurement timelines forces pricing volatility into sub-6 GHz massive MIMO configurations before regulatory clarity stabilizes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments European FWA procurement, with CE marking certification grade and volume scale driving differentiation. Premium tier equipment with pre-integrated baseband-to-antenna systems commands substantial markups from German carriers facing compressed compliance windows. Pricing pressure stems from carrier consolidation of procurement frameworks around multi-vendor RFPs. Residential subscribers exhibit highest price sensitivity, while enterprise private network deployments remain least elastic due to SLA-backed throughput requirements.
Supply Chain Analysis
Export-control regimes restricting millimeter-wave phased-array technology flows from US and select European jurisdictions fragment vendor access to critical RF engineering components. Taiwan, South Korea, and China concentrate baseband processor and RF front-end manufacturing, with European CPE design houses drawing from this geographic cluster for core silicon. GaN power amplifier substrates and advanced packaging substrates represent critical input dependencies. Single-source vulnerability concentrates around 3.5 GHz filter bank suppliers. Distribution runs through carrier-direct procurement frameworks and CE-marked equipment aggregators serving smaller national operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European FWA platform economics pivot on interoperability standards harmonization through ETSI, with Release 16 URLLC ecosystem maturation creating winner-take-most dynamics for pre-certified equipment vendors.
For Market Incumbents: Harden procurement relationships through captive R&D partnerships with Stuttgart automotive clusters seeking private 5G FWA independence. Lock in millimeter-wave CPE supply agreements before French and Italian spectrum refarming compresses upgrade windows. Vertical integration into cloud-native baseband architectures defends margin position against Nokia-Ericsson platform consolidation.
For New Entrants and Emerging Players: Eastern European suburban broadband gaps in Poland and Romania represent the most penetrable entry point, where incumbent fixed-line infrastructure sparsity and wireless last-mile economics dominate. Industrial private networks for Dutch port logistics automation offer premium equipment demand with limited incumbent penetration. CE marking pre-certification investment enables faster procurement cycle insertion against established vendor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated baseband-to-antenna specialists with ETSI harmonized standards compliance and active antenna system portfolios. The 5G NR equipment refresh window extending across suburban European markets supports long-term viability for platform-integrator archetypes. Monitor BEREC-coordinated spectrum auction synchronization as the inflection signal for procurement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification Investment | Compresses equipment approval timelines for German carriers facing tightest compliance windows under Radio Equipment Directive mandates. |
| Millimeter-Wave CPE R&D Partnership | Secures phased-array antenna engineering talent scarce across European design houses competing for dense urban corridor deployments. |
| Private Network Campus Deployment | Captures premium pricing from Stuttgart automotive and Rotterdam port complexes seeking infrastructure independence. |
| Spectrum Refarming Alignment | Positions upgrade cycles ahead of French ANSM and Italian regulator 3.5 GHz clearance timeline compressions. |
| Self-Install CPE Channel Expansion | Accelerates subscriber acquisition velocity through UK supermarket retail partnerships displacing direct operator sales. |
Research Methodology
A standing panel of carrier procurement executives, RF engineering directors, national regulatory affairs leads, and industrial campus network architects provided ongoing calibration across primary interview cycles. Secondary validation drew from BEREC spectrum auction records, ETSI harmonized standards documentation, CE marking certification databases, and carrier capex disclosure filings. Bottom-up equipment shipment modeling triangulated against top-down addressable market sizing across technology and deployment model dimensions.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning 5G release variants, end-user archetypes, deployment control depth, and service type layering. CAGRs derived from equipment procurement cycle analysis and subscriber penetration trajectory calibration. Millimeter-wave CPE cost curves and spectrum allocation velocity served as industry-specific forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in carrier capex commitment patterns or East Asian foundry allocation rationing would shift the trajectory. Forecasts reflect documented assumptions around regulatory timeline adherence and equipment certification velocity. Material shifts in EU Gigabit Infrastructure Act implementation pace or BEREC spectrum harmonization scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Wireless Intercoms Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
Mobile WLAN Access Points Market