
 Wireless Smart Plug Market | 2026-2036
Wireless Smart Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Smart Plug Market Insights
Small business owners and facility managers are redrawing procurement priorities for wireless smart plugs as energy accountability tightens across leased commercial spaces. TP-Link Technologies leverages its Kasa ecosystem and aggressive retail distribution to sustain volume leadership in North American big-box channels. Panasonic Corporation anchors premium positioning through integrated energy analytics and enterprise-grade Zigbee stacks. Xiaomi Inc. competes on cost-engineered Wi-Fi modules that dominate e-commerce volumes across emerging Asian markets.
A wireless smart plug is a compact mains-connected device that inserts between a wall outlet and an electrical load, embedding a relay, microcontroller, and RF transceiver to enable remote on-off switching, scheduling, and power-consumption telemetry via smartphone or hub. Typical units carry 10-15 ampere ratings, incorporate overload protection, and communicate through 2.4 GHz Wi-Fi or sub-gigahertz mesh protocols. Indoor plugs lead absolute shipment volumes due to universal compatibility with lamps, chargers, and entertainment equipment, while energy monitoring plugs command higher margins by satisfying utility rebate eligibility and landlord submetering requirements. Wi-Fi connectivity dominates residential installs because it eliminates hub dependency, though Zigbee retains structural importance in whole-home platforms where mesh resilience and lower latency matter.
The Federal Communications Commission governs RF emissions and spectrum compliance for Wi-Fi and Zigbee variants sold in the United States, while the EU Radio Equipment Directive mandates CE marking, interoperability testing, and cybersecurity baselines for European market access. China's Ministry of Industry and Information Technology enforces GB standards for wireless transmitters and standby-power thresholds that shape factory output destined for domestic and export channels. Buyers and vendors must monitor how fragmented national cybersecurity certification requirements reshape firmware development roadmaps and regional product variant strategies.
Market Dynamics
Utility rebate programs and landlord submetering mandates are compressing purchase cycles for energy-monitoring hardware, forcing vendors to pre-certify products against fragmented national cybersecurity baselines before regional launch.
Growth Catalysts
- EU Ecodesign Directive:Mandates real-time energy metering and standby-power reduction in connected devices sold across member states, creating pull-through demand for compliant hardware in residential and commercial channels.
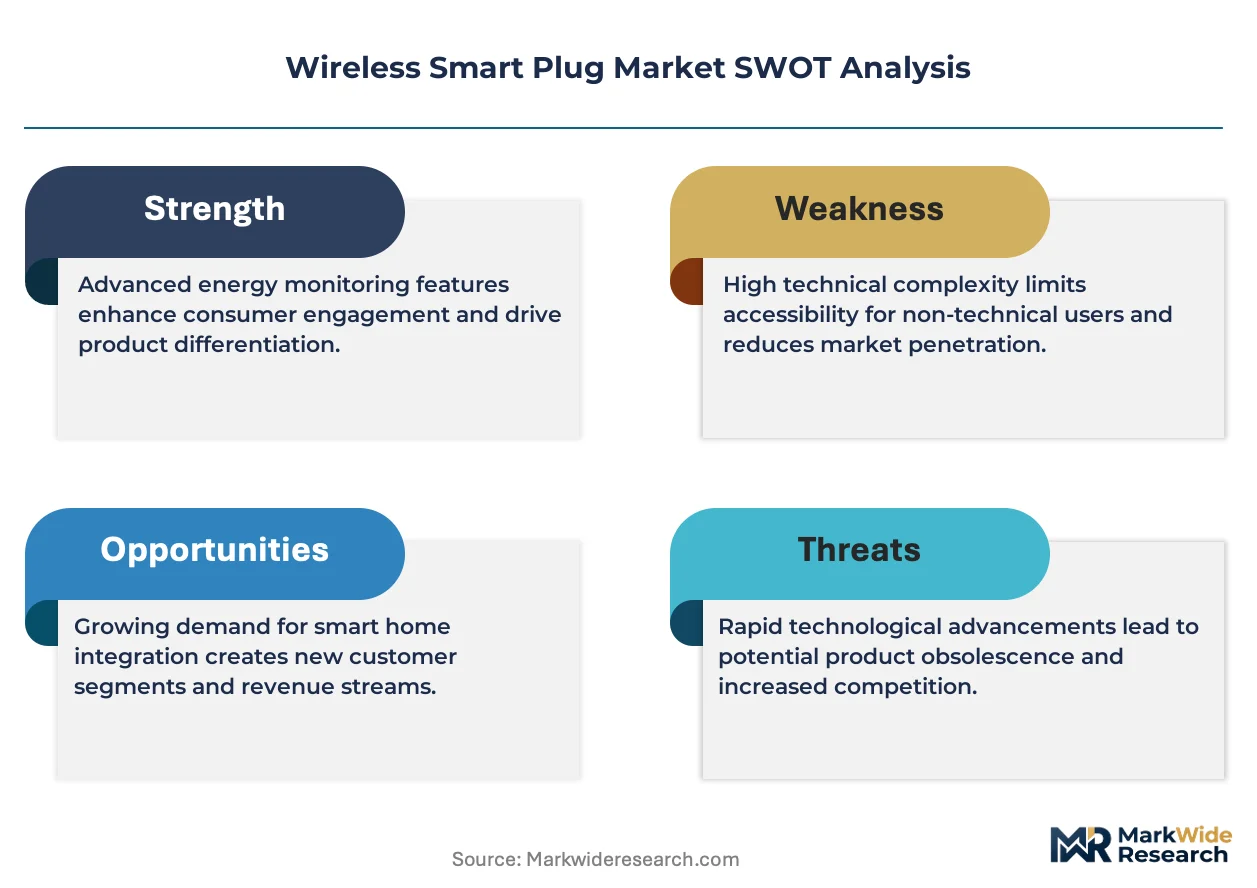
- Wi-Fi 6 penetration:Lower latency and improved mesh stability in dense RF environments is displacing hub-dependent Zigbee installations in multi-unit dwellings and retrofit commercial spaces.
- Landlord submetering requirements:Property management firms in Germany and California are mandating tenant-level energy accountability, driving bulk procurement of metering-capable plugs.
Market Restraints
- Silicon supply concentration:RF transceiver and microcontroller fabrication concentrates in Taiwan and South Korea, exposing vendors to geopolitical disruption and foundry allocation constraints.
- Cybersecurity certification fragmentation:The EU Cybersecurity Act, US NIST IoT guidelines, and China's GB standards impose non-harmonized testing regimes that extend product launch timelines by 6-12 months.
- Hub-based system substitution:Whole-home energy management platforms with built-in outlet control reduce standalone plug attach rates in new construction and deep renovation projects.
Strategic Opportunities
- India smart city deployments:Municipal energy efficiency mandates in Bangalore, Hyderabad, and Pune are creating tender opportunities for utility-managed load control in public housing and street lighting.
- Matter protocol convergence:Cross-platform interoperability between Wi-Fi, Thread, and Zigbee is collapsing ecosystem lock-in, enabling challenger brands to access previously walled-garden install bases.
- Commercial HVAC integration:Facility managers are plugging auxiliary loads into smart outlets to capture granular consumption data for Scope 2 emissions reporting under CSRD and SEC climate disclosure rules.
Industry Challenges
- Firmware security engineering talent:Shortage of embedded systems developers with cryptographic implementation expertise is delaying secure boot and OTA update rollouts.
- Legacy electrical infrastructure compatibility:Aging outlet wiring and grounding configurations in pre-1980s housing stock in the US Northeast and Midwest cause elevated return rates and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Smart Plug Market |
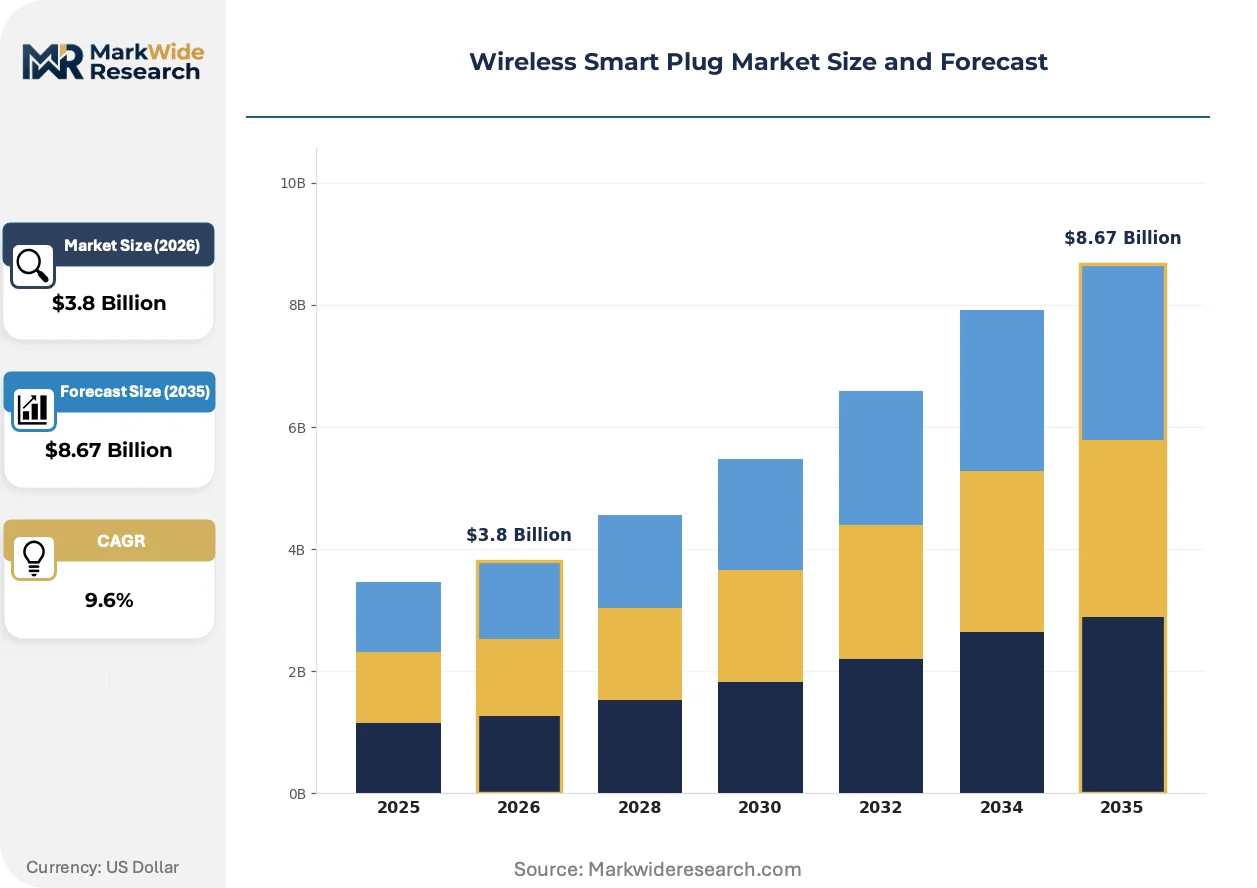
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Plugs, Outdoor Plugs, Energy Monitoring Plugs, Smart Adapters Connectivity: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Small Business, Large Enterprises, DIY Enthusiasts Application: Home Automation, Energy Management, Security Systems, Appliance Control |
| Companies Covered | TP-Link Technologies, Panasonic Corporation, Xiaomi Inc., Amazon, Belkin International, D-Link Corporation, Leviton Manufacturing, Philips, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Smart Plug Market Trends and Innovations
Hardware architectures are bifurcating between cost-optimized Wi-Fi modules for price-sensitive retail and premium Zigbee/Thread stacks for whole-home platform integration, with firmware-defined feature gating replacing physical SKU proliferation.
Edge-based load disaggregation algorithms are displacing cloud-dependent pattern recognition for appliance-level energy breakdown. Residential buyers in Germany and California are adopting these plugs to satisfy granular home energy audit requirements without subscription fees. Local inference reduces latency for real-time demand response signals from utilities.
The EU Radio Equipment Directive's 2024 cybersecurity baseline amendments are forcing firmware architecture redesigns for CE marking eligibility. Vendors must implement secure boot chains, signed OTA updates, and vulnerability disclosure processes before market entry. Premium product tiers are absorbing these compliance costs while economy SKUs face margin compression or regional withdrawal.
Facility managers in leased commercial spaces are unbundling energy monitoring from building management systems, purchasing standalone plugs through distributor e-commerce portals rather than integrated contractor proposals. This procurement pattern shift is most visible in US Class-B office retrofits and German Mittelstand manufacturing facilities where capital expenditure approval cycles for full BMS upgrades remain stalled.
Wireless Smart Plug Market Segmentation
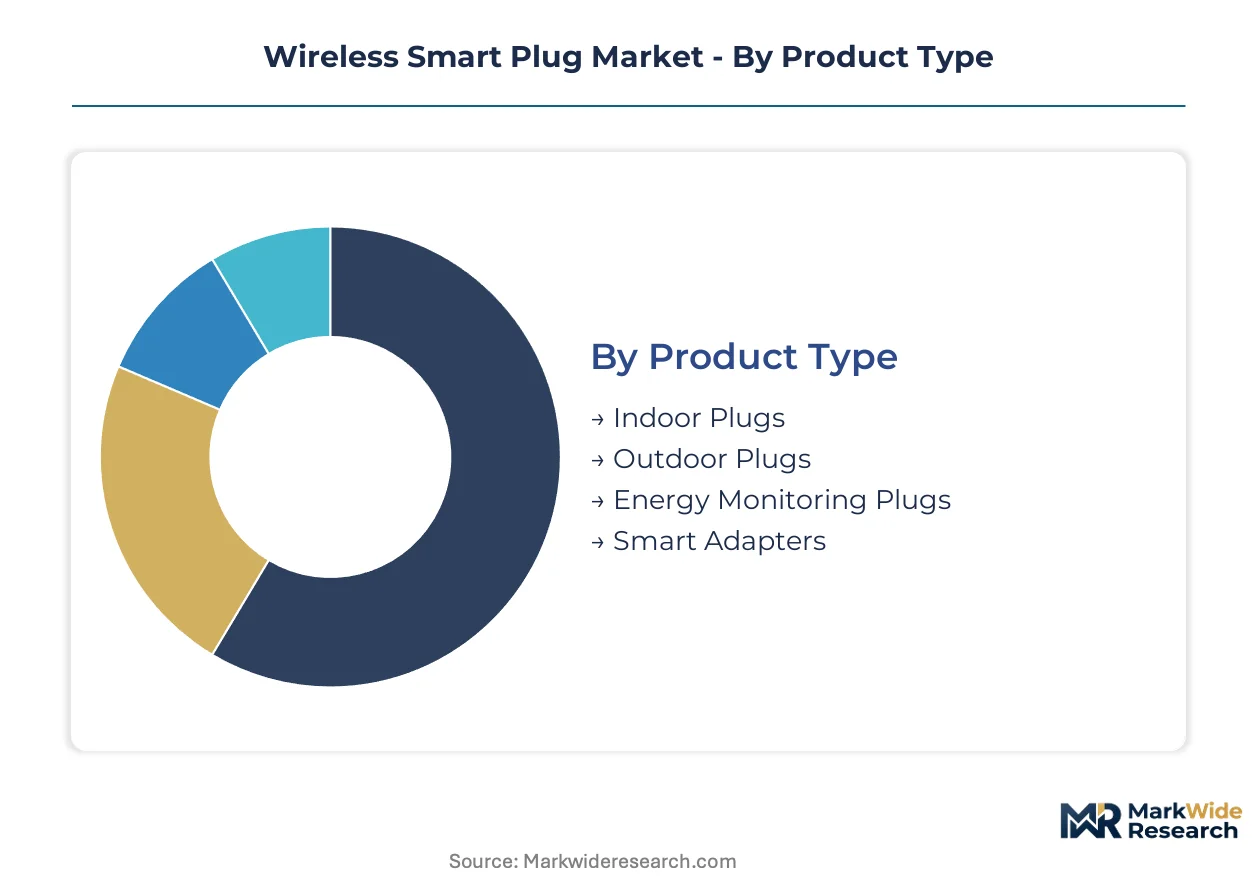
Wireless smart plug segmentation reveals how hardware architectures diverge between mass-market retail and specialized commercial deployments. Each dimension exposes distinct margin structures, certification burdens, and substitution threats from integrated building systems.
Product Type:
Substitution pressure from whole-home energy management platforms hits indoor and basic adapter formats hardest, while metering-capable variants defend attach rates through regulatory compliance mandates.
- Indoor Plugs:Compact 10-15 ampere units with basic relay switching and Wi-Fi transceivers dominate absolute shipment volumes through retail big-box and e-commerce channels. Residential buyers in the United States and Germany deploy these for lamp and entertainment equipment control where hub-free installation matters most.
- Energy Monitoring Plugs:Embedded real-time power measurement circuits with calibrated wattage telemetry satisfy EU Ecodesign Directive metering requirements and California utility rebate eligibility. Landlord submetering mandates in Germany and commercial Scope 2 reporting obligations under CSRD sustain premium pricing power against standalone alternatives.
- Outdoor Plugs:Weatherized housings with IP64+ ratings and ground-fault protection target patio lighting and pool equipment circuits.
- Smart Adapters:Pass-through form factors converting standard outlets into single smart ports address legacy infrastructure constraints in pre-1980s housing stock.
Indoor plugs anchor the volume base while energy monitoring plugs gain share at the steepest rate.
Connectivity:
Protocol selection determines hub dependency, installation friction, and compatibility with incumbent whole-home platforms across residential versus commercial contexts.
- Wi-Fi:Direct router communication eliminates bridge hardware, reducing upfront cost and setup complexity for mainstream residential buyers. Wi-Fi 6 penetration in multi-unit dwellings across the United States and China is displacing earlier mesh-dependent configurations through improved latency stability in dense RF environments.
- Zigbee:Sub-gigahertz mesh networking delivers lower power draw and superior whole-home coverage for integrated automation stacks. German and Dutch utility-managed demand response programs specify Zigbee for load control endpoints to ensure signal reliability during peak shaving events.
- Z-Wave:Proprietary sub-GHz protocol retains installed base in North American security-centric home automation systems.
- Bluetooth:Low-energy variants serve proximity-based commissioning and temporary control scenarios without network infrastructure.
Wi-Fi carries the volume base while Zigbee defends structural position in regulated utility programs.
End User:
Procurement authority and energy accountability rules fragment customer requirements across consumer self-install, landlord bulk purchase, and enterprise IT governance models.
- Residential:Homeowner-driven purchases through retail and direct-to-consumer channels prioritize smartphone app usability and voice assistant integration. Climbing utility rates in Germany and California accelerate retrofit adoption beyond early adopter cohorts.
- Small Business:Facility managers in leased commercial spaces procure through distributor e-commerce portals to unbundle monitoring from stalled building management system upgrades. German Mittelstand manufacturing facilities and US Class-B office retrofits drive this procurement pattern shift.
- Large Enterprises:IT security governance and centralized procurement favor enterprise-grade Zigbee stacks with certificate-based device authentication.
- DIY Enthusiasts:Open-source firmware compatibility and local API access distinguish this segment from mass-market retail.
Residential buyers anchor the volume base while small business procurement expands most quickly.
Application:
Use case specificity determines whether smart plugs compete against dedicated hardware or serve as flexible retrofit solutions.
- Home Automation:Scheduling, scene control, and voice integration dominate consumer value propositions. United States smart-home penetration rates and retail channel density sustain this application's volume leadership.
- Energy Management:Granular consumption telemetry and utility demand response integration command hardware premiums. EU Ecodesign Directive compliance requirements and German landlord submetering rules embed this application in regulatory workflows.
- Security Systems:Randomized occupancy simulation and remote status verification serve vacation property and second-home owners.
- Appliance Control:Load-specific optimization for water heaters, dehumidifiers, and auxiliary HVAC units targets efficiency-conscious retrofitters.
Home automation anchors the volume base while energy management climbs the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense retail channel infrastructure and utility rebate programs anchor North American demand, while Germany's landlord submetering mandates and China's factory-to-consumer e-commerce density shape distinct procurement patterns across three continents.
United States
Big-box retail distribution networks and FCC-certified Wi-Fi 6 hardware penetration drive residential retrofit cycles. The Inflation Reduction Act's residential energy efficiency incentives compress payback periods for metering-capable units. California's Title 24 building standards and Texas's ERCOT demand response programs concentrate procurement in coastal and deregulated grid zones.
Germany
EU Ecodesign Directive compliance deadlines and landlord energy accountability rules accelerate commercial bulk purchases. The Federal Network Agency's smart metering rollout specifications favor Zigbee mesh architectures for utility-managed load control. Industrial Mittelstand facilities in Baden-Württemberg and North Rhine-Westphalia unbundle plug procurement from stalled building management upgrades.
China
MIIT GB standards for wireless transmitters and domestic e-commerce platform density enable cost-engineered Wi-Fi module proliferation. Factory clusters in Shenzhen and Dongguan supply both domestic channels and export markets with firmware-customized variants. Tier-one cities including Shanghai and Beijing deploy municipal smart city pilots with utility-managed street lighting controls.
India
Bangalore and Hyderabad smart city tenders create procurement channels for utility-managed public housing load control. The Bureau of Indian Standards' compulsory registration scheme for electronic goods shapes import compliance timelines. Domestic assembly operations in Tamil Nadu and Gujarat address price-sensitive residential retrofit demand through distributor networks.
Japan
METI's Top Runner program for standby power reduction and home energy management system integration standards elevate hardware specifications. Tokyo and Osaka metropolitan area utility demand response programs specify sub-gigahertz mesh protocols for signal reliability. Premium retail channels in Kanto and Kansai regions sustain higher-margin Zigbee product tiers.
Wireless Smart Plug Market Competitive Landscape
Listed leaders compete with private specialists across certification velocity and retail channel access. The vendor base fragments across three tiers: ecosystem-anchored platforms with voice assistant integration, component-integrated manufacturers leveraging captive semiconductor supply, and white-label specialists serving distributor private-label programs. Capacity expansion and strategic certification pre-positioning dominate competitive moves as cybersecurity baselines diverge across jurisdictions.
Within the ecosystem-anchored tier, TP-Link Technologies and Xiaomi Inc. exemplify divergent geographic positioning strategies. Panasonic Corporation occupies a position bridging premium hardware fabrication and enterprise-grade protocol stacks. These three entities represent distinct archetypes: retail volume leadership through channel density, cost-engineered module dominance in emerging markets, and integrated energy analytics for regulated commercial procurement.
| Leading Market Players |
|---|
| TP-Link Technologies |
| Panasonic Corporation |
| Xiaomi Inc. |
| Amazon |
| Belkin International |
| D-Link Corporation |
| Leviton Manufacturing |
| Philips |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan and South Korea foundries lock in RF transceiver supply and stabilize unit economics for vendors navigating EU cybersecurity certification costs. These arrangements shield premium-tier manufacturers from spot-market silicon volatility while forcing economy-SKU producers toward margin-compression or regional withdrawal.
Pricing Analysis
Volume-discount tiering structures separate energy-monitoring plugs with CE/FCC certification from basic indoor units and white-label economy variants. Certification-grade differentiation and utility rebate eligibility sustain premium pricing power in Germany and California, while cost compression in Wi-Fi modules intensifies pricing pressure at the economy tier. Residential buyers through e-commerce channels exhibit highest price sensitivity, whereas facility managers procuring for landlord submetering mandates show lowest sensitivity due to compliance-driven purchasing authority.
Supply Chain Analysis
Inventory lead times for microcontrollers and RF transceivers have extended as Taiwan and South Korea fabrication capacity prioritizes automotive and smartphone allocations. The supply chain draws from Shenzhen and Dongguan assembly clusters, with raw material dependencies spanning silicon wafers, relay components, and flame-retardant housings. Single-source vulnerability concentrates in advanced node semiconductor fabrication, while distribution runs through big-box retail, distributor e-commerce portals, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware security engineering talent scarcity constrains how quickly vendors can implement secure boot chains and signed OTA updates demanded by fragmented national cybersecurity baselines. This capability gap separates pre-certified incumbents from challengers facing 6-12 month launch delays.
For Market Incumbents: Secure pre-certification against EU Cybersecurity Act, US NIST IoT guidelines, and China GB standards before regional launches to defend against white-label challengers exploiting Matter protocol convergence. Prioritize backward integration into captive microcontroller supply through foundry partnerships in Taiwan, and reinforce channel control through exclusive distributor e-commerce portal placements for facility manager procurement. For New Entrants and Emerging Players: Firmware customization services for landlord submetering mandates represent a service-layer gap where incumbents under-serve Mittelstand manufacturing facilities and US Class-B office retrofits. Target German commercial procurement through unbundled energy monitoring offerings, and pursue utility-managed demand response program certification as the fastest path to revenue visibility. For Investors and Strategic Acquirers: Component-integrated manufacturers with captive semiconductor supply and enterprise-grade Zigbee stacks command durable positioning as acquisition targets. Long-term viability hinges on cybersecurity certification velocity rather than hardware cost engineering; watch for EU Radio Equipment Directive enforcement actions as the inflection indicator separating compliant from non-compliant vendor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Pre-Positioning | EU Radio Equipment Directive amendments force firmware architecture redesigns for CE marking eligibility. |
| Foundry Capacity Reservation | Taiwan and South Korea fabrication allocation constraints favor vendors with long-term supply agreements. |
| Commercial Channel Unbundling | Facility managers procuring through distributor e-commerce portals bypass stalled BMS upgrade cycles. |
| Matter Protocol Integration | Cross-platform interoperability collapses ecosystem lock-in for challenger brand market access. |
| Edge-Based Load Disaggregation | Local inference algorithms satisfy German home energy audit requirements without subscription fees. |
Research Methodology
The analysis maps indoor plugs, energy monitoring variants, outdoor housings, and smart adapters, each validated through primary interviews with smart home platform engineers, facility managers at Mittelstand facilities, utility demand response program coordinators, and big-box retail category buyers. Secondary sources include FCC equipment authorization databases, EU Radio Equipment Directive guidance documents, MIIT GB standard filings, and utility rebate program specifications. Bottom-up shipment estimates triangulate against top-down market value reconstructions.
Consistency checks validated volume and value outputs against hyperscaler smart home device disclosures, foundry capacity allocation reports, and customs trade data for RF module categories. The analytical framework models connectivity protocol, end-user procurement authority, and application specificity across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic indicators and regulatory implementation timelines, incorporating smart city tender pipelines and landlord submetering mandate adoption curves as industry-specific inputs.
Underlying assumptions cover EU Ecodesign Directive enforcement intensity, foundry capacity expansion trajectories, and Matter protocol adoption velocity, with deviation risk concentrated in cybersecurity certification timeline extensions and geopolitical disruption to Taiwan semiconductor supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Indonesia IoT Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
IoT IAM Market
Internet of Things (IoT)
Satellite IoT Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IoT Integration Market