
 Wireless Earphone Market | 2026-2036
Wireless Earphone Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Earphone Market Intelligence
Chinese contract manufacturers is shifting assembly capacity toward true wireless stereo earbuds as Bluetooth 5.3 and LE Audio protocols mature. Apple Inc. leverages vertical integration across its custom silicon and audio codec stack to sustain premium positioning. Samsung Electronics Co., Ltd. anchors its Galaxy Buds lineup through tight hardware-software coupling with Android ecosystems. Sony Group Corporation differentiates via industry-leading active noise cancellation algorithms and studio-grade driver tuning.
Wireless earphones are untethered audio reproduction devices employing Bluetooth radio frequency transceivers, lithium-polymer cells, and MEMS microphones to deliver stereo sound without physical connection to source equipment. Typical units operate within 2.400–2.4835 GHz ISM bands with 10-meter nominal range and integrate codecs such as AAC, aptX, or LC3 for compressed audio transmission. True wireless configurations dominate value creation as they eliminate neckband wiring and command higher average selling prices through charging case bundling. The connectivity dimension shows Bluetooth sustaining absolute volume leadership while NFC pairing gains traction in enterprise deployment scenarios. Consumer end users represent the mature revenue base, whereas gamer-oriented sub-segments with sub-20ms latency specifications are expanding fastest.
The Federal Communications Commission governs RF emission limits and spectrum allocation for devices sold in the United States, while the Bluetooth Special Interest Group administers interoperability certification that gates market access for non-compliant hardware. The European Union's Radio Equipment Directive mandates CE marking and electromagnetic compatibility testing, forcing redesign cycles for manufacturers targeting European distribution. REACH chemical restrictions further constrain adhesive and PCB substrate selection in driver assemblies. Stakeholders must monitor LE Audio broadcast audio capabilities and Auracast deployment timelines as these standards will reshape venue-based assistive listening and public audio streaming infrastructure.
Market Dynamics
Bluetooth Low Energy Audio certification is compressing interoperability testing timelines while Shenzhen's manufacturing cluster accelerates component cost deflation across true wireless stereo supply chains.
Growth Catalysts
- Fitness-Driven Replacement Cycles:Exercise applications now dominate upgrade timing for wireless audio hardware. Gym memberships and outdoor activity participation correlate directly with device refresh frequency.
- REACH Chemical Compliance:European adhesive restrictions are forcing PCB substrate redesigns that incidentally improve thermal dissipation in driver assemblies.
- Remote Work Audio Standards:Enterprise IT departments now mandate sub-50ms latency specifications for video conferencing compatibility. MEMS microphone arrays with beamforming algorithms satisfy these procurement requirements.
Market Restraints
- Lithium-Polymer Cell Concentration:Battery cell production clusters in China's Pearl River Delta create single-source vulnerability for charging case manufacturers.
- FCC RF Certification Bottlenecks:United States market entry requires 8-14 week testing queues at accredited laboratories. Smaller OEMs face working capital strain during these intervals.
- Wired Audio Residual Preference:Studio professionals and audiophile segments continue specifying 3.5mm analog connections for uncompressed source fidelity.
Strategic Opportunities
- Auracast Public Infrastructure:LE Audio broadcast capabilities enable venue-based assistive listening deployments. Airports, museums, and theaters represent untapped installation contracts.
- Gaming Sub-20ms Latency Tier:Competitive multiplayer titles now specify audio synchronization thresholds. Hardware vendors can command premium positioning through dedicated low-latency codec optimization.
- India BIS Certification Pathway:Mandatory safety testing for wireless devices creates first-mover advantage for brands establishing local compliance infrastructure ahead of enforcement deadlines.
Industry Challenges
- MEMS Microphone Integration Complexity:Multi-microphone noise cancellation algorithms require acoustic engineering talent scarce outside Shenzhen, Tokyo, and San Jose clusters.
- Bluetooth SIG Certification Backlogs:Interoperability testing delays extend product launch windows. Queue management now determines seasonal retail placement.
- Codec Licensing Fragmentation:AAC, aptX, and LC3 intellectual property pools impose royalty stacking. Legal teams must navigate overlapping patent claims across Qualcomm, Fraunhofer, and Bluetooth SIG portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Earphone Market |
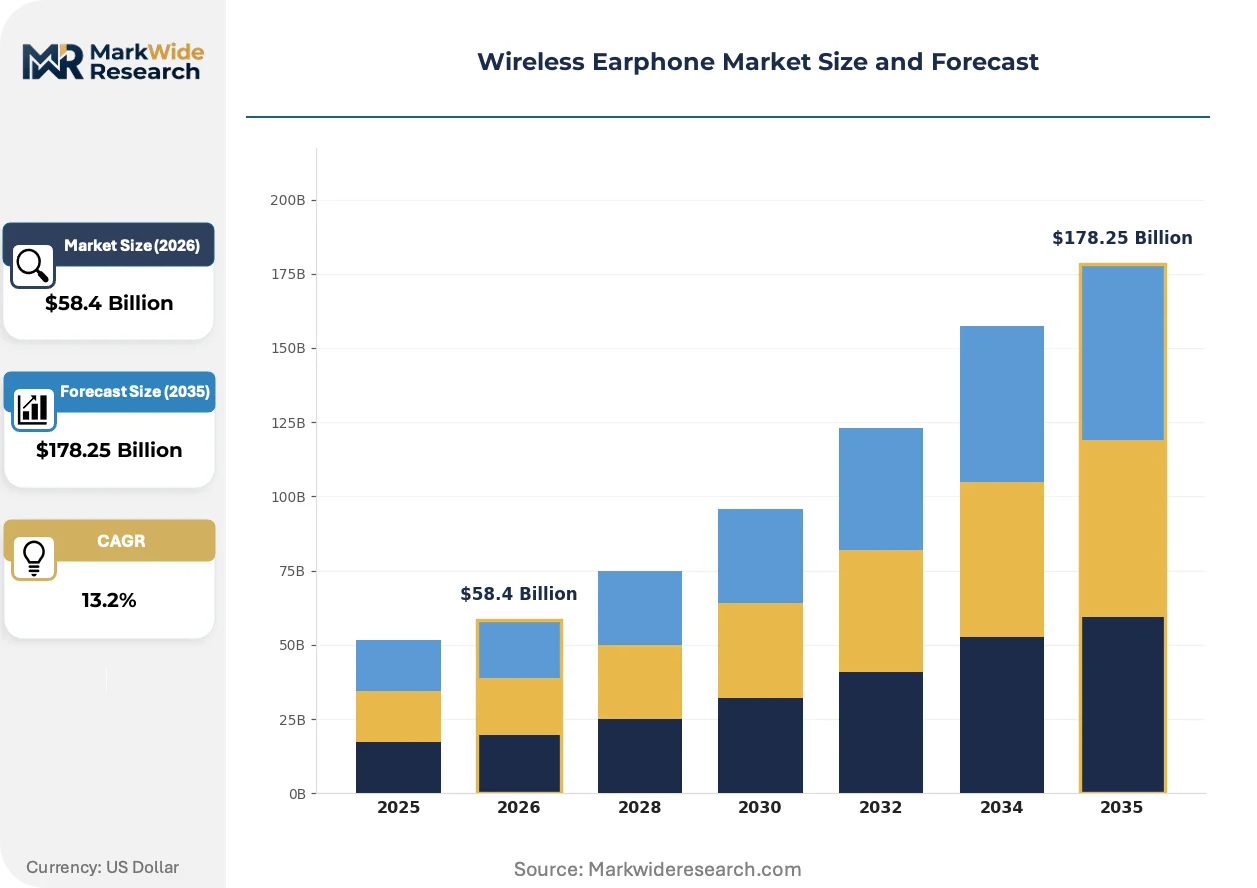
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, Over-Ear, On-Ear, True Wireless Connectivity: Bluetooth, NFC, Infrared, Wi-Fi End User: Consumers, Businesses, Gamers, Audiophiles Feature: Noise Cancellation, Water Resistance, Touch Control, Voice Assistant |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Bose Corporation, Sony Group Corporation, Sennheiser electronic GmbH & Co. KG, Logitech International S.A., Xiaomi Corporation, Skullcandy, JVCKENWOOD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Earphone Market Strategic Shifts & Innovations
Codec efficiency gains and broadcast audio protocols are restructuring how audio streams reach end users across consumer and commercial deployment scenarios.
LC3 codec technology is integrating into mid-tier chipset platforms after initial flagship exclusivity periods. White-label manufacturers in Shenzhen now access this compression standard through MediaTek and BES Semiconductor reference designs. The technology is integrating lossless-equivalent perceived quality at half the bitrate of SBC predecessors, enabling smaller battery footprints or extended playback duration within identical charging case dimensions.
REACH substance restrictions are constraining solder flux and conformal coating chemistries in European-bound production lines. Manufacturers reformulating driver assemblies report 3-6 month qualification delays but achieve concurrent thermal performance improvements. Premium tier products targeting German and French distribution channels absorb these compliance costs most readily through existing margin structures.
Enterprise procurement departments now unbundle audio hardware from unified communications platform contracts. IT administrators source wireless earphones separately from Microsoft Teams or Zoom licensing, creating direct OEM relationships previously intermediated by systems integrators. This pattern concentrates in North American Fortune 500 deployments where device standardization reduces help desk ticket volumes.
Wireless Earphone Market Segmentation
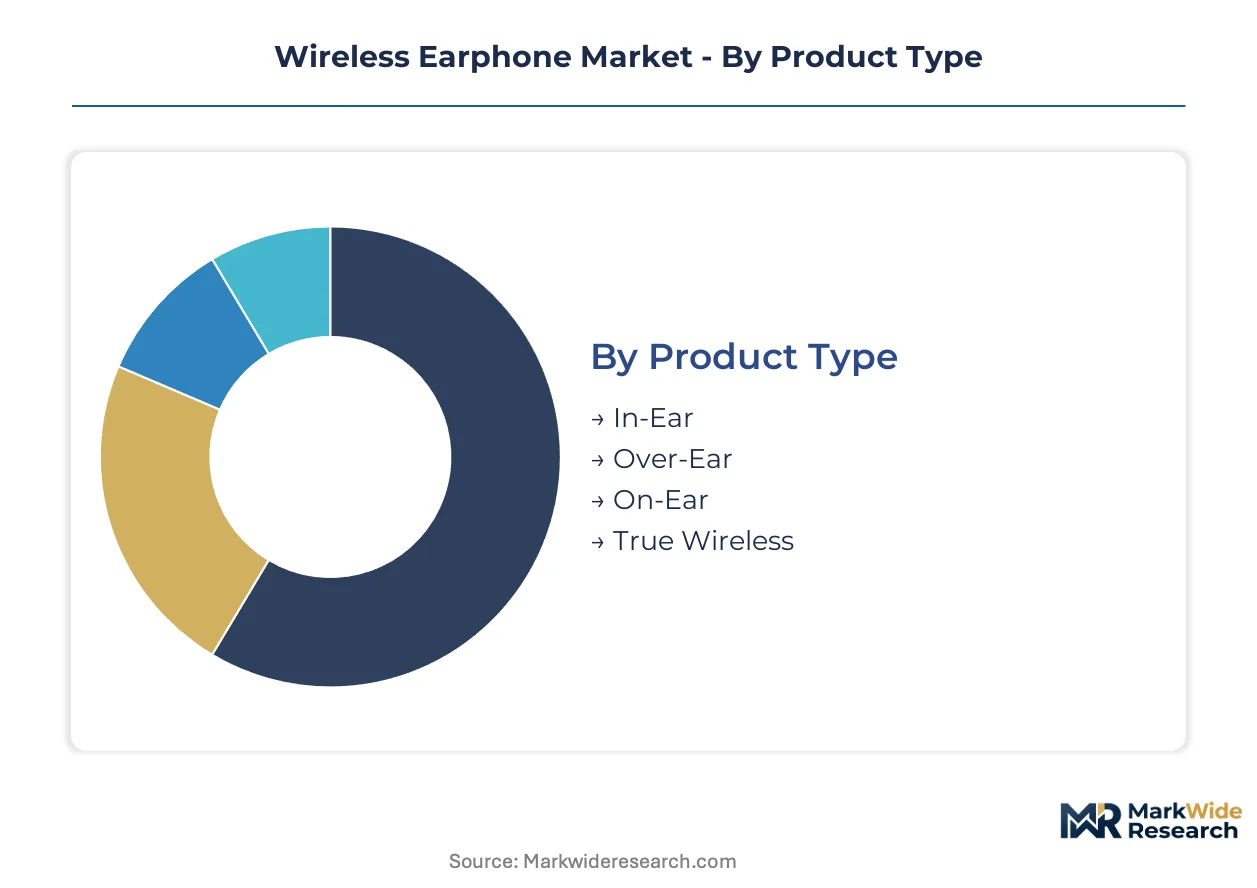
Wireless earphone segmentation reveals how hardware specifications, connectivity protocols, and user workflows fragment manufacturing priorities. Each dimension carries distinct margin structures and certification requirements that reshape supplier selection.
Product Type:
Integration depth separates standalone wearable units from embedded systems in smart eyewear or helmet audio. Form factor determines acoustic chamber geometry and driver selection.
- True Wireless:Completely cable-free configurations pair individual earbuds with a charging case containing lithium-polymer cells. Shenzhen contract manufacturers dominate assembly for both domestic Chinese brands and Western OEMs targeting gym and commute use cases.
- In-Ear:Canal-sealing designs with silicone or foam tips create passive noise isolation through mechanical fit. Demand concentrates in Japan and South Korea where compact portability outweighs battery life concerns.
- Over-Ear:Circumaural cups housing larger dynamic drivers deliver extended frequency response. Audiophile segments in Germany and the United States sustain premium positioning through planar magnetic and electrostatic variants.
- On-Ear:Supra-aural pads rest against rather than around the ear, balancing portability with driver size. Corporate procurement departments favor this category for hot-desking environments where device sharing occurs.
Volume placements concentrate in True Wireless; the faster expansion belongs to In-Ear configurations as fitness applications multiply.
Connectivity:
Cost tier stratification separates royalty-bearing proprietary stacks from open-standard implementations. Protocol selection gates interoperability with source devices and determines power budget allocation.
- Bluetooth:Radio frequency transceivers operating in the 2.400–2.4835 GHz ISM band sustain absolute volume leadership through backward compatibility and chipset cost deflation. FCC and Bluetooth SIG certification requirements create compliance moats for established suppliers.
- NFC:Near-field magnetic induction enables tap-to-pair workflows in enterprise deployment scenarios. Financial services and healthcare facilities in Singapore and Switzerland specify this protocol for reduced IT support burden.
- Wi-Fi:Higher bandwidth connectivity supports lossless audio streams and multi-room synchronization. Home theater integration drives adoption in North American and Australian residential markets.
- Infrared:Line-of-sight optical transmission persists in specialized aviation and assistive listening installations. Regulatory simplicity attracts institutional buyers with restricted RF environments.
Bluetooth captures the dominant share; Wi-Fi connectivity is gaining share fastest as residential audio ecosystems mature.
End User:
Application-specific requirements fragment performance specifications across latency tolerance, microphone array complexity, and durability ratings. Each user category imposes distinct procurement channels and replacement cadences.
- Consumers:General-purpose listeners prioritize convenience and brand affiliation over technical specifications. Mass-market retail distribution through electronics chains and direct-to-consumer platforms sustains volume.
- Gamers:Competitive multiplayer participants demand sub-20ms latency synchronization between visual and audio channels. Dedicated low-latency codec implementations command premium positioning in South Korea and the United States esports markets.
- Businesses:Enterprise IT departments mandate MEMS microphone arrays with beamforming algorithms for video conferencing compatibility. Microsoft Teams and Zoom certification programs gate procurement eligibility.
- Audiophiles:Critical listeners specify uncompressed or high-resolution codec support with flat frequency response tuning. Specialist retailers and direct sales sustain margin structures resistant to mass-market discounting.
Consumer volume dominates current shipments; gamer-oriented specifications show the steepest expansion trajectory as latency-sensitive applications proliferate.
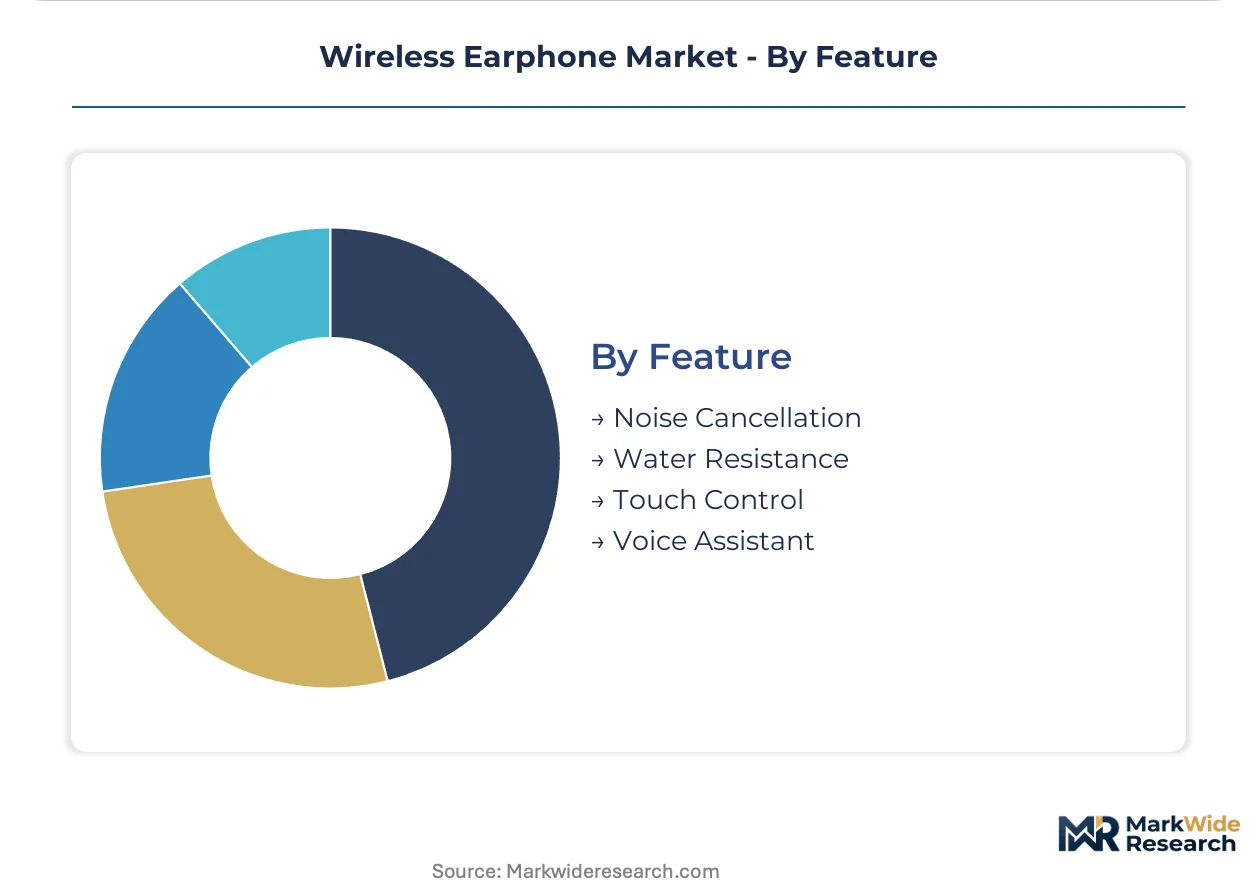
Feature:
Customer type differentiation separates must-have baseline capabilities from premium tier add-ons. Feature bundling determines average selling price realization and manufacturing BOM complexity.
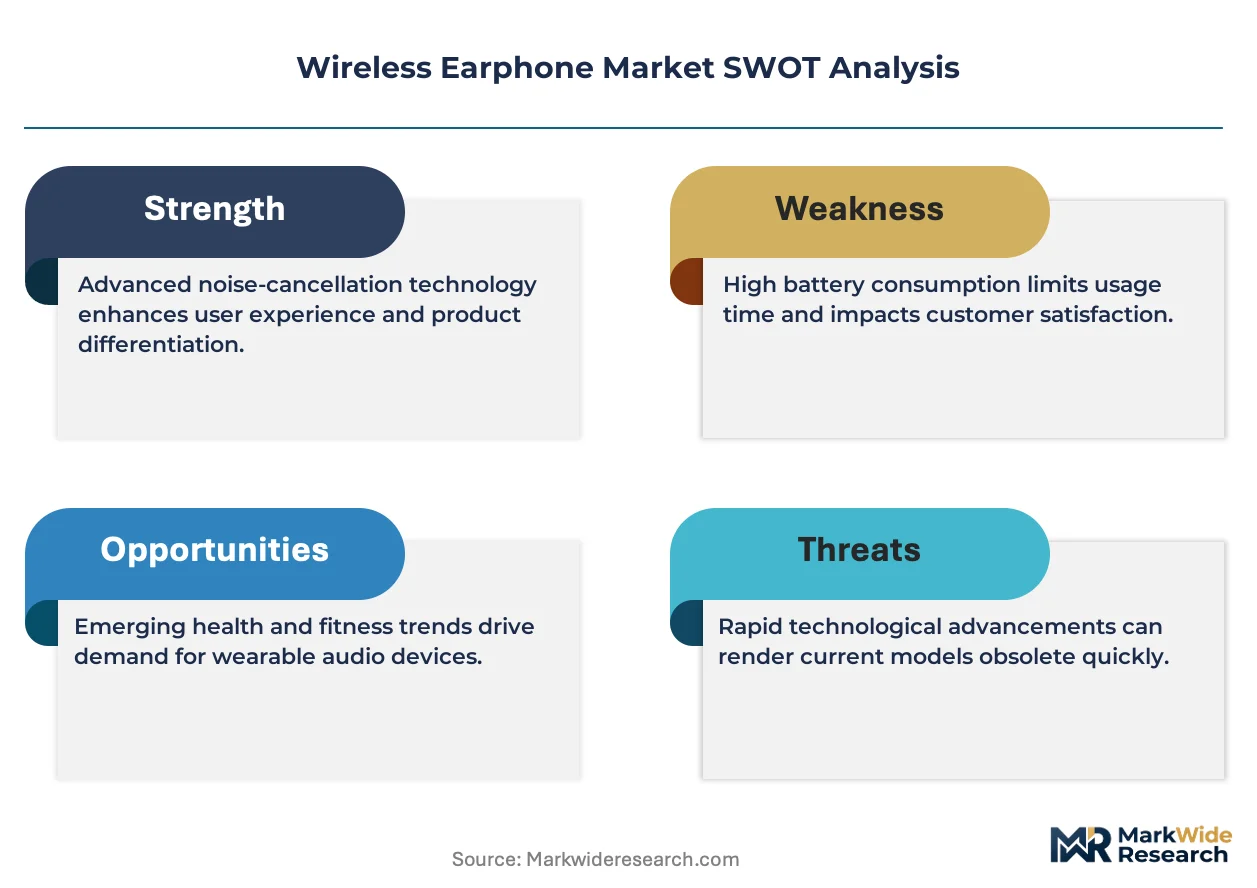
- Noise Cancellation:Hybrid active systems combining feedforward and feedback microphones with DSP processing. Sony and Bose algorithm implementations set performance benchmarks for frequent flyers in the United States and United Kingdom.
- Voice Assistant:Wake-word detection and cloud connectivity for Alexa, Google Assistant, or Siri integration. Smart home ecosystem penetration in Germany and Japan drives inclusion at mid-tier price points.
- Water Resistance:IPX4 through IPX7 ingress protection ratings for sweat and rain exposure. Fitness applications in Australia and Brazil specify these certifications as baseline requirements.
- Touch Control:Capacitive surface interfaces replacing mechanical buttons for playback and call management. Gesture complexity varies by manufacturer with haptic feedback emerging as a differentiator.
Noise Cancellation anchors premium tier placements; Voice Assistant integration is climbing the fastest as smart home adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-polymer cell production clusters in China's Pearl River Delta anchor upstream material flows for charging case manufacturers worldwide. Shenzhen's electronics manufacturing ecosystem compresses component lead times and enables rapid product iteration cycles. This geographic concentration shapes competitive positioning across North American, European, and Asian end markets.
United States
Fitness enthusiasts and remote workers drive replacement cycles for wireless audio hardware. FCC RF emission standards and Bluetooth SIG interoperability certification create compliance moats for established suppliers. Austin and San Jose host acoustic engineering talent clusters developing MEMS microphone arrays with beamforming algorithms for enterprise video conferencing.
Germany
Audiophile segments sustain premium positioning for over-ear configurations with planar magnetic drivers. REACH chemical restrictions and CE marking under the Radio Equipment Directive force PCB substrate redesigns that improve thermal dissipation. Berlin and Munich anchor specialist retail distribution channels resistant to mass-market discounting.
China
Shenzhen's contract manufacturers shift assembly capacity toward true wireless stereo earbuds as Bluetooth 5.3 and LE Audio protocols mature. MIIT governs radio transmission equipment type approval while GB standards address electromagnetic compatibility. The Pearl River Delta drives component cost compression for both domestic brands and export-bound production.
Japan
Compact in-ear configurations dominate demand where portability outweighs battery life concerns. METI oversees technical standards conformity certification for radio equipment. Tokyo and Osaka clusters concentrate acoustic engineering expertise for hybrid active noise cancellation algorithms.
South Korea
Esports participants demand sub-20ms latency specifications for competitive multiplayer gaming. MFDS regulates product safety while KCC manages radio frequency certification. Seoul's hardware-software coupling capabilities support tight Android ecosystem integration for Galaxy Buds-tier products.
Wireless Earphone Market Key Industry Players
Global majors compete with regional champions across silicon integration, acoustic engineering, and manufacturing scale. The vendor base stratifies into three tiers: vertically integrated technology conglomerates controlling custom chipsets and codec stacks; audio-specialist houses with studio-grade driver tuning heritage; and Shenzhen-based contract manufacturers serving white-label and domestic brand demand. Consolidation pressures concentrate in the mid-tier as LE Audio certification requirements raise R&D barriers. Dominant competitive moves include backward integration into MEMS microphone supply and geographic expansion through India BIS certification pathways.
Within the vertically integrated tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify hardware-software coupling strategies that sustain premium positioning. Sony Group Corporation anchors the audio-specialist archetype through active noise cancellation algorithm development. These three entities occupy positions that reflect divergent competitive foundations: Cupertino-based captive silicon control, Seoul-based Android ecosystem integration, and Tokyo-based acoustic engineering heritage.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Bose Corporation |
| Sony Group Corporation |
| Sennheiser electronic GmbH & Co. KG |
| Logitech International S.A. |
| Xiaomi Corporation |
| Skullcandy |
| JVCKENWOOD Corporation |
| Others |
Cost & Logistics Intelligence
Enterprise IT procurement mandates for sub-50ms latency specifications and MEMS microphone beamforming arrays are forcing contract manufacturers to absorb qualification costs for premium-tier chipsets, compressing margins on standard-tier products while inflating average selling prices for certified enterprise configurations. Shenzhen's component cost deflation partially offsets this pressure, but REACH compliance redesigns for European-bound shipments add 3-6 month qualification delays that prop pricing premiums for compliant inventory.
Pricing Analysis
Warranty and service bundling separates premium positioning from unbundled transactional sales, with enterprise procurement contracts now incorporating replacement guarantees and dedicated support tiers that inflate lifetime contract values. Three-tier pricing structure across premium, standard, and economy levels reflects Bluetooth SIG certification tier, active noise cancellation algorithm sophistication, and charging case battery capacity. Cost compression in standard-tier true wireless configurations is intensifying because MediaTek and BES Semiconductor reference designs democratize LC3 codec access. Gamer and audiophile segments exhibit lowest price sensitivity; mass-market fitness consumers drive volume at thin margins.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Apple, Samsung, and Sony, while white-label manufacturers serve domestic Chinese brands and Western retailers through Shenzhen trading companies. Lithium-polymer cell production clusters in China, South Korea, and Japan anchor upstream material flows for charging case manufacturers. MEMS microphone arrays, Bluetooth 5.3 chipsets, and acoustic driver assemblies draw from Taiwan and South Korea foundries. Single-source vulnerability in China's Pearl River Delta battery cell concentration creates supply chain risk. Distribution runs through electronics retail chains, direct-to-consumer platforms, and enterprise IT procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS microphone integration complexity and acoustic engineering talent scarcity outside Shenzhen, Tokyo, and San Jose clusters prop pricing for noise cancellation-enabled configurations. This supply-constrained dynamic sustains margin structures for incumbent specialists while raising barriers for undifferentiated entrants.
For Market Incumbents: To counter LE Audio certification backlogs and interoperability testing delays, secure queue priority through Bluetooth SIG membership tier advancement and backward integration into MEMS microphone supply. Capacity addition in India's BIS certification infrastructure captures first-mover advantage ahead of enforcement deadlines. For New Entrants and Emerging Players: Launch via white-label manufacturing partnerships targeting India's BIS certification pathway and Auracast public infrastructure deployment contracts. Gaming sub-20ms latency specifications represent the most penetrable segment, with esports procurement in South Korea and the United States accepting premium positioning for dedicated low-latency codec optimization. For Investors and Strategic Acquirers: The window for entry favors acoustic engineering specialists with hybrid active noise cancellation algorithm portfolios and established Bluetooth SIG certification relationships. Long-term viability hinges on backward integration into driver assembly design and REACH-compliant substrate qualification capabilities. The signal to watch is Auracast venue deployment timelines in airports, museums, and theaters as inflection indicator for broadcast audio hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| LE Audio Certification Investment | Bluetooth SIG queue priority secures seasonal retail placement against testing backlogs. |
| Backward Integration into MEMS Microphones | In-house production of beamforming arrays reduces dependency on Tokyo and San Jose talent clusters. |
| India BIS Certification Infrastructure | Local compliance capability captures first-mover advantage ahead of wireless device safety mandates. |
| Auracast Venue Partnership Program | Airport and museum installation contracts establish recurring revenue from broadcast audio deployments. |
| Gaming Latency Optimization R&D | Sub-20ms codec implementations command premium positioning in South Korea esports procurement. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with acoustic engineering directors, enterprise IT procurement managers, contract manufacturing executives, and Bluetooth SIG certification leads with validation against FCC equipment authorization databases, MIIT radio transmission approvals, and European Radio Equipment Directive conformity assessments. Bottom-up shipment modeling and top-down value estimation triangulated across component bill-of-material analysis and retail channel audit data.
Granularity-level framing applied product type, connectivity protocol, end user segment, and feature bundling dimensions at the SKU level across the projection horizon. CAGRs derived from logistic diffusion modeling of Bluetooth 5.3 and LE Audio adoption curves, with chipset cost deflation trajectories and lithium-polymer cell pricing trends as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for Auracast broadcast audio deployment would alter the outlook for venue-based hardware demand. Forecasts reflect base-case assumptions regarding REACH chemical restriction enforcement timelines and India BIS certification implementation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Soft Support Products Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Phone Tripod Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
4K Television Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Smart Headphones Market