
 True Wireless Stereo Market | 2026-2036
True Wireless Stereo Market Size, Share, and Industry Trends Forecast 2026-2036
True Wireless Stereo Market Analytics
The EU's Ecodesign for Energy-related Products Directive is rebalancing material selection and battery longevity requirements across the True Wireless Stereo supply base. Apple Inc. leverages its silicon-to-software integration to sustain premium positioning and control end-to-end audio latency. Samsung Electronics Co., Ltd. anchors its Galaxy Buds portfolio through deep hardware-software coupling with its smartphone ecosystem. Sony Corporation differentiates via proprietary LDAC codec licensing and audiophile-grade driver engineering.
True Wireless Stereo denotes a cordless audio architecture where two independent earpieces receive synchronized left/right channel streams from a source device, typically operating via Bluetooth 5.3 or higher with sub-40ms latency thresholds for video synchronization. The primary commercial purpose is untethered personal audio consumption across mobile computing, fitness, and communication workflows. In-ear configurations dominate unit economics due to miniaturization feasibility and mass-market price accessibility, while active noise cancellation technology commands disproportionate margin pools as consumers prioritize acoustic isolation. Sports-oriented designs represent the fastest-growing product type as sweat resistance ratings and secure-fit mechanisms migrate from premium to mid-tier price bands.
FCC equipment authorization in the United States, CE marking under the EU Radio Equipment Directive, and China's SRRC certification collectively govern transmission power, electromagnetic compatibility, and spectrum compliance for wireless audio devices. These frameworks shape demand by mandating interoperability testing, battery safety protocols, and recyclability disclosures that filter out subscale manufacturers. Stakeholders must monitor evolving right-to-repair mandates and battery passport requirements that will force modular design investments and reshape aftermarket service economics.
Market Dynamics
Bluetooth LE Audio and Auracast broadcast protocols are compressing latency benchmarks below 20ms while fragmenting codec licensing power across semiconductor vendors rather than handset OEMs.
Growth Catalysts
- Fitness-optimized audio demand:Workout-integrated biometric sensing and secure-fit mechanisms are pulling sports-oriented designs from premium tiers into mass-market price bands.
- EU Ecodesign Directive:Battery longevity mandates and material recyclability disclosures are filtering out subscale assemblers and consolidating contract manufacturing toward vertically integrated facilities.
- LDAC and LC3plus codec proliferation:Lossless streaming over Bluetooth is automating quality-tier differentiation that previously required wired connections.
Market Restraints
- Lithium-polymer cell cost volatility:Miniaturized battery packs constitute 18-22% of bill-of-materials exposure, with cell suppliers concentrated in Guangdong and Jiangsu provinces.
- FCC/CE/SRRC certification stacking:Multi-jurisdictional radio equipment authorization extends product launch timelines by 4-7 months for non-vertically integrated brands.
- Wired earphone residual substitution:Audiophile and studio monitoring segments retain preference for analog connectivity in professional content creation workflows.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component assembly incentives are attracting acoustic driver and MEMS microphone suppliers to establish captive capacity outside China.
- Auracast public broadcast deployment:Airports, stadiums, and transit authorities in Germany and the United Kingdom are piloting assistive listening infrastructure that requires LE Audio-native hardware.
- Hearing aid convergence:OTC hearing aid regulations from the US FDA are collapsing the boundary between medical audio devices and consumer TWS form factors.
Industry Challenges
- RF antenna engineering scarcity:Compact 2.4GHz antenna design for metalized enclosures requires specialized simulation talent concentrated among semiconductor reference design teams.
- Right-to-repair modularization:EU battery passport requirements are forcing adhesive-free assembly redesigns that conflict with IPX7 waterproofing certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | True Wireless Stereo Market |
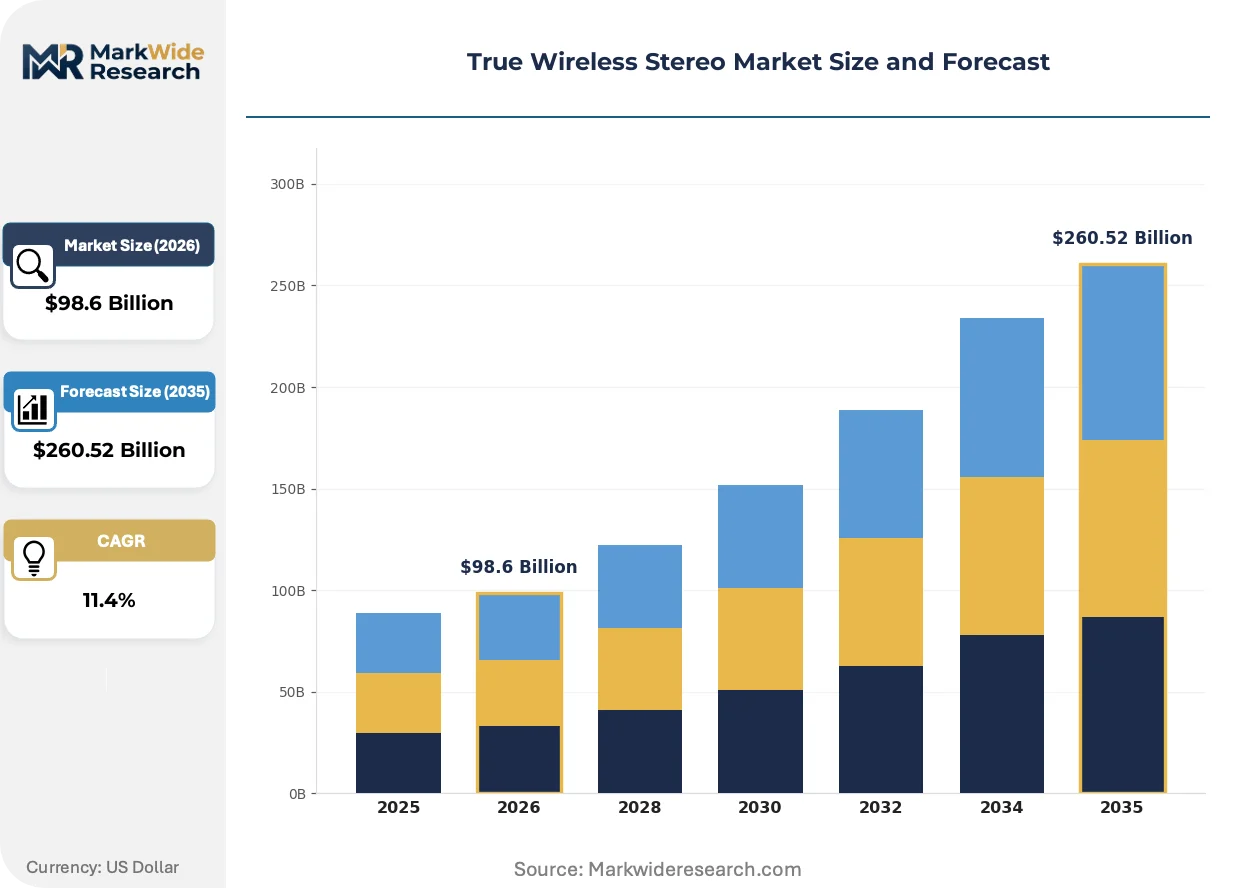
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $260.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, Over-Ear, On-Ear, Sports Technology: Bluetooth, NFC, Wi-Fi, Active Noise Cancellation End User: Consumers, Athletes, Audiophiles, Professionals Distribution Channel: Online Retailers, Brick-and-Mortar, Specialty Stores, Retail Chains |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Sony Corporation, Bose Corporation, Jabra, Sennheiser Electronic GmbH & Co. KG, Xiaomi Corporation, Anker Innovations Limited, Harman International Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
True Wireless Stereo Market Evolving Landscape
Audio silicon integration is collapsing the traditional boundary between connectivity chipsets and DSP acceleration, compressing the vendor landscape toward semiconductor houses with in-house audio codec IP.
Neural network-based adaptive noise cancellation is automating real-time acoustic environment classification that previously required manual mode switching. Fitness enthusiasts and open-office workers are adopting these systems fastest, with flagship-tier penetration exceeding 60% in North American and Chinese urban markets. The technology is automating the displacement of fixed-filter ANC architectures that dominated 2019-2023 product cycles.
China's SRRC certification framework is tightening spurious emission limits for 2.4GHz devices, forcing firmware-level power backoff algorithms that reduce effective transmission range. Domestic brands with in-house RF calibration capabilities are absorbing compliance costs faster than import-reliant competitors. The regulatory friction is concentrating market share among vertically integrated manufacturers with captive testing laboratories.
Direct-to-consumer subscription bundles are unbundling hardware-software value capture, with audio streaming services subsidizing device costs in exchange for multi-year membership lock-in. This channel compression is displacing traditional retail margin stacking across electronics superstores in South Korea and Japan. The model is most visible among smartphone ecosystem vendors with captive content platforms.
True Wireless Stereo Market Segmentation
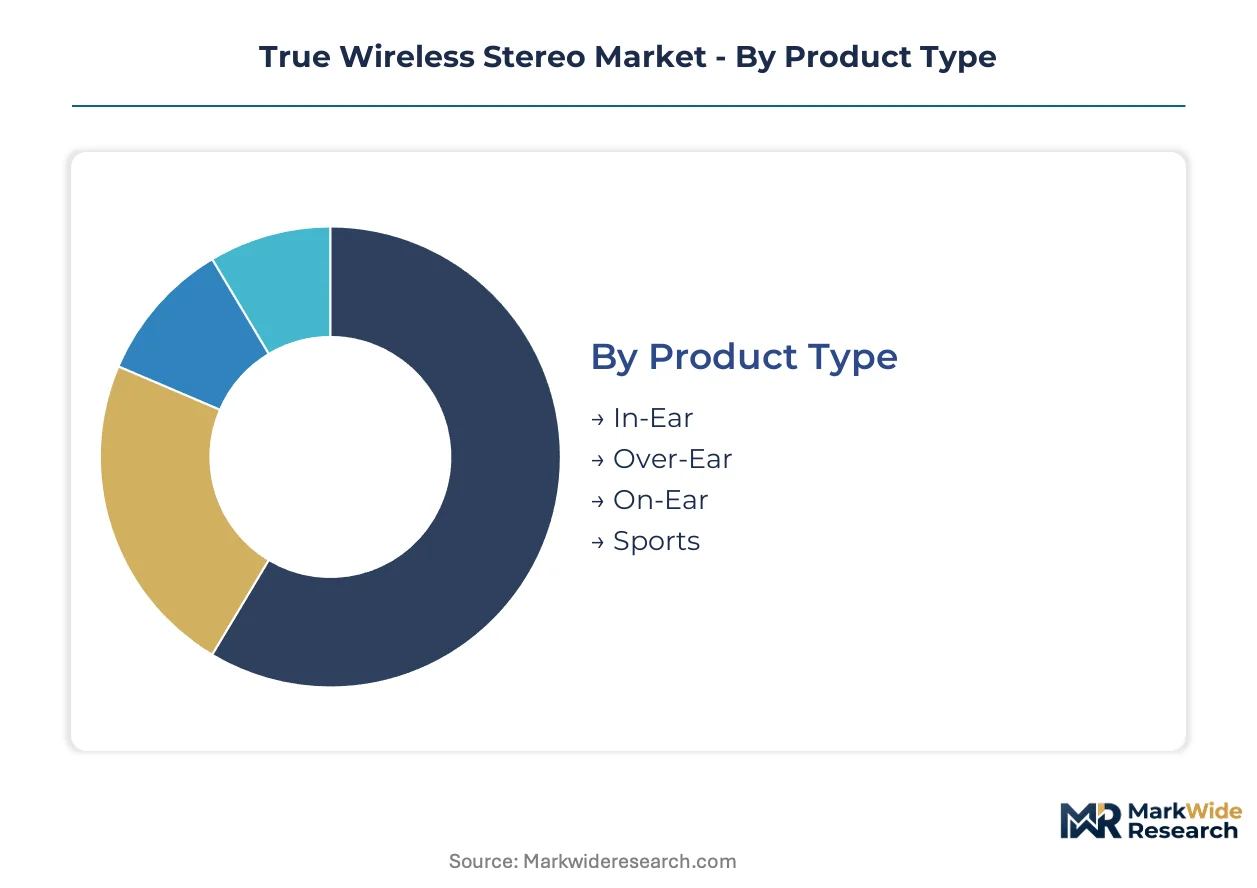
Segmentation in the True Wireless Stereo market reveals how certification burdens, codec licensing, and form-factor miniaturization create divergent margin structures across product tiers. Each dimension carries distinct regulatory and supply chain implications that reshape competitive positioning.
Product Type:
FCC equipment authorization and IPX waterproofing certifications cluster differently across wearable audio form factors, with ingress protection ratings driving testing cost variance.
- In-Ear:Miniaturized driver assemblies and MEMS microphone integration enable mass-market price accessibility. Demand concentrates in China where domestic brands leverage captive acoustic component manufacturing. The segment absorbs the majority of Bluetooth LE Audio chipset volumes as silicon vendors optimize reference designs for canal-fit geometries.
- Sports:Sweat resistance ratings and secure-fit mechanisms require adhesive-free assembly redesigns to satisfy emerging EU battery passport requirements. Athletes and fitness enthusiasts in Germany and the United Kingdom are pulling these designs from premium tiers into mid-market price bands through subscription-bundle distribution models.
- Over-Ear:Larger acoustic chambers accommodate proprietary driver engineering and extended battery packs for audiophile-grade output.
- On-Ear:Compact headband mechanisms target commuter segments prioritizing situational awareness over full isolation.
In-Ear sits at the top of the volume ranking, with Sports climbing the fastest.
Technology:
Codec licensing power and radio equipment authorization timelines fragment differently across connectivity architectures, reshaping semiconductor vendor competitive dynamics.
- Bluetooth:Bluetooth 5.3 and LE Audio protocols compress latency below 20ms while fragmenting codec licensing across semiconductor vendors rather than handset OEMs. The technology spans all price tiers with Auracast broadcast deployment in German airports and UK transit authorities creating assistive listening infrastructure demand.
- Active Noise Cancellation:Neural network-based adaptive architectures automate real-time acoustic environment classification, displacing fixed-filter designs from 2019-2023 product cycles. Flagship-tier penetration exceeds 60% in North American and Chinese urban markets among open-office workers.
- NFC:Tap-to-pair functionality simplifies onboarding for non-technical users in retail chain environments.
- Wi-Fi:Lossless streaming capability targets home theater integration and multi-room audio synchronization.
Bluetooth commands absolute volume leadership, while Active Noise Cancellation gains share fastest through premium tier automation.
End User:
Customer workflows dictate feature prioritization, with biometric sensing and latency tolerance creating divergent product specification requirements.
- Consumers:General-purpose audio consumption across mobile computing and communication workflows drives baseline feature sets and price elasticity. Mass-market penetration in China and India concentrates demand for sub-premium tiers with standard Bluetooth codec support.
- Audiophiles:Lossless streaming requirements and proprietary codec licensing preferences sustain wired residual substitution in professional content creation workflows. LDAC and LC3plus adoption automates quality-tier differentiation previously requiring analog connectivity.
- Athletes:Workout-integrated biometric sensing and secure-fit mechanisms prioritize IPX ratings and ear canal stability over acoustic fidelity.
- Professionals:Video synchronization demands sub-40ms latency thresholds for broadcast and conferencing applications.
Consumers dominate absolute shipment volumes, with Audiophiles expanding most quickly through high-resolution streaming service adoption.
Distribution Channel:
Channel economics compress margin stacking differently across direct-to-consumer and retail intermediation models, with content platform bundling reshaping hardware-software value capture.
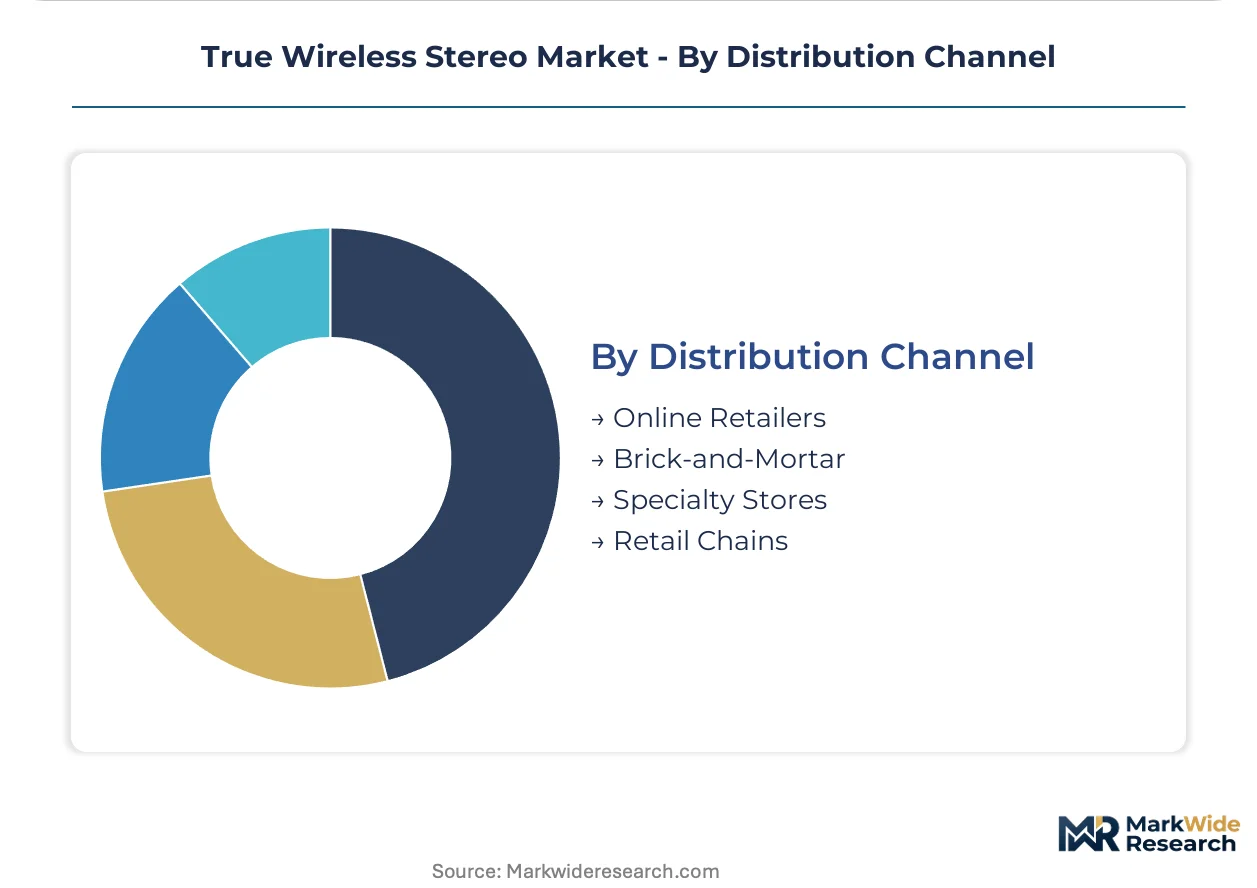
- Online Retailers:Direct-to-consumer subscription bundles unbundle hardware-software value capture, with audio streaming services subsidizing device costs for multi-year membership lock-in. The model displaces traditional retail margin stacking across electronics superstores in South Korea and Japan.
- Specialty Stores:Audiophile-grade product demonstration and codec comparison capabilities sustain premium positioning for lossless streaming hardware. Knowledgeable staff drive conversion for LDAC and proprietary driver engineering differentiation.
- Brick-and-Mortar:Tactile fit testing and immediate availability serve non-technical consumers prioritizing physical evaluation.
- Retail Chains:Volume scale and promotional calendar alignment drive mass-market penetration through price-tier visibility.
Online Retailers lead volume contribution, with Specialty Stores climbing fastest through audiophile segment premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
True Wireless Stereo technology first achieved mass-market scale through smartphone ecosystem integration in the United States and China, with subsequent manufacturing concentration developing across East Asian electronics corridors.
China
Domestic brands command the majority of unit shipments through vertically integrated manufacturing in Guangdong and Jiangsu provinces. MIIT certification requirements for SRRC radio equipment authorization filter import-reliant competitors while privileging in-house RF calibration capabilities. Shenzhen and Dongguan anchor the global contract manufacturing base, with acoustic driver and MEMS microphone suppliers operating captive facilities.
United States
FCC equipment authorization mandates sub-40ms latency thresholds for video synchronization, driving semiconductor vendor reference design optimization. FDA OTC hearing aid regulations collapse boundaries between medical audio devices and consumer TWS form factors. Cupertino and Austin host ecosystem vendors leveraging silicon-to-software integration for premium positioning.
Germany
EU Ecodesign Directive battery longevity mandates and material recyclability disclosures filter subscale assemblers toward consolidated contract manufacturing. Auracast broadcast deployment in Frankfurt and Munich airports creates assistive listening infrastructure demand for LE Audio-native hardware. Berlin anchors specialty retail channels sustaining audiophile-grade product demonstration.
South Korea
Direct-to-consumer subscription bundles displace traditional retail margin stacking across Seoul electronics superstores. MFDS regulatory frameworks govern biometric sensing integration in workout-optimized designs. Suwon and Seoul Capital Area host smartphone ecosystem vendors coupling hardware-software integration across Galaxy Buds portfolios.
India
PLI scheme incentives attract acoustic driver and MEMS microphone suppliers to establish captive capacity outside China. BIS certification requirements for wireless audio devices extend product launch timelines for non-vertically integrated brands. Karnataka and Tamil Nadu industrial corridors concentrate emerging component assembly operations.
True Wireless Stereo Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the True Wireless Stereo value chain, with semiconductor foundries and audio silicon houses controlling codec licensing power while brand marketers outsource assembly. The vendor base concentrates around three tiers: smartphone ecosystem anchors, standalone audio specialists, and contract-manufacturing-dependent challengers. Strategic moves center on silicon-to-software integration depth and Auracast public broadcast deployment partnerships.
Within the smartphone ecosystem tier, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions defined by captive hardware-software coupling and end-to-end latency control. Sony Corporation anchors the standalone audio specialist archetype through proprietary codec licensing and audiophile-grade driver engineering representation.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Sony Corporation |
| Bose Corporation |
| Jabra |
| Sennheiser Electronic GmbH & Co. KG |
| Xiaomi Corporation |
| Anker Innovations Limited |
| Harman International Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Lithium-polymer cell costs cascade through three distinct pricing tiers as Guangdong and Jiangsu suppliers calibrate output to certification-grade demand from FCC, CE, and SRRC jurisdictions. Miniaturized battery packs absorb 18-22% of bill-of-materials exposure, compressing margins for non-vertically integrated assemblers while concentrating pricing power among captive cell manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by codec licensing depth and ANC architecture sophistication. Premium tiers command separation through LDAC and LC3plus codec support plus neural network-based adaptive noise cancellation, while economy tiers compete on Bluetooth baseline connectivity. Cost compression in the mid-tier intensifies because sports-oriented designs migrate IPX-rated features downward. Mass-market consumers in China and India exhibit highest price sensitivity; audiophile segments in Germany and Japan show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from smartphone ecosystem vendors mandate multi-supplier qualification for MEMS microphones and acoustic drivers across China, South Korea, and Vietnam. Raw material dependencies center on rare-earth magnets for driver assemblies, lithium-cobalt oxide cathodes for cells, and epoxy molding compounds for chipset packaging. Single-source vulnerability concentrates in Bluetooth audio silicon where Qualcomm and MediaTek reference designs dominate. Distribution runs through direct-to-consumer subscription bundles and electronics superstore chains in Seoul and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The True Wireless Stereo market functions as a regulatory compounder where EU Ecodesign Directive battery passport mandates are accelerating modular design investments and filtering subscale manufacturers.
For Market Incumbents: Extend Auracast deployment partnerships with German and UK transit authorities to lock in LE Audio-native hardware standards before assistive listening infrastructure matures. Deepen backward integration into MEMS microphone and acoustic driver production to absorb SRRC certification cost advantages that currently favor domestic Chinese competitors. Defend against emerging contract-manufacturing-dependent challengers by controlling end-to-end latency through silicon-to-software integration. For New Entrants and Emerging Players: Capture India's PLI scheme incentives for component assembly outside China before Karnataka and Tamil Nadu industrial corridors reach capacity saturation. Target sports-oriented designs for fitness enthusiasts where secure-fit mechanisms and biometric sensing remain underdeveloped in mid-market price bands. Pursue white-label partnerships with audio streaming services seeking hardware subsidy vehicles for multi-year membership lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where EU right-to-repair mandates force adhesive-free assembly redesigns that conflict with IPX7 waterproofing certifications. Long-term viability favors semiconductor houses with in-house audio codec IP and captive RF calibration laboratories. Acquisition target archetype: vertically integrated acoustic component suppliers with MIIT-certified testing facilities. Watch Auracast public broadcast deployment velocity in Frankfurt and Munich airports as inflection indicator for LE Audio hardware refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-to-Software Integration | Apple and Samsung control end-to-end latency through captive chipset and firmware development. |
| Auracast Infrastructure Partnership | German and UK transit authorities pilot assistive listening networks requiring LE Audio-native hardware. |
| PLI Scheme Manufacturing Expansion | India attracts acoustic driver and MEMS microphone suppliers establishing captive capacity outside China. |
| EU Ecodesign Compliance Investment | Battery passport mandates force modular assembly redesigns that filter subscale assemblers. |
| OTC Hearing Aid Convergence | FDA regulations collapse boundaries between medical audio devices and consumer TWS form factors. |
Research Methodology
Coverage spans China, the United States, Germany, South Korea, and India, with primary inputs from each market combining interviews with RF engineering directors, acoustic component procurement leads, semiconductor reference design teams, and streaming platform hardware partnership managers. Secondary validation draws from FCC equipment authorization databases, MIIT SRRC certification filings, EU Ecodesign Directive implementation guidance, and India PLI scheme beneficiary disclosures. Bottom-up shipment estimates triangulate against top-down value projections across the analysis window.
Rate-of-change decomposition separates volume growth from average selling price evolution across product type, technology architecture, end user workflow, and distribution channel dimensions. CAGRs derive from logistic adoption curves fitted to Bluetooth LE Audio chipset penetration and ANC feature migration patterns. Industry-specific forecast inputs include Auracast infrastructure deployment schedules and FDA OTC hearing aid regulatory timelines.
Raw material cost volatility, certification timeline extensions, and codec licensing fragmentation are the dominant revision risks to modeled outcomes. Deviation in lithium-polymer cell supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
PC Accessories Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Ereader Market
Consumer Electronics
Adult Sex Dolls Market