
 Home Entertainment Devices Market | 2026-2036
Home Entertainment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Home Entertainment Devices Market Intelligence
The shift from passive video streaming towards interactive gaming and virtual reality entertainment is broadening the functional requirements for home devices. Sony Corporation leverages its deep integration with its PlayStation gaming consoles to capture this expanding user base. Samsung Electronics differentiates through its sustained R&D in advanced display technologies, particularly for its Smart TV lineup. Meanwhile, Bose Corporation sustains its premium position in the high-fidelity soundbar and home theater audio system segment.
Home entertainment devices encompass a range of electronic products designed for consuming audio and visual media within a residential setting. These systems integrate components like processors for content streaming, high-resolution displays often featuring OLED or 4K Ultra HD technology, and multi-channel audio outputs. Smart TVs constitute the central hub of the ecosystem, while soundbars represent the fastest-growing audio peripheral category, enhancing the built-in sound capabilities. Demand for OLED and 4K Ultra HD technologies is expanding rapidly, commanding premium pricing and defining the high-end market tier.
Product development must adhere to stringent electronic waste regulations like the EU's WEEE Directive and material restrictions under RoHS. Standards such as CE marking in Europe and FCC certification in the United States govern electromagnetic compatibility and market access. These frameworks directly impact component sourcing and design choices for manufacturers. The key decision for firms is how to balance feature integration against rising compliance costs and evolving energy consumption mandates.
Market Dynamics
The central tension shaping the market is the balance between integrating high-performance features for gaming and VR against the rising costs and design constraints imposed by global energy efficiency and e-waste regulations like the EU's Ecodesign Directive.
Growth Catalysts
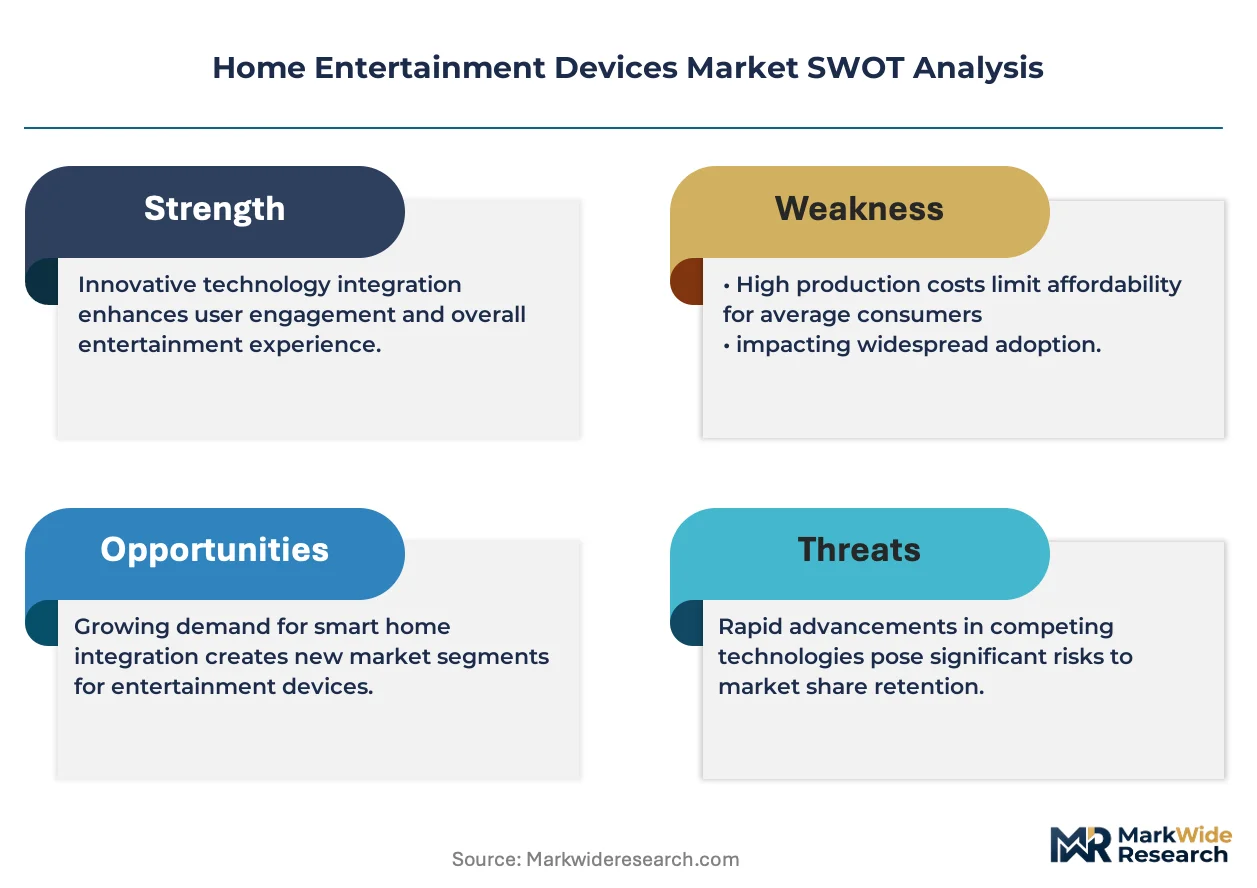
- Advanced Display Technology:Demand for superior visual experiences in home cinema and gaming applications propels the adoption of OLED and 4K Ultra HD displays, which command premium price points and define high-end product tiers.
- Broadband Infrastructure Expansion:Improved internet connectivity and speed, particularly in high-growth markets like India and China, enable seamless streaming of high-bitrate content, directly supporting sales of 4K-capable devices.
- Interactive Entertainment:The shift from passive media consumption to interactive applications, including console gaming and virtual reality, necessitates more powerful processors and display technologies, driving hardware upgrade cycles.
Market Restraints
- Component Cost Volatility:The pricing of critical components, such as high-resolution display panels and advanced system-on-chip (SoC) processors, is subject to supply chain fluctuations, impacting manufacturer margins and final product costs.
- Regulatory Compliance Burden:Adherence to stringent electronic waste frameworks, notably the EU's WEEE Directive, requires significant investment in product lifecycle management, recycling programs, and compliant material sourcing.
- Thermal Management Constraints:Increasing processing power within compact device form factors creates significant thermal engineering challenges, adding complexity and cost to product design to ensure reliability and performance.
Strategic Opportunities
- Smart Home Ecosystem Integration:Developing devices that serve as central hubs for interconnected smart home products offers a pathway to expand functionality beyond entertainment and increase ecosystem lock-in.
- Next-Generation Audio Formats:There is a significant opportunity in developing audio systems, beyond soundbars, that natively support object-based audio for a more immersive, three-dimensional sound experience in residential settings.
- Emerging Market Penetration:Targeting the expanding middle class in underpenetrated regions, such as Southeast Asia and Latin America, with appropriately featured and priced premium audio and video products presents a major growth vector.
Industry Challenges
- Global Certification Complexity:Navigating the varied and time-consuming certification processes for market access, including CE marking in Europe and FCC approval in the United States, poses a significant operational hurdle.
- Semiconductor Supply Chain Risk:The industry's heavy reliance on a concentrated number of semiconductor foundries for essential processors and controllers creates vulnerability to geopolitical disruptions and capacity shortages.
- Codec Licensing Costs:The necessity of licensing multiple patented audio and video codecs for broad content compatibility adds a substantial and often complex layer of cost to every device manufactured.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Entertainment Devices Market |
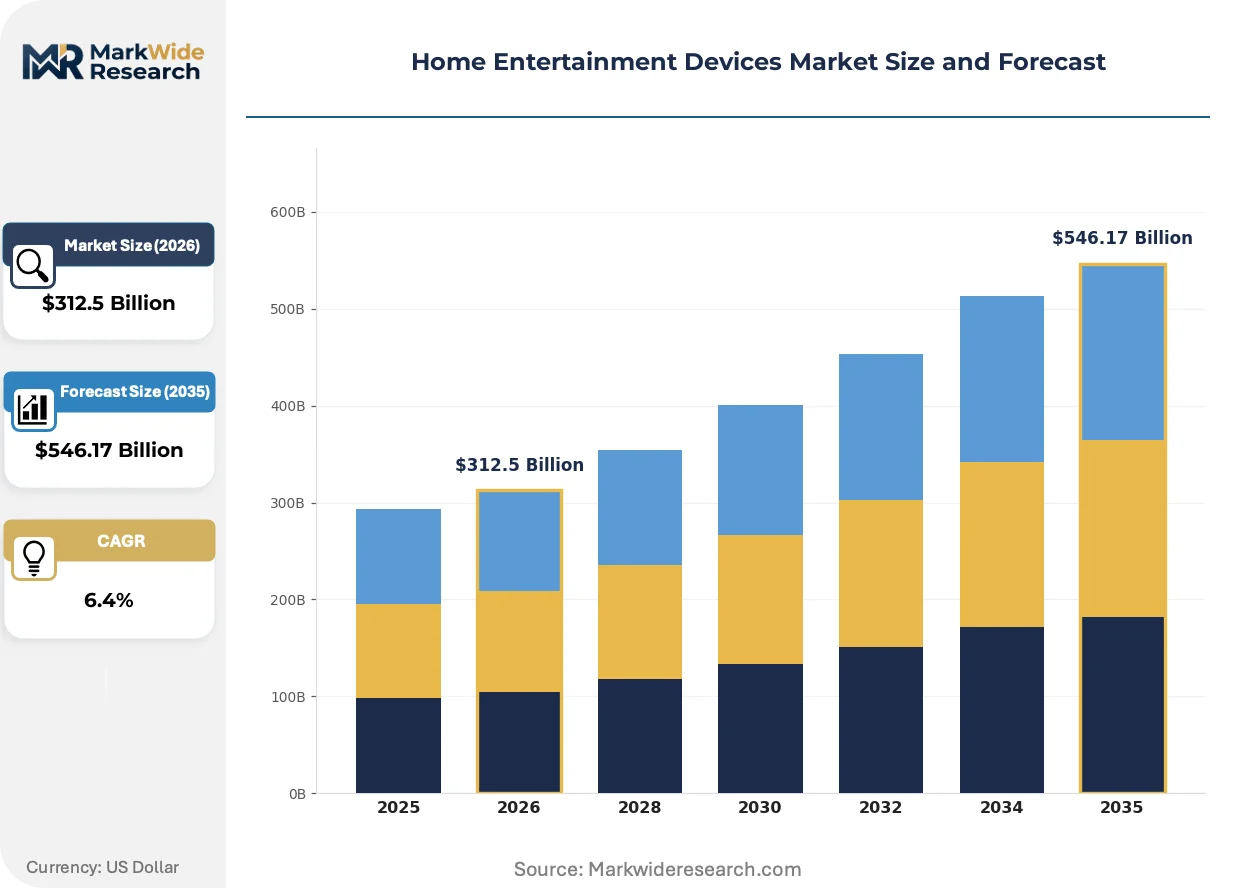
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $546.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TVs, Streaming Devices, Soundbars, Blu-ray Players, Home Theater Systems Technology: LCD, OLED, 4K Ultra HD, HDR, 3D Application: Video Streaming, Gaming, Music Playback, Virtual Reality Entertainment, Educational Content End User: Residential Users, Small Business Owners, Content Creators, Broadcast Centers |
| Companies Covered | Bose Corporation, Harman International, Sony Corporation, Onkyo Corporation, Pioneer Corporation, Samsung Electronics, Yamaha Corporation, Denon, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Entertainment Devices Market Strategic Shifts & Innovations
A convergence of interactive content demands, sophisticated on-device processing, and stringent environmental regulations is reshaping product development. This forces manufacturers to innovate simultaneously in performance, energy efficiency, and material circularity to maintain a competitive edge.
Artificial intelligence (AI) processing is a key technology for enhancing audio-visual quality. This capability is being widely adopted in the premium Smart TV and soundbar segments for features like real-time 4K upscaling and adaptive sound equalization. AI is integrating advanced computational functions directly into the device hardware, personalizing the user experience while reducing latency and dependence on cloud-based services.
European Union "Right to Repair" initiatives are influencing device design beyond the continent's borders. These regulations compel manufacturers to create products that are more durable, easier to disassemble, and have accessible spare parts. The high-end, integrated Smart TV segment is most affected, pushing firms toward more modular designs that can be repaired or upgraded instead of fully replaced.
Consumer preference is shifting from a focus on one-time hardware ownership to valuing continuous access to content and services. This change disrupts traditional retail models, as manufacturers and content providers increasingly offer hardware bundled with long-term service subscriptions. This trend is most advanced within the gaming console market and is gaining traction in premium streaming device categories across North America and Europe.
Home Entertainment Devices Market Segmentation
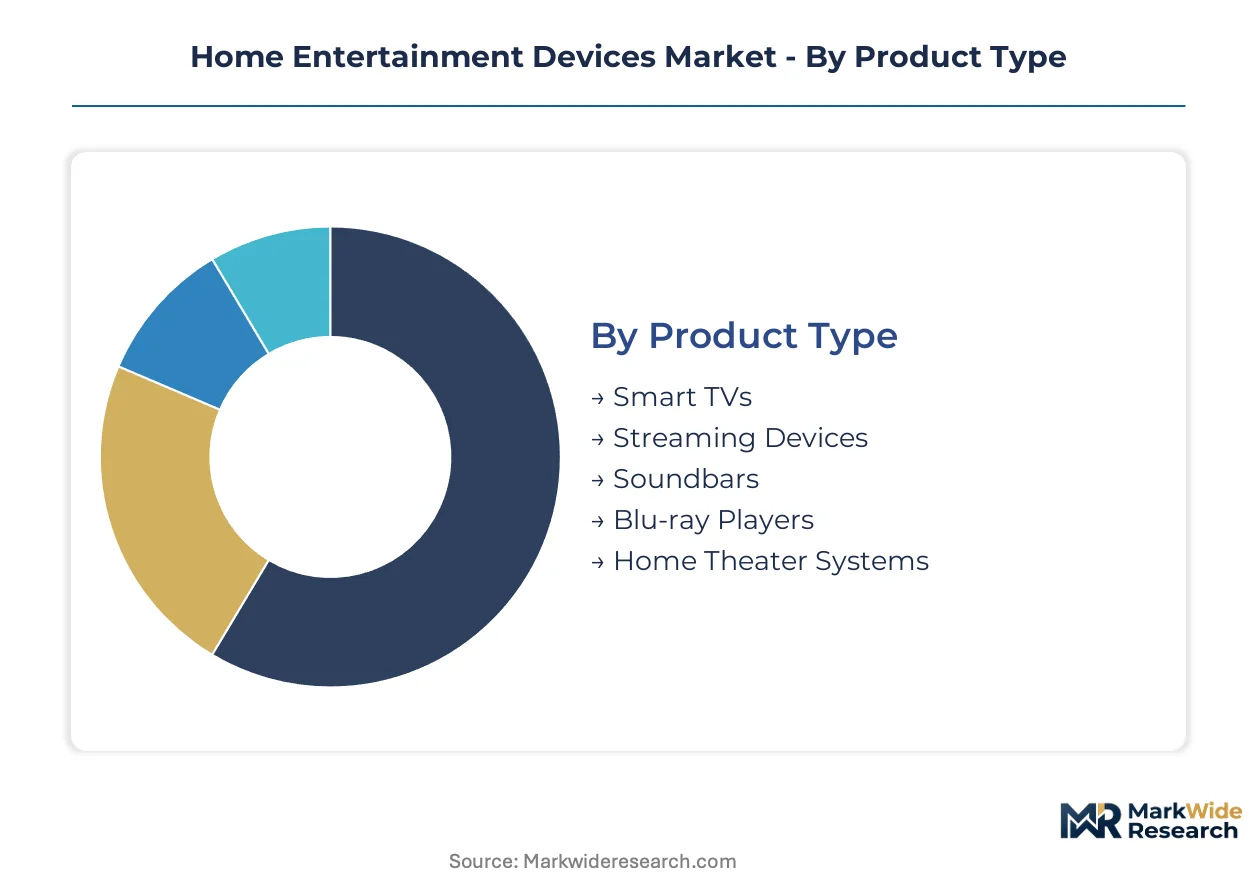
Understanding the Home Entertainment Devices Market through detailed segmentation reveals distinct patterns in product evolution and consumer preferences. This analysis dissects the market by product type, underlying technology, primary application, and specific end-user groups. These insights are crucial for manufacturers to align product development with demand.
Product Type:
Product differentiation within home entertainment devices often hinges on their integration depth, ranging from standalone units to components embedded within broader systems.
- Smart TVs:These devices integrate high-resolution displays with embedded operating systems, facilitating direct content streaming and smart home control. Demand concentrates in key Asian markets, such as China, driven by the expanding middle-class purchasing power and improved broadband infrastructure.
- Soundbars:These audio peripherals enhance built-in television sound, often featuring multi-channel audio outputs and wireless connectivity. Demand expands rapidly across Europe, where consumers seek immersive audio experiences without extensive home theater installations.
- Streaming Devices:Compact hardware units connect to displays, providing access to various online content platforms.
- Blu-ray Players:Optical disc players offer high-definition video and audio playback, catering to physical media enthusiasts.
- Home Theater Systems:Comprehensive audio-visual setups include multiple speakers and a receiver for cinematic experiences.
Smart TVs lead volumes today; Soundbars are gaining share fastest.
Technology:
Technology segmentation highlights distinct performance levels and associated cost tiers, influencing product capabilities and consumer investment.
- OLED:Organic Light-Emitting Diode technology delivers superior contrast and perfect blacks through individually lit pixels, enhancing visual immersion. Premium demand is concentrated in Western European markets, where consumers prioritize high-fidelity visual experiences for home cinema.
- 4K Ultra HD:This display standard offers a resolution of 3840x2160 pixels, providing exceptional detail and clarity for large-screen viewing. Adoption accelerates in North America, driven by the widespread availability of high-bitrate streaming content.
- LCD:Liquid Crystal Display technology uses a backlight and polarizing filters to produce images, offering cost-effective display solutions.
- HDR:High Dynamic Range enhances contrast and color accuracy, providing a more lifelike visual experience.
- 3D:Three-dimensional display technology creates an illusion of depth, though its market presence has significantly diminished.
4K Ultra HD technology holds the largest installed base; OLED is expanding most quickly.
Application:
Functional utility drives application-based segmentation, reflecting diverse consumer needs from passive consumption to interactive engagement.
- Gaming:This application involves the use of home devices for interactive video games, necessitating high refresh rates, low latency, and powerful graphics processing. Demand is particularly robust in South Korea, driven by a strong esports culture and advanced broadband infrastructure.
- Virtual Reality Entertainment:This segment provides immersive digital experiences, requiring specialized headsets and high-performance computing for rendering virtual environments. Investment concentrates in the United States, propelled by technological innovation and expanding content libraries.
- Video Streaming:Consumption of on-demand or live video content through internet-connected devices.
- Music Playback:Audio consumption through various devices, ranging from soundbars to multi-room audio systems.
- Educational Content:Devices facilitate learning through interactive applications and video lessons.
Video Streaming remains the dominant application; Virtual Reality Entertainment is climbing the fastest.
End User:
Segmentation by end-user differentiates demand based on customer type, from individual households to professional entities with distinct requirements.
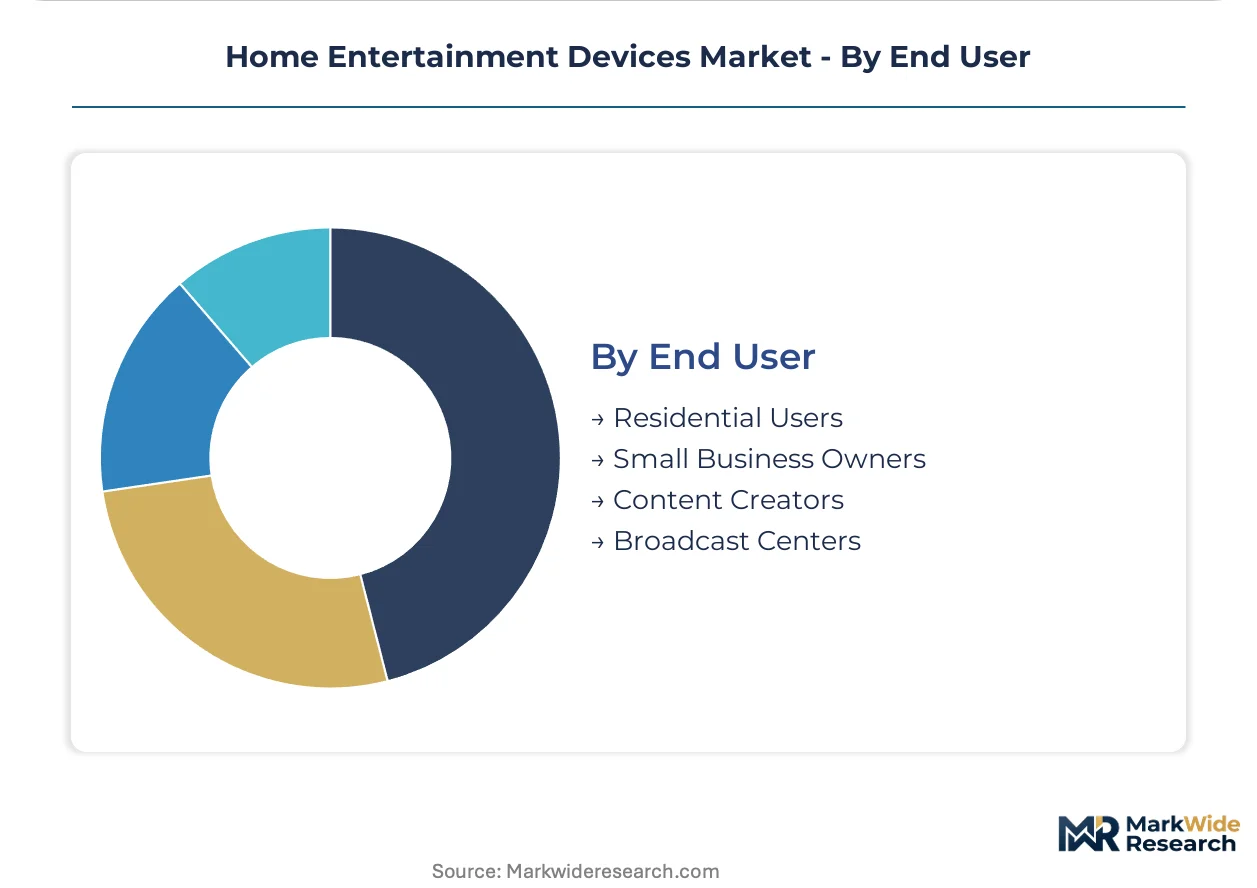
- Residential Users:This segment encompasses individual households that consume entertainment and media for personal enjoyment and leisure activities. It represents the largest volume component of the market, driven by rising disposable incomes across global urban centers.
- Content Creators:These professionals and enthusiasts produce audio-visual content, requiring high-fidelity monitors, specialized audio interfaces, and robust editing workstations. Demand for such advanced equipment is significant in creative hubs like London, supporting digital media production.
- Small Business Owners:Utilize devices for background music, digital signage, or presentation purposes in commercial settings.
- Broadcast Centers:Professional facilities employ high-end home entertainment technologies for monitoring and quality control.
Residential Users command the largest share; Content Creators exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory pressures in some regions compel manufacturers to strategically relocate production. This shift seeks to optimize compliance costs while maintaining market access. Home entertainment device producers are particularly sensitive to these evolving global frameworks.
China
Expanding middle-class purchasing power and improved broadband infrastructure drive demand for Smart TVs and 4K Ultra HD devices. The national GB standards govern product quality and safety for market entry. Manufacturing hubs in the Yangtze River Delta concentrate production, developing integrated supply chains for display components.
United States
Investment in virtual reality entertainment and rapid 4K Ultra HD adoption fuels demand for high-performance processors and displays. FCC certification ensures electromagnetic compatibility for all electronic devices sold domestically. Silicon Valley companies drive innovation, pushing boundaries in interactive content and device integration.
Germany
Premium demand for OLED displays and high-fidelity audio systems defines the German market for home entertainment. The EU's Ecodesign Directive mandates energy efficiency, influencing product design and component selection. Berlin's tech scene fosters innovation in smart home integration, connecting devices into broader ecosystems.
India
Broadband infrastructure expansion and rising disposable incomes accelerate the uptake of streaming devices and 4K-capable televisions. The BIS standards ensure product conformity and consumer safety for imported and domestically manufactured goods. Bengaluru's IT sector supports digital content delivery, enabling seamless streaming experiences.
South Korea
A robust esports culture and advanced display technologies like OLED drive gaming and interactive entertainment device sales. The national KC certification mark ensures product safety and electromagnetic compatibility. Seoul's technology parks house leading display manufacturers, pioneering next-generation visual experiences.
Home Entertainment Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied integration levels in the home entertainment devices market. The market exhibits a tiered structure, with premium players focusing on innovation and value-segment manufacturers prioritizing cost efficiency and broad market access. Archetypes include integrated electronics giants offering comprehensive solutions, specialized audio-visual providers, and niche component manufacturers. Strategic partnerships for technology co-development and portfolio diversification across product categories represent dominant competitive moves among these diverse entities.
On the premium-tier vector, Sony Corporation exemplifies deep integration with content ecosystems, leveraging its PlayStation gaming platforms for hardware sales and user lock-in. Samsung Electronics, a South Korean electronics giant, represents sustained investment in advanced display technologies, particularly for its Smart TV lineup and OLED innovation. Meanwhile, Bose Corporation, a US-based audio specialist, occupies a premium position in the high-fidelity soundbar and home theater audio system segment. These entities anchor distinct competitive approaches, ranging from broad consumer electronics portfolios to specialized audio excellence, within the broader market landscape.
| Leading Market Players |
|---|
| Bose Corporation |
| Harman International |
| Sony Corporation |
| Onkyo Corporation |
| Pioneer Corporation |
| Samsung Electronics |
| Yamaha Corporation |
| Denon |
| LG Electronics |
Cost & Logistics Intelligence
Skilled engineering talent in regions like Silicon Valley and Seoul drives innovation, influencing the premium pricing tiers for advanced home entertainment devices. Lower labor costs in manufacturing hubs, conversely, enable competitive pricing across mass-market product segments.
Pricing Analysis
Retailer markup on consumer electronics significantly shapes final product costs for residential users. This market primarily utilizes a pricing structure that stratifies across premium, standard, and economy tiers. Price differentiation stems from advanced display technologies like OLED and brand premium, alongside comprehensive after-sales service. Pricing softness reflects component cost volatility for critical parts such as display panels and advanced SoCs. Residential users in the mass market exhibit high price sensitivity, while content creators prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate single-point failure risks for manufacturers. The supply chain for home entertainment devices draws heavily from manufacturing hubs in China, South Korea, and Taiwan. Key dependencies include advanced semiconductor system-on-chips and high-resolution display panels. Geopolitical disruptions and capacity shortages in the semiconductor industry present a structural risk. Distribution runs through established retail channels, both online and brick-and-mortar, with a growing direct-to-consumer model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Home Entertainment Devices Market functions as a stable compounder, with expanding middle-class purchasing power globally driving consistent demand for enhanced audio-visual experiences.
For Market Incumbents: Extend deep integration with content ecosystems, leveraging proprietary platforms to capture user loyalty and drive hardware sales. Investment in modular product designs directly addresses evolving EU Right to Repair regulations, reducing lifecycle costs. This approach mitigates the threat of increasing regulatory compliance burden and supports long-term brand value.
For New Entrants and Emerging Players: Enter via niche segments focusing on next-generation audio formats like object-based sound for immersive experiences. Target underpenetrated emerging markets in Southeast Asia and Latin America with appropriately featured and priced premium audio-video products. A viable go-to-market angle involves bundling hardware with long-term service subscriptions to attract new residential users.
For Investors and Strategic Acquirers: Integrated electronics giants are the most active acquirers in this space, seeking to expand their technology portfolios and market reach. Long-term viability for the sector hinges on sustained consumer demand for immersive entertainment experiences over a five-to-ten-year window. Acquisition targets should include specialized AI processing startups or advanced display component manufacturers. The adoption rate of next-generation virtual reality platforms serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Content Ecosystem Integration | Sony strengthens user lock-in through PlayStation gaming platforms and exclusive media offerings. |
| Invest in Modular Product Design | Samsung addresses EU Ecodesign Directive, enhancing repairability and reducing electronic waste. |
| Develop Object-Based Audio Systems | Bose captures premium audio market share by delivering immersive, three-dimensional sound experiences. |
| Expand into Emerging Markets | LG Electronics taps into rising disposable incomes in India and China for 4K-capable televisions. |
| Bundle Hardware with Service Subscriptions | Companies like Sony capture recurring revenue streams from gaming and streaming content access. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming the core of the data collection approach. Primary interviews involved product development executives, supply chain managers, retail channel partners, and consumer electronics analysts. Secondary validation drew from industry association reports, patent databases, financial filings of public companies, and technology news archives. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation.
The forecast framework anchored the projection horizon to historical reference periods, ensuring continuity in trend analysis. Segmentation dimensions modeled included product type, technology, application, end-user, and regional market dynamics. Compound annual growth rates were derived through regression analysis and market share projections across the modeling period. Key industry-specific forecast inputs included broadband penetration rates and display panel manufacturing capacity.
Inputs from industry reports and company disclosures were available through the study window; gaps in emerging market consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Deviation in semiconductor supply stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Mobile Accessories Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Global Office and Contact Center Headset Market