
 Middle East and Africa Refurbished and Used Mobile Phones Market | 2026-2036
Middle East and Africa Refurbished and Used Mobile Phones Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Refurbished and Used Mobile Phones Market Insights
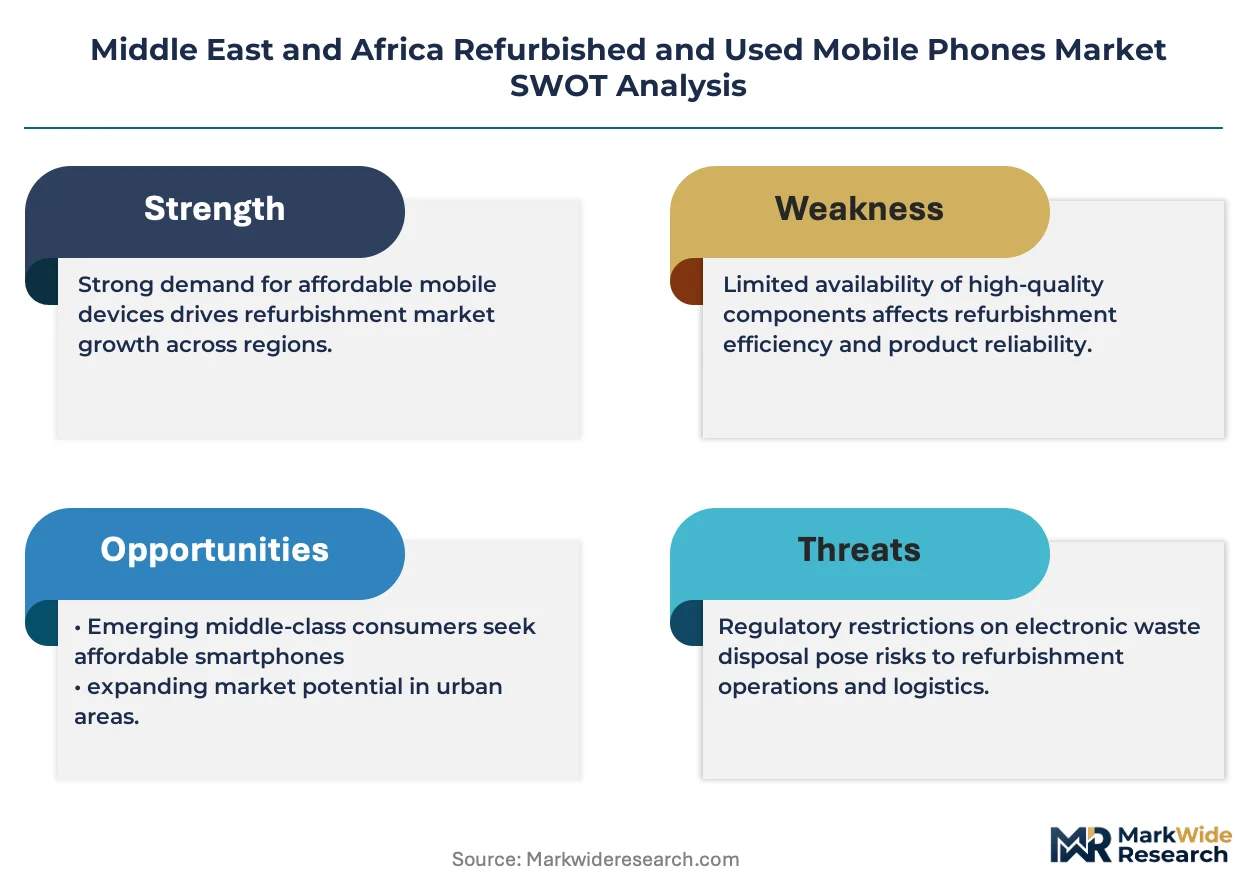
Grade-A refurbishment certification is collapsing the stigma historically attached to pre-owned mobile devices across Middle East and Africa consumer markets. Samsung Electronics Co. Ltd leverages its extensive authorized service network to dominate certified refurbishment programs in South Africa and Nigeria. Apple Inc. sustains premium resale values through stringent battery health thresholds and proprietary diagnostics tools. Back Market competes by aggregating verified seller inventory across multiple African markets under unified quality guarantees.
Refurbished and used mobile phones constitute previously owned wireless communication devices restored to functional working condition through component replacement, software reset, and cosmetic repair processes, typically graded by screen integrity, battery cycle count, and housing wear metrics for secondary commercial sale. The smartphone segment anchors volume across the region as Android devices from Chinese OEMs circulate through informal trading corridors from Dubai to Lagos. Certified pre-owned inventory commands margin premiums through warranty backing and traceable sourcing, while repair shops function as critical last-mile distribution nodes in markets with limited formal retail penetration.
South Africa's National Regulator for Compulsory Specifications enforces electromagnetic compatibility standards on imported used devices, while Dubai's Department of Economy and Tourism regulates re-export certification for phones transiting through Jebel Ali Free Zone. The EU WEEE directive indirectly shapes supply flows as Middle Eastern traders absorb devices retired from European carrier upgrade cycles. Stakeholders must monitor evolving e-waste handling mandates across Gulf Cooperation Council states and East African Community customs protocols to anticipate supply disruptions and compliance cost shifts.
Market Dynamics
Grade-A refurbishment certification is collapsing the stigma historically attached to pre-owned mobile devices across Middle East and Africa consumer markets, reshaping how quality assurance and warranty backing determine purchase decisions.
Growth Catalysts
- Young professionals and students in urban centers:This demographic cluster drives adoption of affordable smartphones in Lagos, Johannesburg, and Nairobi, creating sustained demand for certified pre-owned inventory.
- Nigeria's Standards Organisation quality certification:Mandatory quality certification requirements for imported used devices are professionalizing informal trading corridors and building consumer trust in secondary markets.
- Dubai's Jebel Ali Free Zone re-export certification:Regulatory clarity on device transit documentation is streamlining supply flows from European retirement cycles into African consumption hubs.
Market Restraints
- Electromagnetic compatibility compliance costs:South Africa's National Regulator for Compulsory Specifications enforces testing standards that raise landed costs for small-volume importers.
- Battery degradation uncertainty:Technical limitations in verifying lithium-ion cycle counts without proprietary diagnostics create information asymmetry between sellers and buyers.
- Supply concentration in informal trading corridors:Heavy reliance on Dubai-to-Lagos shipping routes creates vulnerability to customs protocol shifts and shipping disruptions.
Strategic Opportunities
- Kenya's underpenetrated secondary cities:Mombasa, Kisumu, and Nakuru present distribution expansion potential beyond Nairobi's saturated retail environment.
- EU WEEE directive supply absorption:Environmental retirement mandates in Europe are accelerating device availability for Middle Eastern traders to capture and redirect southward.
- Repair shop network formalization:Converting informal handset repair operations into authorized service nodes creates last-mile warranty fulfillment infrastructure.
Industry Challenges
- Component authentication skill gaps:Technicians lack standardized training to detect counterfeit screens, batteries, and logic boards in high-volume refurbishment operations.
- Multi-jurisdiction certification timelines:Navigating overlapping requirements from Gulf Cooperation Council states and East African Community customs protocols delays inventory velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Refurbished and Used Mobile Phones Market |
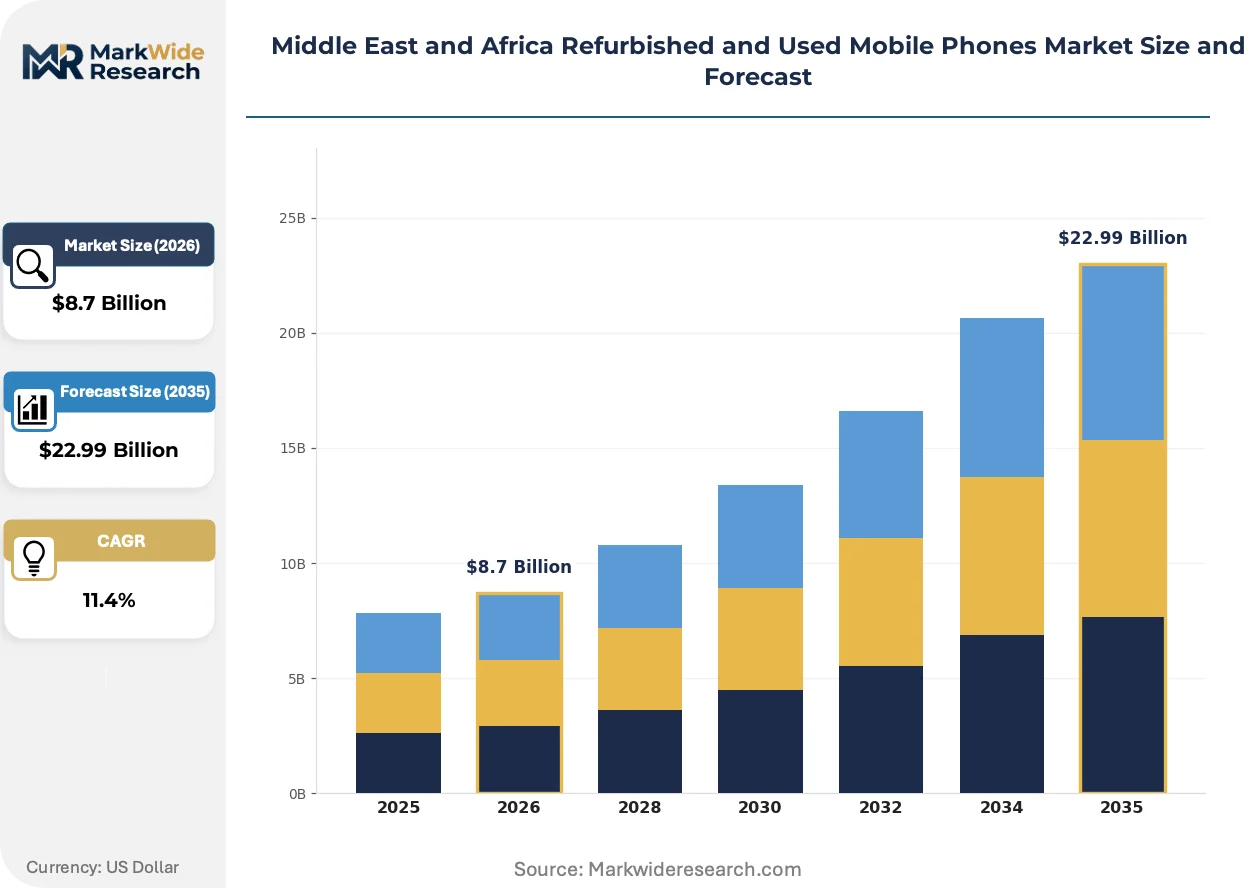
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartphones, Feature Phones, Tablets, Phablets Operating System: Android, iOS, Windows, HarmonyOS Distribution Channel: Online Retail, Offline Retail, Direct Sales, Repair Shops Condition: Refurbished, Used, Open-Box, Certified Pre-Owned |
| Companies Covered | Samsung Electronics Co. Ltd, Apple Inc., Amazon.com Inc., Verizon Communications Inc., AT&T Inc., Reboxed Limited, Nippon Telephone Inc., Back Market, Gazelle, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Refurbished and Used Mobile Phones Market Trends and Innovations
Diagnostic automation and blockchain traceability are actively reshaping how refurbished devices are authenticated, priced, and distributed across Middle East and Africa markets.
Blockchain-based provenance tracking is decomposing the opacity that historically plagued secondary device supply chains. Dubai-based traders are adopting distributed ledger systems to document device origin, repair history, and component replacement records. This technology is decomposing price premiums previously commanded by opaque intermediaries who controlled information asymmetry.
South Africa's National Regulator for Compulsory Specifications electromagnetic compatibility standards are tightening import documentation requirements for used devices. Industrial consequence includes forced professionalization of previously informal importers who must now maintain testing laboratory relationships. The certified pre-owned segment is responding by consolidating around authorized refurbishment programs with in-house compliance capabilities.
Buyer preference is rotating toward warranty-backed purchases over unverified informal transactions. Urban consumers in Lagos and Nairobi are abandoning open-air electronics markets for e-commerce platforms offering unified quality guarantees. This shift is most visible among salary-earning professionals aged 25-35 who prioritize device reliability over lowest upfront cost.
Middle East and Africa Refurbished and Used Mobile Phones Market Segmentation
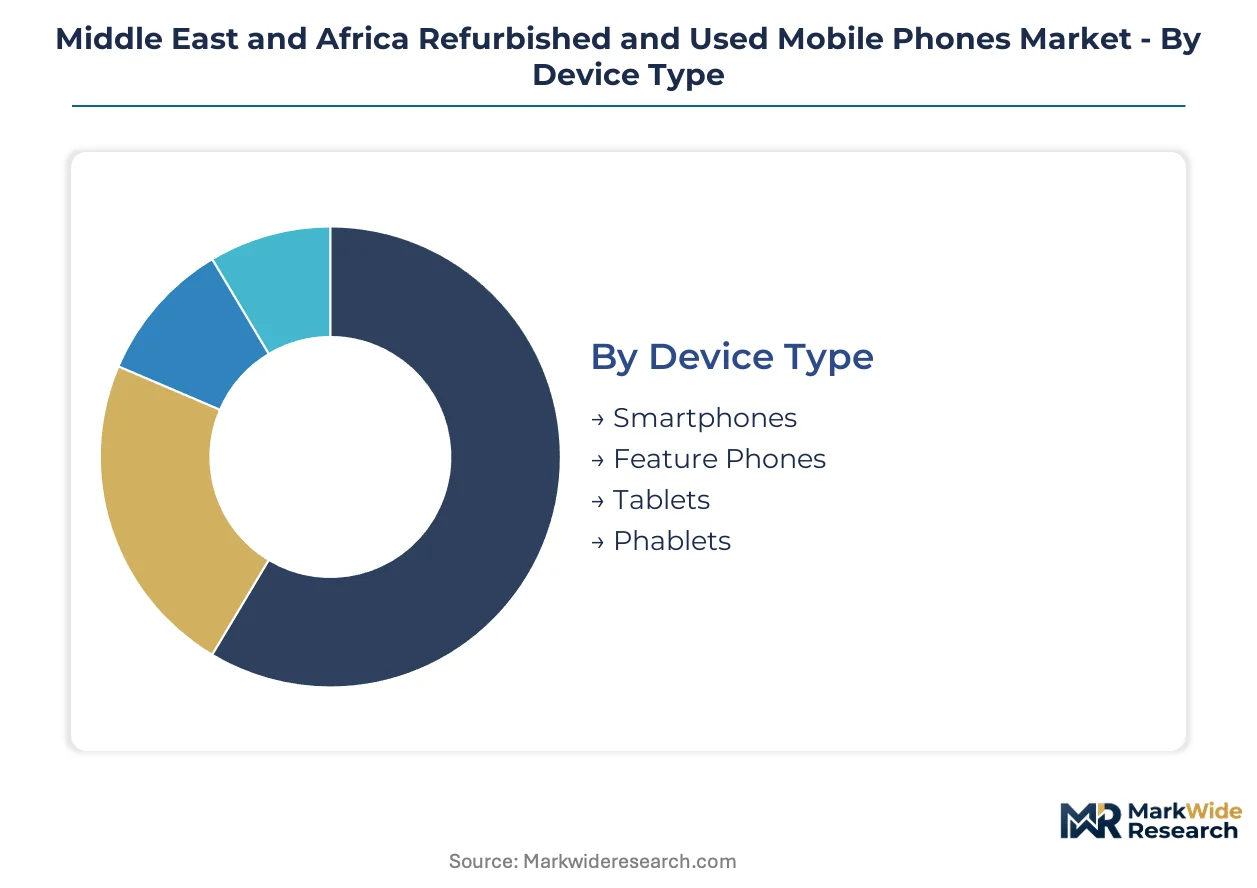
Device condition grading and operating system fragmentation create distinct margin tiers across Middle East and Africa distribution channels. Channel selection directly shapes which customer segments each condition tier reaches.
Device Type:
Channel economics vary sharply across form factors, with smartphones and tablets flowing through divergent fulfillment paths.
- Smartphones:Android handsets from Chinese OEMs dominate volume through Dubai-to-Lagos trading corridors. Lagos, Johannesburg, and Nairobi absorb the majority of certified pre-owned inventory as young professionals prioritize affordable 4G and 5G connectivity.
- Feature Phones:Basic voice-and-text devices sustain rural distribution through informal repair shop networks. Kenya's secondary cities and Nigeria's northern states maintain residual demand for extended battery life and durability.
- Tablets:Education sector procurement in South Africa and UAE drives institutional volume. Corporate fleet retirements from European enterprises supply refurbished inventory through Jebel Ali Free Zone re-export channels.
- Phablets:Oversized screen formats appeal to mobile commerce users and content consumers. Nigerian and Kenyan urban markets show concentrated uptake among trader demographics requiring portable productivity tools.
Smartphones dominate installed base. Tablets represent the fastest-climbing trajectory as education digitization accelerates.
Operating System:
OS licensing constraints and hardware lifecycle mismatches reshape cost structures for importers and refurbishers.
- Android:Open-source architecture enables deep customization for regional carriers. Chinese OEM devices circulate through informal trading corridors with minimal software friction, though fragmentation across OS versions complicates warranty standardization.
- iOS:Apple's proprietary diagnostics and battery health thresholds sustain premium resale values. South Africa's authorized service network captures certified pre-owned volume through stringent quality certification requirements.
- Windows:Legacy enterprise tablets and hybrid devices enter secondary markets through corporate fleet retirements. Limited repair infrastructure in East African markets constrains volume expansion.
- HarmonyOS:Huawei's ecosystem builds presence in Gulf Cooperation Council states where US trade restrictions have reshaped supply flows. Device availability concentrates through Dubai-based traders with direct China sourcing relationships.
Android commands volume leadership. iOS captures margin concentration through certified refurbishment programs.
Distribution Channel:
Channel formalization is accelerating as warranty backing displaces price-only purchasing criteria among salary-earning demographics.
- Online Retail:Aggregator platforms unify quality guarantees across verified seller networks. Urban consumers aged 25-35 in Lagos and Nairobi abandon open-air markets for traceable inventory with return policies.
- Offline Retail:Formal electronics stores in South Africa and Nigeria's urban centers provide tactile inspection and immediate fulfillment. Electromagnetic compatibility compliance documentation requirements favor established retailers with testing laboratory relationships.
- Direct Sales:Bulk institutional procurement bypasses retail markup for education and corporate fleet deployments. B2B relationships with Dubai-based traders enable volume pricing for Kenyan and Nigerian resellers.
- Repair Shops:Informal handset repair operations function as critical last-mile nodes in markets with limited formal retail penetration. Conversion to authorized service nodes creates warranty fulfillment infrastructure in underpenetrated secondary cities.
Repair shops anchor rural and secondary city coverage. Online retail is where urban expansion concentrates.
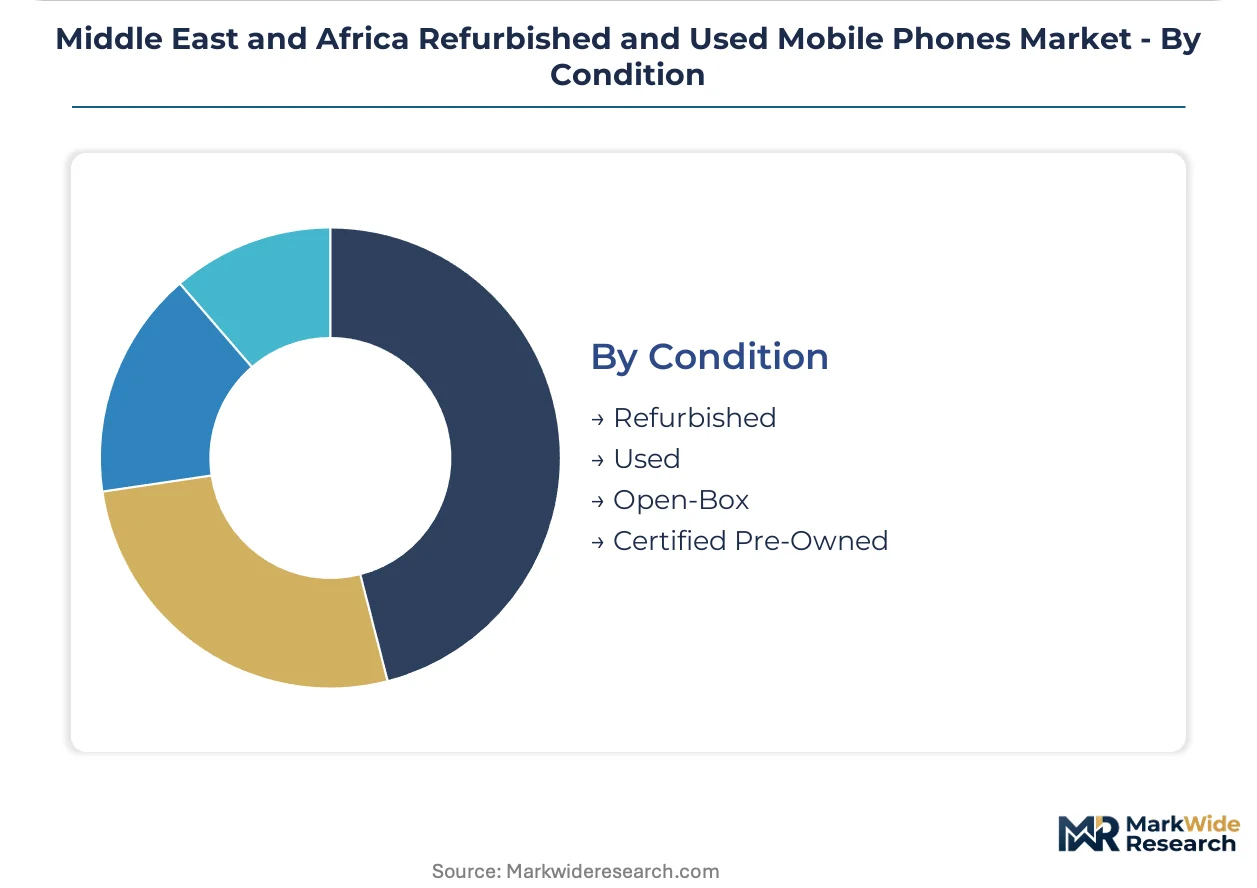
Condition:
Condition grading standardization is collapsing historical stigma through transparent quality certification frameworks.
- Refurbished:Component replacement and cosmetic restoration return devices to functional working condition. Grade-A certification programs in South Africa and Nigeria professionalize previously informal quality assessment.
- Used:As-is devices trade at steepest discounts through open-air markets and informal corridors. Battery degradation uncertainty creates information asymmetry that certified alternatives exploit.
- Open-Box:Unactivated returns and cancelled orders offer near-new condition at moderate discounts. Limited and unpredictable supply constrains dedicated inventory positioning.
- Certified Pre-Owned:Warranty backing and traceable sourcing command margin premiums. Samsung's authorized service network and Apple's diagnostics-backed programs dominate this tier in South Africa and Nigeria.
Used devices dominate transaction volume. Certified pre-owned is where margin expansion and consumer trust building concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device flows concentrate through Dubai's Jebel Ali Free Zone before redistribution southward into African consumption hubs. This logistical chokepoint shapes pricing and availability patterns across both Middle Eastern and sub-Saharan markets.
Nigeria
Lagos anchors West African volume as young professionals and students drive affordable smartphone adoption. The Standards Organisation of Nigeria enforces mandatory quality certification for imported used devices, professionalizing previously informal trading corridors. Kano and Port Harcourt function as secondary distribution nodes feeding northern and Niger Delta markets.
South Africa
Johannesburg and Cape Town concentrate certified pre-owned demand among salary-earning demographics aged 25-35. The National Regulator for Compulsory Specifications enforces electromagnetic compatibility standards that raise compliance costs for small-volume importers. Durban's port infrastructure handles bulk institutional procurement for education sector tablet deployments.
Kenya
Nairobi's saturated retail environment pushes expansion toward Mombasa, Kisumu, and Nakuru as underpenetrated secondary cities. The country's national communications regulator monitors device type approval requirements for network compatibility. Repair shop networks in these secondary markets function as critical last-mile warranty fulfillment nodes.
United Arab Emirates
Dubai's Department of Economy and Tourism regulates re-export certification for phones transiting through Jebel Ali Free Zone. The emirate absorbs devices retired from European carrier upgrade cycles and redirects them southward. Abu Dhabi's institutional procurement programs drive education sector tablet volume through formal direct sales channels.
Saudi Arabia
Riyadh and Jeddah concentrate Gulf Cooperation Council demand for premium-tier certified pre-owned inventory. The Saudi Food and Drug Authority and national standards body oversee product safety compliance for consumer electronics. The Eastern Province's corporate fleet retirement programs supply refurbished tablets through B2B redistribution networks.
Middle East and Africa Refurbished and Used Mobile Phones Market Competitive Landscape
Concentration sits with multinational OEMs and platform aggregators who control certification infrastructure and warranty backing capabilities. Samsung Electronics and Apple anchor the premium tier through authorized service networks, while Back Market exemplifies the aggregator archetype unifying fragmented seller inventory under quality guarantees. Repair shop networks and informal traders occupy the long tail, though regulatory professionalization is forcing consolidation. Dominant competitive moves include strategic partnerships with testing laboratories for compliance documentation and geographic expansion into underpenetrated secondary cities.
Within the OEM tier, Samsung Electronics Co. Ltd and Apple Inc. represent contrasting approaches to certified refurbishment—Samsung leveraging extensive authorized service networks, Apple enforcing proprietary diagnostics thresholds. Back Market occupies a distinct aggregator position, unifying verified seller inventory across multiple African markets. These three players exemplify how quality certification and traceable sourcing command margin premiums in markets historically plagued by information asymmetry.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| Apple Inc. |
| Amazon.com Inc. |
| Verizon Communications Inc. |
| AT&T Inc. |
| Reboxed Limited |
| Nippon Telephone Inc. |
| Back Market |
| Gazelle |
| Others |
Pricing and Supply Chain Analysis
Container utilization rates through Dubai's Jebel Ali Free Zone determine margin compression thresholds for African redistributors, concentrating price-setting power among traders with direct European carrier relationships and in-house electromagnetic compatibility testing capabilities.
Pricing Analysis
Nigeria's Standards Organisation certification mandates dictate the pricing tier structure across West African import corridors. Pricing stratifies across certified pre-owned, Grade-A refurbished, and as-is used tiers, with battery health verification and warranty backing as the primary differentiation drivers. Cost compression in the uncertified tier intensifies as Lagos-based aggregators consolidate inventory sourcing. Informal traders in open-air markets exhibit highest price sensitivity, while salary-earning professionals in Johannesburg and Nairobi prioritize reliability over upfront cost minimization.
Supply Chain Analysis
Container availability fluctuations on the Dubai-Lagos shipping lane reshape landed cost calculations for small-volume importers. Supply concentrates in the United Arab Emirates as the primary transit hub, with secondary consolidation in South Africa and Nigeria as consumption endpoints. The chain draws from retired European carrier inventory, replacement screens and batteries from Chinese component manufacturers, and diagnostic equipment from South Korean suppliers. Single-source vulnerability sits with Dubai's re-export certification bottleneck. Distribution runs through formal e-commerce platforms, authorized service networks, and informal repair shop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based provenance tracking is disrupting information asymmetry that historically protected opaque intermediaries, creating a regulatory-technology inflection that favors capitalized players with compliance infrastructure.
For Market Incumbents: Secure authorized refurbishment certification across Gulf Cooperation Council and East African Community jurisdictions before regulatory timelines tighten. Consolidate testing laboratory partnerships to defend margin position against electromagnetic compliance cost escalations. Lock in direct sourcing relationships with European carrier retirement programs to bypass Dubai trader markups.
For New Entrants and Emerging Players: Differentiate on diagnostic transparency by deploying battery health verification tools that match Apple and Samsung proprietary standards. Target Kenya's secondary cities—Mombasa, Kisumu, and Nakuru—where repair shop formalization creates first-mover warranty fulfillment opportunities. Pursue B2B education sector procurement in South Africa and Nigeria as the most penetrable institutional channel.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform aggregators with unified quality guarantees over fragmented informal trader networks. The five-to-ten year viability window hinges on regulatory professionalization completing across major African markets. Acquisition targets should demonstrate in-house compliance documentation capabilities and established testing laboratory relationships. Watch for e-waste handling mandate harmonization across Gulf Cooperation Council states as the signal for supply disruption severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Distributed ledger deployment decomposes price premiums previously extracted by information-asymmetric intermediaries in Dubai trading corridors. |
| Authorized Service Network Expansion | Samsung and Apple certified refurbishment programs capture margin concentration through warranty-backed quality guarantees in Lagos and Johannesburg. |
| Secondary City Distribution Buildout | Mombasa and Kisumu repair shop formalization creates last-mile infrastructure beyond Nairobi's saturated retail environment. |
| Electromagnetic Compliance Investment | South Africa's National Regulator for Compulsory Specifications mandates force professionalization of previously informal import operations. |
| Education Sector B2B Procurement | Institutional tablet deployments through Durban and Abu Dhabi channels bypass retail markup and establish recurring revenue relationships. |
Research Methodology
The analysis maps smartphone, tablet, and feature phone refurbishment tiers, each validated through primary interviews with Dubai-based traders, Lagos electronics market distributors, South African authorized service network managers, and Kenyan repair shop operators. Secondary sources include Nigeria's Standards Organisation certification records, South Africa's National Regulator for Compulsory Specifications electromagnetic compatibility filings, UAE Department of Economy and Tourism re-export documentation, and EU WEEE directive retirement flow data. Bottom-up channel volume estimates triangulate against top-down device retirement projections from European carrier upgrade cycles.
Consistency checks against regional customs data and carrier trade-in program disclosures validated volume and value outputs across the projection horizon. The analytical framework models condition grade, operating system fragmentation, distribution channel formalization, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from fitted growth curves calibrated to urban professional adoption patterns and certification mandate implementation timelines. Key inputs include lithium-ion battery replacement cost trajectories and Dubai-to-Lagos shipping lane capacity utilization rates.
Material uncertainties—customs protocol shifts, e-waste mandate harmonization delays, and component authentication skill gap resolution—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory professionalization pacing and European device retirement volume stability. Practitioners should keep alternative scenarios live as Gulf Cooperation Council e-waste handling mandates and East African Community customs protocol negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Phone Tripod Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Airport Retailing Consumer Electronics Market