
 India Wireless Audio Market | 2026-2036
India Wireless Audio Market Size, Share, and Industry Trends Forecast 2026-2036
India Wireless Audio Market Foresight
Codec standardization across Bluetooth LE Audio and LC3 is fragmenting platform compatibility requirements for device makers. Imagine Marketing Limited (boAt) leverages its Mumbai-based design center to dominate budget-tier earbuds with rapid SKU turnover. Samsung Electronics Co Ltd anchors premium Android audio through its Galaxy Buds ecosystem and Knox security integration. Apple Inc. controls the high-ASP segment by tethering AirPods to its iOS device base.
India Wireless Audio encompasses portable sound reproduction equipment that transmits audio signals without physical cabling, typically operating on Bluetooth protocols with 2.4 GHz ISM band transmission, Class 2 power profiles, and battery capacities ranging from 40 mAh in earbuds to 5000 mAh in portable speakers. Earbuds lead volume shipments due to smartphone bundle deals and gym-centric use cases, while soundbars capture disproportionate margin pools as consumers upgrade home entertainment systems post-pandemic. Bluetooth technology sustains near-universal device interoperability, though Wi-Fi-enabled multi-room speakers represent the fastest-growing connectivity segment among urban households with fiber broadband.
BIS certification under the Compulsory Registration Scheme and WPC approval for radio frequency devices govern market access, with recent amendments pushing brands toward local assembly to qualify for government procurement and PLI scheme benefits. CDSCO oversight applies to hearing-aid-integrated wearables, creating a dual-regulatory pathway for health-audio convergence products. Stakeholders must monitor whether BIS expands mandatory testing to cover latency specifications and battery safety protocols, as these parameters increasingly influence consumer purchase decisions and return rates.
Market Dynamics
The BIS Compulsory Registration Scheme is compressing import timelines and forcing brands toward local assembly partnerships, reshaping competitive positioning around PLI scheme eligibility rather than pure cost arbitrage.
Growth Catalysts
- Bluetooth LE Audio with LC3 codec:This protocol stack halves power consumption while enabling broadcast audio, opening public venue deployments in metro stations and airports.
- PLI scheme for electronics manufacturing:Tier-2 cities attract assembly investments as brands qualify for fiscal incentives tied to domestic value addition.
- Fitness ecosystem integration:Gym chains bundle true wireless earbuds with membership tiers, creating hardware-anchored subscription models.
Market Restraints
- Lithium-ion cell import dependence:Battery supply concentrates in East Asian manufacturing clusters, exposing margins to shipping cost volatility and forex fluctuation.
- BIS testing queue congestion:Mandatory local certification creates six-to-eight week entry delays for new SKUs, compressing product launch windows.
- Wired audio residual preference:Audiophile segments and budget-conscious rural buyers sustain demand for 3.5mm headphones, limiting category conversion rates.
Strategic Opportunities
- Hearing-aid wearable convergence:CDSCO's medical device pathway for audio wearables creates a regulated channel for OTC hearing assistance products.
- Tamil Nadu electronics corridor:Sriperumbudur and Oragadam clusters offer plug-and-play assembly infrastructure with proximity to Chennai port logistics.
- Wi-Fi multi-room audio:Fiber broadband penetration in Mumbai and Bengaluru enables whole-home audio systems that bypass Bluetooth range constraints.
Industry Challenges
- RF engineering talent scarcity:Antenna design and interference mitigation skills concentrate in Bengaluru and Hyderabad, constraining R&D scaling in other clusters.
- Battery safety certification complexity:UN 38.3 testing for air shipment and BIS thermal runaway protocols add parallel compliance tracks for each SKU variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wireless Audio Market |
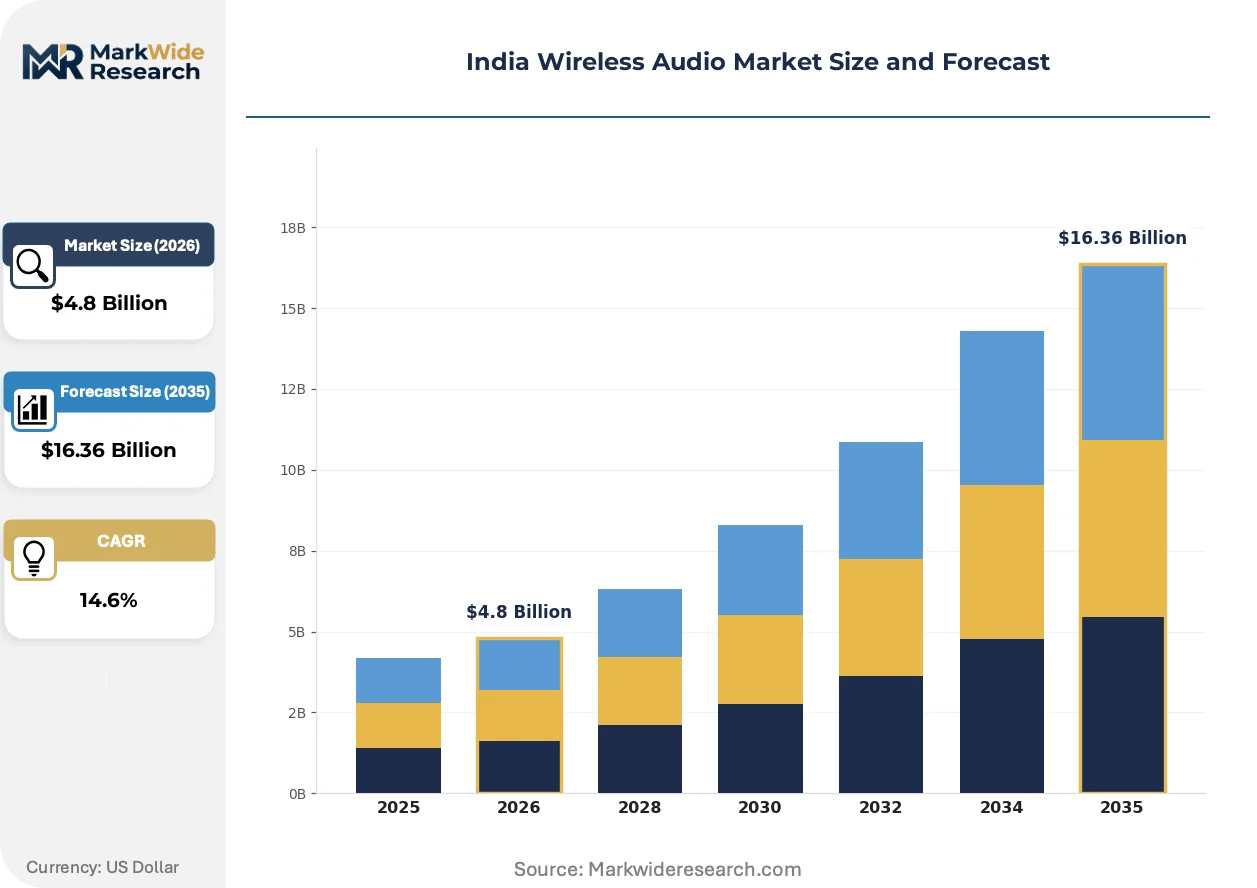
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headphones, Earbuds, Speakers, Soundbars Technology: Bluetooth, Wi-Fi, RF, NFC End User: Consumers, Corporate, Educational Institutions, Entertainment Distribution Channel: Online Retail, Offline Stores, Wholesale, Direct Sales |
| Companies Covered | Imagine Marketing Limited (boAt), Samsung Electronics Co Ltd, Apple Inc., Sony Group Corporation, Bose Corporation, BBK Electronics, Xiaomi Corporation, Sennheiser, Anker Innovations, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wireless Audio Market Shifts & Advancements
Codec virtualization and regulatory localization are compressing product lifecycles while opening new compliance-driven competitive moats for domestic assemblers.
Auracast broadcast audio is virtualizing public address infrastructure. Transit authorities in Delhi and Mumbai pilot hearing-loop replacement systems that stream gate announcements directly to passenger earbuds. This architecture eliminates copper wiring in station retrofits and enables personalized volume control for hearing-impaired travelers.
BIS amendments to the Compulsory Registration Scheme now cover latency specifications and battery thermal thresholds. The Bureau of Indian Standards mandates local lab testing for RF emission profiles, pushing multinational brands to establish captive testing facilities in NCR and Pune rather than relying on overseas certification reciprocity.
Channel consolidation is compressing distributor margins as e-commerce platforms bundle wireless audio with smartphone purchases. Flipkart and Amazon India negotiate exclusive colorways and launch windows, displacing traditional electronics retail in Maharashtra and Karnataka urban centers. Offline channels pivot toward experiential demonstration for premium soundbars where acoustic testing drives conversion.
India Wireless Audio Market Segmentation
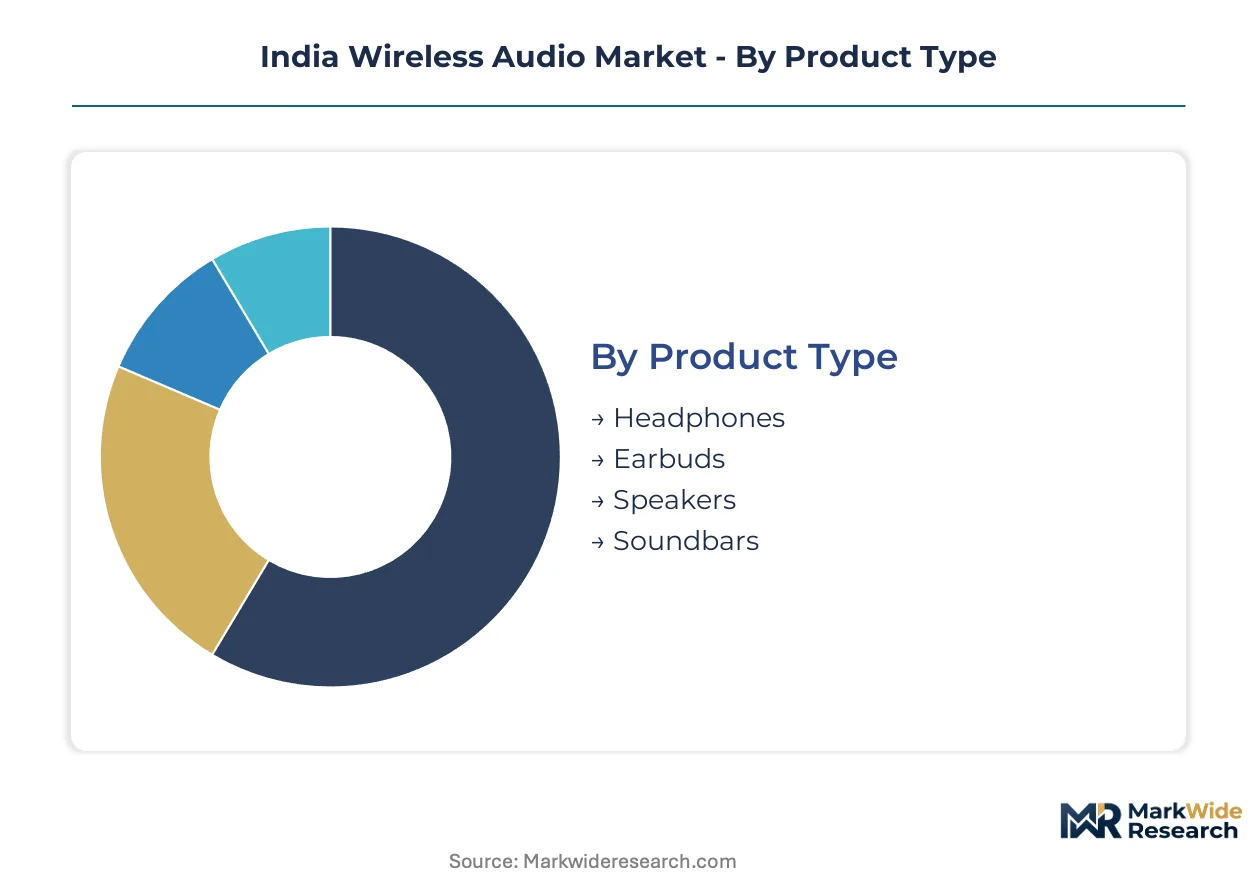
Segmentation in India's wireless audio market reveals how codec standards, connectivity protocols, and procurement channels fragment revenue pools across distinct customer workflows. Each dimension carries regulatory and supply-chain implications that shape competitive entry strategies.
Product Type:
Mature categories dominate current revenue while emerging form factors capture fitness and home-theater expansion.
- Earbuds:True wireless stereo devices with 40-60 mAh per-bud batteries and touch-control interfaces. Demand concentrates in Maharashtra and Karnataka gym chains bundling hardware with membership tiers, though BIS certification queues compress launch windows for new SKUs.
- Soundbars:Multi-driver arrays with HDMI-ARC connectivity and subwoofer pairing protocols. Tamil Nadu and Delhi NCR households upgrading post-pandemic home theaters drive disproportionate margin capture despite lower shipment volumes.
- Headphones:Over-ear and on-ear designs with active noise cancellation and 500+ mAh battery capacities.
- Speakers:Portable and desktop units spanning Bluetooth-only to Wi-Fi multi-room architectures.
Earbuds retain volume leadership; soundbars hold the steepest expansion curve.
Technology:
Cost tiers separate legacy connectivity from next-generation protocol stacks with diverging certification burdens.
- Bluetooth:Dominant protocol operating on 2.4 GHz ISM band with Class 2 power profiles and LE Audio codec virtualization. Tamil Nadu assembly clusters optimize for this standard's component ecosystem, though antenna design talent scarcity in non-Bengaluru locations constrains R&D scaling.
- Wi-Fi:Multi-room synchronization and lossless streaming over 5 GHz bands requiring fiber broadband penetration. Mumbai and Bengaluru urban households with FTTH connectivity drive adoption as Bluetooth range limitations frustrate whole-home coverage.
- RF:Proprietary radio frequency systems for specialized enterprise and broadcast applications.
- NFC:Tap-to-pair functionality primarily embedded in premium-tier devices for seamless device handoff.
Bluetooth anchors current shipment volumes; Wi-Fi multi-room systems are climbing the fastest.
End User:
Application contexts determine feature prioritization and procurement authority structures.
- Consumers:Individual purchasers prioritizing battery life, codec compatibility, and price-to-performance ratios. Tier-2 cities accelerate adoption as PLI scheme incentives localize assembly and compress retail pricing.
- Corporate:Enterprise procurement of unified communications headsets with Teams and Zoom certification. CDSCO oversight for hearing-aid-integrated wearables creates dual-regulatory pathways for health-audio convergence products in this segment.
- Educational Institutions:Bulk purchasing for hybrid learning infrastructure with durability and sanitization requirements.
- Entertainment:Venue and broadcast deployments leveraging Auracast broadcast audio for public address virtualization.
Consumers retain volume leadership; corporate represents the fastest-growing procurement channel.
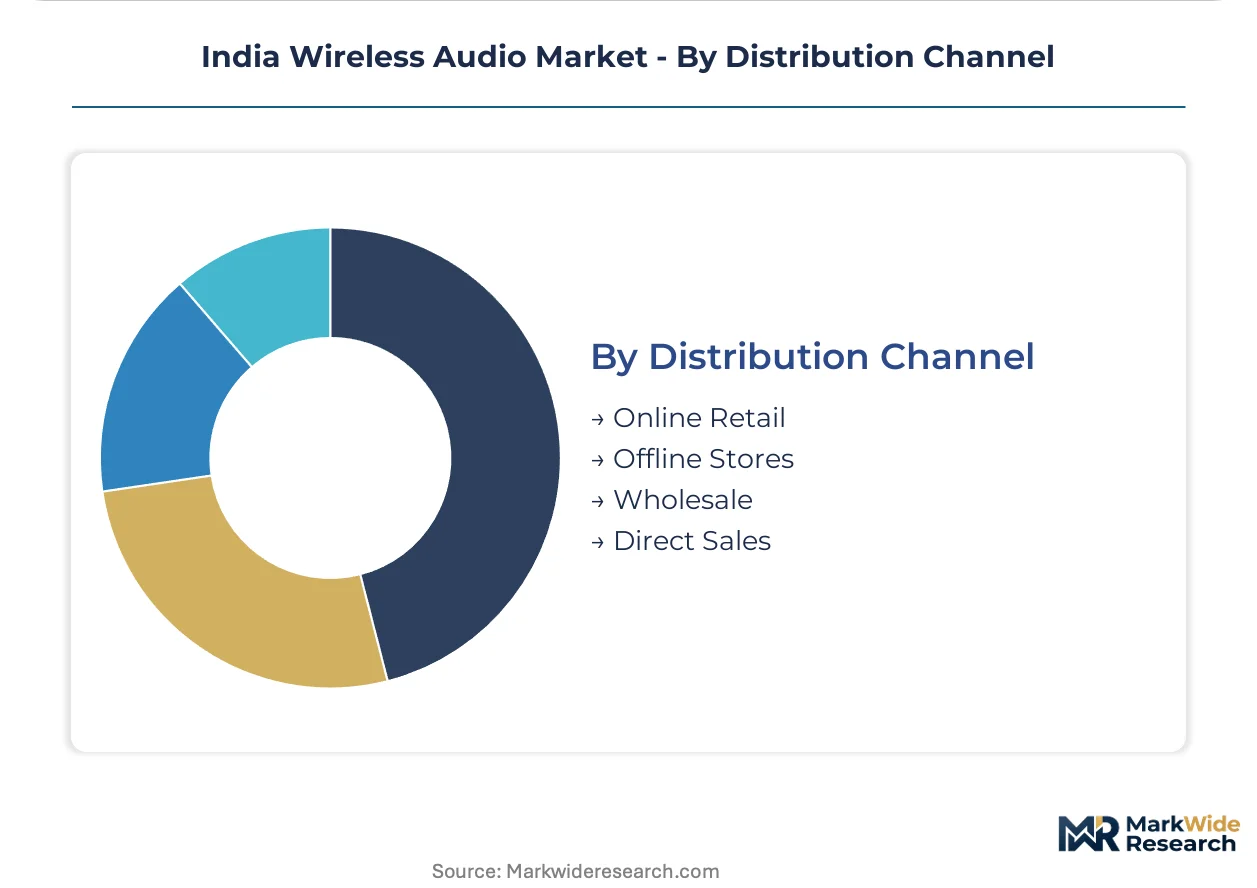
Distribution Channel:
Geography determines channel efficiency as e-commerce platforms consolidate negotiating power.
- Online Retail:Platform-exclusive colorways and bundled smartphone promotions displacing traditional electronics retail. Flipkart and Amazon India dominate Maharashtra and Karnataka urban centers with launch-window exclusivity.
- Offline Stores:Experiential demonstration for premium soundbars where acoustic testing drives conversion in Chennai and Delhi NCR malls.
- Wholesale:Bulk distribution to regional electronics markets and smaller retail networks.
- Direct Sales:Manufacturer-owned channels for enterprise and institutional contracts with customized fleet management.
Online retail retains volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals and fitness enthusiasts in tier-2 Indian cities are accelerating adoption of true wireless earbuds, while electronics manufacturing clusters concentrate in states with PLI scheme infrastructure.
Maharashtra
Mumbai's design centers and Pune's testing facilities drive product development velocity for budget-tier brands. BIS mandates local certification for all imported wireless devices, compressing entry timelines for new SKUs. The Mumbai metropolitan electronics retail corridor dominates online-offline channel integration for smartphone-bundled audio sales.
Karnataka
Bengaluru's RF engineering talent pool anchors antenna design and interference mitigation capabilities for premium device makers. The state's electronics manufacturing policy complements central PLI incentives for domestic value addition. Whitefield and Electronic City clusters host captive testing facilities established by multinational brands seeking BIS compliance reciprocity.
Tamil Nadu
Sriperumbudur and Oragadam assembly corridors offer plug-and-play manufacturing infrastructure with Chennai port logistics proximity. CDSCO oversight for hearing-aid-integrated wearables creates dual-regulatory pathways for health-audio convergence products. Post-pandemic home theater upgrades in Chennai households drive soundbar margin capture disproportionate to shipment volumes.
Telangana
Hyderabad's semiconductor design ecosystem feeds into wireless audio chip customization for mid-tier brands. The state's electronics manufacturing cluster policy attracts assembly investments seeking fiscal incentives tied to domestic production. Secunderabad's logistics hubs facilitate battery component sourcing from East Asian supply chains.
Delhi-NCR
Gurugram and Noida host captive BIS testing facilities established by brands avoiding overseas certification delays. The region's consumer electronics retail density supports experiential demonstration formats for premium soundbar conversions. NCR's enterprise procurement channels drive unified communications headset demand with Teams and Zoom certification requirements.
India Wireless Audio Market Competitive Landscape
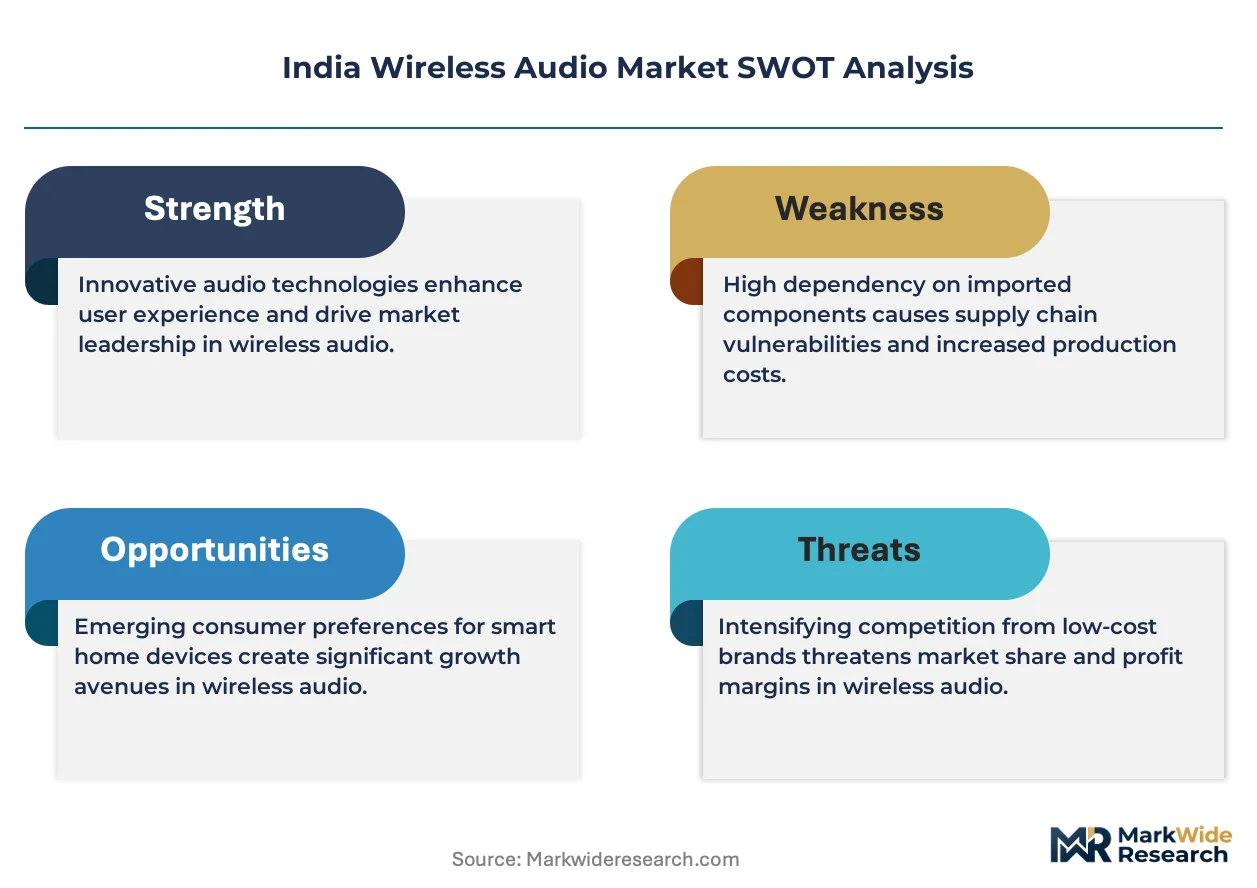
Channel-controlling players compete with product-specialist players across tiered price bands defined by certification compliance rather than pure cost arbitrage. The vendor base clusters around three strategic archetypes: domestic assemblers leveraging PLI scheme eligibility, multinational electronics conglomerates with ecosystem lock-in capabilities, and audio-specialist brands commanding audiophile loyalty. Competitive moves concentrate on local assembly partnerships for BIS compliance acceleration and exclusive e-commerce launch windows displacing traditional electronics retail.
Among domestic assemblers, Imagine Marketing Limited (boAt) exemplifies the rapid-SKU-turnover archetype targeting budget-tier consumers through Mumbai-based design integration. Samsung Electronics Co Ltd and Apple Inc. occupy positions at the premium ecosystem-locked tier, with the former anchoring Android audio through Galaxy device integration and the latter controlling high-ASP segments via iOS tethering. These three companies represent the dominant competitive anchors shaping pricing architecture and certification investment thresholds across Maharashtra, Karnataka, and Tamil Nadu demand clusters.
| Leading Market Players |
|---|
| Imagine Marketing Limited (boAt) |
| Samsung Electronics Co Ltd |
| Apple Inc. |
| Sony Group Corporation |
| Bose Corporation |
| BBK Electronics |
| Xiaomi Corporation |
| Sennheiser |
| Anker Innovations |
| Others |
Supply & Pricing Matrix
BIS testing queue congestion functions as the primary pricing chokepoint, compressing launch windows for new SKUs while simultaneously forcing brands toward local assembly partnerships that reshape cost structures across premium and economy tiers.
Pricing Analysis
Cost-plus contracts with lithium-ion cell indexation dominate procurement between assembly partners and battery suppliers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with PLI scheme eligibility creating differentiation between domestic assemblers and import-dependent competitors. Cost compression in the economy tier intensifies because smartphone bundle deals commoditize entry-level earbuds. Tier-2 city consumers exhibit highest price sensitivity, while enterprise procurement channels for unified communications headsets show lowest sensitivity due to compliance requirements.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Dixon Technologies, and Lava International holding assembly capacity in Sriperumbudur and Noida. Component sourcing draws from China, Vietnam, and South Korea for lithium-ion cells, Bluetooth chipsets, and antenna substrates. Single-source vulnerability in East Asian battery supply chains exposes margins to shipping cost volatility and forex fluctuation. Distribution runs through e-commerce platform consolidation, with Flipkart and Amazon India negotiating exclusive launch windows that displace traditional electronics retail in Maharashtra and Karnataka urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wired audio residual preference in audiophile and rural segments constitutes the substitution threat that wireless incumbents must neutralize through feature differentiation and price compression.
For Market Incumbents: Entrench ecosystem lock-in by deepening Galaxy Buds and AirPods integration with smartphone operating systems, while accelerating captive BIS testing facility investments in NCR and Pune to compress certification timelines against emerging domestic challengers.
For New Entrants and Emerging Players: Tier-3 city underpenetration offers white-space expansion where fitness ecosystem bundling remains nascent and offline demonstration formats for soundbars retain conversion leverage. Target hearing-aid wearable convergence products requiring CDSCO medical device pathway compliance as the most defensible entry angle.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors domestic assemblers with PLI scheme eligibility and established BIS compliance infrastructure. Acquisition targets should demonstrate captive testing capabilities and Tamil Nadu or Maharashtra assembly footprint. Quarterly review of BIS amendment timelines and PLI scheme incentive disbursement rates is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Qualifies brands for PLI scheme incentives and accelerates BIS certification timelines. |
| Captive Testing Facility Establishment | Eliminates six-to-eight week overseas certification delays for new SKU launches. |
| Fitness Ecosystem Bundling | Creates hardware-anchored subscription models through gym chain membership tiers. |
| Auracast Broadcast Audio Deployment | Opens transit authority and public venue replacement of copper-wired PA infrastructure. |
| Hearing-Aid Wearable Convergence | Accesses CDSCO-regulated medical device channel for OTC hearing assistance products. |
Research Methodology
A standing panel of RF engineering directors, BIS certification consultants, electronics manufacturing plant managers, and e-commerce category buyers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against BIS registration databases, WPC approval records, PLI scheme beneficiary disclosures, and customs import manifests for wireless audio hardware. Bottom-up shipment estimates from Tamil Nadu and Maharashtra assembly clusters were triangulated with top-down consumer expenditure surveys.
Scenario-bracketing anchored volume projections across conservative, baseline, and aggressive regulatory enforcement assumptions. Segmentation dimensions modeled include product form factor, connectivity protocol, end-user application context, and distribution channel structure. CAGRs were derived from curve-fitting historical shipment trajectories against PLI scheme incentive disbursement schedules and fiber broadband penetration curves in Mumbai and Bengaluru.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated smartphone OEMs or sudden BIS testing capacity expansion would shift outcomes. Quarterly review of BIS amendment proposals and lithium-ion cell import duty adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Global Audio Devices and Components Market
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
Global Automotive Premium Audio System Market
Audio Equipment
Monitoring Sound Box for Playing Market
Audio Equipment
Car Audio Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Smart Audio System Market
Audio Equipment
Canada Gaming Headsets Market
Audio Equipment
Japan Gaming Headset Market
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Radio Headset Market
Audio Equipment
United Kingdom Gaming Headset Market
Audio Equipment
Studio Headphones Market