
 Soft Support Products Market | 2026-2036
Soft Support Products Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Support Products Market Analytics
Home-based recovery patients are reorganizing demand patterns away from acute-care procurement, pulling volume toward retail and direct-to-consumer channels. DJO Global leverages its rehabilitation heritage to sustain clinical credibility in this shift. Zimmer Biomet anchors hospital contract relationships while extending into outpatient positioning solutions. Ottobock differentiates through specialized seating and support expertise drawn from its prosthetics lineage.
Soft support products encompass pliable, body-conforming devices engineered from viscoelastic or elastomeric substrates to redistribute pressure, maintain neutral joint alignment, and reduce musculoskeletal load during seated or recumbent postures. Manufacturing employs open-cell polyurethane foaming or gel-infusion molding to achieve density gradients between 40 and 80 kilograms per cubic meter for calibrated support. Memory foam back cushions and lumbar rolls command the widest installed base, though gel-based knee pillows are capturing faster growth in travel and sports recovery segments where thermal regulation and portability carry premium value.
The FDA's medical device quality system regulation shapes product testing protocols for clinical-grade supports, while ISO 10993 biocompatibility standards govern skin-contact material safety across international distribution. The EU Medical Device Regulation tightens post-market surveillance requirements for products claiming therapeutic positioning benefits, raising compliance costs for cross-border suppliers. Stakeholders must weigh certification investments against channel-specific margin structures as clinical and consumer boundaries blur.
Market Dynamics
Workplace ergonomics mandates in Germany are triggering institutional procurement waves that are restructuring distribution channels across the soft support products sector, pulling volume from acute-care settings toward direct-to-consumer platforms.
Growth Catalysts
- EU Medical Device Regulation:Tightened post-market surveillance requirements for therapeutic positioning claims are elevating quality thresholds, filtering out marginal suppliers and consolidating demand around certified manufacturers.
- Industrial wellness sector:German workplace ergonomics mandates are driving bulk purchasing agreements for lumbar rolls and ergonomic seating across manufacturing and logistics facilities.
- Gel-infusion molding:Advances in thermal-regulating gel substrates are expanding addressable use cases into sports recovery and travel segments where portability and temperature management command premium positioning.
Market Restraints
- Polyurethane foam feedstock volatility:Petrochemical input cost swings compress margin predictability for open-cell foam manufacturers operating on fixed hospital contract terms.
- East Asian foam concentrate supply:Geopolitical friction around specialty chemical precursors creates single-source vulnerability for density-gradient formulations above 60 kilograms per cubic meter.
- Biocompatibility testing timelines:ISO 10993 skin-contact certification cycles extend 14-18 months, freezing product iteration speed for clinical-grade launches.
Strategic Opportunities
- Home-based recovery expansion:Post-surgical patients in the United States are bypassing durable medical equipment intermediaries, creating direct-to-patient subscription models for positioning device replenishment.
- CE marking acceleration:Streamlined conformity assessment pathways for Class I orthopedic supports under the EU MDR reduce time-to-market for manufacturers with established quality management systems.
- Smart textile convergence:Integration of pressure-mapping sensors with viscoelastic substrates enables real-time posture feedback, opening premium pricing tiers in corporate wellness programs.
Industry Challenges
- Polymer formulation expertise scarcity:The specialized knowledge required for density-gradient foaming with calibrated viscoelastic response is concentrated among aging technical workforces in Germany and Japan.
- Dual-channel compliance complexity:Manufacturers serving both clinical and retail segments must maintain parallel quality systems under FDA 21 CFR Part 820 and consumer product safety frameworks, doubling audit overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Support Products Market |
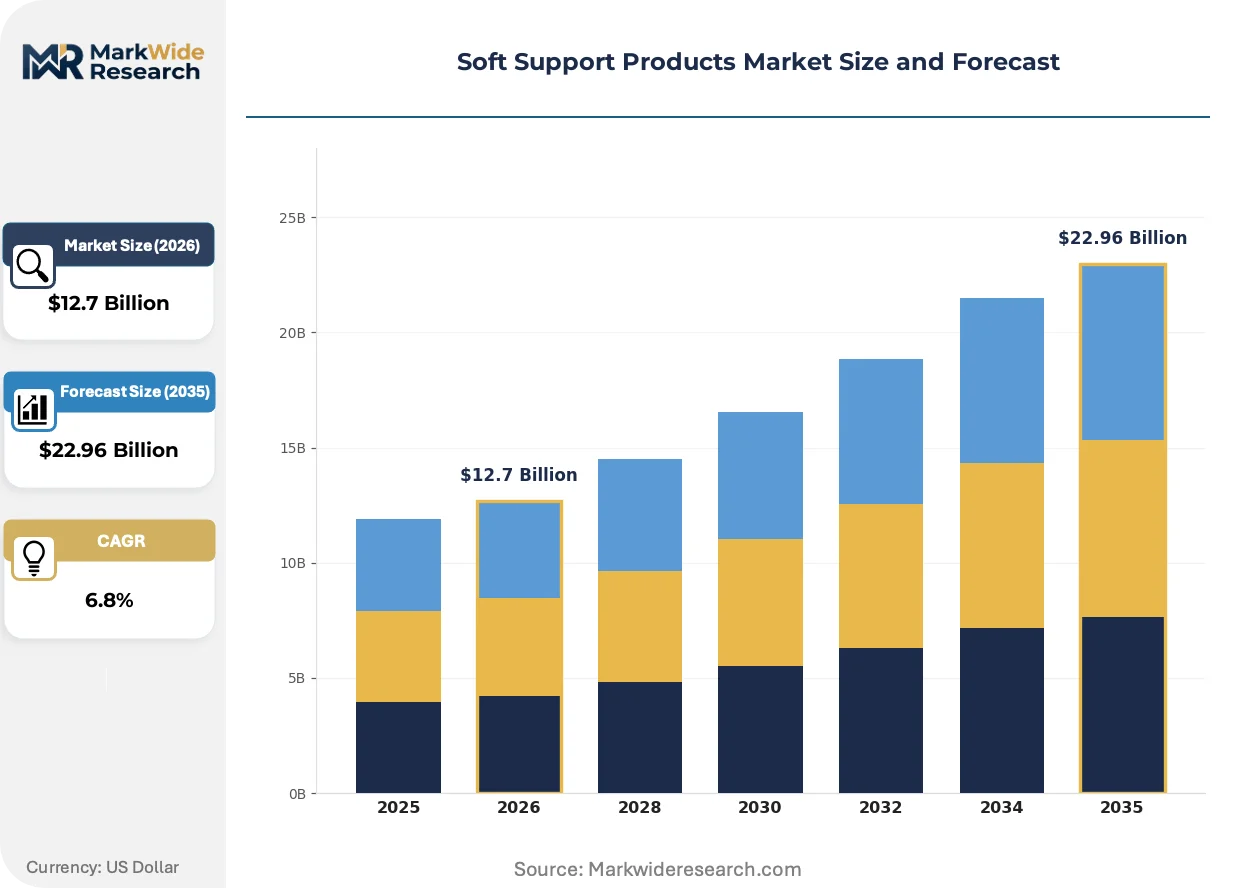
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Back Cushions, Neck Supports, Knee Pillows, Lumbar Rolls Material: Memory Foam, Gel, Air, Polyester Application: Healthcare, Sports, Travel, Home End User: Individuals, Clinics, Wellness Centers, Hospitals |
| Companies Covered | 3M, Zimmer Biomet, Ossur, DJO Global, Breg, Essity, Smith & Nephew, Stryker, Ottobock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Support Products Market Evolving Landscape
Material science advances and regulatory recalibration are compressing product development cycles while fragmenting buyer power across clinical and consumer domains. Three developments are restructuring competitive positioning.
Phase-change material integration is supplanting static gel formulations in premium knee pillows and travel cushions. Airlines and long-haul transportation operators are adopting these substrates at accelerating pace for crew rest applications. The shift is compressing addressable margins for conventional gel manufacturers while rewarding thermal-management specialists with aerospace heritage.
REACH restrictions on isocyanate exposure in polyurethane manufacturing are forcing reformulation of open-cell foaming processes across European production facilities. Industrial hygiene compliance costs are elevating minimum efficient scale, pushing mid-tier converters toward toll-manufacturing arrangements with larger chemical processors. German industrial wellness procurement is most affected, with buyers now requiring extended safety data sheets as contract preconditions.
Hospital materials management departments are unbundling positioning device procurement from bundled surgical episode payments, creating spot-market purchasing for post-acute recovery kits. Retail pharmacies and orthopedic specialty distributors are capturing this volume in the United States through same-day fulfillment partnerships with outpatient surgery centers. The pattern is most visible in ambulatory surgical facility networks concentrated in Texas and Florida, where patient discharge velocity prioritizes take-home kit completeness over brand loyalty.
Soft Support Products Market Segmentation
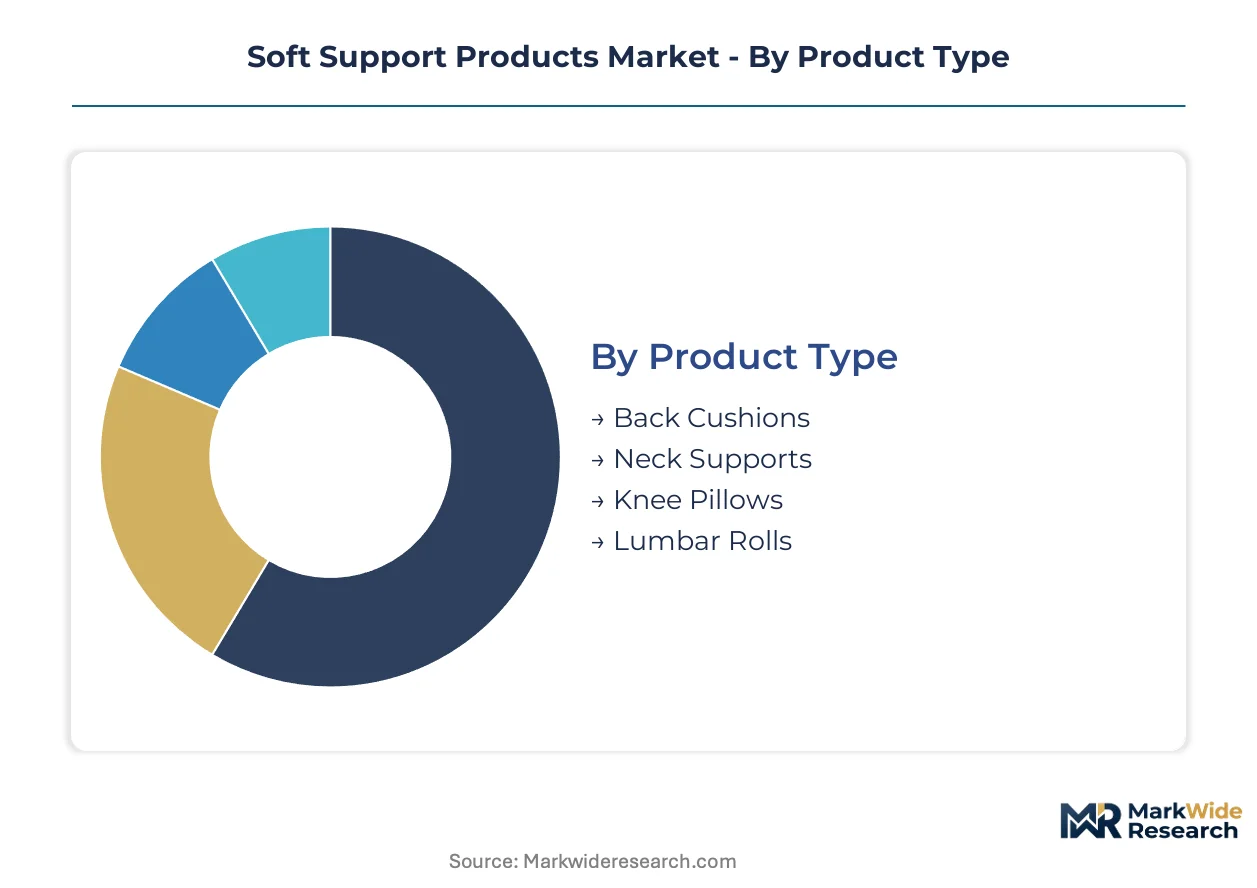
Segmentation in soft support products determines channel strategy and margin architecture. Clinical-grade positioning devices flow through institutional procurement, while consumer-oriented formats exploit retail and direct-to-patient pathways. Material composition and application context dictate certification requirements and pricing power.
Product Type:
Channel mix varies sharply by product format. Back cushions and lumbar rolls dominate hospital and industrial wellness procurement, while knee pillows and neck supports concentrate in travel retail and sports specialty channels.
- Back Cushions:Viscoelastic foam substrates with density gradients between 50 and 70 kilograms per cubic meter provide calibrated lumbar support. German manufacturing facilities and US outpatient surgery centers drive institutional procurement of clinical-grade variants with ISO 10993 biocompatibility certification.
- Lumbar Rolls:Cylindrical positioning devices engineered from open-cell polyurethane or gel-infusion molding maintain neutral spinal curvature during seated postures. Workplace ergonomics mandates in Germany are accelerating bulk purchasing agreements across logistics and automotive assembly facilities.
- Neck Supports:Contoured foam collars and travel pillows target airline crew rest applications and patient transport.
- Knee Pillows:Inter-leg positioning wedges for side-sleepers and post-surgical recovery.
Back cushions dominate installed base. Knee pillows are where expansion concentrates.
Material:
Cost tier stratification separates premium thermal-regulating substrates from commodity foam conversions. Gel and memory foam command clinical and travel premium positioning, while air and polyester occupy value-oriented home and sports segments.
- Memory Foam:Open-cell polyurethane formulations with calibrated viscoelastic response between 40 and 80 kilograms per cubic meter. REACH restrictions on isocyanate exposure are elevating compliance costs for European manufacturers and pushing mid-tier converters toward toll-manufacturing arrangements.
- Gel:Thermal-regulating elastomeric substrates with phase-change material integration supplanting static formulations in premium travel and crew rest applications. Airlines are adopting these substrates at accelerating pace, compressing margins for conventional gel manufacturers.
- Air:Inflatable chambers with adjustable firmness for portable positioning and travel.
- Polyester:Fiber-fill and batting constructions for economy-tier home and sports recovery applications.
Memory foam anchors revenue concentration. Gel substrates are gaining share fastest in premium positioning.
Application:
Customer type fragmentation splits demand between institutional procurement and direct-to-consumer fulfillment. Healthcare and home applications are reorganizing around patient discharge velocity, while sports and travel exploit portability and thermal management as differentiation vectors.
- Healthcare:Clinical-grade positioning devices for post-surgical rehabilitation and pressure injury prevention. US ambulatory surgical facility networks in Texas and Florida are unbundling procurement from bundled episode payments, creating spot-market purchasing for take-home recovery kits.
- Home:Retail and direct-to-patient channels for sleep positioning and ergonomic seating. Post-surgical patients are bypassing durable medical equipment intermediaries, enabling subscription replenishment models.
- Sports:Recovery-focused positioning for athletic training and injury management.
- Travel:Portable cushions for long-haul transportation and hospitality applications.
Healthcare commands pricing power. Home is where channel restructuring concentrates.
End User:
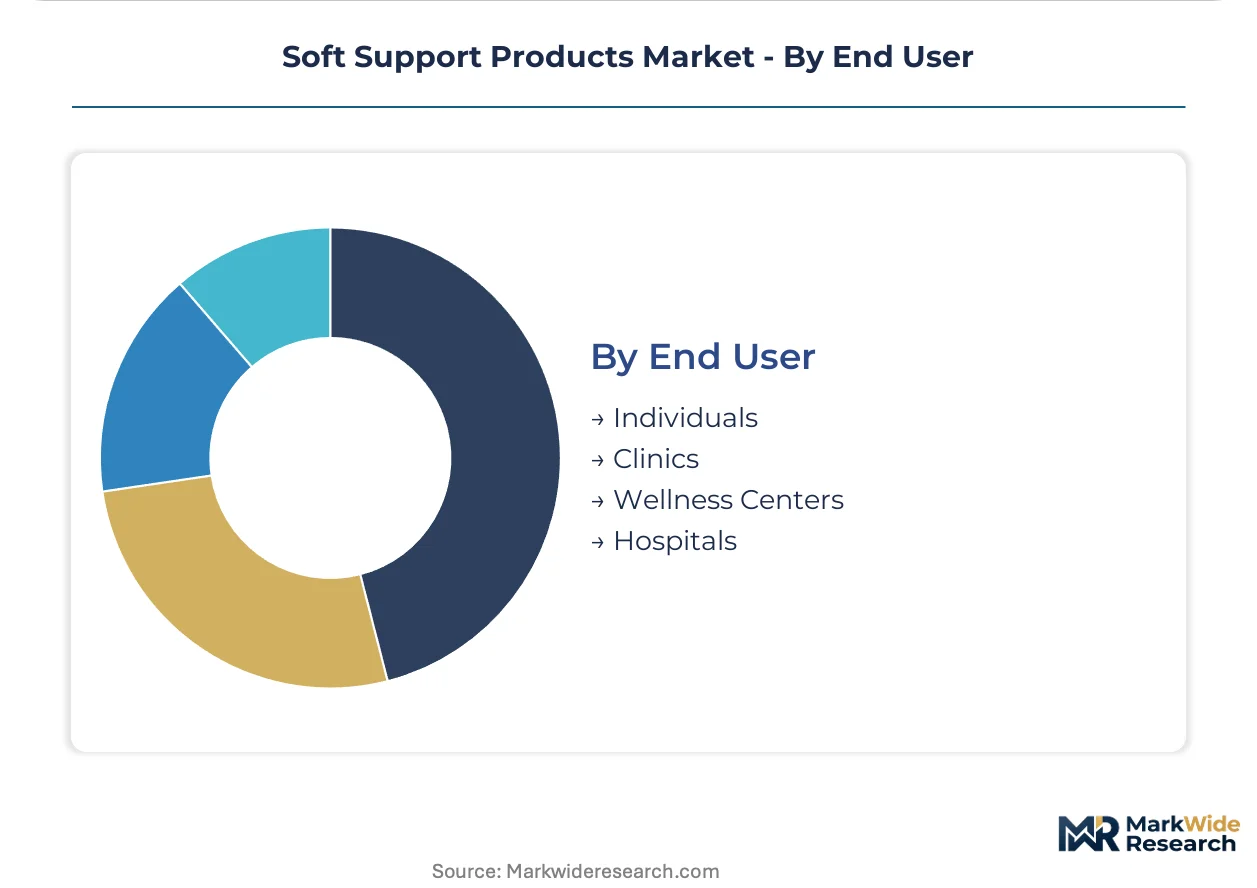
Volume concentration sits with institutional buyers, though margin expansion favors direct channels. Hospitals and wellness centers demand certified clinical-grade products, while individual purchasers prioritize convenience and thermal comfort over regulatory documentation.
- Individuals:Direct-to-consumer and retail pharmacy purchasers for home-based recovery and ergonomic seating. Same-day fulfillment partnerships between retail pharmacies and outpatient surgery centers are capturing discharge kit volume in the United States.
- Hospitals:Materials management departments procuring clinical-grade positioning devices under FDA 21 CFR Part 820 quality system regulation. Unbundling from bundled surgical payments is compressing brand loyalty in favor of take-home kit completeness.
- Clinics:Outpatient rehabilitation and orthopedic specialty practices.
- Wellness Centers:Corporate and industrial ergonomics programs, particularly in Germany where workplace mandates drive bulk purchasing.
Hospitals anchor contract value. Individuals are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export specialized polyurethane foaming equipment and density-calibrated substrates to outpatient surgery networks in Texas and Florida. This trade corridor channels European technical expertise into North American post-acute procurement channels.
United States
Ambulatory surgical facilities in Texas and Florida are unbundling positioning device procurement from bundled episode payments. FDA's 21 CFR Part 820 quality system regulation governs clinical-grade imports. Houston and Dallas medical supply distributors are capturing discharge kit volume through same-day fulfillment partnerships.
Germany
Industrial wellness mandates across automotive assembly and logistics facilities are accelerating bulk purchasing agreements for lumbar rolls. REACH restrictions on isocyanate exposure in polyurethane manufacturing are elevating compliance costs for open-cell foam producers. Bavarian chemical processors are consolidating toll-manufacturing arrangements with mid-tier converters.
Japan
Aging technical workforces concentrated in Osaka and Nagoya are creating polymer formulation expertise scarcity for viscoelastic density-gradient foaming. METI industrial standards govern workplace ergonomics equipment certification. Tokyo-based rehabilitation device distributors are expanding into direct-to-patient subscription models.
China
Domestic foam concentrate supply chains face geopolitical friction around specialty chemical precursors above 60 kilograms per cubic meter density. NMPA medical device classification governs therapeutic positioning claims. Yangtze River Delta manufacturers are vertically integrating into gel-infusion molding for travel and sports recovery segments.
United Kingdom
Post-surgical patients are bypassing durable medical equipment intermediaries, pulling demand toward retail pharmacy channels. MHRA aligns with EU MDR post-market surveillance requirements for therapeutic positioning benefits. London and Southeast England distribution networks are integrating pressure-mapping sensor technologies from corporate wellness programs.
Soft Support Products Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and channel reach. The vendor base stratifies between hospital contract incumbents and direct-to-consumer challengers. Three archetypes dominate: diversified orthopedic conglomerates with rehabilitation heritage, specialized seating and support experts drawn from prosthetics lineages, and industrial wellness suppliers with workplace ergonomics credentials. Competitive moves concentrate on M&A to capture outpatient surgery center relationships and geographic expansion into German institutional procurement channels.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker exemplify scale-driven positions anchored in hospital materials management departments. DJO Global occupies a specialist tier leveraging rehabilitation heritage for clinical credibility in retail channel shifts. Ottobock represents the prosthetics-to-positioning lineage, with seating expertise translating into ergonomic support differentiation. These three anchors illustrate how technical credibility and certification depth separate institutional-grade suppliers from commodity foam converters.
| Leading Market Players |
|---|
| 3M |
| Zimmer Biomet |
| Ossur |
| DJO Global |
| Breg |
| Essity |
| Smith & Nephew |
| Stryker |
| Ottobock |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 820 quality system regulation gates both supplier qualification and price differentiation in clinical-grade soft support products, compressing margins for uncertified converters while rewarding ISO 10993-compliant manufacturers with hospital contract premiums. This regulatory threshold simultaneously shapes supply base consolidation and tiered pricing architecture across institutional and consumer channels.
Pricing Analysis
Static gel formulations command prior-generation pricing floors while phase-change material integration and pressure-mapping sensor substrates define next-generation premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified clinical devices from CE-marked wellness products and uncertified retail commodities. Pricing pressure stems from REACH compliance cost inflation in European polyurethane manufacturing, compressing mid-tier converter margins. Hospital materials management departments exhibit lowest price sensitivity due to bundled episode accounting, while individual direct-to-consumer purchasers drive hardest bargain hunting.
Supply Chain Analysis
Port congestion on Rotterdam-Houston petrochemical lanes elevates inbound logistics costs for specialty isocyanate precursors above sixty kilograms per cubic meter density grades. Manufacturing concentrates in Germany, China, and the United States, drawing from East Asian foam concentrate supply chains and Bavarian toll-processing networks. Single-source vulnerability around specialty chemical precursors creates supply chain risk for density-gradient formulations. Distribution runs through hospital materials management departments, retail pharmacy same-day fulfillment partnerships, and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soft support products are approaching a platform-economics inflection where sensor-integrated smart textiles and real-time posture feedback ecosystems will restructure value capture away from commodity foam converters toward data-enabled service providers.
For Market Incumbents: Consolidate polymer formulation expertise scarcity through targeted acquisition of German and Japanese technical workforces nearing retirement. Capture outpatient surgery center relationships in Texas and Florida through same-day fulfillment partnerships before retail pharmacies lock in exclusive discharge kit contracts. Defend against direct-to-consumer challengers by embedding subscription replenishment models into hospital discharge protocols. For New Entrants and Emerging Players: CE marking fast-track pathways for Class I orthopedic supports under EU MDR offer lowest barrier to European institutional procurement. Target German industrial wellness bulk purchasing agreements where workplace ergonomics mandates create predictable volume commitments. Exploit white space in pressure-mapping sensor integration for corporate wellness programs, bypassing clinical certification overhead through wellness-positioning claims. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gel-infusion molding and phase-change material substrate production, favoring scaled chemical processors over mid-tier foam converters. Acquisition targets should display established quality management systems with dual FDA-EU MDR compliance, toll-manufacturing relationships with Bavarian processors, and locked hospital GPO contracts. Watch for inflection in ambulatory surgical facility unbundling velocity as signal for retail channel capture opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Streamlined EU MDR conformity assessment reduces time-to-market for Class I orthopedic supports. |
| Smart Textile Integration | Pressure-mapping sensor convergence with viscoelastic substrates enables real-time posture feedback premiums. |
| Backward Integration into Gel Substrates | In-house phase-change material production captures thermal-regulation value from aerospace suppliers. |
| Hospital System Partnership | Same-day fulfillment alliances with Texas and Florida ambulatory surgical facilities secure discharge kit volume. |
| Direct-to-Patient Subscription Launch | Post-surgical replenishment models bypass durable medical equipment intermediaries in US home recovery. |
Research Methodology
Initial hypotheses were tested against primary input from hospital materials management directors, biomedical engineers, GPO contracts managers, and polyurethane formulation chemists and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, German industrial wellness procurement records, and customs trade data for foam concentrate imports. Bottom-up volume modeling triangulated with top-down market sizing across product type, material substrate, application context, and end-user channel dimensions.
Variance-decomposition analysis isolated segment-level growth contributions across the projection horizon. Segmentation dimensions modeled include product format, material composition, certification tier, and geographic regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating polyurethane feedstock cost trajectories, REACH compliance cost inflation, and ambulatory surgical facility discharge velocity trends as industry-specific forecast inputs.
Underlying assumptions cover REACH restriction enforcement continuity, German workplace ergonomics mandate persistence, and US ambulatory surgical facility network expansion, with deviation risk concentrated in East Asian foam concentrate supply disruptions and FDA medical device reclassification actions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Watch Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
US Knife Sharpening Service Market