
 United States Gaming Peripherals Market | 2026-2036
United States Gaming Peripherals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gaming Peripherals Market Intelligence
The capital-intensity divergence between integrated manufacturers and assembly-reliant brands is unwinding competitive stability in the United States gaming peripherals sector. Logitech International S.A. leverages in-house sensor fabrication to sustain margin control across its wireless mouse portfolio. Razer Inc. anchors its position through proprietary mechanical switch technology and direct-to-consumer channel dominance. Corsair Components Inc. differentiates via vertical integration into custom keycap molding and enthusiast-grade power supply adjacencies.
United States gaming peripherals encompass input and output devices engineered for interactive entertainment, typically featuring sub-1ms polling rates, mechanical actuation points between 1.2mm and 4.0mm, and RF or Bluetooth Low Energy connectivity protocols purpose-built for latency-sensitive gameplay. These products serve commercial purposes spanning competitive esports, content creation, and immersive home entertainment. The keyboards segment leads volume through mechanical switch standardization and RGB ecosystem lock-in, while the wireless technology tier captures expanding margin pools as battery chemistry and RF stability improve. Headsets oriented toward streamers represent the fastest-growing end-user alignment, driven by integrated broadcast-quality microphone arrays and software-defined spatial audio processing.
The FCC governs wireless peripheral emissions under Part 15 rules, while the EPA's e-waste directives and California's SB-20 recycling standards shape material composition and end-of-life obligations for manufacturers selling into the United States. OSHA ergonomic guidelines additionally influence workstation peripheral design for professional gaming environments and esports training facilities. Stakeholders must monitor evolving right-to-repair legislation across multiple states and its potential to unlock aftermarket component ecosystems.
Market Dynamics
Wireless connectivity standardization is fragmenting competitive moats in the United States gaming peripherals sector as Bluetooth Low Energy and proprietary RF protocols converge on sub-1ms latency benchmarks. The FCC's Part 15 equipment authorization process now serves as the primary gating mechanism for product launch velocity, compressing development timelines for brands dependent on outsourced radio module integration.
Growth Catalysts
- Esports infrastructure buildout:Professional gaming venues in Texas and California are mandating tournament-grade peripheral specifications, creating pull-through demand for high-polling-rate input devices certified under ESL and BLAST Premier technical standards.
- Right-to-repair momentum:State-level legislation in New York and Minnesota is unlocking aftermarket component ecosystems for mechanical keyboards, extending product lifecycles and reducing replacement purchase friction.
- Spatial audio adoption:Streamer-oriented headsets with integrated broadcast microphone arrays are capturing share from standalone USB microphone setups, driven by OBS Studio and XSplit software integration requirements.
Market Restraints
- Lithium-polymer cost volatility:Battery chemistry price swings constrain margin stability for wireless mouse and headset portfolios, particularly for brands without captive cell supply agreements.
- Sensor supply concentration:PixArt Imaging and PixArt-derived optical sensor architectures dominate high-performance mouse positioning, creating single-source vulnerability for assembly-reliant peripheral brands.
- California SB-20 compliance burden:Extended producer responsibility mandates for e-waste recycling impose material composition constraints and end-of-life cost accruals that disadvantage smaller market entrants.
Strategic Opportunities
- Midwest esports venue penetration:Ohio and Illinois training facilities remain underpenetrated relative to coastal clusters, offering first-mover positioning for brands with localized distribution partnerships.
- Haptic feedback convergence:Integration of HD haptics from console controller architectures into PC peripherals represents unclaimed white space for immersive gameplay positioning.
- OSHA ergonomic guideline alignment:Professional team procurement specifications increasingly reference OSHA workstation standards, creating regulatory tailwind for adjustable-actuation keyboards and split ergonomic mouse designs.
Industry Challenges
- FCC Part 15 certification timelines:Wireless peripheral authorization delays of 12-16 weeks compress seasonal launch windows and inventory planning precision for holiday-driven categories.
- Mechanical switch IP complexity:Patent thickets surrounding low-profile and magnetic actuation switch architectures create licensing friction for brands developing proprietary keyboard mechanisms.
- RGB ecosystem integration:Proprietary lighting synchronization protocols fragment software development resources and create compatibility maintenance burdens across motherboard vendor partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gaming Peripherals Market |
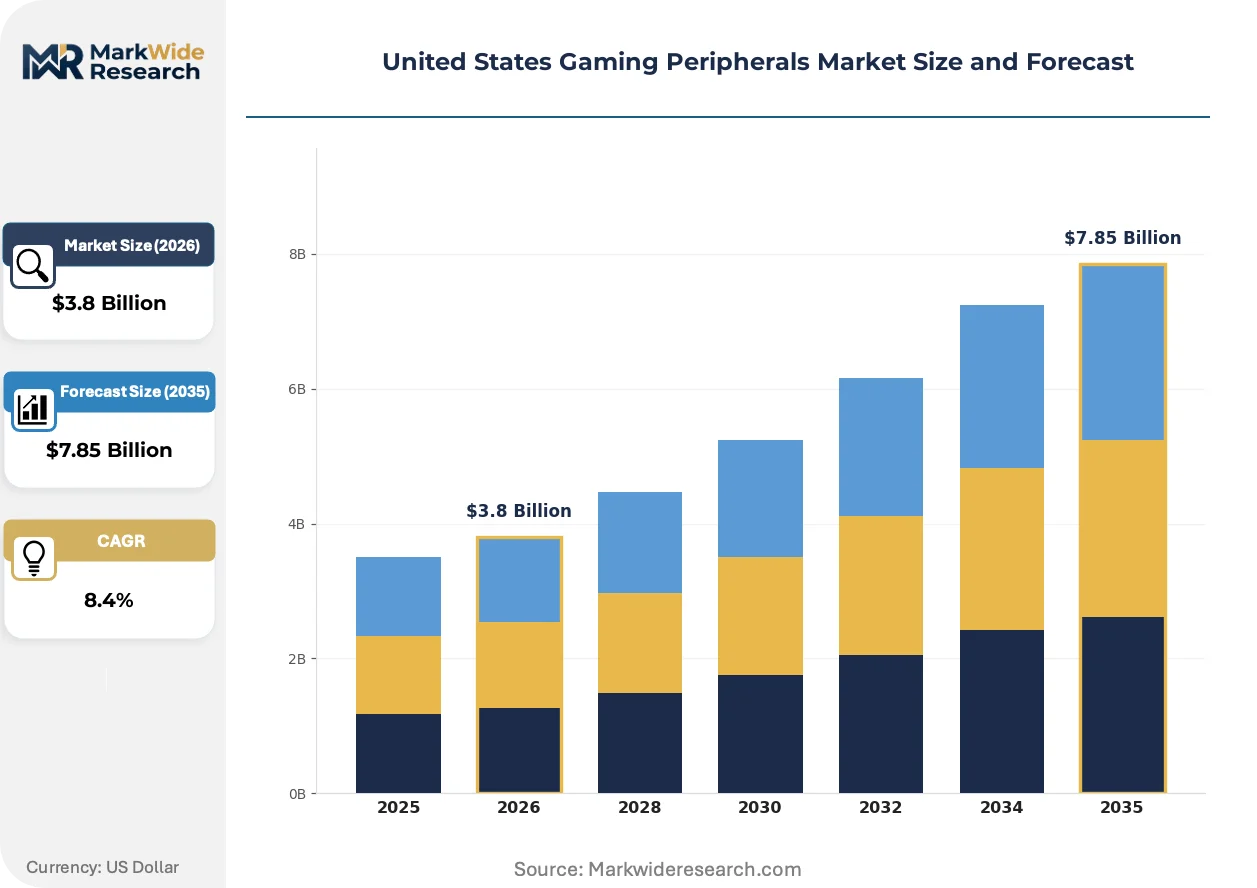
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keyboards, Mice, Headsets, Controllers Technology: Wired, Wireless, Bluetooth, Optical End User: Casual Gamers, Professional Gamers, Esports Teams, Streamers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Logitech International S.A., Razer Inc., Corsair Components Inc., Turtle Beach Corporation, SteelSeries, HyperX, Kingston Technology Corporation, PowerA, Performance Designed Products LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gaming Peripherals Market Strategic Shifts & Innovations
Latency reduction architectures are reshaping product development priorities across the United States gaming peripherals value chain. Component-level innovation in sensor polling, wireless transmission, and display synchronization is compressing the perceptible gap between input action and on-screen response, redefining performance tiering for competitive and enthusiast segments.
Optical-mechanical switch technology is fragmenting the mechanical keyboard market as brands deploy infrared beam interruption mechanisms to eliminate debounce delay and extend rated lifespan beyond 100 million actuations. Esports organizations and content creators are adopting these switches for tournament consistency and reduced maintenance overhead. The technology is fragmenting traditional Cherry MX-derived supply relationships and enabling in-house switch fabrication by vertically integrated peripheral brands.
California's SB-20 recycling standards and emerging right-to-repair legislation across multiple states are forcing material transparency and modular design into product development roadmaps. Manufacturers must now document rare earth content and establish take-back infrastructure, increasing compliance overhead but creating differentiation for brands with established circular supply programs. The keyboard and mouse segments face the most immediate redesign pressure due to higher unit volumes and shorter replacement cycles.
Direct-to-consumer channel expansion is displacing traditional retail distribution for enthusiast-grade peripherals, with brands building owned-commerce infrastructure and community-driven pre-order campaigns. Specialty retailers like Micro Center and B&H Photo retain relevance for hands-on evaluation, but Amazon and brand.com capture margin-rich repeat purchases. Texas and California metro areas show the strongest DTC penetration due to concentrated gaming demographics and same-day fulfillment infrastructure density.
United States Gaming Peripherals Market Segmentation
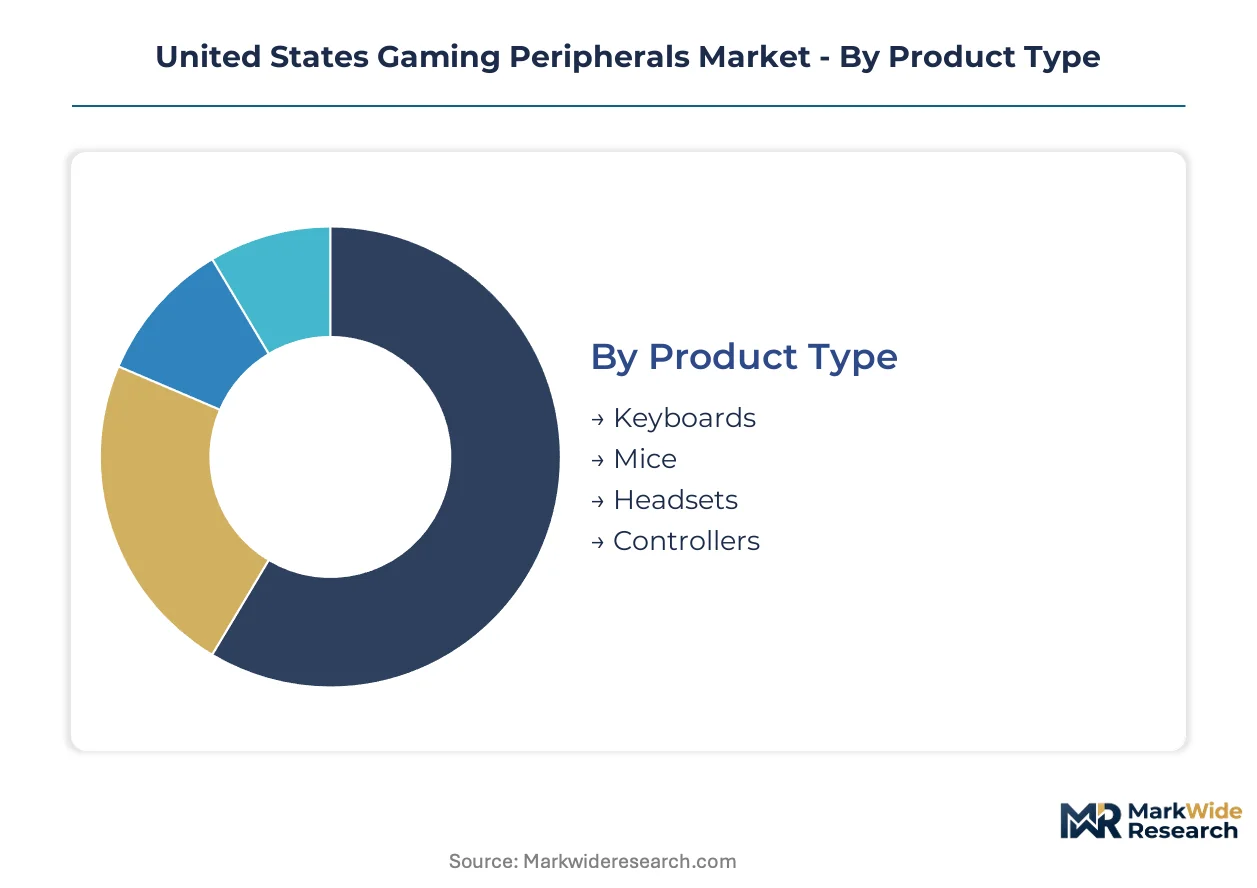
Segmentation in the United States gaming peripherals sector reveals how procurement specifications diverge between esports venues and home entertainment setups. Understanding these divides exposes where margin pools concentrate and where commodification pressures erode pricing power.
Product Type:
Keyboards face the strongest substitution threat from membrane alternatives in budget channels, while mechanical variants defend position through switch customization ecosystems.
- Keyboards:Mechanical switch architectures with actuation points between 1.2mm and 4.0mm anchor tournament specifications at Texas and California esports facilities. RGB ecosystem lock-in sustains repeat purchase cycles among enthusiast segments despite premium pricing.
- Mice:Sub-1ms polling rates and proprietary RF protocols differentiate competitive-grade units from office peripheral substitutes. PixArt-derived sensor supply concentration creates vulnerability for assembly-reliant brands seeking high-DPI positioning performance.
- Headsets:Spatial audio processing and broadcast-quality microphone arrays serve streamer workflows.
- Controllers:HD haptic integration from console architectures represents emerging white space for PC peripheral differentiation.
Keyboards retain volume leadership; headsets hold the steepest expansion curve.
Technology:
Cost tiering separates premium RF implementations from commodity Bluetooth alternatives, with latency benchmarks determining competitive viability across price bands.
- Wired:USB-C and braided cable constructions maintain tournament-grade reliability where RF interference risks disqualify wireless alternatives. California esports venues mandate wired redundancy for championship brackets.
- Wireless:Proprietary 2.4GHz protocols achieve sub-1ms latency parity with wired connections through dedicated USB receivers. Battery chemistry costs constrain margin stability for brands without captive cell agreements.
- Bluetooth:BLE 5.0 implementations serve mobile and cross-platform use cases with higher latency tolerance.
- Optical:Infrared beam interruption eliminates debounce delay in switch mechanisms.
Wired connections defend share in professional environments; wireless configurations are gaining share fastest among home enthusiasts.
End User:
Application intensity varies dramatically between casual entertainment and revenue-generating professional use, reshaping durability and service expectations.
- Casual Gamers:Price-sensitive procurement favors mid-tier mechanical keyboards and entry-level wireless mice with acceptable latency for single-player experiences.
- Professional Gamers:Individual competitors in Texas and California demand tournament-certified peripherals with standardized actuation forces for muscle memory consistency.
- Esports Teams:Bulk procurement contracts specify OSHA ergonomic alignment for training facility workstations.
- Streamers:Integrated audio-visual peripheral stacks reduce cable clutter and simplify OBS Studio workflow configuration.
Casual gamers retain volume leadership; streamers hold the steepest expansion curve.
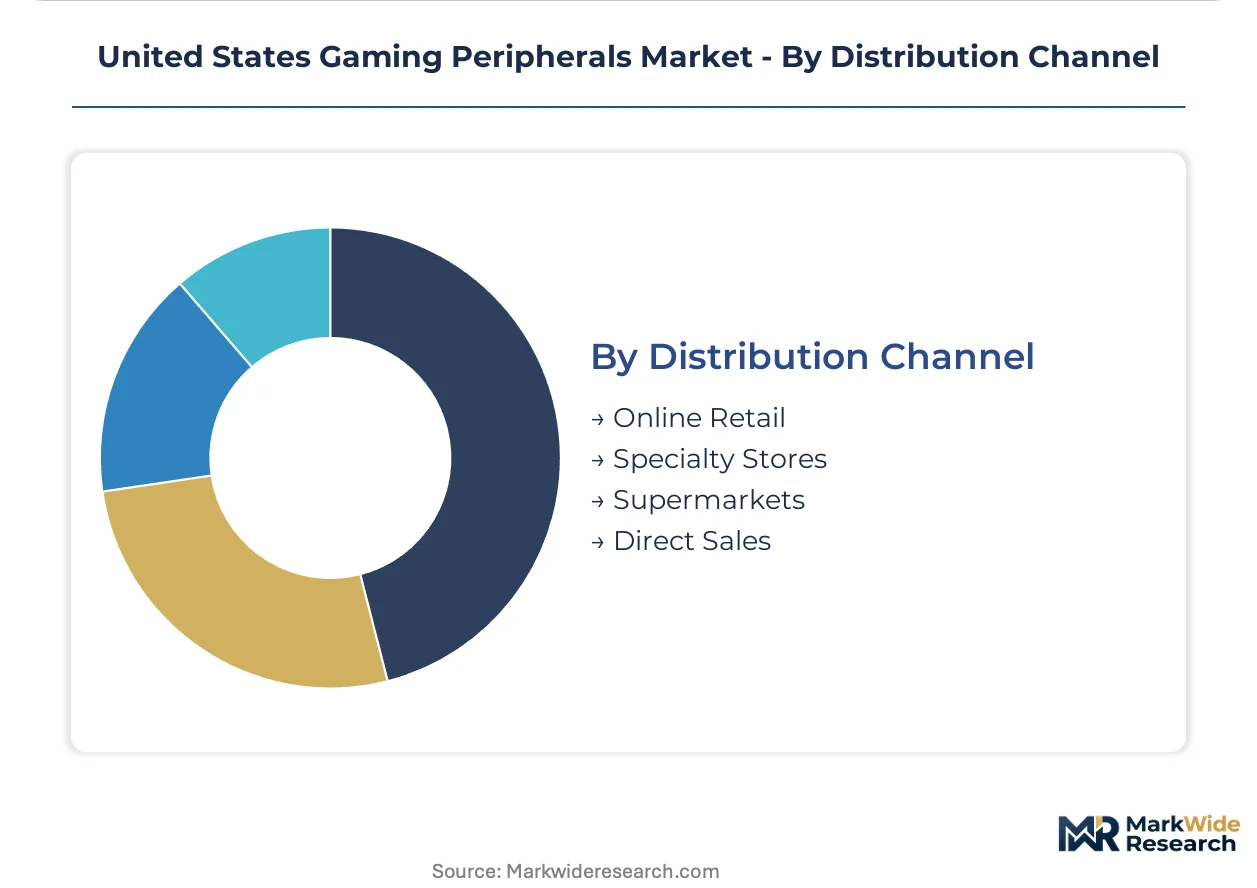
Distribution Channel:
Geography determines fulfillment infrastructure density, with same-day delivery availability concentrating DTC penetration in coastal metro clusters.
- Online Retail:Amazon and brand.com capture margin-rich repeat purchases through subscription replenishment programs for consumable components like mouse feet and keycap sets.
- Specialty Stores:Micro Center and B&H Photo retain relevance for hands-on switch testing and ergonomic evaluation before high-consideration purchases.
- Supermarkets:Big-box electronics sections serve emergency replacement demand with limited SKU depth.
- Direct Sales:Community-driven pre-order campaigns fund limited-edition product development for enthusiast segments.
Online retail retains volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the United States gaming peripherals landscape. Coastal metro buyers absorb premium pricing for tournament-certified equipment, while Midwest and Mountain West markets remain price-sensitive with longer replacement cycles.
California
Esports venue buildout in Los Angeles and San Francisco drives procurement of OSHA-aligned ergonomic workstations for professional training facilities. The state's SB-20 extended producer responsibility mandates force manufacturers to document rare earth content and maintain take-back infrastructure. Santa Monica and Irvine host concentrated gaming studio clusters where streamer-oriented headset specifications shape product development priorities.
Texas
Dallas and Austin anchor the nation's densest esports infrastructure outside California, with tournament-grade peripheral specifications mandated at championship venues. State-level franchise tax incentives support peripheral brand regional headquarters and distribution center placement. Houston's tech corridor generates B2B demand from energy sector firms outfitting employee gaming lounges for recruitment and retention.
New York Metro
Right-to-repair legislation enacted in New York State unlocks aftermarket mechanical keyboard component ecosystems, extending product lifecycles and reducing replacement friction. Manhattan and Brooklyn content creator studios drive integrated audio-visual peripheral stack adoption for broadcast workflows. The state's e-waste recycling directives impose material composition constraints that favor established brands with circular supply programs.
Illinois and Ohio
Chicago and Columbus training facilities remain underpenetrated relative to coastal clusters, offering first-mover positioning for brands with localized distribution partnerships. Midwest price sensitivity favors mid-tier mechanical keyboards and entry-level wireless mice over premium tournament-grade equipment. Cleveland's manufacturing heritage supports assembly operations for brands seeking to reduce coastal logistics costs.
Pacific Northwest
Seattle and Portland gaming demographics concentrate around software developer and tech workforce segments with high disposable income and performance-oriented procurement preferences. Washington state's clean energy mandates influence peripheral brand data center and fulfillment infrastructure location decisions. The region's strong environmental consciousness amplifies demand for repairable, modular designs compliant with emerging circular economy standards.
United States Gaming Peripherals Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the United States gaming peripherals sector. The market structure consolidates around three tiers: integrated manufacturers with captive sensor and switch fabrication, assembly-reliant brands dependent on outsourced radio modules and optical components, and private-label distributors serving price-sensitive mass retail channels. Dominant competitive moves include direct-to-consumer channel expansion to capture margin-rich repeat purchases, and strategic partnerships with esports leagues for tournament certification lock-in.
Within the integrated manufacturing tier, Logitech International S.A. and Razer Inc. exemplify divergent approaches to vertical control. Logitech anchors Swiss-origin engineering credibility through in-house production capabilities, while Razer represents Singapore-US cross-border positioning with direct-to-consumer channel dominance. Corsair Components Inc. sits within the enthusiast-grade specialist archetype, with Fremont, California headquarters signaling West Coast tech cluster alignment. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Logitech International S.A. |
| Razer Inc. |
| Corsair Components Inc. |
| Turtle Beach Corporation |
| SteelSeries |
| HyperX |
| Kingston Technology Corporation |
| PowerA |
| Performance Designed Products LLC |
| Others |
Cost & Logistics Intelligence
Optical-mechanical switch substitution for traditional Cherry MX-derived mechanisms is redrawing component sourcing maps toward Taiwan and mainland China while compressing keyboard margin structures at the mid-tier. This input transition simultaneously elevates in-house fabrication premiums for integrated brands and erodes pricing power for assembly-reliant competitors dependent on outsourced switch supply.
Pricing Analysis
After-market consumable revenue from keycap sets, mouse feet, and cable replacements drives lifetime value capture for brands with strong direct-to-consumer infrastructure. Three-tier pricing structure across premium tournament-certified, standard enthusiast-grade, and economy membrane alternatives stratifies the market, with certification under ESL and BLAST Premier standards commanding substantial premiums. Pricing pressure stems from lithium-polymer battery cost volatility constraining wireless peripheral margins. Casual gamers exhibit highest price sensitivity, while esports teams and professional competitors absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes create geographic disadvantage for Midwest distribution relative to California and Texas coastal clusters. Optical sensor fabrication concentrates in Taiwan and China, while mechanical switch production centers on China and Germany. Rare earth magnet and lithium-cell dependencies tether wireless peripheral margins to commodity price swings. Single-source vulnerability in PixArt-derived sensor architectures threatens assembly-reliant brands. Distribution runs through Amazon and brand.com for repeat purchases, with Micro Center and B&H Photo serving evaluation-intensive initial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
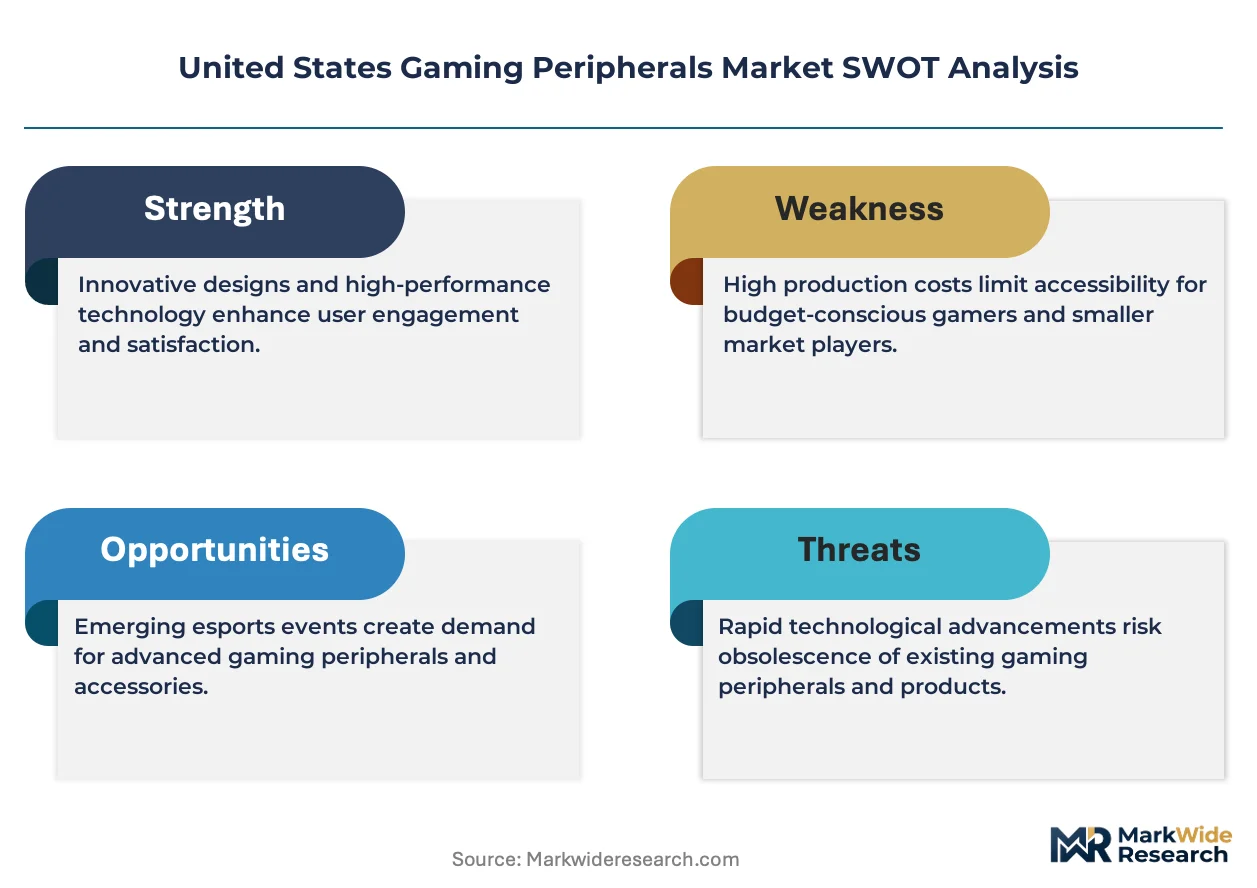
The United States gaming peripherals market sits in early-cycle expansion, with streamer-oriented headset adoption and right-to-repair legislation unlocking aftermarket revenue pools that extend product lifecycles and deepen customer relationships.
For Market Incumbents: Secure captive supply agreements for optical sensor and lithium-polymer cell inputs to insulate margin structures from single-source concentration risks. Defend tournament certification lock-ins with ESL and BLAST Premier through exclusive hardware partnerships that raise switching costs for professional teams. Invest in OSHA ergonomic guideline alignment for training facility procurement specifications, creating regulatory-tailwind differentiation against assembly-reliant challengers.
For New Entrants and Emerging Players: Differentiate on haptic feedback integration from console controller architectures into PC peripherals, an unclaimed white space for immersive gameplay positioning. Target Ohio and Illinois esports training facilities, which remain underpenetrated relative to coastal clusters and favor localized distribution partnerships over brand recognition. Pursue community-driven pre-order campaigns through owned-commerce infrastructure to fund limited-edition product development without traditional retail slotting fee burdens.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated specialists with in-house sensor or switch fabrication capabilities over assembly-reliant brands exposed to PixArt supply concentration. Long-term viability hinges on circular supply program establishment ahead of California SB-20 compliance expansion and emerging right-to-repair mandates across multiple states. Watch FCC Part 15 certification timeline compression as inflection indicator for brands capable of accelerating seasonal launch velocity through integrated radio module development.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Captures margin-rich repeat purchases through subscription replenishment programs for consumable components. |
| Proprietary RF Protocol Development | Achieves sub-1ms latency parity with wired connections while reducing FCC certification dependency on outsourced modules. |
| Optical-Mechanical Switch Integration | Eliminates debounce delay and extends rated lifespan beyond 100 million actuations for tournament consistency. |
| OSHA Ergonomic Certification Alignment | Unlocks professional team procurement specifications referencing workstation standards for training facilities. |
| Circular Supply Program Establishment | Creates differentiation under California SB-20 extended producer responsibility mandates for e-waste recycling. |
Research Approach
The analysis maps keyboards, mice, headsets, and controllers as product categories, each validated through product managers at peripheral brands, esports team equipment coordinators, and specialty retail buyers. Primary interviews with FCC compliance officers and California recycling program administrators supplemented secondary validation through SEC 10-K filings, FCC equipment authorization databases, and state legislative tracking systems. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from distribution channel revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, connectivity technology, end-user intensity, and distribution channel, with regional regulatory clusters capturing FCC, EPA, and state-level right-to-repair variations. CAGRs derive from historical elasticity patterns applied to esports infrastructure buildout trajectories and streamer demographic expansion curves, with battery chemistry cost indices and sensor supply availability serving as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained esports venue investment and stable lithium-polymer supply; material deviation in either would warrant model refresh. Forecasts embed FCC regulatory continuity and California SB-20 enforcement intensity as base-case parameters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Adult Sex Dolls Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Headphones Market
Consumer Electronics
Chromebook Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Europe Mobile Phone Accessories Market