
 Dive Computer Market | 2026-2036
Dive Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Dive Computer Market Outlook
Technical divers and commercial dive teams is collapsing the historical dominance of casual recreational buyers in equipment procurement. Shearwater Research leverages advanced decompression algorithm development to dominate the technical segment. Garmin Ltd. extends its GPS-enabled wearable architecture into wrist-mounted dive instruments for multi-sport consumers. Suunto anchors Nordic brand equity across European military and professional training channels.
A dive computer is an electronic instrument that calculates real-time depth, time, and decompression status through integrated pressure sensors and Bühlmann or VPM-B algorithm processing, enabling divers to manage nitrogen absorption and avoid decompression sickness. Recreational wrist-mounted units with Bluetooth logbook transfer represent the largest volume tier, while technical console systems with air integration command the deepest margin pools. GPS-enabled digital units are gaining fastest among research organizations conducting underwater survey work, whereas analog backup devices persist as mandatory secondary instruments in commercial diving regulations.
EN 13319 harmonization across EU member states and ISO 6425 depth gauge accuracy standards shape product certification timelines and market access conditions for manufacturers. The US Coast Guard and OSHA commercial diving regulations enforce redundant instrumentation requirements that sustain demand for multi-computer configurations. Stakeholders must monitor algorithm validation protocols and wireless air-integration interoperability standards as the primary determinants of product differentiation and liability exposure.
Market Dynamics
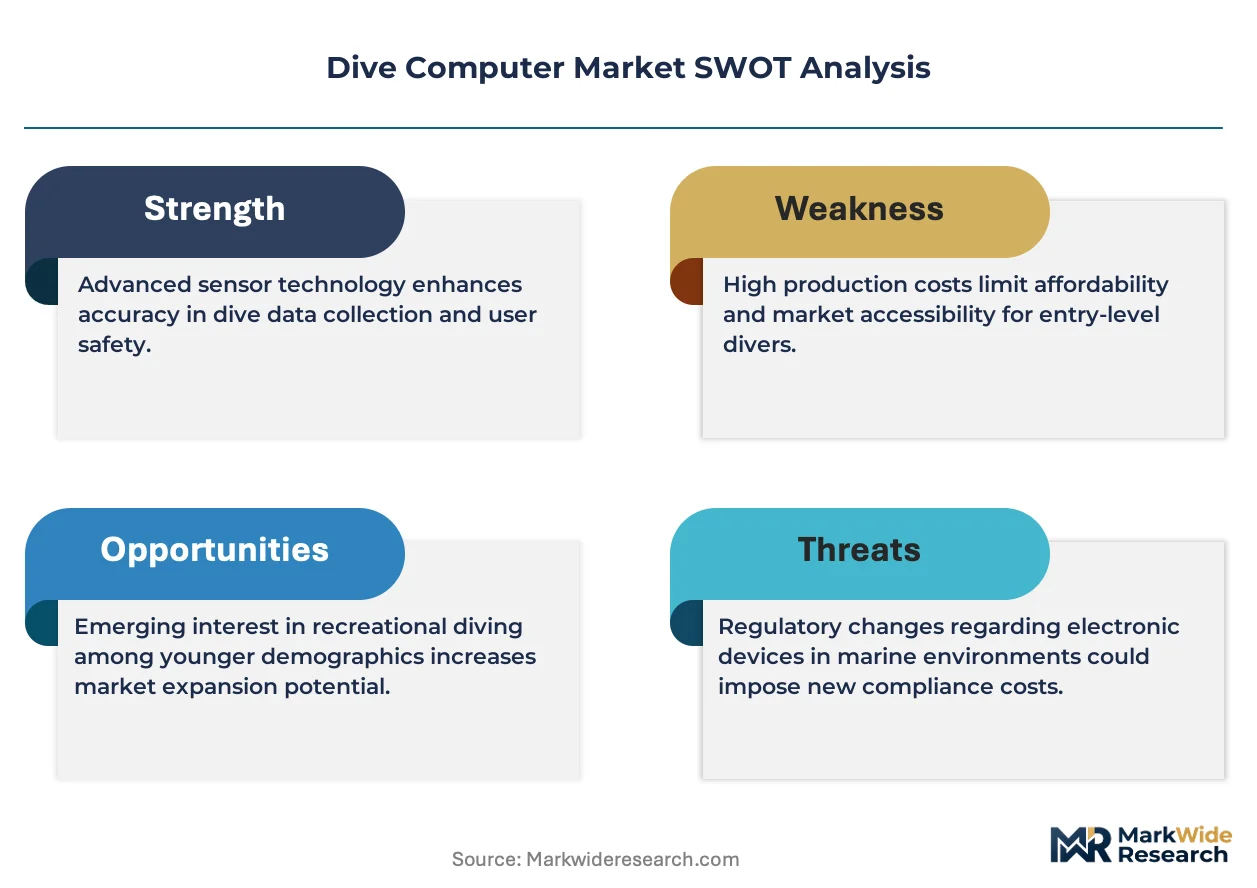
Technical diving certification growth is compressing recreational equipment margins while forcing manufacturers toward Bühlmann ZHL-16C and VPM-B algorithm specialization. This buyer archetype rotation demands redundant gas integration, trimix support, and CCR compatibility that wrist-mounted consumer units cannot satisfy.
Growth Catalysts
- EN 13319 harmonization:The European standardization mandate accelerates product approval cycles across EU member states, reducing certification duplication costs for manufacturers targeting professional training centers.
- Liveaboard fleet renewal:Thailand's charter operator consolidation is standardizing on air-integrated console systems with wireless tank pressure monitoring, creating concentrated procurement volumes.
- CCR adoption curves:Closed-circuit rebreather training expansion is driving demand for multi-sensor dive computers capable of real-time partial pressure oxygen monitoring and automated setpoint control.
Market Restraints
- MEMS pressure sensor supply:Japanese and German sensor foundries face capacity constraints, creating 14-18 week lead times for depth-rated transducers essential to all computer categories.
- Lithium-thionyl chloride volatility:Primary battery chemistry price swings and hazardous material shipping restrictions inflate working capital requirements for manufacturers maintaining regional battery inventories.
- ISO 6425 calibration overhead:Depth gauge accuracy certification demands third-party laboratory validation that adds 8-12 weeks to product launch timelines without corresponding price recovery mechanisms.
Strategic Opportunities
- Indonesian archipelago expansion:Raja Ampat and Komodo liveaboard route development outpaces equipment supplier presence, creating first-mover positioning for technical-focused distributors.
- Archaeological survey digitization:Mediterranean and Caribbean heritage agencies are mandating GPS-logged dive profiles for permit compliance, opening institutional procurement channels.
- Bluetooth LE ecosystem convergence:Integration with smartphone logbook applications and cloud-based decompression planning platforms is creating subscription revenue attachment opportunities alongside hardware sales.
Industry Challenges
- Firmware validation cycles:Algorithm updates require extensive hyperbaric chamber testing and liability review, compressing software release velocity relative to consumer electronics norms.
- Multi-standard compliance engineering:Simultaneous EN 13319, ISO 6425, and OSHA commercial diving certification demands parallel documentation tracks that strain smaller engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dive Computer Market |
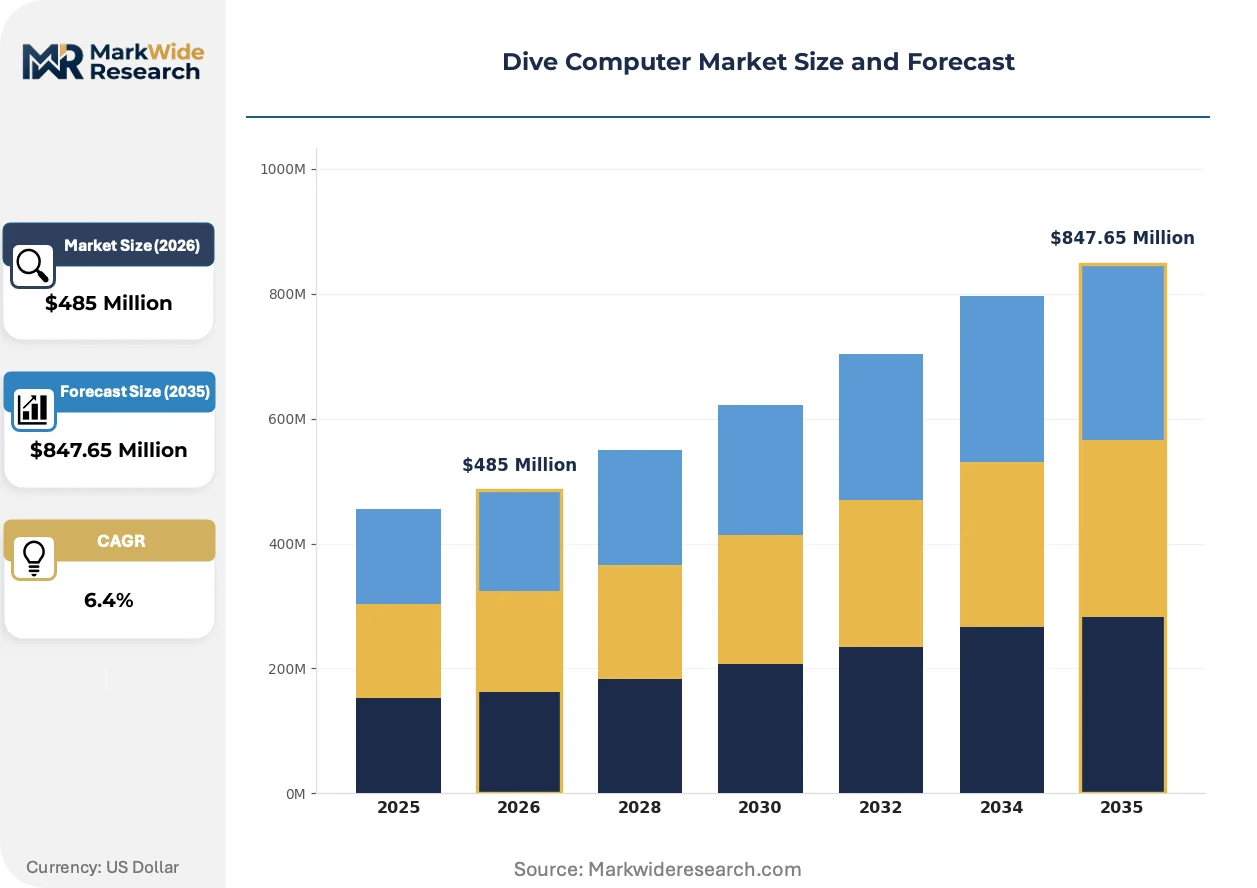
| Market Size in 2026 | $485 Million |
| Market Size in 2035 | $847.65 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recreational, Technical, Wrist-mounted, Console Technology: Digital, Analog, Bluetooth, GPS End User: Divers, Instructors, Commercial Teams, Research Organizations Feature: Air Integration, Nitrox Compatibility, Dive Planning, Safety Alarms |
| Companies Covered | Shearwater Research, Garmin Ltd., Aqua Lung International, Johnson Outdoors, Cressi, Mares, Suunto, Tabata USA, Oceanic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dive Computer Market Strategic Shifts
Algorithm sophistication and sensor fusion architectures are redefining product tier boundaries. Manufacturers now compete on decompression model transparency, wireless ecosystem integration, and modular upgrade pathways rather than depth rating alone.
OLED display technology is miniaturizing. These high-contrast screens enable sunlight-readable dive data presentation at depths exceeding 100 meters where traditional LCD contrast degrades. Technical divers operating in low-visibility cave and wreck environments are adopting OLED-equipped wrist units faster than recreational users, compressing the feature gap between premium consumer and entry-level technical categories.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant gas alternatives in hyperbaric chamber operations used for dive computer validation testing. Chamber operators face retrofit capital requirements that concentrate certification capacity among larger facilities with compliance resources. This regulatory pressure most affects small-batch technical computer manufacturers dependent on external validation services.
Research organizations are consolidating dive computer procurement through centralized institutional frameworks rather than individual researcher purchases. University marine science departments and government survey agencies now mandate standardized fleet configurations with centralized data management platforms. This pattern is most visible in Australian and Mediterranean coastal monitoring programs where interoperability requirements override individual feature preferences.
Dive Computer Market Segmentation
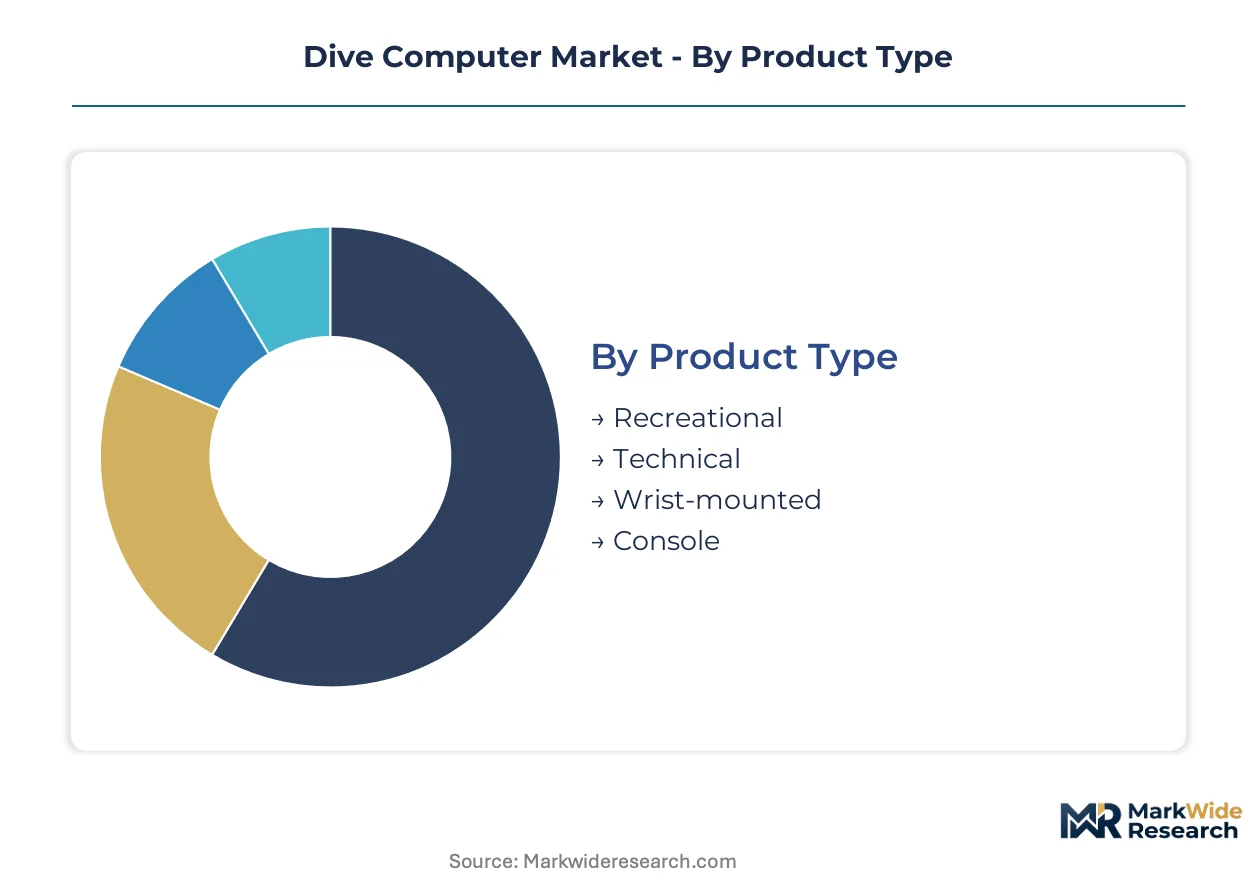
Dive computer segmentation tracks how buyer archetypes and use cases fragment across decompression algorithm requirements, sensor integration depth, and regulatory compliance tiers. Manufacturers must align product architectures with distinct certification standards and operational environments rather than pursuing universal designs.
Product Type:
Substitute pressure concentrates on recreational wrist-mounted units as smartphone dive logging apps and rental fleet standardization erode individual ownership economics. Technical and console systems face weaker substitution threats due to mandatory redundancy requirements and CCR integration complexity.
- Recreational:Entry-level wrist units with Bühlmann ZHL-16C algorithms and Bluetooth logbook transfer dominate volume sales through resort retail channels. Thailand's liveaboard fleet renewal is standardizing on bulk procurement of air-integrated recreational units with wireless tank monitoring, compressing margins for standalone depth-time instruments.
- Technical:Multi-sensor consoles with trimix support, CCR setpoint control, and redundant gas integration serve cave and wreck penetration divers. Shearwater Research dominates this tier through VPM-B algorithm specialization and real-time partial pressure oxygen monitoring capabilities that consumer units cannot replicate.
- Wrist-mounted:Compact form factors with OLED displays and GPS surface positioning appeal to multi-sport consumers extending Garmin wearable ecosystems underwater.
- Console:Bulkhead-integrated systems with hose-connected pressure sensors persist in commercial diving operations where OSHA mandates redundant instrumentation and physical durability overrides miniaturization preferences.
Recreational retains volume leadership; technical holds the steepest expansion curve as certification growth outpaces casual cruise-line demand recovery.
Technology:
Cost tier stratification separates validated digital platforms from legacy analog backups, with wireless connectivity modules commanding premium positioning in institutional procurement frameworks.
- Digital:Microprocessor-driven decompression calculation with integrated pressure transducers and algorithm-selectable conservatism settings. Australian and Mediterranean marine science departments mandate GPS-logged digital profiles for research permit compliance, consolidating fleet standardization around centralized data management platforms.
- Bluetooth:Low-energy wireless protocols enabling smartphone logbook synchronization and cloud-based dive planning subscription attachments. This connectivity layer is gaining fastest among research organizations requiring seamless data pipeline integration from field operations to archival systems.
- Analog:Mechanical depth gauges and timer combinations serve as mandatory secondary instruments under US Coast Guard commercial diving regulations where electronic failure modes must have mechanical backup.
- GPS:Surface positioning and dive site mapping capabilities integrated into wrist-mounted architectures for underwater survey documentation and archaeological site logging.
Digital platforms anchor installed base economics; Bluetooth connectivity is climbing the fastest as subscription revenue models attach to hardware sales.
End User:
Customer type maturity varies sharply, with commercial teams and research organizations consolidating procurement through institutional frameworks while individual divers fragment across experience levels.
- Divers:Individual recreational and technical certification holders purchasing through retail and direct channels. Indonesian archipelago route development is outpacing equipment supplier presence, creating first-mover positioning for distributors targeting independent technical divers in Raja Ampat and Komodo liveaboard corridors.
- Commercial Teams:OSHA-regulated professional diving operations requiring redundant multi-computer configurations and documented maintenance protocols. This segment demands EN 13319 and ISO 6425 dual certification with third-party calibration records.
- Instructors:Training center staff and certification agency affiliates standardizing on console systems with student-visible displays and simplified menu architectures for demonstration purposes.
- Research Organizations:University marine science departments and government survey agencies mandating interoperable fleet configurations with centralized profile management and institutional data repositories.
Divers retain volume leadership; research organizations are gaining share fastest through centralized procurement frameworks overriding individual feature preferences.
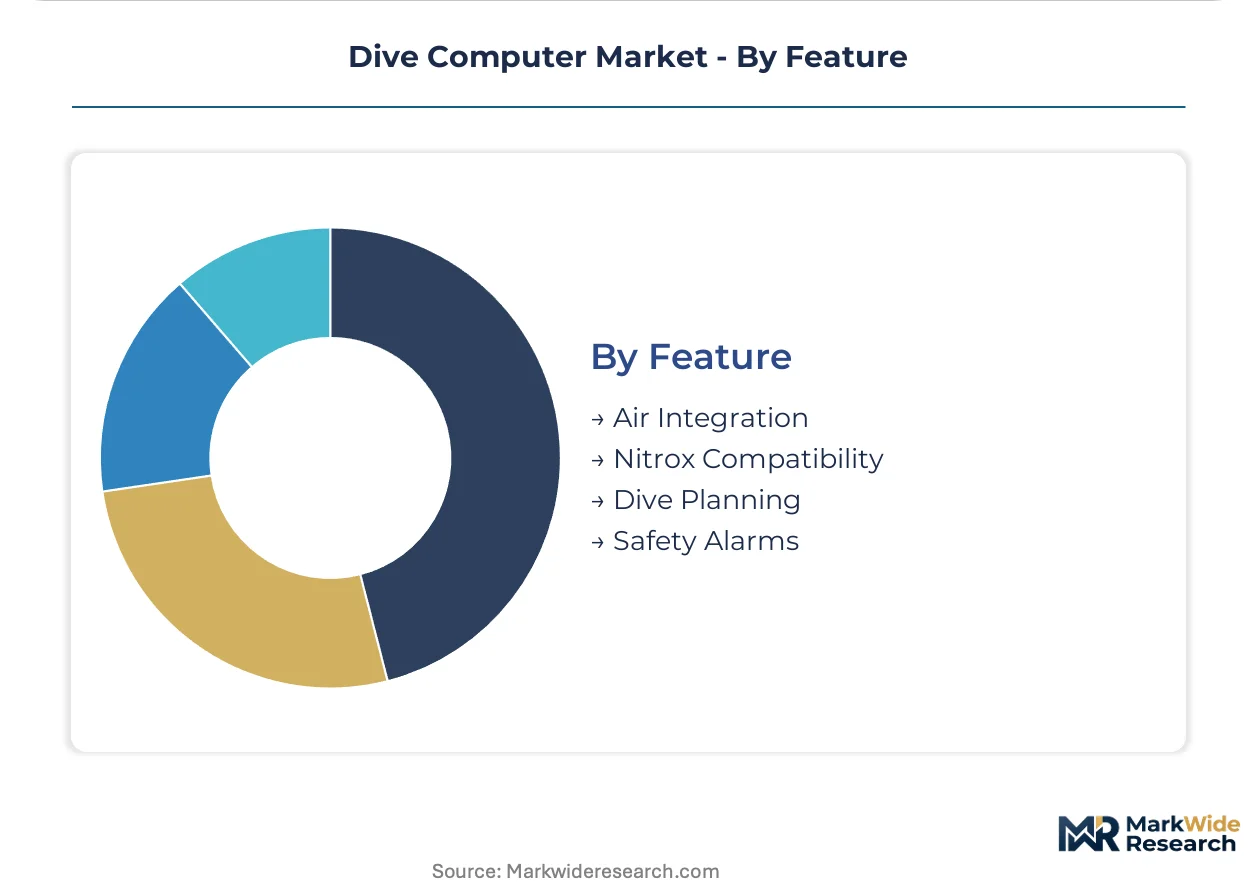
Feature:
Margin concentration tracks certification-grade functionality, with air integration and nitrox support commanding premium pricing while basic safety alarms commoditize across entry tiers.
- Air Integration:Wireless tank pressure monitoring and gas consumption rate calculation enabling real-time remaining bottom time estimation. Thailand's charter operator consolidation is driving concentrated procurement of console systems with this feature as fleet standardization reduces training complexity across rotating dive staff.
- Nitrox Compatibility:Oxygen fraction programming and maximum operating depth calculation for enriched air diving. CCR adoption curves are accelerating demand for multi-sensor computers capable of automated setpoint control and real-time partial pressure monitoring beyond recreational nitrox boundaries.
- Dive Planning:Pre-dive decompression schedule simulation and surface interval optimization tools integrated into desktop and mobile companion applications.
- Safety Alarms:Ascent rate violation, no-decompression limit proximity, and mandatory stop alerts standard across all certification tiers with limited differentiation potential.
Air integration retains volume leadership; nitrox compatibility holds the steepest expansion trajectory as technical certification pipelines deepen oxygen-enriched and closed-circuit training penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dive equipment manufacturers export precision-engineered console systems to Thailand's liveaboard charter operators, establishing a trade corridor that channels European technical specifications into Southeast Asian fleet renewal programs.
United States
Commercial diving operations along the Gulf Coast sustain demand for redundant multi-computer configurations. OSHA commercial diving regulations mandate documented maintenance protocols and backup instrumentation that inflate procurement budgets for offshore construction contractors. Houston anchors the professional training infrastructure where certification agencies standardize on console systems with student-visible displays.
Germany
Technical diving certification growth in Bavaria and North Rhine-Westphalia compresses recreational equipment margins. EN 13319 harmonization accelerates product approval cycles across EU member states, reducing certification duplication costs for manufacturers targeting professional training centers. Stuttgart's precision sensor foundries face capacity constraints for depth-rated MEMS transducers.
Thailand
Liveaboard fleet renewal in the Andaman Sea and Gulf of Thailand concentrates procurement volumes for air-integrated console systems. The country's tourism authority coordinates charter operator consolidation that standardizes wireless tank pressure monitoring across rotating dive staff. Phuket's marine equipment distributors capture first-mover positioning in fleet standardization contracts.
Australia
University marine science departments mandate GPS-logged digital profiles for research permit compliance. The country's heritage agencies require standardized fleet configurations with centralized data management platforms for underwater survey documentation. Sydney's coastal monitoring programs consolidate procurement through institutional frameworks overriding individual feature preferences.
Indonesia
Raja Ampat and Komodo liveaboard route development outpaces equipment supplier presence among independent technical divers. The archipelago's expanding charter corridors create distribution gaps that regional distributors target with CCR-compatible multi-sensor systems. Bali's dive training centers anchor the certification pipeline feeding advanced technical penetration diving demand.
Dive Computer Market Competitive Environment
Listed leaders compete with private specialists across algorithm development and sensor integration dimensions. The vendor base stratifies into three tiers: diversified wearable technology conglomerates, dedicated diving instrumentation specialists, and regional equipment distributors with captive training relationships. Strategic archetypes include algorithm-centric technical specialists, GPS-enabled multi-sport extenders, and Nordic military-channel anchors. Competitive moves concentrate on wireless ecosystem convergence and firmware validation capacity expansion.
Within the technical-specialist tier, Shearwater Research and Suunto exemplify divergent positioning strategies. Garmin Ltd. occupies the multi-sport extender archetype, leveraging wearable ecosystem architecture into wrist-mounted instruments. These three anchors represent the competitive vectors—algorithm transparency, GPS integration, and military-channel brand equity—that manufacturers must navigate to defend positioning against rental fleet standardization and smartphone logging substitution threats.
| Leading Market Players |
|---|
| Shearwater Research |
| Garmin Ltd. |
| Aqua Lung International |
| Johnson Outdoors |
| Cressi |
| Mares |
| Suunto |
| Tabata USA |
| Oceanic |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Thailand's liveaboard charter operators and German console manufacturers lock in multi-year supply access while stabilizing unit pricing across fleet renewal cycles. This contractual architecture insulates procurement budgets from lithium-thionyl chloride battery volatility and MEMS sensor foundry capacity constraints.
Pricing Analysis
Current-generation OLED-equipped technical wrist units command substantial premiums over prior-generation LCD-based recreational models, while next-generation CCR-integrated consoles with multi-sensor architectures are entering at elevated price points. Three-tier pricing structure across premium technical, standard recreational, and economy rental tiers reflects algorithm sophistication and certification grade differentiation. Price erosion runs through entry-level recreational units as smartphone dive logging apps compress individual ownership economics. Commercial diving operations demonstrate lowest price sensitivity due to OSHA-mandated redundancy requirements, whereas independent recreational divers exhibit highest sensitivity to replacement cycles.
Supply Chain Analysis
Strategic stockpile preferences dominate among manufacturers buffering against Japanese and German MEMS pressure sensor foundry capacity constraints and lithium-thionyl chloride battery chemistry volatility. Component sourcing concentrates in Germany for precision-engineered console systems, Japan for depth-rated transducers, and Thailand for final assembly serving Southeast Asian fleet operators. Raw material dependencies encompass rare earth elements for OLED displays, specialized polymers for pressure housings, and precision-machined titanium for technical-grade wrist units. Single-source vulnerability in sensor foundry capacity creates procurement risk concentration. Distribution runs through marine equipment distributors with captive training center relationships in Phuket, Houston, and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dive computer market dynamics constitute a defensive-moat story anchored in regulatory entrenchment, where EN 13319 and ISO 6425 certification timelines create structural barriers that extend incumbent runway against substitution threats.
For Market Incumbents: Consolidate algorithm validation capacity through captive hyperbaric chamber partnerships or exclusive certification facility relationships, neutralizing the firmware validation cycle bottleneck that constrains smaller competitors. Deepen backward integration into MEMS pressure sensor sourcing through strategic offtake agreements with Stuttgart foundries, securing supply priority as capacity constraints intensify across technical and commercial segments.
For New Entrants and Emerging Players: Lead with Bluetooth LE ecosystem convergence as the primary differentiation vector, attaching subscription revenue models to hardware sales through cloud-based decompression planning platforms. Target Indonesian archipelago route development as the most penetrable geography, where Raja Ampat and Komodo liveaboard corridor expansion outpaces established supplier presence among independent technical divers.
For Investors and Strategic Acquirers: The market sits at a technical-diver archetype rotation phase that favors algorithm-specialist manufacturers with VPM-B and Bühlmann ZHL-16C development capabilities over recreational-volume commoditizers. Acquisition targets should demonstrate firmware validation infrastructure and institutional procurement channel access. Watch CCR training certification growth rates as the inflection indicator signaling sustained premium-tier demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Validation Infrastructure Expansion | Captive hyperbaric chamber capacity compresses firmware release cycles relative to competitors dependent on external EU F-Gas Regulation-compliant facilities. |
| Bluetooth LE Ecosystem Integration | Cloud-based logbook synchronization creates recurring subscription revenue attachment alongside hardware sales through smartphone application partnerships. |
| Indonesian Distribution Network Buildout | First-mover positioning in Raja Ampat and Komodo corridors captures technical diver procurement ahead of established supplier market entry. |
| MEMS Sensor Foundry Partnership | Strategic offtake agreements with Japanese and German transducer manufacturers secure depth-rated component supply priority during capacity constraints. |
| Institutional Procurement Framework Certification | Australian and Mediterranean research agency fleet standardization mandates create sticky demand through centralized data management platform integration. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with dive equipment manufacturers, technical training center operators, commercial diving contractors, and marine science research coordinators; and secondary validation through EN 13319 regulatory filings, ISO 6425 certification records, OSHA commercial diving regulation documentation, and customs trade data for precision sensor imports. Bottom-up triangulation across product category shipment estimates and top-down cross-checks against liveaboard fleet procurement disclosures ensured analytical coherence.
Across the projection horizon, the analytical framework modeled segmentation dimensions encompassing product type tier, decompression algorithm requirement, sensor integration depth, end-user archetype maturity, and regional regulatory compliance cluster. CAGRs were derived through algorithm adoption curve analysis and certification pipeline growth trajectories. Industry-specific forecast inputs incorporated CCR training expansion rates and fleet renewal procurement cycle timing.
Underlying assumptions cover MEMS foundry capacity normalization, lithium-thionyl chloride shipping restriction stability, and EN 13319 harmonization maintenance across EU member states, with deviation risk concentrated in sensor supply chain disruptions and regulatory calibration timeline extensions. Revision becomes warranted when technical certification growth diverges materially from recreational demand compression baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Tablet Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Earbuds Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Ereader Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Streaming Devices Market