
 High-End Audiophile Speakers Market | 2026-2036
High-End Audiophile Speakers Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Audiophile Speakers Market Insights
The EU Green Deal is decoupling high-end speaker manufacturing from conventional material-intensive processes, compelling suppliers to reformulate cabinet compositions and amplifier topologies. Focal leverages its in-house driver manufacturing in Saint-Étienne to control acoustic consistency across beryllium and flax-cone platforms. Bowers & Wilkins sustains brand cachet through dedicated research facilities in Worthing, where diamond-dome tweeter development anchors its 800 Series prestige tier. Dynaudio competes from its Danish headquarters with emphasis on MSP magnesium silicate polymer drivers and room-correction software integration.
High-end audiophile speakers are precision electroacoustic transducer systems engineered to reproduce recorded sound with minimal distortion, typically employing multi-way driver arrays with dedicated crossover networks and enclosure designs tuned to eliminate cabinet resonance below 200 Hz. Floor-standing configurations occupy the dominant value position due to their capacity for extended bass response and full-spectrum output without subwoofer supplementation, while wireless technology variants are expanding fastest as amplifier integration eliminates external component complexity. Music studios represent a concentrated margin pool where flat-frequency-response monitors command substantial premiums for mastering and mixing applications.
REACH chemical restrictions govern driver-adhesive formulations and cabinet finishes across European supply chains, while CE marking mandates electromagnetic compatibility for active and wireless configurations. The FCC in the United States regulates radio-frequency emissions from Bluetooth and Wi-Fi enabled models, creating divergent testing requirements for transatlantic product lines. Stakeholders must monitor evolving ecodesign thresholds and wireless protocol standards to preserve market access and justify replacement cycles among discerning buyers.
Market Dynamics
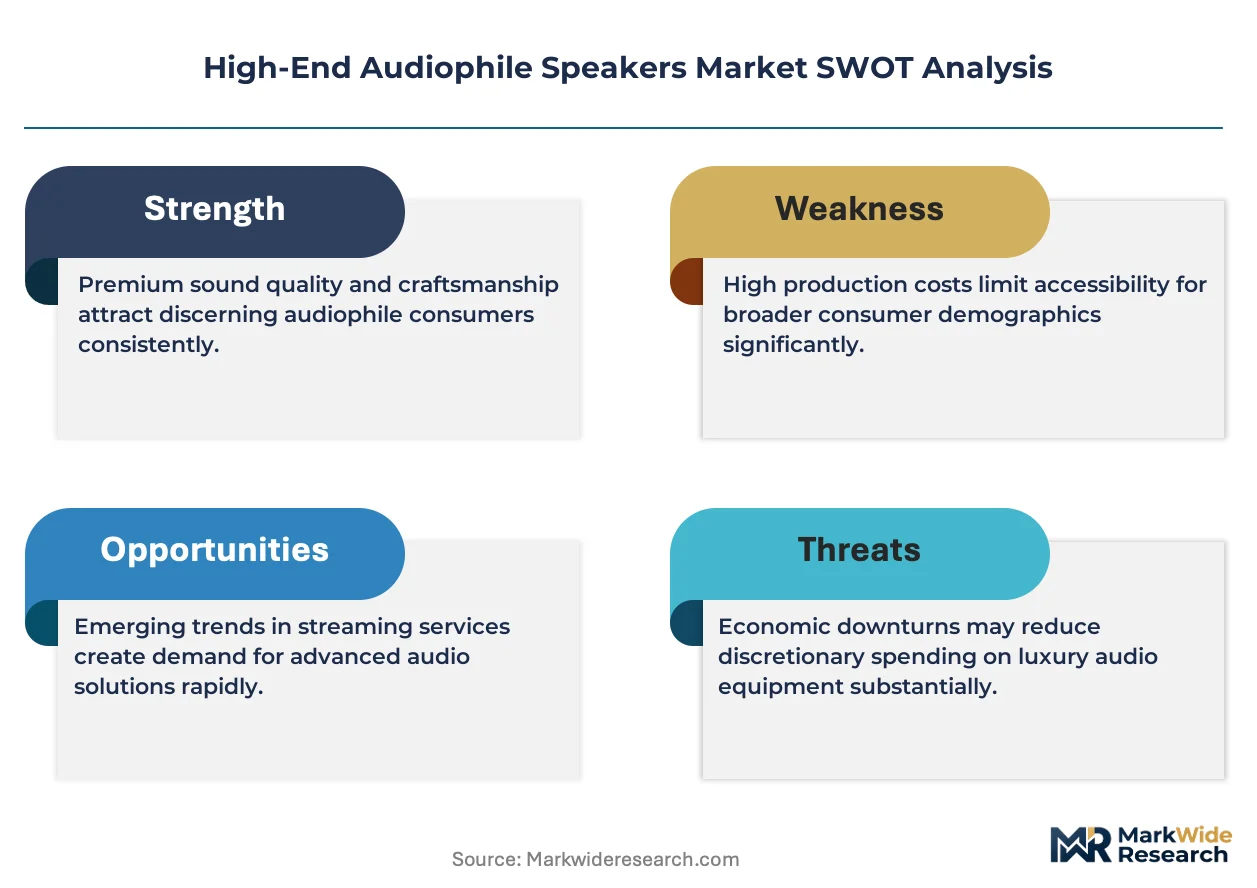
The EU Green Deal's ecodesign mandates are forcing a wholesale reconfiguration of cabinet materials and amplifier topologies, decoupling high-end manufacturing from legacy material-intensive processes. Manufacturers must now validate sustainable sourcing across beryllium, flax composites, and rare-earth magnet supply chains while preserving acoustic performance benchmarks.
Growth Catalysts
- REACH chemical compliance:Driver-adhesive reformulation under ECHA guidelines is accelerating adoption of water-based bonding agents and bio-derived cone materials in Saint-Étienne and Copenhagen manufacturing clusters.
- Wireless amplifier integration:Active loudspeaker architectures with embedded Class-D amplification eliminate external component complexity, compressing system footprint for urban residential installations.
- Germany's audio engineering concentration:Established clusters in Stuttgart and Berlin sustain consistent demand for reference-grade floor-standing systems through deep technical expertise and high disposable income households.
Market Restraints
- Beryllium supply concentration:Primary extraction of acoustic-grade beryllium copper concentrates in Utah and Kazakhstan creates input cost volatility and geopolitical exposure for tweeter manufacturers.
- CE marking electromagnetic compatibility:Active and wireless configurations face extended testing timelines and certification costs that compress margin structures for smaller European specialists.
- Subwoofer supplementation decline:Full-range floor-standing systems with extended bass response below 30 Hz are displacing satellite-plus-subwoofer configurations in premium residential segments.
Strategic Opportunities
- Professional mastering studios:Flat-frequency-response monitors command substantial premiums in Los Angeles, Nashville, and London post-production facilities where translation accuracy determines purchasing decisions.
- Room-correction software convergence:DSP-based acoustic optimization integrated with magnesium silicate polymer driver platforms enables precise boundary compensation without physical room treatment.
- Direct-to-consumer channel expansion:Manufacturer-owned retail and appointment-only listening rooms bypass traditional dealer networks, capturing margin and controlling brand narrative.
Industry Challenges
- Acoustic measurement technician scarcity:Precision anechoic chamber operation and Klippel near-field scanner expertise concentrates among aging specialists in Denmark and France, constraining quality assurance scaling.
- FCC and CE divergent RF testing:Bluetooth and Wi-Fi enabled models require separate electromagnetic compatibility validation for transatlantic product lines, extending development cycles and certification budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Audiophile Speakers Market |
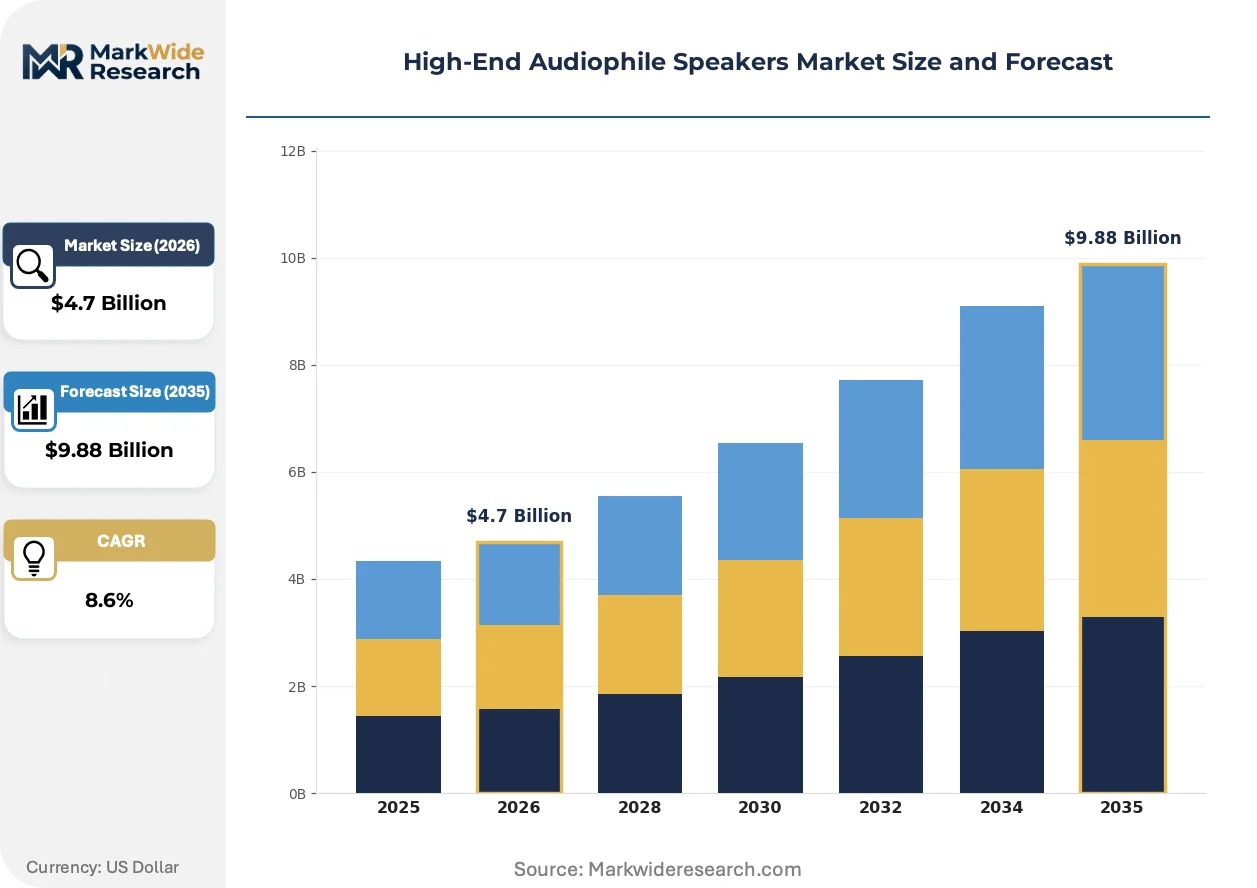
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor-standing, Bookshelf, Subwoofers, Soundbars Technology: Active, Passive, Wireless, Bluetooth End User: Audiophiles, Home Theaters, Music Studios, Retail Outlets Size: Compact, Medium, Large, Custom |
| Companies Covered | Monitor Audio, Focal, KEF, Dynaudio, DALI, Bowers & Wilkins, SVS, Q Acoustics, Sonus Faber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Audiophile Speakers Market Trends and Innovations
Active acoustic architectures and sustainable material science are converging to redefine performance benchmarks and manufacturing footprints across the premium loudspeaker segment.
Gallium nitride Class-D amplification is electrifying power supply sections in active floor-standing systems, enabling higher switching frequencies with reduced thermal load. Mastering engineers in London and Los Angeles are adopting these platforms for critical listening environments. The technology is electrifying the displacement of bulky linear power supplies and external amplifier racks in residential installations.
REACH chemical restrictions are governing driver-adhesive formulations and cabinet finishes across European supply chains, compelling reformulation of legacy solvent-based coatings. Manufacturers in Denmark and France are transitioning to UV-cured waterborne finishes that satisfy ECHA hazard classifications. Active and wireless configurations face the most stringent compliance timelines, with CE marking mandates compressing product development schedules.
Appointment-only manufacturer-direct retail is displacing traditional dealer networks for ultra-premium purchases above fifty thousand dollars. Discerning buyers in Munich, Tokyo, and New York now expect private listening sessions with engineering staff rather than showroom demonstrations. This channel shift is most visible in Germany, where established acoustic heritage brands leverage in-house manufacturing transparency to justify extended replacement cycles.
High-End Audiophile Speakers Market Segmentation
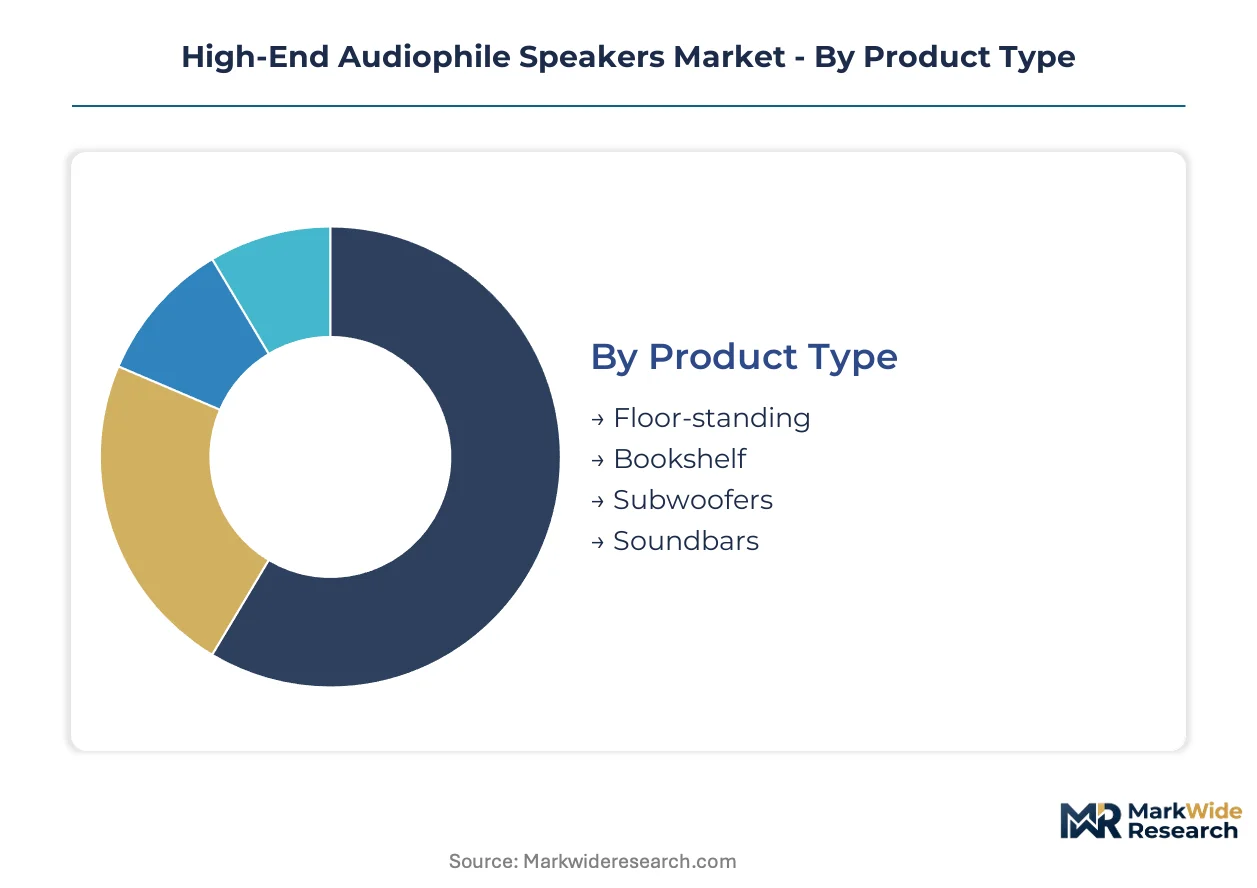
High-end audiophile speakers fragment across acoustic architecture, signal processing, installation context, and physical scale. Each dimension carries distinct margin profiles and technical certification requirements that shape procurement decisions.
Product Type:
Customization intensity varies from bespoke cabinet tuning to mass-produced driver arrays, with acoustic performance benchmarks stratifying purchase tiers.
- Floor-standing:Multi-way driver configurations with dedicated bass enclosures extend response below 30 Hz without subwoofer supplementation. Premium residential installations in Stuttgart and Berlin absorb the majority of reference-grade units as consumers prioritize full-spectrum output.
- Bookshelf:Compact two-way designs employing beryllium or diamond-dome tweeters with mid-woofers in sealed or ported enclosures. Nearfield monitoring applications in London and Los Angeles post-production suites drive demand for translation-accurate compact systems.
- Subwoofers:Dedicated low-frequency reinforcement with servo-controlled or passive radiator architectures.
- Soundbars:Integrated multi-channel arrays with DSP-based room correction for space-constrained installations.
Most installed capacity flows through Floor-standing configurations. Expansion is steepest in Bookshelf systems for professional monitoring environments.
Technology:
Signal path complexity determines regulatory exposure and margin capture across amplification integration levels.
- Active:Embedded Class-D or gallium nitride amplification eliminates external component chains. CE marking mandates and FCC electromagnetic compatibility requirements extend development timelines for transatlantic product lines.
- Passive:External amplifier dependency preserves upgrade flexibility and component separation. Traditional two-channel enthusiasts in Germany and Japan sustain demand for high-sensitivity designs with premium crossover networks.
- Wireless:Wi-Fi and proprietary mesh protocols enable multi-room distribution without cable infrastructure.
- Bluetooth:Compressed audio streaming for casual listening contexts with codec-dependent fidelity limitations.
Passive architectures retain the largest installed base. Wireless integration is climbing the fastest as urban residential footprints shrink.
End User:
Technical sophistication and budget authority diverge sharply across listening contexts and purchasing decision structures.
- Audiophiles:Individual collectors pursuing subjective acoustic preferences with discretionary expenditure on reference systems. Private listening rooms in Munich, Tokyo, and Copenhagen concentrate the highest per-unit transaction values.
- Home Theaters:Multi-channel immersive audio installations with subwoofer arrays and surround processing. Residential integrators in Los Angeles and New York specify matched loudspeaker families for consistent timbre across seating positions.
- Music Studios:Flat-frequency-response monitors for tracking, mixing, and mastering with translation-critical accuracy requirements.
- Retail Outlets:Demonstration systems and ambient audio installations with durability and visual design priorities.
Audiophile direct purchases generate the highest margins. Music studio procurement is expanding most quickly as content production capacity multiplies.
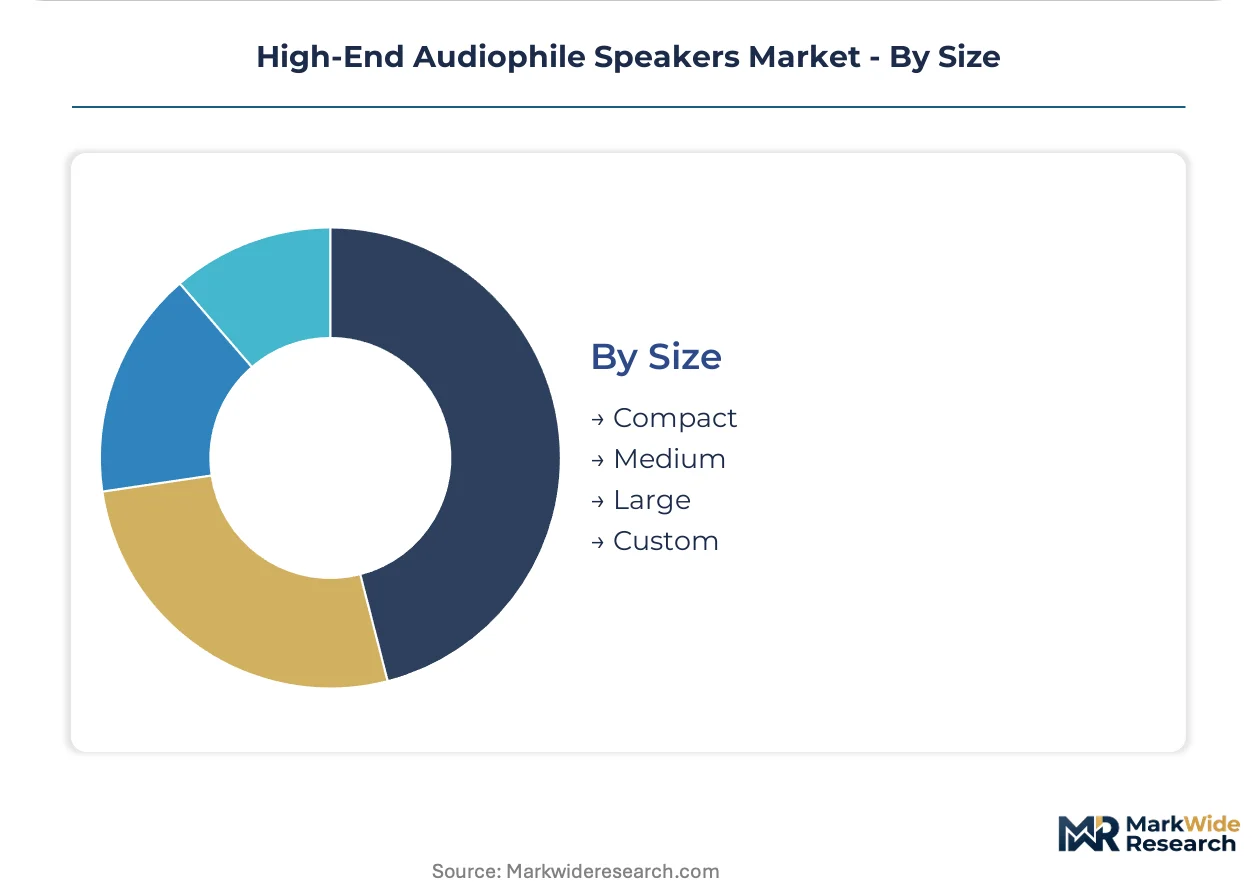
Size:
Physical envelope constraints dictate driver complement, cabinet bracing requirements, and shipping logistics economics.
- Compact:Stand-mount or desktop configurations with limited bass extension requiring boundary reinforcement or subwoofer pairing. Urban apartments in Paris and Tokyo absorb volume-constrained premium systems.
- Medium:Full-range floor-standing or large stand-mount designs balancing output capability with residential practicality. German and Danish manufacturers concentrate production in this envelope for export markets.
- Large:Statement systems with multiple bass drivers and substantial cabinet volume for dedicated listening rooms.
- Custom:Bespoke dimensions, finishes, and driver selections commissioned for specific architectural integration.
Medium configurations dominate production volume. Custom sizing is gaining share fastest among ultra-premium purchasers seeking architectural integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-end audiophile speaker manufacturing traces its commercial lineage to post-war European acoustic engineering, with Danish and British firms establishing the foundational driver technologies and cabinet craftsmanship that defined the category through the late twentieth century.
Germany
Stuttgart and Berlin concentrate Europe's densest clusters of reference-grade loudspeaker demand, driven by high disposable income households and deep technical expertise in acoustic engineering. The EU Green Deal's ecodesign requirements under the European Commission mandate sustainable material sourcing and energy-efficient amplification for all CE-marked active systems. Manufacturing transparency tours in Bavaria and North Rhine-Westphalia now anchor direct-to-consumer sales strategies for heritage brands.
United States
Los Angeles and Nashville post-production facilities sustain concentrated procurement of flat-frequency-response monitors for mastering and mixing applications, while New York residential integrators specify matched loudspeaker families for premium home theater installations. FCC electromagnetic compatibility regulations govern Bluetooth and Wi-Fi enabled models, creating divergent testing requirements from European CE marking protocols. Private listening rooms in Manhattan and Brooklyn increasingly bypass traditional dealer networks for ultra-premium purchases.
United Kingdom
London mastering studios and high-net-worth collectors in the Southeast drive demand for precision electroacoustic transducer systems with minimal distortion specifications. REACH chemical restrictions through ECHA govern driver-adhesive formulations and cabinet finishes across domestic supply chains. Research facilities in Worthing anchor diamond-dome tweeter development for prestige-tier product lines.
France
Saint-Étienne hosts in-house driver manufacturing operations controlling acoustic consistency across beryllium and flax-cone platforms for export markets. ECHA guidelines on water-based bonding agents accelerate reformulation of legacy solvent-based coatings in cabinet production. Parisian urban apartments absorb volume-constrained premium bookshelf systems requiring boundary reinforcement.
Denmark
Copenhagen manufacturing clusters emphasize MSP magnesium silicate polymer drivers integrated with room-correction software for residential installations. CE marking mandates for active loudspeaker architectures compress product development schedules for wireless configurations. Precision anechoic chamber operation expertise concentrates among aging specialists, constraining quality assurance scaling for expanding output.
High-End Audiophile Speakers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across acoustic architecture sophistication and material certification tiers. The vendor base stratifies between heritage European houses with captive manufacturing, Asian-scale fabricators, and specialist driver technology licensors. Three archetypes dominate: vertically integrated acoustic engineering houses controlling raw material-to-finished-product chains; component-assembly brands sourcing third-party drivers and cabinets; and technology-licensing specialists monetizing proprietary transducer patents. Competitive moves concentrate on direct-to-consumer channel expansion and sustainable material certification acquisition.
Within the heritage European tier, Focal and Dynaudio exemplify vertically integrated manufacturing archetypes with geographic anchoring in Saint-Étienne and Copenhagen respectively. Bowers & Wilkins occupies a position bridging British acoustic heritage with research-led prestige-tier positioning. These three firms represent distinct approaches to driver technology control, with Focal emphasizing in-house beryllium and flax-cone production, Dynaudio prioritizing magnesium silicate polymer platforms with DSP integration, and Bowers & Wilkins anchoring brand cachet through dedicated research facilities and diamond-dome development.
| Leading Market Players |
|---|
| Monitor Audio |
| Focal |
| KEF |
| Dynaudio |
| DALI |
| Bowers & Wilkins |
| SVS |
| Q Acoustics |
| Sonus Faber |
| Others |
Pricing and Supply Chain Analysis
Performance-tier divergence between reference-grade floor-standing systems and mass-market wireless configurations manifests in both component-grade pricing premiums and captive manufacturing footprints. Heritage European houses command substantial markups through in-house beryllium driver production while Asian-scale fabricators compete on amplifier integration cost.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction values, with certification-grade acoustic performance and sustainable material sourcing as primary differentiation drivers. Cost compression in wireless-integrated active systems is intensifying because gallium nitride Class-D amplification commodifies power electronics. Home theater integrators exhibit highest price sensitivity, while mastering studio procurement shows minimal elasticity.
Supply Chain Analysis
Acoustic-grade beryllium copper supply rests on extraction operations in Utah and Kazakhstan, creating geographic concentration risk for tweeter manufacturers. Rare-earth magnet sourcing draws from Chinese processing facilities, while flax-composite cone materials feed from French agricultural supply chains. Single-source vulnerability in beryllium refining exposes margin structures to geopolitical disruption. Distribution runs through manufacturer-direct appointment channels and traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in active loudspeaker architectures where amplifier integration eliminates external component chains and sustainable certification unlocks premium positioning.
For Market Incumbents: Hedge against wireless-technology commoditization by deepening captive driver manufacturing in Saint-Étienne and Copenhagen clusters. Prioritize REACH-compliant finish reformulation to preempt regulatory exclusion from EU markets. Channel control through appointment-only retail preserves pricing power against dealer-network disintermediation. For New Entrants and Emerging Players: The price-point gap between bookshelf monitors for project studios and reference floor-standing systems offers white-space entry. Target London and Los Angeles post-production facilities with flat-frequency-response designs undercutting heritage brand premiums. Pursue direct-to-consumer launch with room-correction software bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where precision anechoic chamber expertise concentrates among aging specialists in Denmark and France. Long-term viability favors vertically integrated manufacturing houses with captive transducer technology and sustainable material certification. Watch gallium nitride amplifier adoption rates as inflection indicator for active-system margin trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Manufacturer-owned listening rooms in Munich and New York bypass dealer margin capture. |
| Sustainable Material Certification | EU Green Deal ecodesign compliance preserves CE marking access for active loudspeaker exports. |
| Driver Technology Backward Integration | In-house beryllium and flax-cone production controls acoustic consistency across product tiers. |
| Room-Correction Software Integration | DSP-based acoustic optimization differentiates magnesium silicate polymer driver platforms. |
| Professional Studio Monitor Development | Flat-frequency-response designs command premiums in Los Angeles and Nashville mastering facilities. |
Research Methodology
Coverage spans Germany, United States, United Kingdom, France, and Denmark, with primary inputs from each market cluster. The research combines interviews with acoustic engineering directors, mastering studio procurement managers, residential integrators, and heritage brand manufacturing heads with secondary validation from ECHA regulatory filings, FCC electromagnetic compatibility databases, and EU Green Deal implementation directives. Bottom-up unit demand modeling and top-down value triangulation cross-verify segment outputs.
Granularity-level modeling disaggregates volume and value across product type, technology architecture, end-user context, and physical size tier throughout the forecast period. CAGRs derive from fitted trend extrapolation with scenario-weighted adjustments. Industry-specific inputs include beryllium supply concentration indices, CE marking compliance timelines, and professional studio facility expansion pipelines.
Caveats apply where REACH chemical restriction evolution or gallium nitride supply disruption could materially shift the outlook. Forecasts reflect assumptions regarding sustained high-disposable-income household demand in Stuttgart and Berlin, wireless protocol standardization stability, and mastering studio capacity expansion in London and Los Angeles. A small set of regulatory and technology triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Clip-On Headphones Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
Audio Interface Market
Audio Equipment
Digital a/V Decoder Market
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
India Wireless Audio Market
Audio Equipment
Soundbar Market
Audio Equipment
Guitar Head Amplifiers Market
Audio Equipment
Smart Audio System Market
Audio Equipment
North America Gaming Headsets Market
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Commercial Microphone Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Germany Radio Headset Market
Audio Equipment
Home Audio Equipment Market