
 Wireless Speakers Market | 2026-2036
Wireless Speakers Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Speakers Market Intelligence
Demand from corporate clients for integrated audio solutions in conference rooms and commercial spaces is consolidating around vendors offering seamless network integration. This shift benefits specialized manufacturers over general consumer electronics brands. Sonos Inc. specializes in multi-room audio software and hardware ecosystems, creating a strong user lock-in effect. In parallel, Bose Corporation leverages its established brand reputation in acoustic engineering and noise-cancellation to secure premium commercial contracts. Harman International Industries competes across multiple price points and applications.
A wireless speaker is an electronic device that receives audio signals using radio frequency or infrared waves, eliminating the need for audio cables. These systems typically incorporate amplifiers, drivers, and wireless receivers, operating over protocols like Bluetooth and Wi--Fi to stream audio from a source device. The primary function is to provide portable or fixed audio playback for personal and commercial applications. The smart speakers segment, integrating voice assistants, shows significant value growth. Concurrently, the portable speakers category continues to lead in unit volume, driven by its convenience and affordability for personal audio use.
Regulatory compliance is a critical barrier to entry and a key design constraint. Manufacturers must adhere to FCC regulations in the United States concerning radio frequency interference and CE marking requirements in Europe for safety and health standards. In India, BIS certification is mandatory for electronic goods, impacting market access timelines. Stakeholders must balance investments in next-generation connectivity and AI features against maintaining core audio fidelity to meet diverse consumer expectations.
Market Dynamics
The wireless speaker market's evolution is defined by the need to balance advanced feature integration, such as AI voice assistants and multi-node networking, against the persistent demand for core audio fidelity and acoustic performance, creating divergent design and investment priorities.
Growth Catalysts
- Connectivity Standards:The evolution of protocols governed by the Bluetooth Special Interest Group, including LE Audio, enables higher-quality streaming and improved power efficiency, expanding use cases for portable devices.
- Hospitality Sector Integration:Hotels and resorts are increasingly deploying networked audio systems for in-room entertainment and ambient soundscapes in common areas, creating a significant commercial demand channel.
- Consumer Electronics Growth:Demand for personal audio devices is concentrating in high-growth consumer markets, such as India, supported by rising disposable incomes and smartphone penetration.
Market Restraints
- Component Cost:The high cost of specialized components like high-performance digital-to-analog converters (DACs) and custom-engineered acoustic drivers creates a barrier to achieving premium audio quality at lower price points.
- Latency and Synchronization:Inherent latency in Wi-Fi and Bluetooth protocols presents a structural challenge for professional applications and perfectly synchronized multi-room audio, impacting user experience.
- Substitution Threat:Smart home hubs and television soundbars, which integrate voice control and video-centric audio features, present a potent substitute, often at a competitive price for a multi-function device.
Strategic Opportunities
- Commercial Wellness Applications:Integrating wireless speakers into corporate wellness programs to deliver ambient biophilic soundscapes or guided meditation represents an emerging commercial application beyond entertainment.
- AI-Driven Personalization:The convergence of spatial audio processing with AI algorithms presents an opportunity to create highly personalized listening experiences that adapt to the user's environment and content.
- Untapped Commercial Verticals:There is significant opportunity for tailored audio solutions in underpenetrated commercial sectors within Southeast Asian economies, including retail, education, and smaller hospitality venues.
Industry Challenges
- Multi-Region Compliance:Manufacturers face significant operational hurdles managing simultaneous certification processes, such as FCC for the US, CE for Europe, and BIS for India, which delays product launches.
- Protocol Licensing Complexity:Navigating the intellectual property landscape for essential wireless communication and audio codec patents involves complex licensing negotiations and royalty payments, adding to product costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Speakers Market |
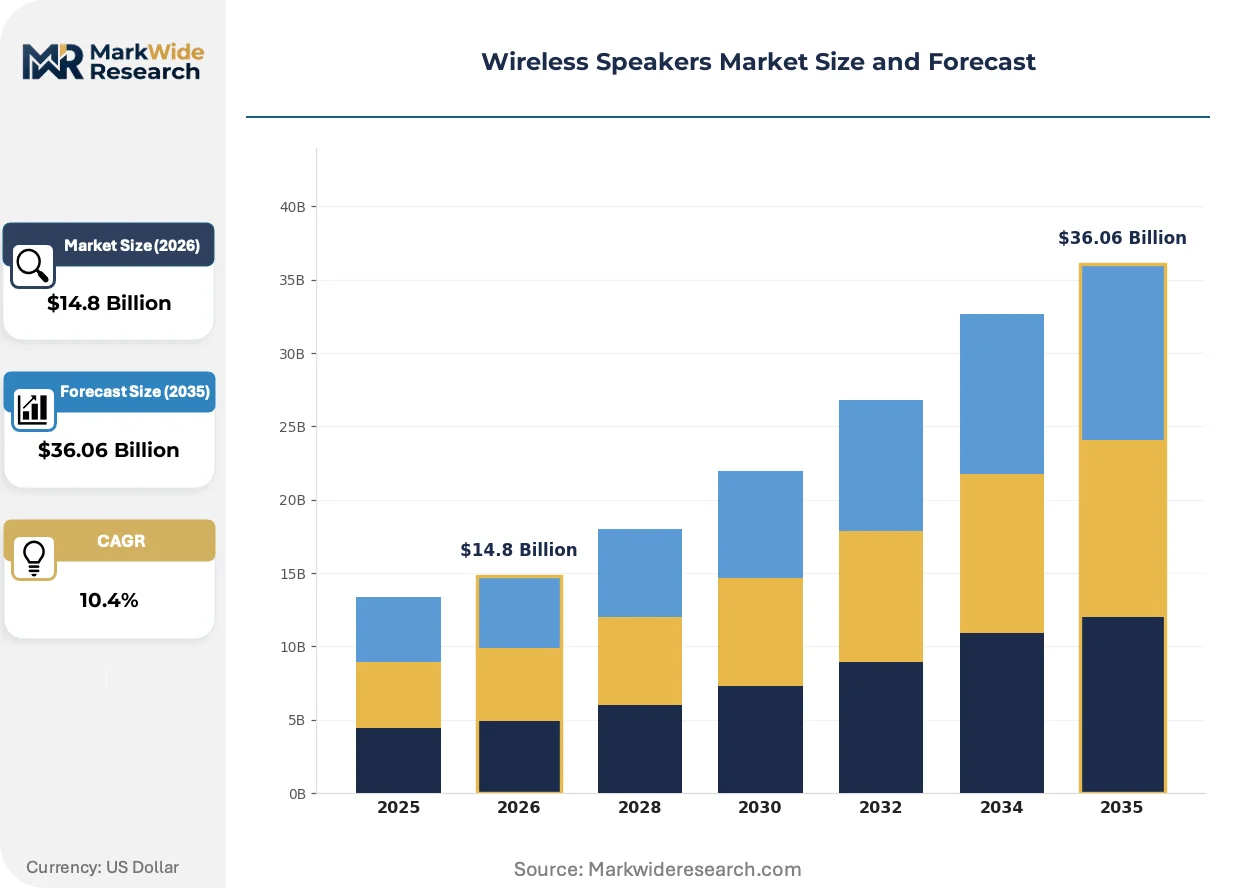
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $36.06 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Speakers, Home Theater Systems, Smart Speakers, Soundbars, Party Speakers Technology: Bluetooth, Wi-Fi, NFC, Infrared, RF Application: Personal Audio, Home Entertainment, Commercial Use, Outdoor Events, Conference Rooms End User: Consumers, Event Organizers, Corporate Clients, Educational Institutions, Hospitality Sector |
| Companies Covered | Harman International Industries, Apple Inc., Bose Corporation, Ultimate Ears, Amazon.com Inc., Sonos Inc., Samsung Electronics, LG Electronics, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Speakers Market Strategic Shifts & Innovations
The market is bifurcating, with one segment pursuing ultimate audio fidelity and another prioritizing smart-feature integration and voice control. This divergence shapes product development, forcing manufacturers to choose between serving audio purists or the mainstream smart home consumer, with limited overlap between the two value propositions.
Multi-room audio software platforms provide a unified interface for controlling speakers throughout a home or commercial space. Residential and corporate clients are rapidly adopting these systems for their convenience and seamless user experience. This trend is consolidating the market around vendors that can deliver a robust, proprietary software ecosystem, creating strong user lock-in and a significant competitive moat against hardware-only competitors.
Europe's Radio Equipment Directive (RED) sets mandatory requirements for all wireless devices sold within the EU. The directive enforces harmonized standards for efficient radio spectrum use, electromagnetic compatibility, and user safety. This regulation affects every manufacturer targeting the European market, compelling them to incorporate design-for-compliance from the initial stages and increasing the cost and complexity of market entry.
A notable behavioral change is occurring in corporate purchasing for integrated audio-visual systems. Buyers are moving away from one-time capital expenditures on hardware toward subscription-based or managed-service models that include installation, maintenance, and software updates. This shift is most pronounced in North American and European corporate environments, favoring suppliers with strong service and network integration capabilities.
Wireless Speakers Market Segmentation
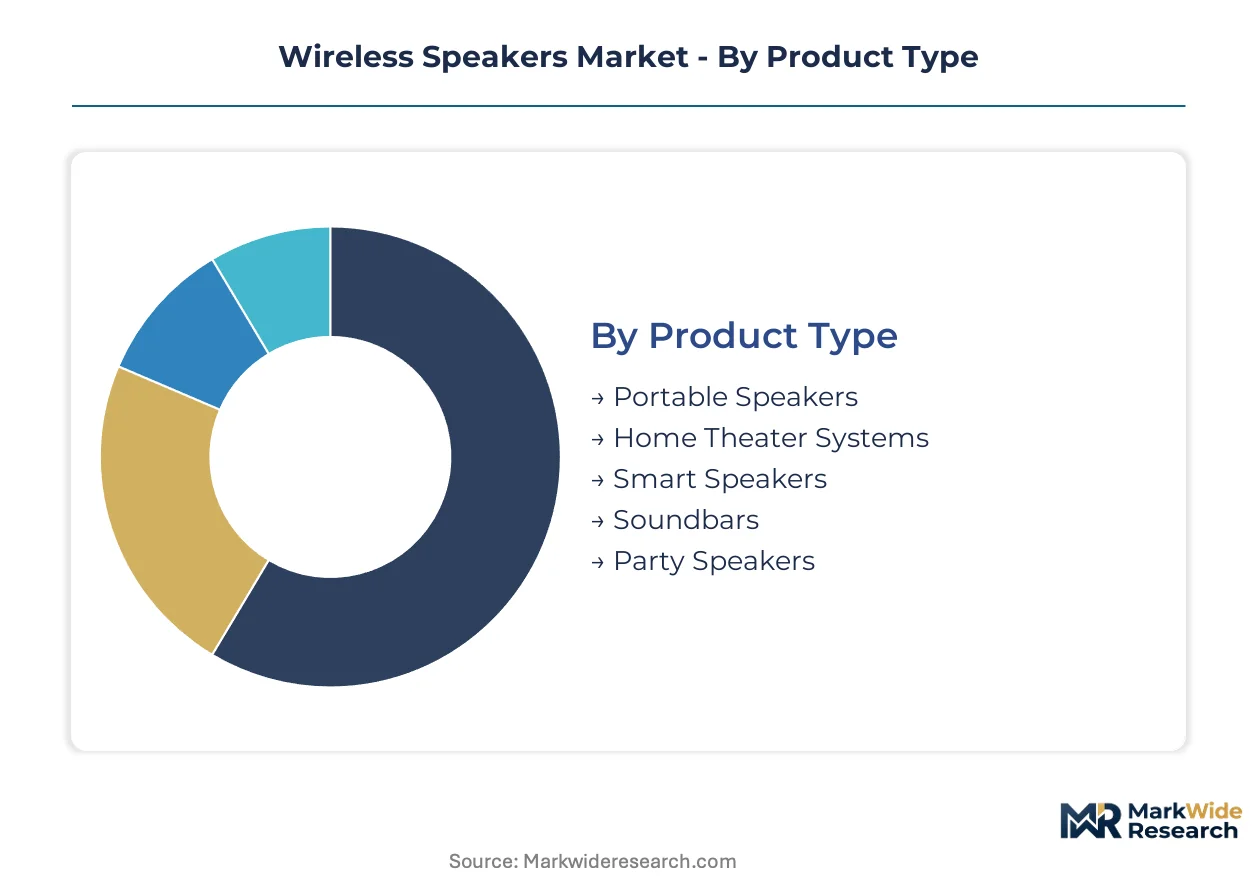
The wireless speakers market exhibits diverse segmentation, reflecting varied consumer preferences and commercial requirements. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively, addressing specific demand drivers and technological needs across different user bases.
Product Type:
Supply concentration in the wireless speaker market often aligns with manufacturing scale for specific product types.
- Portable Speakers:These compact, battery-powered devices offer audio playback on the go, primarily connecting via Bluetooth. Demand is high in India and other consumer electronics markets, driven by convenience and affordability for personal audio use.
- Smart Speakers:Integrating voice assistants like Amazon Alexa or Google Assistant, these devices offer interactive control and smart home capabilities. This segment shows significant value growth, as consumers prioritize integrated AI features for home automation and content access.
- Home Theater Systems:These multi-channel audio setups provide immersive sound for cinematic experiences within residential settings.
- Soundbars:Designed to enhance television audio, soundbars offer an integrated audio solution for home entertainment without extensive wiring.
- Party Speakers:High-output speakers with robust designs, often featuring lighting effects, cater to social gatherings and outdoor events.
Portable Speakers absorb the bulk of installed capacity; Smart Speakers are expanding most quickly.
Technology:
Application diversity drives the development and adoption of various wireless communication technologies within speakers.
- Bluetooth:A short-range wireless technology for streaming audio from source devices, governed by the Bluetooth Special Interest Group. The evolution of LE Audio enables higher-quality streaming and improved power efficiency for portable devices.
- Wi-Fi:Utilized for multi-room audio systems and higher-fidelity streaming, Wi-Fi connectivity supports greater bandwidth and network integration. Sonos Inc. leverages Wi-Fi for its proprietary multi-room audio ecosystems, creating user lock-in.
- NFC:Near Field Communication simplifies Bluetooth pairing through a quick tap between compatible devices.
- Infrared:An older technology primarily used for line-of-sight remote control functions in some audio systems.
- RF:Radio Frequency technology, beyond standard Bluetooth, can offer extended range and specialized applications, particularly in professional audio setups.
Advanced Wi-Fi capabilities differentiate premium offerings, while Bluetooth remains foundational for mass-market accessibility.
Application:
Customer type influences the specific application areas where wireless speakers see the most significant deployment.
- Commercial Use:Integrated audio solutions for conference rooms, retail spaces, and hospitality venues. Demand from corporate clients for seamless network integration benefits specialized manufacturers.
- Personal Audio:Individual listening experiences, often facilitated by portable speakers for mobile use or desktop setups. This segment leads in unit volume, driven by convenience and affordability.
- Home Entertainment:Audio systems designed for residential use, including music playback, movies, and gaming.
- Outdoor Events:Robust, high-power speakers suitable for public gatherings, parties, and open-air venues.
- Conference Rooms:Specialized audio equipment providing clear communication and presentation support in corporate environments.
Demand for Commercial Use solutions is undergoing rapid transformation, while Personal Audio represents a stable, high-volume segment.
End User:
Margin profiles vary significantly across different end-user segments, impacting product features and pricing strategies.
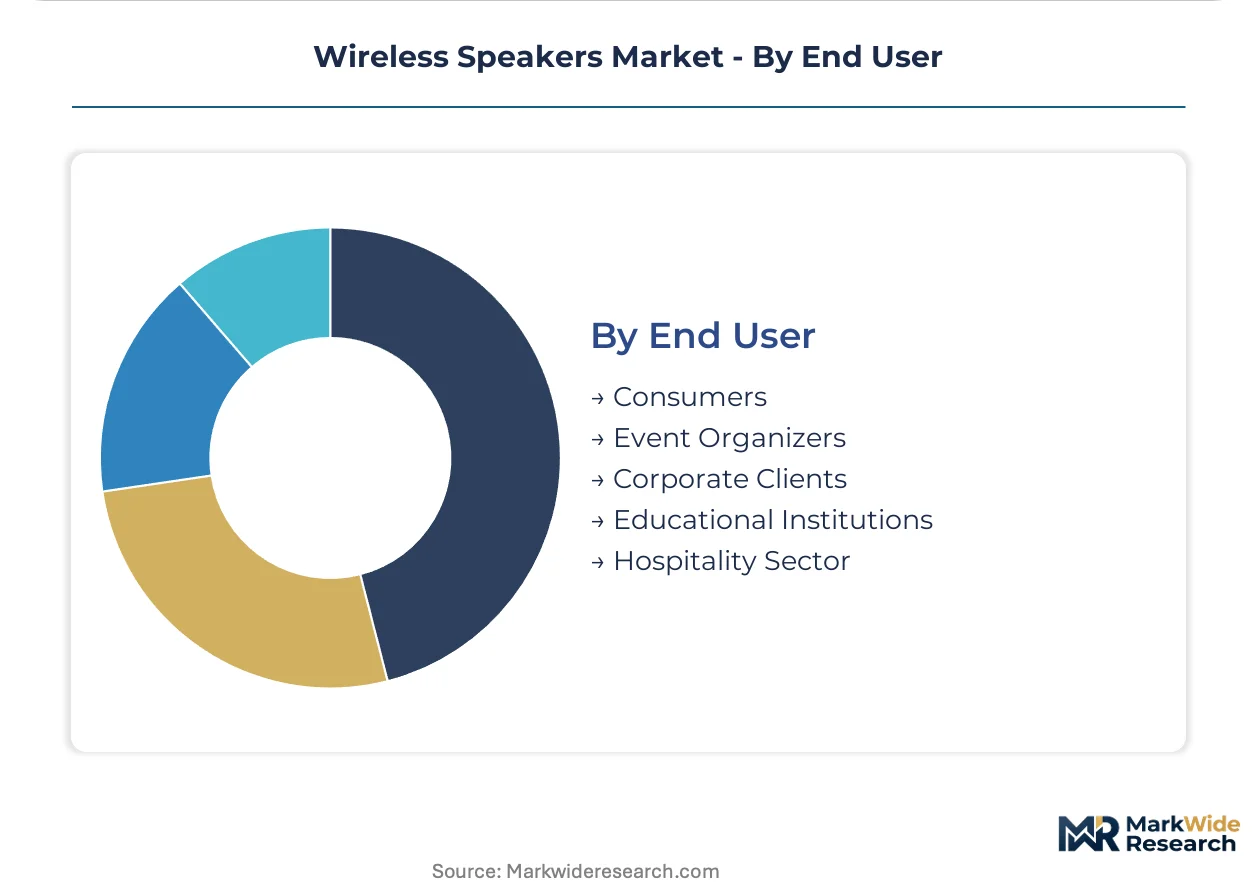
- Consumers:The largest end-user group, purchasing speakers for personal audio, home entertainment, and smart home integration. Rising disposable incomes in markets like India support this segment's expansion.
- Hospitality Sector:Hotels and resorts deploying networked audio systems for in-room entertainment and ambient soundscapes. This creates a significant commercial demand channel for specialized vendors.
- Event Organizers:Procuring robust, high-output speakers for concerts, festivals, and other large-scale gatherings.
- Corporate Clients:Investing in integrated audio solutions for meeting rooms, offices, and commercial spaces. Procurement is shifting towards managed service models in North American and European corporate environments.
- Educational Institutions:Utilizing wireless speakers for classroom presentations, lecture halls, and campus-wide audio systems.
The shift towards managed audio services influences procurement among Corporate Clients, contrasting with direct retail channels for Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for wireless speakers is evident in high-growth consumer electronics markets, particularly India, driven by rising disposable incomes and smartphone penetration. Commercial applications in the hospitality sector and corporate environments also contribute significantly to regional market dynamics. Manufacturers must navigate diverse regulatory landscapes across these key geographies.
India
Rising disposable incomes and smartphone penetration drive significant demand for portable wireless speakers among Indian consumers. The Bureau of Indian Standards (BIS) certification is mandatory for electronic goods, impacting market access timelines for new products. Major consumer electronics manufacturing clusters in states like Maharashtra and Tamil Nadu are expanding production capacity to meet this domestic demand.
United States
Consumer preferences for smart speakers with integrated voice assistants and multi-room audio systems fuel demand in the United States. Manufacturers must adhere to Federal Communications Commission (FCC) regulations concerning radio frequency interference for all wireless devices. Technology hubs in California and Texas continue to innovate in AI-driven personalization and spatial audio processing.
Germany
Strong consumer purchasing power and a high appreciation for audio fidelity support the premium segment of the wireless speakers market in Germany. The Radio Equipment Directive (RED) in Europe sets mandatory requirements for all wireless devices sold, ensuring compliance for efficient spectrum use. Engineering centers in Bavaria and Baden-Württemberg focus on advanced acoustic design and connectivity standards.
Japan
Technological sophistication and an emphasis on compact, high-quality audio devices characterize the wireless speaker market in Japan. Manufacturers navigate regulations set by the Ministry of Economy, Trade and Industry (METI) for electronic product safety and efficiency standards. Research and development clusters in Tokyo and Osaka are pioneering new materials and miniaturization techniques.
China
A large consumer base and rapid urbanization propel the adoption of both portable and smart wireless speakers across China. Manufacturers must comply with GB standards and regulations from the State Administration for Market Regulation (SAMR) for product quality and safety. Major electronics production hubs in the Pearl River Delta region are expanding capacity for domestic and export markets.
Wireless Speakers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches like commercial wellness applications and AI-driven personalization. The market structure exhibits a blend of large diversified electronics corporations and specialized audio firms. Strategic archetypes include integrated ecosystem providers, acoustic engineering specialists, and mass-market volume players. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand feature sets.
Within the integrated ecosystem archetype, Sonos Inc. exemplifies a strong user lock-in effect through its proprietary multi-room audio software and hardware. Bose Corporation, leveraging its established brand reputation, anchors the premium segment with its focus on acoustic engineering and noise-cancellation technologies. Harman International Industries sits within the diversified electronics segment, competing across multiple price points and application areas.
| Leading Market Players |
|---|
| Harman International Industries |
| Apple Inc. |
| Bose Corporation |
| Ultimate Ears |
| Amazon.com Inc. |
| Sonos Inc. |
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned component suppliers, often specializing in high-performance digital-to-analog converters, influence both supply consistency and pricing stability within the wireless speaker market. These specialized firms often dictate terms for critical acoustic drivers, impacting overall manufacturing costs for premium offerings.
Pricing Analysis
The market exhibits a clear volume-versus-margin split, with portable speakers driving high unit sales at lower price points. Per-unit transactional pricing dominates for consumer products, while commercial solutions often involve project-based or subscription models for integrated systems. Brand premium, exemplified by Bose Corporation, and advanced acoustic fidelity are key price differentiation drivers. Pricing pressure stems from the substitution threat posed by multi-functional smart home hubs. Consumers, particularly in emerging markets like India, represent the most price-sensitive segment, contrasted with corporate clients prioritizing seamless integration and reliability over initial cost.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of wireless speakers, particularly for units assembled in Asia and shipped globally. Supply concentration for electronic components, including specialized acoustic drivers and wireless communication chips, centers in China and Taiwan. Raw material dependencies include rare earth elements for magnets and specialized polymers for speaker cones. Multi-region regulatory compliance presents a structural supply chain risk, delaying market access for new products. Distribution runs through a hybrid model, combining direct-to-consumer online sales, traditional retail channels, and specialized commercial integrators for corporate and hospitality applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless speaker market is currently in a technology-transition phase, as advanced AI voice assistants and spatial audio processing begin to replace basic Bluetooth streaming functionality.
For Market Incumbents: Cement proprietary software ecosystems and multi-room audio capabilities to counter substitution threats from smart home hubs. Invest in advanced acoustic engineering and AI integration to maintain a premium positioning. Control key component supply chains, such as high-performance digital-to-analog converters, to mitigate cost volatility and ensure quality. Expand service-led offerings for corporate clients in North America and Europe, leveraging network integration expertise.
For New Entrants and Emerging Players: Launch via direct-to-consumer channels, targeting underpenetrated commercial verticals in Southeast Asian economies with tailored audio solutions. Focus on niche applications like commercial wellness programs or educational institutions to build market share. Develop specialized AI-driven personalization features for specific user segments. Offer flexible subscription-based models for integrated audio systems to attract smaller businesses.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated specialists in North American and European corporate environments focused on managed audio services. Long-term viability rests on firms capable of combining hardware excellence with robust software platforms and recurring revenue streams. The shift towards subscription-based procurement by corporate clients signals a key inflection point to watch for acquisition targets. Prioritize companies with strong intellectual property in spatial audio or AI processing.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven spatial audio platforms | Creates highly personalized listening experiences, adapting to user environments and content preferences. |
| Expand managed audio service offerings | Captures recurring revenue from corporate clients, shifting from one-time capital expenditures to service models. |
| Secure long-term component supply agreements | Mitigates cost volatility for specialized acoustic drivers and high-performance digital-to-analog converters. |
| Target commercial wellness applications | Opens new revenue streams beyond entertainment in corporate and hospitality sectors. |
| Invest in multi-region regulatory compliance expertise | Accelerates market access and reduces delays for new product launches in key geographies like India and Europe. |
Research Approach
Multi-period observation of connectivity standard evolution and consumer electronics adoption rates anchored the trend analysis, supplemented by interviews with industry leaders. Primary data collection involved conversations with product development executives, commercial integrators, retail channel managers, and regulatory compliance specialists. Secondary data sources included government certifications (FCC, CE, BIS), industry association reports, and consumer electronics trade publications. Bottom-up and top-down triangulation validated market size and growth projections.
Segment-weighting approaches allocated market share across product type, technology, application, and end-user, with an additional dimension for regional regulatory compliance frameworks. Analytical frameworks assessed the impact of evolving Bluetooth and Wi-Fi standards on device interoperability and audio quality. Compound annual growth rates were derived from historical data and projected forward across the analysis window, incorporating inputs such as smartphone penetration rates and disposable income trends in key consumer markets.
Component cost volatility, shifts in regulatory enforcement, and rapid technological obsolescence are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding economic stability and consumer spending patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Mobile Accessories Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Wet Wipes Market